
 Latin America Motorcycle Loan Market | 2026-2036
Latin America Motorcycle Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Motorcycle Loan Market Insights
Asset-light leasing models are rewriting competitive entry barriers across Latin America motorcycle finance. Banco Santander leverages its retail banking footprint to pre-approve riders at point-of-sale terminals. Banco Bradesco anchors its position through captive partnerships with Honda and Yamaha dealer networks. Honda Financial Services competes by integrating insurance and maintenance bundles into installment contracts.
A motorcycle loan constitutes a secured or unsecured credit instrument collateralized by a two-wheeled motor vehicle, typically featuring interest rates indexed to central bank benchmarks and tenures spanning twelve to sixty months. Its primary commercial purpose channels liquidity to individual and fleet purchasers who lack immediate capital for vehicle acquisition. Secured loans dominate outstanding portfolio value, as lien structures reduce default severity for underwriters. Dealer financing represents the fastest-expanding origination channel, driven by manufacturer subsidies that compress front-end rates below retail alternatives. Fleet operators command preferential pricing through volume commitments, though individual buyers generate higher per-unit margin yields.
Brazil's central bank and Mexico's CNBV impose reserve requirements and interest-rate caps that constrain pricing flexibility for motorcycle lenders. ANVISA in Brazil and COFEPRIS in Mexico regulate vehicle safety standards that indirectly affect loan-to-value ratios by altering replacement costs. Stakeholders must monitor how digital onboarding platforms alter credit bureau integration and fraud exposure across Andean and Southern Cone markets.
Market Dynamics
Digital onboarding platforms are compressing origination timelines across Brazil, Mexico, and Colombia while exposing lenders to new fraud vectors that legacy credit bureau integrations cannot flag in real time.
Growth Catalysts
- Fleet operator expansion:Last-mile delivery services in São Paulo and Mexico City are scaling two-wheeler financing commitments to reduce fuel costs and navigate congestion.
- CNBV disclosure mandates:Mexico's consumer protection framework is standardizing loan term transparency, reducing information asymmetry between underwriters and individual borrowers.
- Embedded finance integration:Point-of-sale terminals at Honda and Yamaha dealerships are collapsing approval cycles from days to minutes.
Market Restraints
- Central bank rate volatility:Brazil's SELIC benchmark fluctuations are compressing net interest margins for fixed-rate motorcycle portfolios.
- Replacement cost inflation:ANVISA safety standard updates are elevating vehicle homologation expenses, indirectly inflating loan-to-value ratios.
- Informal lending substitution:Unregulated peer-to-peer vehicle financing in Colombian secondary markets siphons price-sensitive borrowers from formal channels.
Strategic Opportunities
- Andean corridor penetration:Peru and Ecuador exhibit motorcycle ownership rates below regional medians with minimal captive finance presence.
- Telematics-bundled underwriting:GPS-enabled collateral tracking is converging with usage-based insurance to create dynamic pricing models for fleet accounts.
- Green mobility incentives:Sub-national tax abatements for electric two-wheelers in Minas Gerais are creating preferential origination windows.
Industry Challenges
- Credit bureau fragmentation:SPC Brasil, Serasa, and Buró de Crédito maintain non-interoperable scoring architectures that complicate cross-border portfolio management.
- Legacy system integration:Core banking platforms at established lenders require middleware layers to accommodate API-driven dealer connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Motorcycle Loan Market |
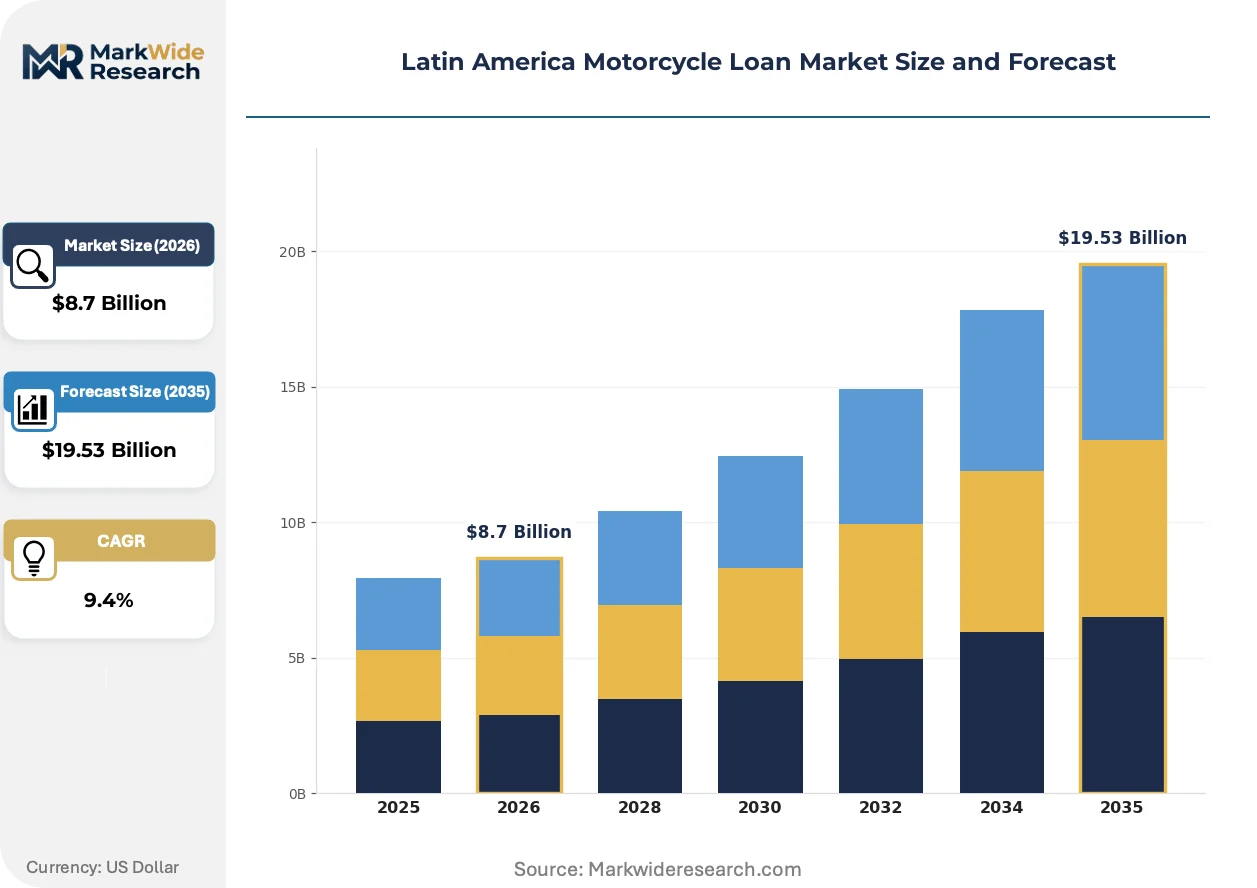
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Personal Loans, Dealer Financing Customer Segment: Individual Buyers, Corporate Buyers, Fleet Operators, Rideshare Operators Loan Tenure: Short-Term, Medium-Term, Long-Term, Flexible Terms Interest Rate Type: Fixed Rates, Variable Rates, Tiered Rates, Promotional Offers |
| Companies Covered | Banco Santander, Banco Bradesco, Banco do Brasil, Banco Votorantim, Banco Safra, Scotiabank, CitiBanamex, Honda Financial Services, Harley-Davidson Financial Services, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Motorcycle Loan Market Trends and Innovations
Automation is reconstructing every stage of motorcycle loan origination, from identity verification to collateral registration, while regulatory pressure on transparency accelerates standardization.
Blockchain-enabled smart contracts are virtualizing lien registration and title transfer processes across Brazilian state motor vehicle departments. Fleet operators with multi-state footprints are piloting these systems to compress documentation cycles. This virtualization is eliminating notary bottlenecks that previously extended funding timelines by five to ten business days.
CNBV's 2024 fintech licensing framework is formalizing digital-first lender entry into Mexico's motorcycle finance segment. The regulation mandates minimum capital buffers and real-time reporting protocols that favor technology-native underwriters over legacy banks. Sub-scale regional lenders in Guanajuato and Jalisco are consolidating to meet these thresholds.
Subscription-based vehicle access is displacing traditional installment purchase among urban gig workers in Bogotá and Medellín. Riders prioritize all-inclusive monthly payments covering maintenance, insurance, and registration over asset ownership. Colombian fintech platforms are capturing this cohort through app-based fleet membership models that bypass conventional dealer networks.
Latin America Motorcycle Loan Market Segmentation
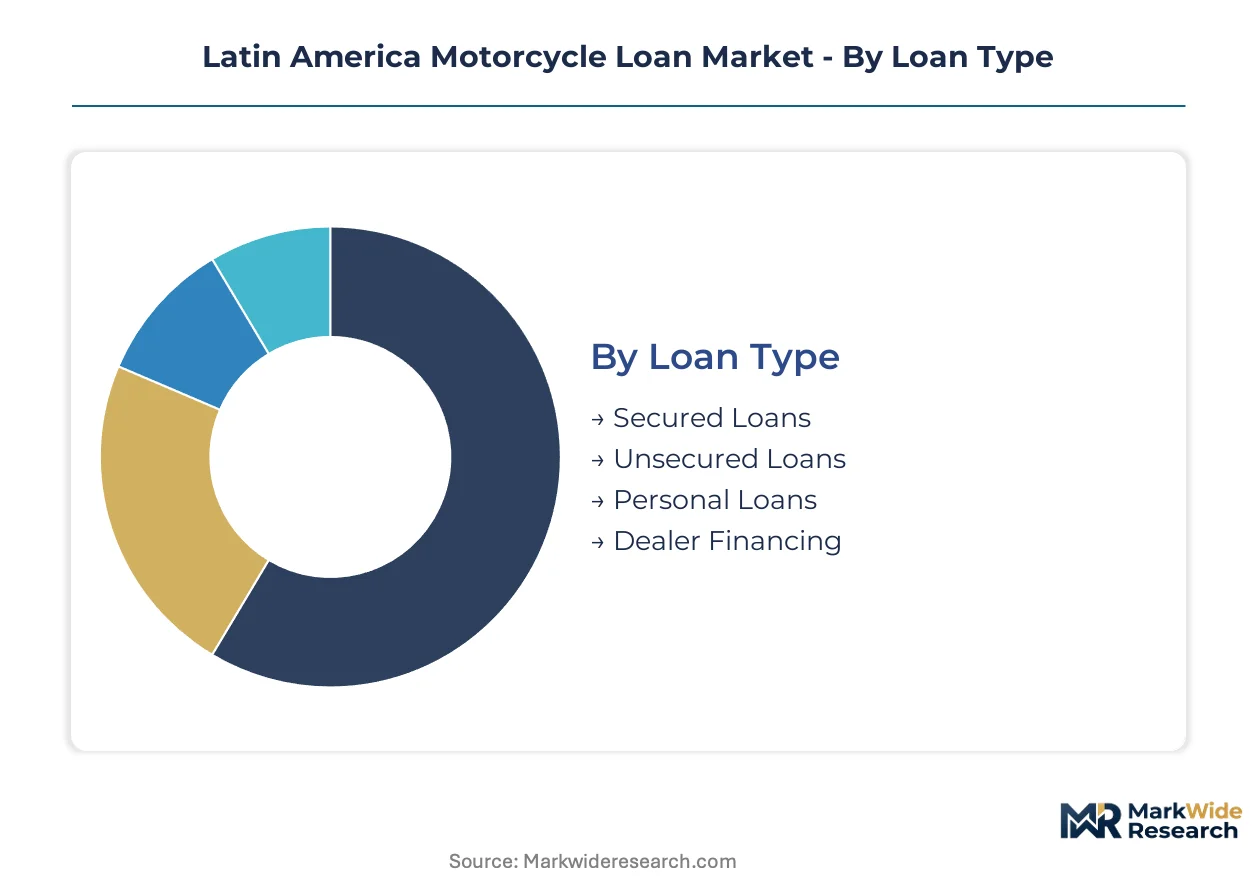
Motorcycle loan segmentation in Latin America reflects divergent risk-return profiles across collateral structures and borrower types. Lenders calibrate underwriting engines, servicing intensity, and collection protocols differently for each slice, creating specialized operational footprints.
Loan Type:
After-sales-service intensity varies sharply across loan structures, with lien perfection and collateral monitoring demanding differentiated field operations.
- Secured Loans:Collateralized by vehicle title with perfected liens registered at state motor vehicle departments. Brazil's southeastern states concentrate demand among fleet operators seeking lower rates through asset backing.
- Dealer Financing:Manufacturer-subsidized programs at Honda and Yamaha point-of-sale terminals compress approval cycles through embedded pre-qualification. Captive finance arms in São Paulo and Minas Gerais anchor volume.
- Unsecured Loans:Credit-based approvals without collateral attachment, carrying higher rates to absorb default severity. Serasa scoring integration dominates underwriting.
- Personal Loans:General-purpose consumer credit subsequently applied to vehicle acquisition, often at rates above dedicated motorcycle products.
Secured loans hold the largest share; momentum sits with dealer financing.
Customer Segment:
Cost tier stratification separates mass-market individual borrowers from volume-negotiated fleet accounts with divergent margin profiles.
- Fleet Operators:Multi-unit commitments from last-mile delivery services in São Paulo and Mexico City command preferential pricing through volume guarantees. Telematics integration enables dynamic collateral monitoring.
- Individual Buyers:Single-unit purchasers generating higher per-loan margins through rate premiums, concentrated in Brazil's urban peripheries where formal credit penetration remains incomplete.
- Corporate Buyers:Mid-size enterprises acquiring staff transportation fleets, typically through relationship banking channels rather than dealer-direct origination.
- Rideshare Operators:Gig-economy drivers in Bogotá and Medellín accessing subscription-based alternatives that displace traditional installment structures.
Fleet operators hold the largest share; momentum sits with rideshare operators.
Loan Tenure:
Application patterns align tenure selection with borrower cash flow predictability and vehicle replacement cycles.
- Medium-Term:Twenty-four to thirty-six month structures balancing manageable installments with reasonable interest burden. Dominates individual buyer preferences across Brazil's southeastern states.
- Long-Term:Forty-eight to sixty month tenures reducing monthly obligations for price-sensitive borrowers, extending portfolio duration and rate risk exposure for lenders.
- Short-Term:Twelve to eighteen month accelerated amortization favored by fleet operators with predictable revenue streams.
- Flexible Terms:Seasonal or revenue-linked repayment schedules piloted among agricultural and informal-sector borrowers in Colombia.
Medium-term structures hold the largest share; momentum sits with flexible terms.
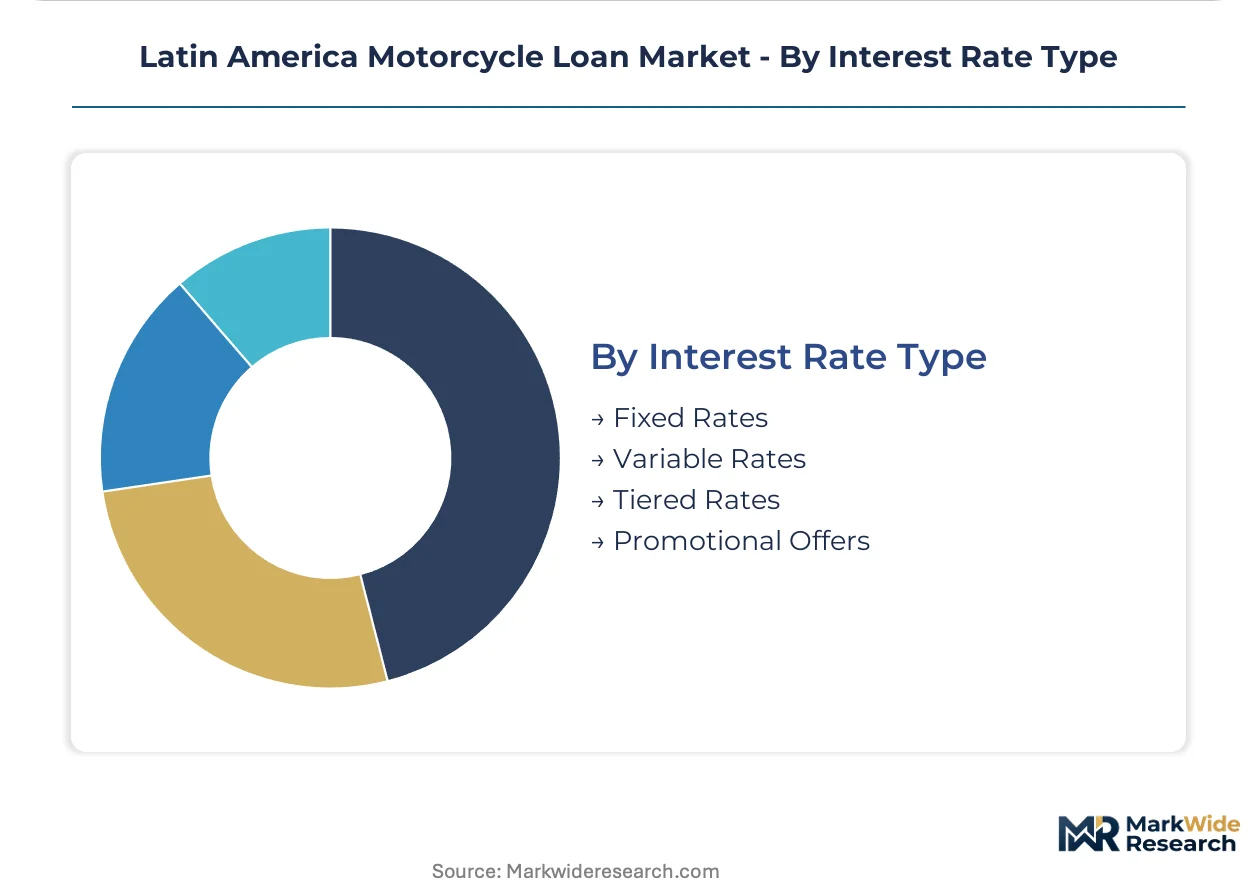
Interest Rate Type:
Margin compression pressures are forcing rate structure innovation as SELIC volatility erodes fixed-rate portfolio economics.
- Variable Rates:Indexed to central bank benchmarks with periodic adjustments transferring rate risk to borrowers. Brazil's fleet operators increasingly accept this structure for front-end rate reductions.
- Fixed Rates:Locked obligations through maturity exposing lenders to funding cost mismatches when SELIC rises, still preferred by risk-averse individual borrowers.
- Promotional Offers:Manufacturer-subsidized zero-rate or low-rate programs at point-of-sale, recaptured through higher vehicle pricing or dealer incentives.
- Tiered Rates:Risk-based pricing stratifying borrowers across credit score bands, requiring granular bureau integration that SPC Brasil and Serasa data supports.
Fixed rates hold the largest share; momentum sits with variable rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
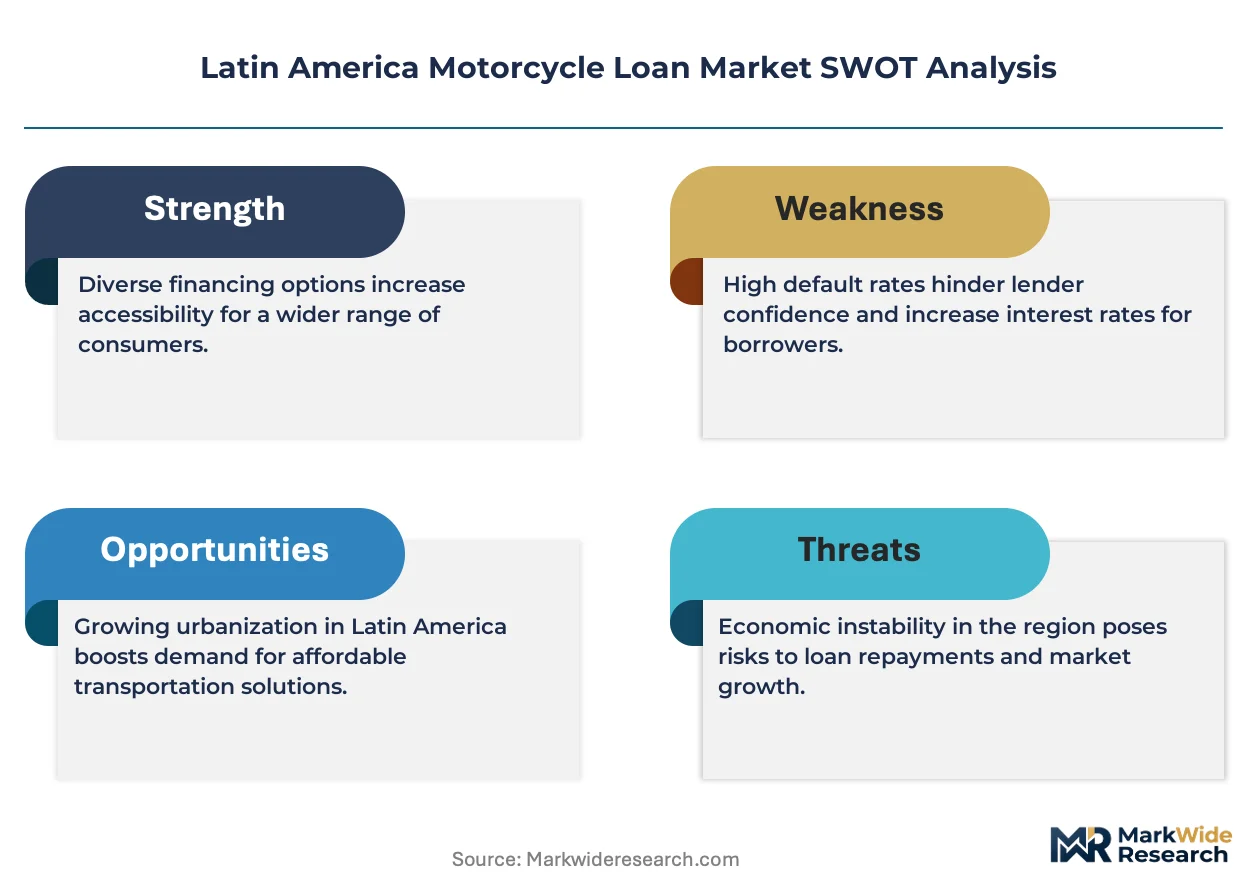
Central bank rate transparency mandates across Brazil, Mexico, and Colombia are accelerating formal credit penetration for two-wheeler financing. Sub-national tax incentives for electric motorcycles in Minas Gerais and delivery fleet electrification programs in Mexico City are redirecting origination flows. Urban density corridors in São Paulo, Mexico City, and Bogotá concentrate demand where last-mile logistics operators scale vehicle commitments.
Brazil
Fleet operators in São Paulo and Minas Gerais dominate secured loan origination for last-mile delivery consolidation. The central bank's SELIC benchmark volatility and consumer credit disclosure tightening reshape lender pricing models. Southeastern state motor vehicle departments pilot blockchain-enabled lien registration to compress documentation cycles.
Mexico
CNBV's 2024 fintech licensing framework formalizes digital-first lender entry with mandated capital buffers and real-time reporting protocols. Embedded finance at Honda and Yamaha dealerships collapses approval timelines through point-of-sale pre-qualification. Mexico City delivery services scale two-wheeler commitments to reduce fuel costs and navigate congestion.
Colombia
Subscription-based vehicle access displaces traditional installment purchase among gig workers in Bogotá and Medellín. Informal peer-to-peer vehicle financing in secondary markets siphons price-sensitive borrowers from formal channels. Colombian fintech platforms capture this cohort through app-based fleet membership models.
Chile
Credit bureau fragmentation complicates cross-border portfolio management for lenders with Andean corridor exposure. The country's national banking regulator maintains reserve requirements that constrain pricing flexibility for motorcycle portfolios. Santiago's urban logistics operators show emerging demand for telematics-bundled underwriting with GPS-enabled collateral tracking.
Peru
Motorcycle ownership rates sit below regional medians with minimal captive finance presence from manufacturer-affiliated lenders. Sub-national transport electrification incentives in Lima-Callao create preferential origination windows for electric two-wheeler financing. Agricultural and informal-sector borrowers in regional corridors pilot seasonal or revenue-linked repayment schedules.
Latin America Motorcycle Loan Market Competitive Landscape
Channel-controlling players compete with product-specialist players across origination architecture and borrower access models. Retail banking networks with pre-approval infrastructure at point-of-sale terminals hold structural advantages in approval velocity. Three archetypes dominate: universal banks leveraging branch density, captive finance arms integrating manufacturer subsidies, and digital-native platforms collapsing documentation cycles. Strategic consolidation and API-driven dealer connectivity represent the dominant competitive moves as legacy core banking platforms require middleware adaptation.
Among Brazil-based universal banks, Banco Santander, Banco Bradesco, and Banco do Brasil occupy positions spanning retail origination infrastructure and captive manufacturer partnerships. These institutions exemplify the channel-control archetype through point-of-sale terminal penetration and pre-approval engine deployment. Honda Financial Services represents the captive finance model, integrating insurance and maintenance bundles into installment contracts. The competitive terrain favors entities that compress funding timelines while navigating central bank reserve requirements and disclosure mandates.
| Leading Market Players |
|---|
| Banco Santander |
| Banco Bradesco |
| Banco do Brasil |
| Banco Votorantim |
| Banco Safra |
| Scotiabank |
| CitiBanamex |
| Honda Financial Services |
| Harley-Davidson Financial Services |
| Others |
Pricing and Supply Chain Analysis
Japanese and South Korean component suppliers dominate telematics hardware and GPS-enabled collateral tracking systems, concentrating margin capture upstream while Brazilian and Mexican lenders compete on origination velocity and bundled service economics downstream.
Pricing Analysis
Volume commitment tiers create the primary spread between fleet operators and individual borrowers across Latin America motorcycle finance. Three-tier pricing structure separates large fleet accounts with telematics integration from standard individual buyers through unsecured channels and economy-tier borrowers accessing informal lending alternatives. Pricing pressure stems from Brazil's SELIC benchmark volatility compressing net interest margins on fixed-rate portfolios. Fleet operators exhibit lowest price sensitivity due to fuel cost savings and congestion navigation benefits, while individual buyers in urban peripheries demonstrate highest elasticity to rate movements.
Supply Chain Analysis
Export-control restrictions on semiconductor components from Taiwan and South Korea are constraining telematics device availability for GPS-enabled collateral tracking systems. Hardware assembly concentrates in China, Mexico, and Brazil with final integration at São Paulo and Mexico City distribution hubs. Lithium-ion battery cell supply rests on South Korean and Chinese cathode material flows vulnerable to tariff exposure at USMCA border crossings. Distribution runs through captive dealer networks anchored by Honda and Yamaha point-of-sale terminals with direct lender API integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America motorcycle finance is approaching a platform-economics inflection as embedded finance APIs and open-banking interoperability collapse origination friction and disintermediate traditional credit bureau architectures.
For Market Incumbents: Harden core banking infrastructure against API-driven dealer connectivity demands while consolidating middleware layers that accommodate real-time credit decisioning. Defensive priorities center on pre-approval engine deployment at point-of-sale terminals to neutralize digital-native entrants and regulatory capital buffers mandated by CNBV's fintech licensing framework.
For New Entrants and Emerging Players: Establish a beachhead in Peru and Ecuador where motorcycle ownership rates sit below regional medians and captive finance presence remains minimal. White-space targets include telematics-bundled underwriting for agricultural borrowers with seasonal revenue-linked repayment schedules and subscription-based fleet membership models displacing traditional installment structures among Colombian gig workers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital-first lending platforms as CNBV-mandated minimum capital buffers and real-time reporting protocols favor technology-native underwriters over legacy banks. Acquisition targets include sub-scale regional lenders in Guanajuato and Jalisco consolidating to meet regulatory thresholds. The signal to watch is blockchain-enabled lien registration adoption rates across Brazilian state motor vehicle departments as documentation cycle compression indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Driven Dealer Connectivity | Collapses approval cycles from days to minutes at Honda and Yamaha point-of-sale terminals. |
| Telematics-Bundled Underwriting | Converges GPS-enabled collateral tracking with usage-based insurance for dynamic fleet pricing. |
| Blockchain Lien Registration | Eliminates notary bottlenecks extending funding timelines by five to ten business days. |
| Subscription-Based Fleet Access | Captures gig-economy drivers in Bogotá and Medellín through app-based membership models. |
| Andean Corridor Expansion | Addresses underpenetrated Peru and Ecuador markets with minimal captive finance presence. |
Research Methodology
The analysis maps secured loan origination, dealer financing programs, unsecured consumer credit, and subscription-based fleet access, each validated through primary interviews with motorcycle lender underwriting heads, captive finance strategy directors, fintech platform CTOs, and central bank regulatory affairs officers. Secondary validation draws from Brazil's central bank consumer credit disclosure filings, CNBV fintech licensing registry data, ANVISA vehicle homologation records, and Serasa credit bureau scoring architecture documentation. Bottom-up origination volume estimates triangulate against top-down macroeconomic absorption models.
Assumptions held fixed include SELIC benchmark trajectory ranges, CNBV capital buffer maintenance thresholds, and electric two-wheeler tax abatement continuity in Minas Gerais. The projection horizon spans loan type segmentation across collateral structures, customer tier stratification between fleet and individual borrowers, tenure preference distributions, and interest rate type adoption patterns. CAGRs derive from regression-weighted historical origination momentum against projected fleet operator expansion in São Paulo and Mexico City delivery corridors. Industry-specific inputs incorporate telematics penetration curves and blockchain lien registration pilot scalability.
Macroeconomic conditions sit as an overlay; deviation in Brazil's SELIC volatility bands, Mexican peso liquidity conditions, or Colombian informal lending substitution rates would shift the trajectory. Material shifts in CNBV fintech licensing enforcement intensity or ANVISA safety standard update frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Germany Auto Loan Market