
 Housing Finance Market | 2026-2036
Housing Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Housing Finance Market Analysis
Licensed mortgage underwriter capacity is unwinding across regional banking networks, creating origination bottlenecks that non-bank lenders exploit. Rocket Mortgage leverages its proprietary digital platform to compress closing cycles and capture purchase-market share from branch-dependent rivals. U.S. Bank sustains its position through balance sheet depth and correspondent relationships with community lenders. Guild Mortgage specializes in construction-to-permanent products that serve first-time buyers in supply-constrained Sun Belt metros.
Housing finance encompasses the array of credit instruments, securitization mechanisms, and servicing infrastructure that channel capital from institutional investors to residential property purchasers, with loan-to-value ratios, debt-to-income thresholds, and credit score cutoffs functioning as core underwriting parameters that determine eligibility and pricing. Mortgage loans anchor the product mix, generating recurring servicing fee streams and secondary market execution opportunities that lenders optimize for gain-on-sale margins. Online alternatives within service type are expanding fastest, as API-connected income verification and automated valuation models displace manual document collection. Traditional financing retains the largest volume footprint but faces margin compression from fintech-enabled disintermediation.
Fannie Mae and Freddie Mac conservatorship structures in the United States shape conforming loan limits and securitization standards that define the investable universe for fixed-income portfolios. The Consumer Financial Protection Bureau enforces qualified mortgage rules and ability-to-repay documentation that filter borrower eligibility and litigation exposure. FHA insurance programs expand market access for credit-impaired applicants, embedding countercyclical stabilization into federal housing policy. Stakeholders must monitor how Basel III endgame proposals alter bank holding company capital treatment of mortgage servicing rights and residual interests.
Market Dynamics
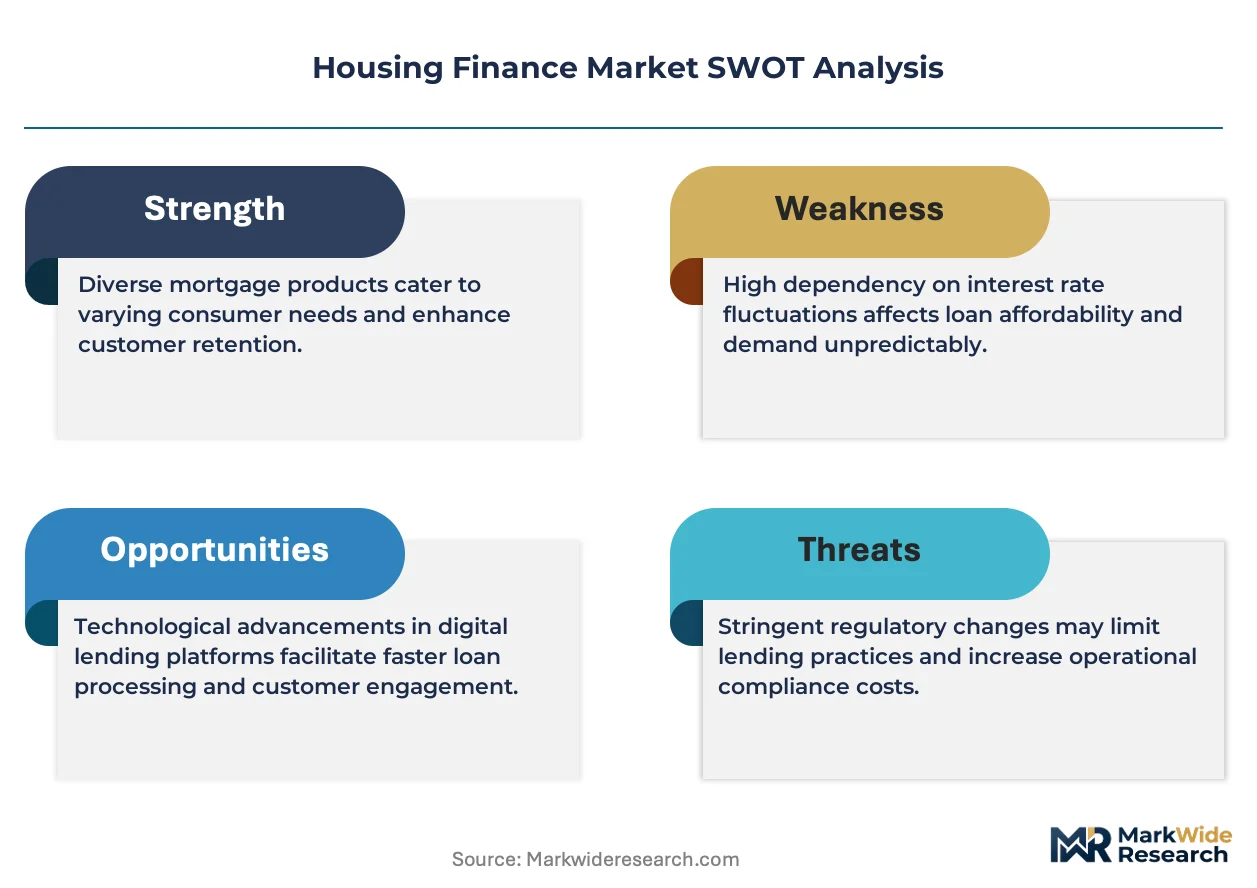
Basel III capital adequacy requirements are forcing regional banks to shed mortgage servicing rights and shrink balance sheet exposure, redirecting origination flow toward non-bank lenders with lighter regulatory burdens and securitization-dependent funding models.
Growth Catalysts
- API-connected income verification:Automated employment and asset verification platforms reduce manual document collection cycles from weeks to hours. First-time buyer segments with thin credit files gain approval access previously blocked by legacy underwriting workflows.
- FHA insurance programs:Federal countercyclical stabilization mechanisms expand market access for credit-impaired applicants during rate volatility periods. Embedded government backstops sustain origination volumes when private mortgage insurance retreats.
- Sun Belt metro concentration:Supply-constrained housing markets in Texas, Florida, and Arizona generate construction-to-permanent loan demand that outpaces national origination growth rates. Migration-driven household formation sustains purchase-market activity independent of refinancing cycles.
Market Restraints
- Basel III endgame mortgage servicing rights treatment:Proposed risk-weighting increases for MSR holdings elevate capital charges above economic returns for bank holding companies. Regulatory uncertainty freezes portfolio acquisition appetite among depository institutions.
- Interest rate volatility:Rapid benchmark shifts compress gain-on-sale margins and extend pipeline hedging costs. Warehouse funding spreads for non-bank originators widen disproportionately during central bank policy transition periods.
- Secondary market liquidity concentration:Fannie Mae and Freddie Mac conservatorship structures create single-counterparty dependency for conforming loan execution. Issuance capacity constraints during stress periods transmit funding disruptions across origination channels.
Strategic Opportunities
- Construction-to-permanent product expansion:Supply-constrained entry-level markets reward lenders with specialized builder relationships and draw-schedule expertise. First-time buyer cohorts demonstrate willingness to absorb rate locks through extended build timelines.
- Digital closing platform integration:Remote online notarization and e-note vaulting converge to eliminate geographic friction from loan execution. Title and settlement process compression unlocks cost structures unavailable to branch-dependent competitors.
- Qualified mortgage rule recalibration:Consumer Financial Protection Bureau ability-to-repay documentation revisions may expand non-QM execution channels. Alternative credit data incorporation creates eligibility pathways outside traditional FICO-centric underwriting.
Industry Challenges
- Licensed underwriter capacity scarcity:Regional bank network unwinding eliminates training pipelines that historically supplied mortgage operations talent. Non-bank competitors face recruitment friction against technology sector compensation benchmarks.
- Legacy servicing system integration:Proprietary digital platforms require costly middleware development to connect with GSE loan delivery systems. API standardization gaps between fintech origination stacks and investor reporting protocols extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Housing Finance Market |
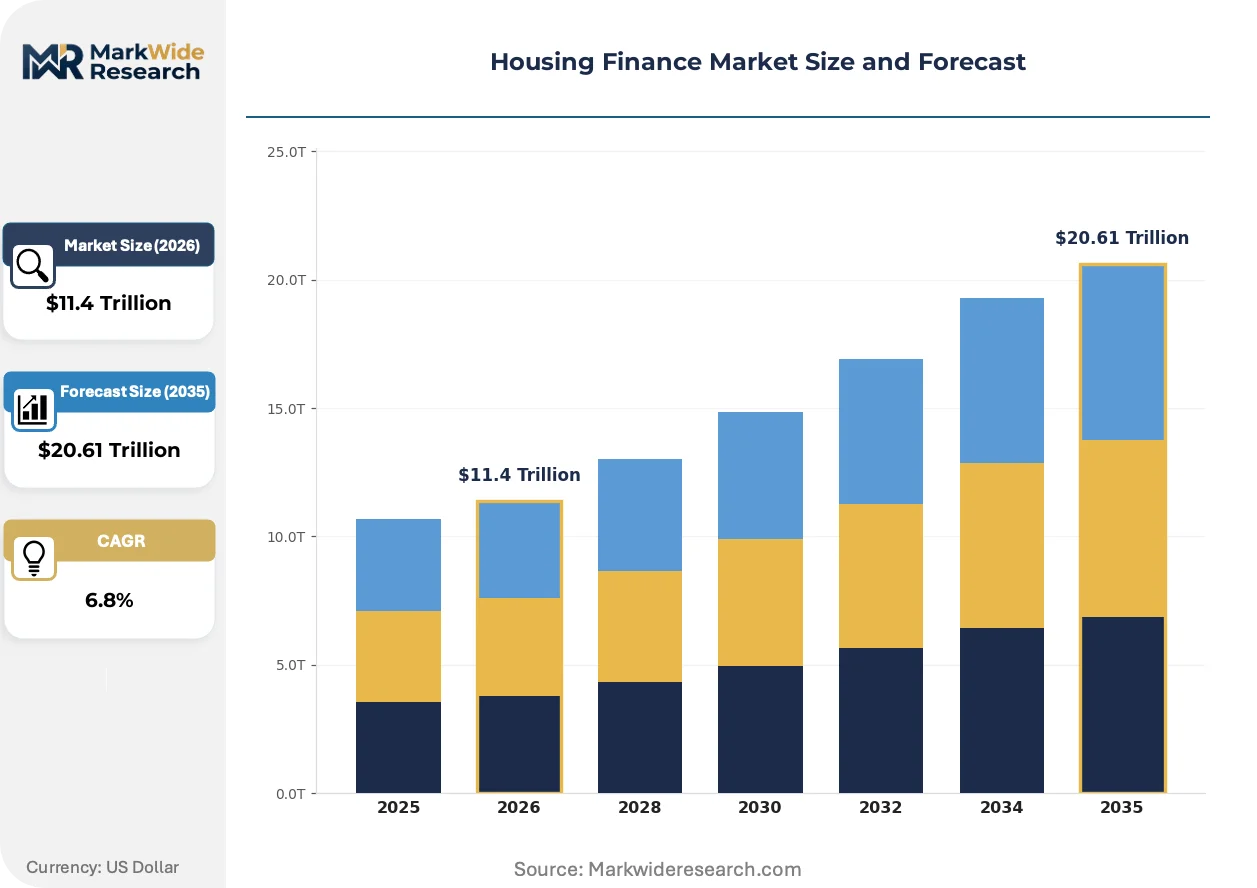
| Market Size in 2026 | $11.4 Trillion |
| Market Size in 2035 | $20.61 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mortgage Loans, Home Equity Loans, Lines of Credit, Refinancing Options Customer Type: First-Time Buyers, Real Estate Investors, Existing Homeowners, Developers Service Type: Traditional Financing, Online Alternatives, Government Programs, Private Financing Term Length: Short-Term Loans, Medium-Term Loans, Long-Term Loans, Flexible Duration Options |
| Companies Covered | Bank of America, LoanDepot, United Wholesale Mortgage, Fairway Independent Mortgage, Guild Mortgage, Rocket Mortgage, Chase, U.S. Bank, CrossCountry Mortgage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Housing Finance Market Emerging Trajectories
Automated valuation models and income verification APIs are compressing origination timelines and redistributing competitive advantage toward technology-native lenders with direct-to-consumer distribution infrastructure.
Automated valuation models leverage satellite imagery and municipal records to generate collateral assessments without physical inspection. Wholesale and correspondent lenders adopt these tools to accelerate purchase cycle responsiveness. The technology is fragmenting appraisal fee revenue pools and compressing traditional valuation service provider margins across conforming loan segments.
Qualified mortgage rule modifications under Consumer Financial Protection Bureau review are reshaping documentation standards for non-QM execution. Expanded alternative credit data acceptance creates eligibility pathways for gig economy borrowers with irregular income documentation. Subprime and near-prime segments are responding with specialized product development targeting previously excluded credit profiles.
First-time buyer segments are bypassing branch-based loan officer relationships in favor of mobile-optimized application platforms with real-time status transparency. Digital-native lenders capture purchase-market share through rate lock transparency and closing timeline guarantees. This channel rotation is most visible in competitive Sun Belt metros where builder-affiliated lending arrangements face disintermediation pressure from independent digital platforms.
Housing Finance Market Segmentation
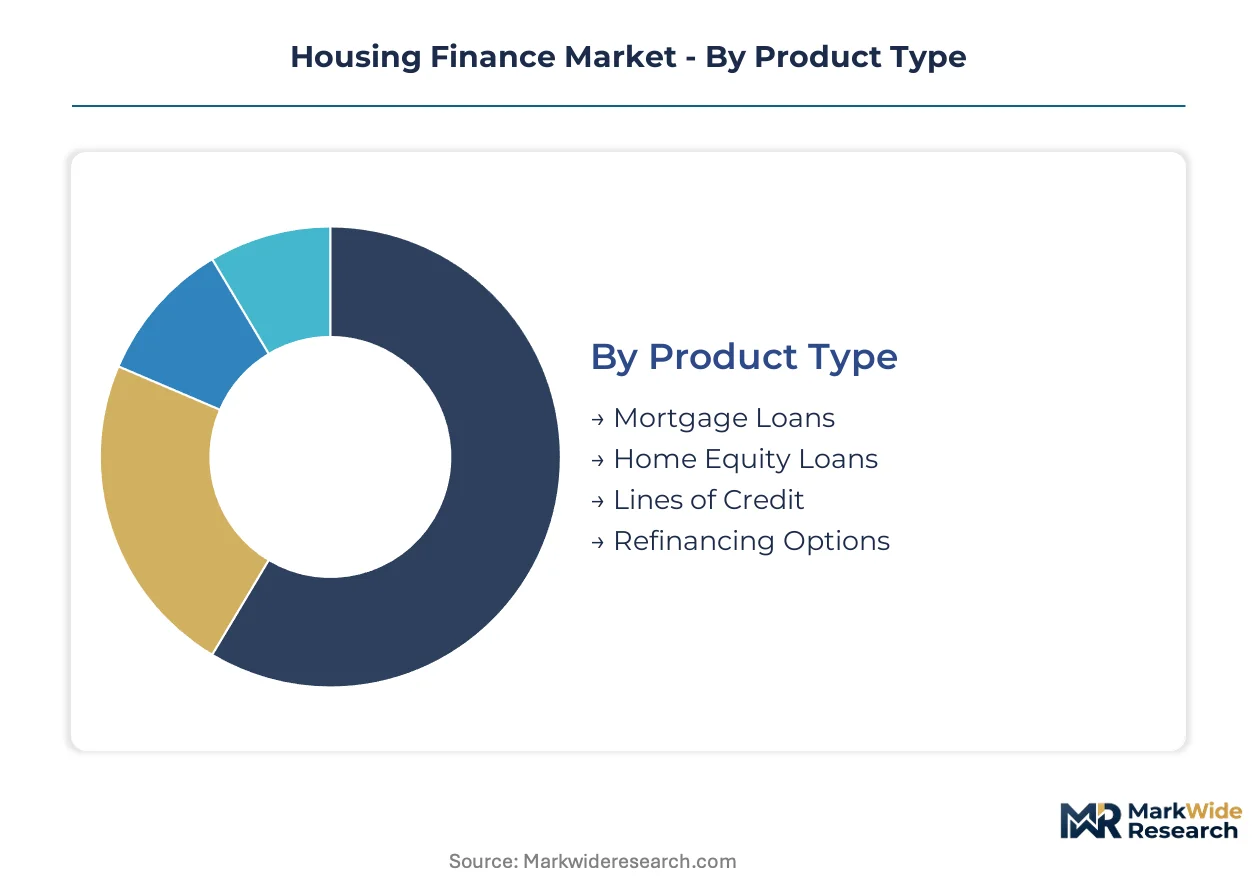
Housing finance segmentation reveals distinct capital allocation patterns across borrower profiles and funding channels. Lenders optimize product mix and distribution strategy based on regulatory treatment, technology infrastructure, and geographic demand concentration.
Product Type:
Domestic demand concentrates in amortizing instruments with GSE execution pathways, while cross-border capital flows into securitized pools.
- Mortgage Loans:Amortizing debt instruments secured by first-lien residential collateral generate recurring servicing revenue and secondary market execution. First-time buyers in Sun Belt metros drive purchase-volume concentration as construction-to-permanent products address supply constraints. FHA insurance backstops sustain origination through rate volatility cycles.
- Home Equity Loans:Closed-end second-lien products extract accumulated collateral value for debt consolidation or home improvement. Existing homeowners in high-appreciation markets deploy these instruments when refinancing economics deteriorate. LTV thresholds and appraisal requirements filter eligibility.
- Lines of Credit:Revolving structures provide liquidity without immediate principal amortization obligations.
- Refinancing Options:Rate-term and cash-out executions respond to benchmark yield curve positioning.
Mortgage loans command the established base. The steepest expansion runs through home equity products as rate-locked homeowners seek liquidity alternatives.
Customer Type:
Cost tier stratification separates rate-sensitive mass-market segments from relationship-driven commercial borrowers.
- First-Time Buyers:Thin-credit-file applicants with limited down payment capacity depend on FHA insurance and automated underwriting platforms. Digital income verification APIs compress approval timelines from weeks to hours. Sun Belt migration patterns concentrate demand in Texas, Florida, and Arizona metros.
- Real Estate Investors:Portfolio landlords and fix-and-flip operators access non-QM execution channels with alternative documentation requirements. Debt service coverage ratio underwriting replaces W-2 income verification. Private capital and correspondent lenders dominate this segment.
- Existing Homeowners:Seasoned borrowers with established payment history and accumulated equity.
- Developers:Construction-phase financing for ground-up residential projects.
Existing homeowners command the established base. The steepest expansion runs through first-time buyers as digital platforms dismantle legacy approval barriers.
Service Type:
Volume concentration shifts from branch-dependent origination toward API-connected digital infrastructure.
- Traditional Financing:Depository institutions with balance sheet capacity and correspondent relationships maintain share through rate transparency and closing certainty. Regional bank networks face underwriter capacity constraints as Basel III treatment of mortgage servicing rights elevates capital charges.
- Online Alternatives:Direct-to-consumer platforms leverage automated valuation models and income verification APIs to compress closing cycles. Non-bank lenders capture purchase-market share from branch-dependent rivals through rate lock guarantees and real-time status transparency.
- Government Programs:FHA, VA, and USDA insurance mechanisms expand market access for credit-impaired applicants.
- Private Financing:Portfolio lenders and hard-money sources serve non-conforming credit profiles.
Traditional financing commands the established base. The steepest expansion runs through online alternatives as mobile-optimized platforms displace loan officer relationships.
Term Length:
Margin structure varies with duration risk and prepayment optionality embedded in contractual terms.
- Short-Term Loans:Bridge financing and construction-phase instruments carry floating-rate exposure and balloon maturities. Developers in supply-constrained markets absorb rate volatility through extended build timelines. Draw-schedule expertise separates specialized lenders from generalist competitors.
- Long-Term Loans:Thirty-year fixed-rate amortization structures dominate conforming execution with GSE backstops. Prepayment optionality and duration risk transfer to institutional investors through mortgage-backed securities. The Consumer Financial Protection Bureau qualified mortgage rules standardize documentation requirements.
- Medium-Term Loans:Hybrid adjustable-rate structures with fixed initial periods.
- Flexible Duration Options:Custom amortization schedules for non-standard income patterns.
Long-term loans command the established base. The steepest expansion runs through short-term instruments as construction-to-permanent products address entry-level supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Housing Finance Agency anchors the dominant geography through conforming loan limits and GSE conservatorship structures. Regulatory treatment of mortgage servicing rights under Basel III endgame proposals is redistributing origination capacity across national banking networks. Capital allocation patterns concentrate in markets with deep secondary market liquidity and government-sponsored enterprise backstops.
United States
Fannie Mae and Freddie Mac securitization standards define the investable universe for institutional fixed-income portfolios. The Consumer Financial Protection Bureau enforces qualified mortgage rules and ability-to-repay documentation that filter borrower eligibility. Sun Belt metros in Texas, Florida, and Arizona generate construction-to-permanent loan demand that outpaces national origination growth rates.
Canada
Office of the Superintendent of Financial Institutions capital adequacy requirements shape mortgage insurer capital buffers and lender risk-weighting frameworks. The Canada Mortgage and Housing Corporation provides mortgage default insurance that expands market access for high-ratio borrowers. Toronto and Vancouver housing markets concentrate origination volume through supply-constrained price dynamics and international capital inflows.
United Kingdom
Financial Conduct Authority mortgage conduct of business rules standardize affordability assessments and interest rate stress testing. The Prudential Regulation Authority oversees capital treatment of residential mortgage exposures for deposit-taking institutions. London and Southeast England housing markets sustain prime lending segments through employment concentration in financial services.
Germany
Bundesanstalt für Finanzdienstleistungsaufsicht supervision covers mortgage lending standards and covered bond issuance requirements. Pfandbrief legislation establishes legal frameworks for mortgage-backed securities that channel institutional capital into residential lending. Munich and Frankfurt metropolitan areas concentrate jumbo mortgage origination through high-income employment clusters.
Australia
Australian Prudential Regulation Authority serviceability buffers and interest-only lending caps constrain credit growth in overheated housing segments. The Australian Securities and Investments Commission enforces responsible lending obligations that elevate documentation requirements. Sydney and Melbourne housing markets drive origination volume through population concentration and supply constraints.
Housing Finance Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across product niches and geographic markets. Depository institutions with balance sheet depth compete against non-bank originators with securitization-dependent funding models and lighter regulatory burdens. Three archetypes dominate: technology-native direct-to-consumer platforms, balance sheet-heavy diversified banks, and construction-lending specialists with builder network relationships. Competitive moves center on digital closing platform integration and correspondent channel expansion to capture purchase-market share from branch-dependent rivals.
Within the technology-native tier, Rocket Mortgage exemplifies direct-to-consumer platform scale with proprietary digital infrastructure. U.S. Bank and Chase represent diversified banking archetypes with balance sheet capacity and GSE correspondent relationships. Guild Mortgage occupies a specialist position in construction-to-permanent products serving first-time buyers in supply-constrained Sun Belt metros.
| Leading Market Players |
|---|
| Bank of America |
| LoanDepot |
| United Wholesale Mortgage |
| Fairway Independent Mortgage |
| Guild Mortgage |
| Rocket Mortgage |
| Chase |
| U.S. Bank |
| CrossCountry Mortgage |
| Others |
Supply Flow & Price Mechanics
GSE correspondent channel scale economies compress origination cost structures for high-volume lenders while elevating price floors for regional banks with thinner balance sheet capacity. This concentration dynamic feeds directly into how mortgage servicing rights trade and how warehouse funding spreads tier across originator archetypes.
Pricing Analysis
Geographic price spreads widen between Sun Belt metros with builder-affiliated lending arrangements and Northeast markets dominated by depository branch networks. Three-tier pricing structure across premium digital platforms, standard correspondent channels, and economy wholesale operations separates Rocket Mortgage's rate-lock guarantees from regional bank quoted rates. Cost compression in the wholesale tier intensifies because non-bank aggregators compete on gain-on-sale margin rather than balance sheet yield. First-time buyers in supply-constrained markets demonstrate lowest price sensitivity, while rate-term refinancers exhibit highest elasticity to basis point shifts.
Supply Chain Analysis
The United States anchors mortgage origination capacity through Fannie Mae and Freddie Mac securitization infrastructure, with Canada and the United Kingdom contributing cross-border capital flows into agency MBS pools. Funding draws from warehouse credit facilities, GSE cash window executions, and private-label securitization conduits. Single-source vulnerability concentrates in the GSE conservatorship structure where issuance capacity constraints transmit disruptions across origination channels. Distribution runs through correspondent lender networks, direct-to-consumer digital platforms, and retail branch footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mortgage servicing rights and ancillary insurance products generate recurring fee streams expanding faster than gain-on-sale execution margins, positioning the market as a service-attach opportunity for platforms with integrated servicing infrastructure.
For Market Incumbents: Secure correspondent channel relationships with community lenders before non-bank competitors capture purchase-market share through digital closing platforms. Defensive consolidation should prioritize mortgage servicing rights portfolios that retain cash flow visibility under Basel III endgame capital treatment. Balance sheet depth at U.S. Bank and Chase represents the priority lever against fintech-enabled disintermediation. For New Entrants and Emerging Players: Anchor in construction-to-permanent products serving first-time buyers in Texas, Florida, and Arizona metros where supply constraints sustain origination volume independent of refinancing cycles. The most penetrable segment sits with thin-credit-file applicants previously blocked by legacy underwriting workflows. A go-to-market angle through builder-affiliated digital platforms bypasses established loan officer relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors non-bank originators with proprietary servicing platforms and API-connected income verification infrastructure. Long-term viability over a five-to-ten year window rests on execution capability in purchase markets rather than rate-sensitive refinancing volume. The acquisition target archetype combines digital origination scale with retained servicing portfolios. The signal to watch is Consumer Financial Protection Bureau qualified mortgage rule recalibration expanding non-QM execution channels.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Closing Platform Integration | Remote online notarization and e-note vaulting eliminate geographic friction from loan execution timelines. |
| Correspondent Channel Expansion | Community lender relationships capture purchase-market share from branch-dependent regional bank networks. |
| Mortgage Servicing Rights Acquisition | Recurring fee streams retain cash flow visibility under evolving Basel III capital treatment frameworks. |
| Construction-to-Permanent Product Development | Builder network relationships address entry-level supply constraints in Sun Belt migration corridors. |
| Alternative Credit Data Partnership | Gig economy income verification expands eligibility pathways outside traditional FICO-centric underwriting. |
Methodological Framework
Initial hypotheses were tested against primary input from mortgage operations executives, correspondent lending directors, GSE securitization specialists, and digital platform product managers and refined through secondary validation against SEC 10-K filings, Federal Housing Finance Agency data releases, Consumer Financial Protection Bureau rulemaking dockets, and Mortgage Bankers Association origination surveys. Bottom-up loan volume modeling triangulated against top-down housing finance flow-of-funds analysis.
Variance decomposition across the projection horizon isolates volume drivers by product type, customer segment, service channel, and geographic demand concentration. Analytical framework segments modeled dimensions across mortgage instrument structure, borrower credit profile, origination technology stack, and regional regulatory treatment. CAGRs derive from cohort-level origination trajectories and servicing portfolio runoff schedules. Forecast inputs incorporate Federal Reserve policy transition paths and Basel III endgame implementation timelines.
Underlying assumptions cover interest rate volatility regimes, GSE conservatorship structures, and non-bank funding market liquidity, with deviation risk concentrated in warehouse funding spread dislocation and secondary market execution capacity constraints. Recalibration cycles align with material shifts in central bank policy, regulatory capital treatment, and digital platform adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Asset-Based Lending Market