
 China Non-Alcoholic Beverages Market | 2026-2036
China Non-Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
China Non-Alcoholic Beverages Market Intelligence
Flavor chemist and food technologist talent pools in the Yangtze River Delta is reorganizing how domestic brands develop reduced-sugar formulations and botanical infusions. Nongfu Spring Co. Ltd leverages its deep well-water sources and PET blow-molding expertise to dominate premium bottled water segments across eastern provinces. Master Kong Holdings Limited anchors the ready-to-drink tea category through extensive distributor networks that reach county-level retail. Danone Asia-Pacific Management Co Ltd competes in specialized nutrition waters and probiotic drinks, drawing on global R&D protocols adapted for Chinese palates.
China non-alcoholic beverages encompass formulated liquid refreshments excluding ethanol, spanning carbonated soft drinks, fruit and vegetable juices, functional drinks with added vitamins or minerals, and packaged still or sparkling waters, typically processed through reverse osmosis, pasteurization, or aseptic cold filling to achieve shelf stability and sensory consistency. These products serve hydration, refreshment, nutritional supplementation, and social consumption occasions across households, workplaces, and foodservice channels. Bottled water and functional beverages capture the most dynamic expansion, with mineral-rich and pH-balanced waters attracting health-conscious urban buyers while energy and probiotic drinks penetrate gym and office channels. Soft drinks remain the largest volume pool but face margin compression as sugar taxes and labeling rules elevate reformulation costs.
SAMR enforces national food safety standards including GB 7101 for beverages and updated nutrition labeling rules that mandate prominent sugar declarations, directly pressuring reformulation timelines and ingredient sourcing. NMPA oversight of functional claims on beverages restricts how brands market added ingredients like collagen or herbal extracts, creating compliance gates for new product registration. MEE wastewater discharge standards for bottling plants raise capital requirements for production facility upgrades, favoring larger operators with environmental compliance teams. Stakeholders must monitor how SAMR's evolving standards on artificial sweeteners and novel food ingredients will reshape permissible formulations before committing to multi-year capacity investments.
Market Dynamics
Reformulation pressure from SAMR's sugar-labeling mandates is forcing domestic brands to rebuild their ingredient pipelines around natural sweeteners and botanical extracts, compressing legacy formulation cycles from eighteen months to under nine.
Growth Catalysts
- Urban health consciousness:Young adult buyers in Shanghai and Beijing are expanding purchases of probiotic-infused functional beverages, creating pull-through demand for pH-balanced mineral waters across gym and office channels.
- GB 7101 enforcement:Updated national food safety standards are accelerating shelf-space reallocation toward cleaner-label products, rewarding early reformulators with premium positioning.
- Yangtze River Delta talent density:Flavor chemist clusters in Jiangsu and Zhejiang provinces are compressing R&D timelines for reduced-sugar botanical infusions, giving domestic brands technical parity with multinational formulations.
Market Restraints
- MEE wastewater compliance:Bottling plants face capital-intensive discharge standard upgrades, favoring operators with dedicated environmental compliance teams and squeezing mid-tier producers.
- Artificial sweetener sourcing:Erythritol and stevia supply concentrates in Shandong and Guangdong provinces, creating input cost volatility when harvest conditions fluctuate.
- NMPA functional-claim gates:Registration protocols for collagen and herbal extract marketing restrict how brands communicate added-ingredient benefits, extending product launch timelines.
Strategic Opportunities
- County-level distribution gaps:Tier-three and tier-four cities in central China remain underpenetrated for premium packaged waters, offering first-mover shelf space before saturation.
- Cold-chain aseptic filling:Convergence of blow-molding precision and flash-pasteurization systems enables ambient-stable probiotic drinks without refrigeration infrastructure.
- Plant-based beverage whitespace:Oat and almond milk alternatives command minimal presence in Guangdong convenience channels, creating entry points before category maturation.
Industry Challenges
- Reformulation talent scarcity:Food technologists with dual expertise in sensory science and regulatory compliance command premium compensation, constraining mid-cap brand technical capacity.
- Dual carbon facility retrofitting:Bottling plants require substantial capital outlays for energy-efficient blow-molding and water-recovery systems to meet provincial emissions targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Non-Alcoholic Beverages Market |
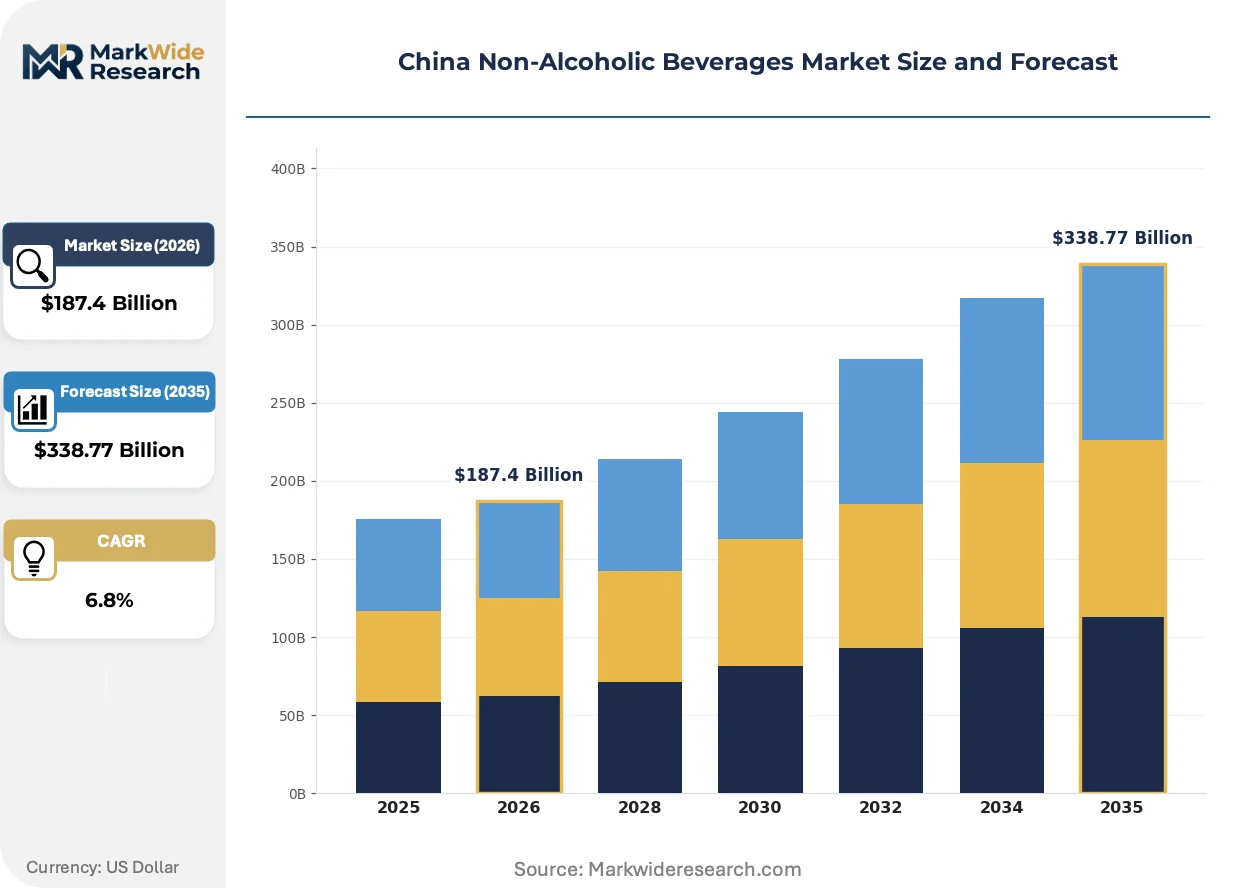
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Juices, Functional Beverages, Bottled Water Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines Consumer Age Group: Kids, Teenagers, Adults, Seniors Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Uni-President China Holdings Ltd, Master Kong Holdings Limited, Nongfu Spring Co. Ltd, Nestle (China) Ltd., Danone Asia-Pacific Management Co Ltd, Hangzhou Wahaha Group Co., Ltd., Hebei Yangyuan ZhiHui Beverage Co. Ltd, Hubei Juneyao Health Drinks Co. Ltd, Coca-Cola China Beverages Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Non-Alcoholic Beverages Market Strategic Shifts & Innovations
Formulation science and channel architecture are undergoing simultaneous recalibration as health claims face tighter scrutiny and distribution networks fragment toward direct-to-office models.
Aseptic cold-filling technology is decomposing the traditional pasteurization-sterilization hierarchy in beverage manufacturing. Tier-one city bottlers are adopting flash-heat and rapid-cool systems at twice the pace of provincial facilities. This technology is decomposing the shelf-life advantage previously held by heat-treated imports, enabling domestic brands to match sensory freshness at lower logistics cost.
SAMR's updated nutrition labeling rules now mandate prominent sugar-content declarations on all packaged drinks. The industrial consequence is a wholesale ingredient sourcing pivot toward monk fruit and allulose alternatives. Functional beverage segments face the steepest compliance burden, with brands stripping added sugars from energy and probiotic lines ahead of enforcement deadlines.
Direct-to-workplace hydration contracts are displacing traditional retail procurement for white-collar employers in Beijing and Shenzhen. Foodservice distributors are losing volume to specialized office-delivery operators who bundle premium waters with coffee and tea services. This channel rotation is most visible in technology and financial services verticals, where facility managers prioritize consolidated beverage sourcing over multi-vendor retail relationships.
China Non-Alcoholic Beverages Market Segmentation
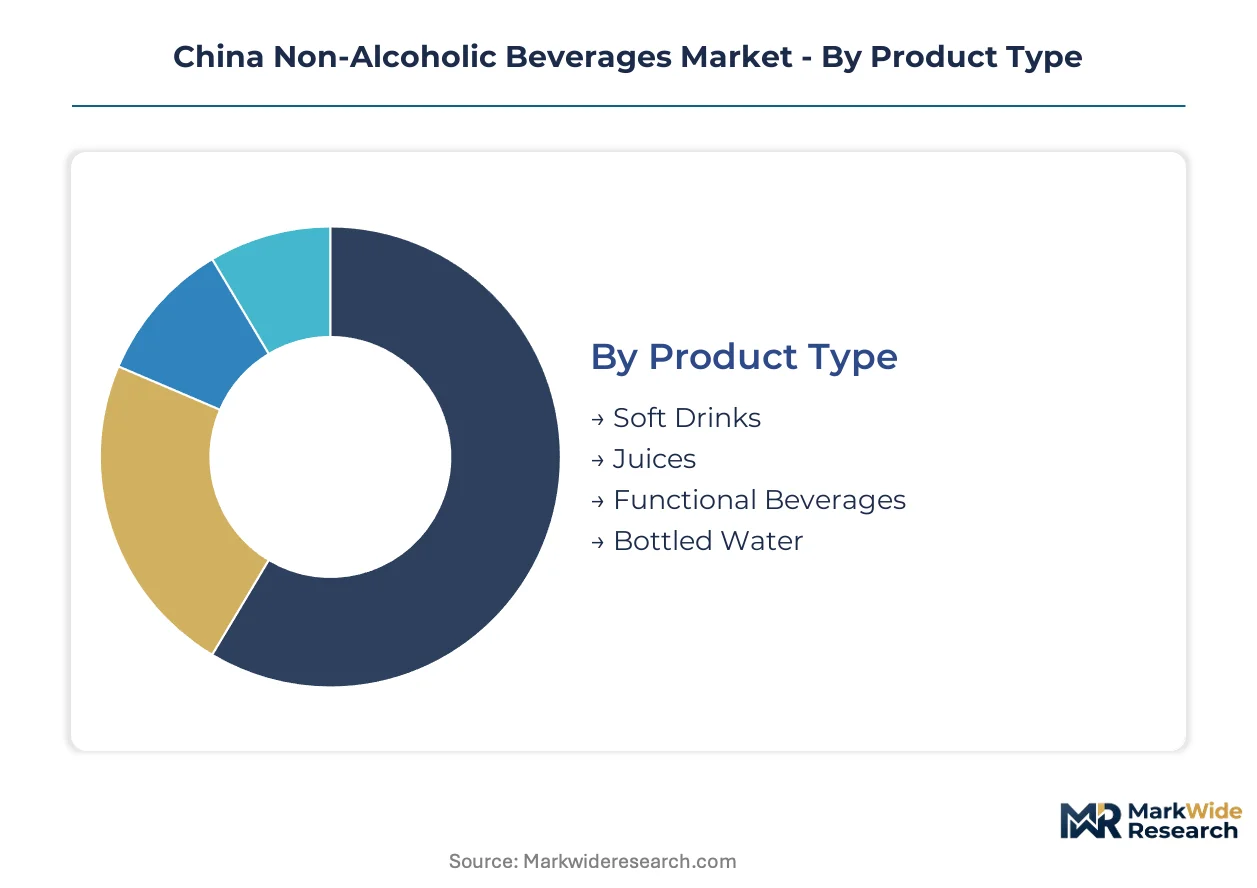
Segmentation reveals how regulatory pressure and channel fragmentation are redistributing margin pools across China's beverage landscape. Understanding where value concentrates within each dimension enables targeted capacity allocation and reformulation investment.
Product Type:
Premium positioning and health claims concentrate margins in functional categories, while volume economics favor mass-market staples with established distribution.
- Soft Drinks:Carbonated formulations face compressed margins as SAMR sugar-labeling mandates force costly reformulation cycles. Legacy brands in Guangdong and Shandong provinces absorb input volatility from concentrated sweetener supply regions.
- Functional Beverages:Probiotic and energy drink segments command shelf-space premiums in Shanghai and Beijing gym channels. NMPA registration gates for collagen and herbal claims extend launch timelines but protect first-mover positioning for compliant entrants.
- Juices:NFC (not-from-concentrate) variants attract tier-one city households seeking cleaner labels, though cold-chain requirements limit geographic reach.
- Bottled Water:Mineral-rich and pH-balanced variants dominate premium segments across eastern provinces, with deep-well sourcing advantages concentrating among Yangtze River Delta operators.
The dominant share belongs to Soft Drinks, while Functional Beverages is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity and brand control, with direct models capturing margin but requiring infrastructure investment.
- Supermarkets:Hypermarket chains in Beijing and Shanghai allocate prime shelf space to reformulated low-sugar lines, using planogram compliance as leverage over supplier terms. GB 7101 enforcement has accelerated category resets toward cleaner-label products.
- Convenience Stores:7-Eleven and FamilyMart networks in Guangdong prioritize grab-and-go functional drinks for office workers. Cold-chain aseptic filling enables ambient-stable probiotic placement without refrigeration infrastructure.
- Online Retail:Tmall and JD.com logistics networks reduce distributor margins but demand promotional pricing discipline during festival windows.
- Vending Machines:Smart payment-enabled units penetrate subway stations and university campuses, though restock frequency constraints favor long-shelf-life formulations.
Supermarkets retain the largest volume share, though Online Retail is expanding most quickly in tier-one cities.
Consumer Age Group:
Purchasing authority and health sensitivity vary sharply across cohorts, driving formulation and messaging differentiation.
- Adults:White-collar professionals in Shenzhen and Beijing drive direct-to-workplace hydration contracts, consolidating procurement decisions with facility managers over individual retail purchases.
- Teenagers:Flavor novelty and social sharing dominate purchase drivers, with citrus and berry profiles dominating convenience channel selection in urban centers.
- Kids:Parental gatekeeping around sugar content limits permissible formulations, with SAMR labeling rules amplifying scrutiny of added sweeteners in school-adjacent retail.
- Seniors:Nutritional supplementation claims attract interest, though NMPA functional-claim restrictions constrain how brands communicate bone-health or digestive benefits.
Adults command the highest per-capita expenditure, while Teenagers show the steepest expansion trajectory in flavored functional categories.
Flavor Profile:
Botanical and regional taste preferences create localization requirements that complicate national rollout strategies.
- Citrus:Mandarin and yuzu variants anchor mass-market acceptance across southern provinces, with flavor chemist clusters in Jiangsu compressing development timelines for reduced-sugar iterations.
- Herbal:Chrysanthemum and goji formulations align with traditional wellness concepts, though sensory consistency challenges require precise extraction protocols from Zhejiang processing facilities.
- Berry:Blueberry and mulberry profiles target premium positioning in tier-one cities, with import-dependent concentrate supply creating cost volatility.
- Tropical:Mango and passionfruit variants dominate summer seasonal launches, with aseptic cold-filling technology preserving volatile aromatic compounds through extended shelf life.
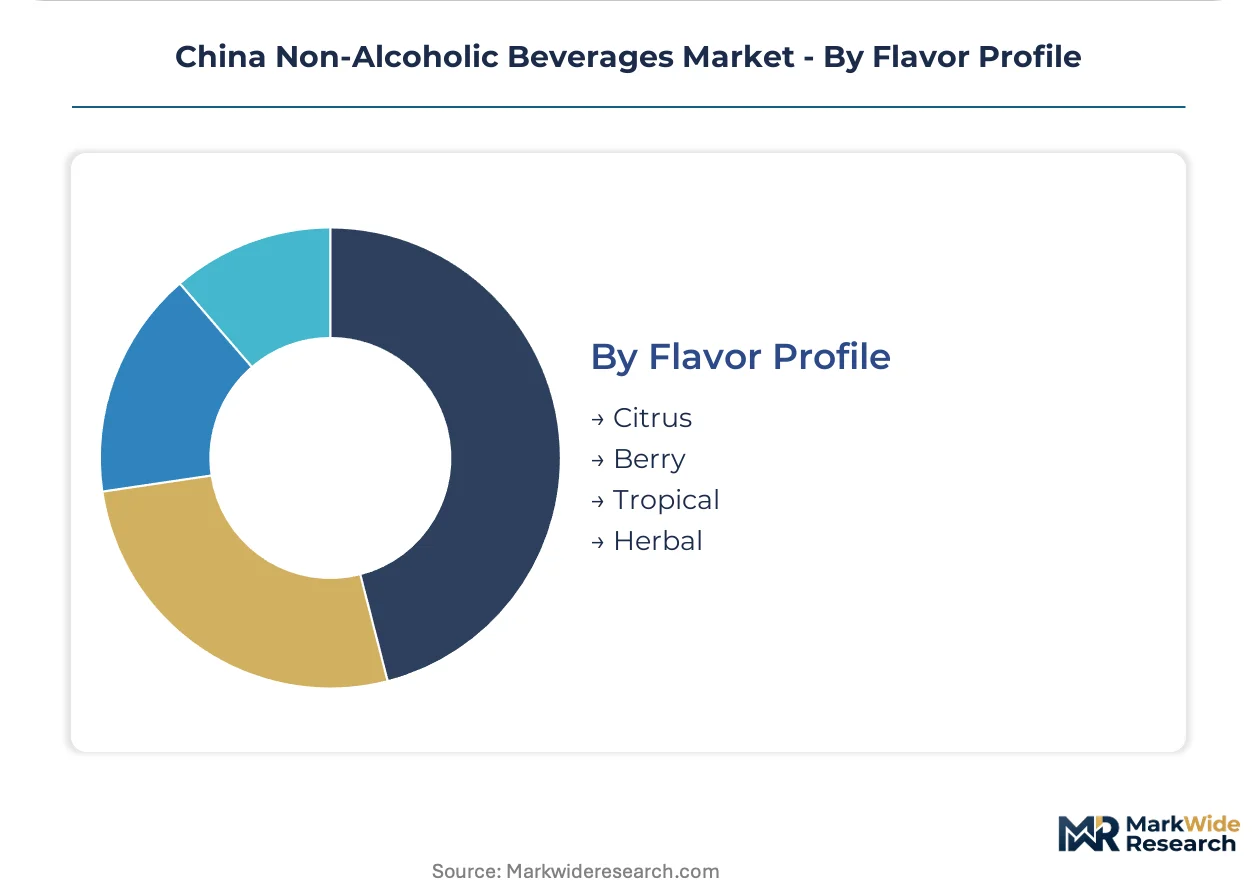
Citrus holds the established volume base, yet Herbal is gaining share fastest as wellness positioning penetrates adult segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across China's provinces diverge sharply between eastern megacities prioritizing premium functional drinks and interior regions where volume-priced soft drinks retain dominance. Yangtze River Delta households allocate substantially higher beverage expenditure per capita than western provinces, with formulation preferences tracking local water quality perceptions and workplace density.
Yangtze River Delta
Shanghai and Hangzhou households drive probiotic-infused functional beverage demand through gym and office channels. SAMR's GB 7101 enforcement accelerates reformulation timelines for Zhejiang-based bottlers. Flavor chemist clusters in Jiangsu compress R&D cycles for reduced-sugar botanical infusions, giving domestic brands technical parity with multinational formulations.
Pearl River Delta
Guangzhou and Shenzhen consumers command premium shelf space for pH-balanced mineral waters and plant-based alternatives. MEE wastewater discharge standards raise capital requirements for Guangdong bottling facility upgrades. Convenience store networks in Dongguan prioritize grab-and-go functional drinks for manufacturing sector workers.
Beijing-Tianjin-Hebei
Direct-to-workplace hydration contracts displace traditional retail procurement among technology and financial services employers. NMPA functional-claim registration protocols restrict collagen and herbal extract marketing for Beijing-headquartered brands. Cold-chain aseptic filling investments concentrate in Tianjin port-zone processing facilities.
Sichuan-Chongqing
Chongqing's dense urban fabric supports vending machine penetration for long-shelf-life formulations. Provincial emissions targets under dual carbon goals pressure Sichuan bottlers toward energy-efficient blow-molding retrofits. Local taste preferences favor citrus and herbal profiles that align with traditional wellness concepts.
Shandong Peninsula
Qingdao and Jinan absorb input volatility from concentrated erythritol and stevia supply regions. Artificial sweetener harvest fluctuations create procurement cost uncertainty for reformulating brands. PET resin and blow-molding equipment suppliers cluster along the peninsula's industrial corridor.
China Non-Alcoholic Beverages Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating among Yangtze River Delta operators possessing captive well-water sources and blow-molding expertise. The mid-cap tier fragments across regional distribution networks, with county-level penetration determining survival. Three archetypes dominate: vertically integrated well-water bottlers, ready-to-drink tea specialists with deep distributor relationships, and functional beverage innovators navigating NMPA registration gates. Competitive moves center on cold-chain aseptic filling investments and direct-to-office channel cultivation.
Among the integrated leader tier, Nongfu Spring Co. Ltd and Master Kong Holdings Limited exemplify contrasting scale strategies, while Danone Asia-Pacific Management Co Ltd represents multinational adaptation to local regulatory and sensory requirements. These three occupy positions spanning premium bottled water dominance, ready-to-drink tea category anchoring, and specialized nutrition waters with global R&D protocols adapted for Chinese palates. Their collective presence shapes shelf-space allocation and reformulation benchmarks across eastern provinces.
| Leading Market Players |
|---|
| Uni-President China Holdings Ltd |
| Master Kong Holdings Limited |
| Nongfu Spring Co. Ltd |
| Nestle (China) Ltd. |
| Danone Asia-Pacific Management Co Ltd |
| Hangzhou Wahaha Group Co., Ltd. |
| Hebei Yangyuan ZhiHui Beverage Co. Ltd |
| Hubei Juneyao Health Drinks Co. Ltd |
| Coca-Cola China Beverages Ltd |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Yangtze River Delta bottling facilities shapes both supply concentration and price floors across China's non-alcoholic beverage sector. Deep-well water access and PET blow-molding scale advantages concentrate margin power among eastern provincial operators while compressing viable entry thresholds for mid-tier reformulators.
Pricing Analysis
Long-term offtake contracts between tier-one city retailers and established bottlers anchor volume pricing, with spot procurement filling seasonal gaps. Three-tier pricing structure across premium, standard, and economy levels separates mineral-rich pH-balanced waters from mass-market purified variants and private-label economy tiers. Cost compression in functional beverage segments is intensifying because SAMR sugar-labeling mandates force rapid reformulation cycles. White-collar employers in Beijing and Shenzhen show least price sensitivity through direct-to-workplace hydration contracts, while county-level distributors in central provinces face acute margin pressure.
Supply Chain Analysis
Shandong Peninsula erythritol and stevia harvests create input chokepoints that propagate volatility through reformulating brands' procurement pipelines. Raw material flows draw from concentrated artificial sweetener processing in Shandong, PET resin production along the peninsula's industrial corridor, and botanical extract facilities in Zhejiang. Single-source vulnerability concentrates in natural sweetener supply when harvest conditions fluctuate. Distribution runs through layered distributor networks reaching county-level retail, with direct-to-office channels bypassing traditional foodservice intermediaries in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's non-alcoholic beverage sector is entering a cyclical recovery phase as post-pandemic workplace normalization restores office-channel consumption volumes. SAMR regulatory clarity on sugar-labeling enforcement provides the cyclical anchor for capacity planning confidence.
For Market Incumbents: Compound shelf-space dominance by accelerating cold-chain aseptic filling investments before NMPA functional-claim registration gates tighten further. Deepen backward integration into captive well-water sources in Jiangsu and Zhejiang to defend margin position against artificial sweetener input volatility. Prioritize direct-to-workplace channel control through facility manager procurement consolidation in Beijing and Shenzhen technology corridors.
For New Entrants and Emerging Players: NMPA fast-track registration for collagen and herbal extract claims offers regulatory beachhead positioning before compliance burdens harden. Target county-level distribution gaps in tier-three and tier-four central China cities where premium packaged water remains underpenetrated. Deploy plant-based beverage launches in Guangdong convenience channels ahead of category maturation, leveraging ambient-stable probiotic technology to minimize cold-chain infrastructure requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bottlers with integrated blow-molding and aseptic filling capabilities over pure-brand plays dependent on co-manufacturing relationships. Long-term viability across the projection horizon rests on environmental compliance teams capable of navigating MEE wastewater discharge upgrades and dual carbon retrofit obligations. Monitor SAMR artificial sweetener approval protocols as the signal for reformulation investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Aseptic Filling Investment | Enables ambient-stable probiotic placement without refrigeration infrastructure in tier-one convenience channels. |
| Direct-to-Workplace Channel Expansion | Consolidates procurement decisions with facility managers over fragmented retail relationships in Beijing and Shenzhen. |
| Natural Sweetener Supply Integration | Reduces procurement cost volatility from Shandong harvest fluctuations through captive erythritol and stevia sourcing. |
| NMPA Functional-Claim Registration | Secures first-mover positioning for collagen and herbal extract marketing before compliance gates extend launch timelines. |
| County-Level Distribution Penetration | Captures shelf space in tier-three and tier-four central China cities ahead of saturation by established eastern operators. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with flavor chemists, beverage brand managers, SAMR regulatory consultants, and convenience channel buyers; and secondary validation through customs records, Nielsen retail audit data, NMPA registration filings, and GB standards documentation. Bottom-up triangulation across provincial bottling capacity and top-down reconciliation against national consumption surveys anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, distribution channel, consumer age cohort, and regional taste preference cluster. CAGRs were derived from regression analysis of historical volume elasticities against regulatory enforcement timelines and urban health consciousness indicators. Specific inputs included SAMR labeling rule implementation schedules, MEE facility upgrade compliance curves, and Yangtze River Delta talent pool migration patterns.
Decision-makers should treat outputs as directional under base assumptions of continued SAMR enforcement trajectory and stable artificial sweetener harvest conditions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as NMPA functional-claim protocols and dual carbon emissions targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Coffee Substitute Market