
 Whole Milk Powder Market | 2026-2036
Whole Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Whole Milk Powder Market Intelligence
Direct procurement between dairy cooperatives and infant formula manufacturers is narrowing as large processors consolidate supply relationships. Fonterra Co-operative Group leverages its New Zealand grass-fed sourcing to sustain premium positioning in Asian markets. Arla Foods amba anchors European supply through its farmer-owned structure, while Amul dominates India's organized dairy channel with unmatched village-level collection density.
Whole milk powder consists of dehydrated milk solids containing standard fat content, typically produced through spray-drying of pasteurized whole milk to preserve protein structure and fat globule integrity for reconstitution stability. The powder serves as a shelf-stable dairy ingredient for food manufacturing, emergency nutrition programs, and regions lacking cold chain infrastructure. Instant whole milk powder leads product type value pools due to superior solubility commanding manufacturing premiums, while organic whole milk powder captures expanding margin pools from European and North American clean-label procurement policies. Infant formula end-use segments drive structural volume growth as demographic expansion in emerging economies sustains long-term ingredient demand.
The EU F-Gas Regulation and REACH chemical standards constrain processing equipment and cleaning agent specifications across European dairy powder facilities, while China's NMPA and national food safety standards govern infant formula ingredient imports with escalating purity requirements. India's FSSAI enforces progressively stricter microbiological limits on dairy powders entering domestic retail and institutional channels. Stakeholders must monitor evolving regulatory divergence between import-dependent markets and self-sufficient dairy regions to align certification investments with destination market access requirements.
Market Dynamics
Large dairy processors are consolidating procurement relationships with infant formula manufacturers, compressing direct cooperative-to-brand channels while Fonterra and Arla lock in multi-year supply agreements that reshape competitive access to premium grass-fed sourcing.
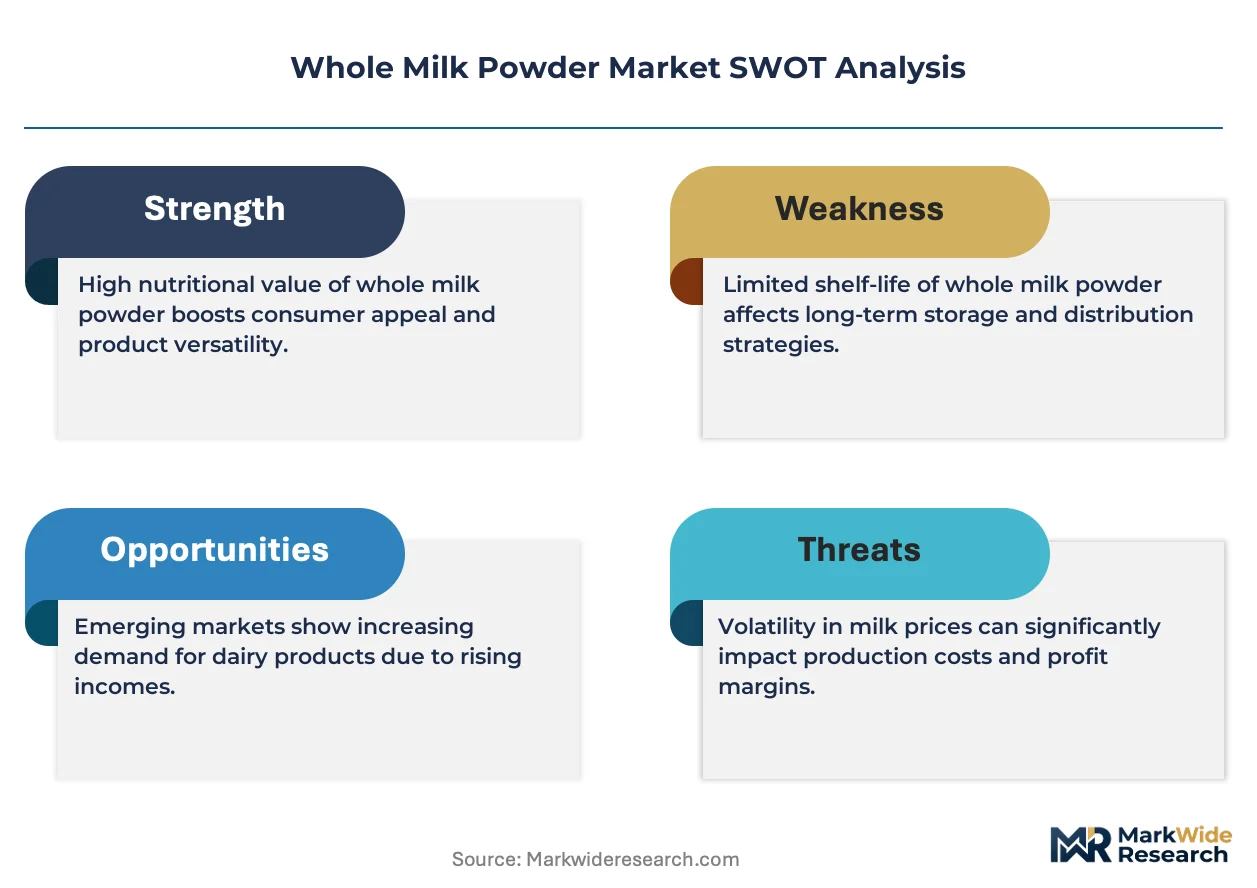
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP refrigerants in spray-drying facilities are accelerating capital replacement cycles, creating demand for modernized processing equipment that improves thermal efficiency and powder quality consistency.
- Infant formula manufacturing:Southeast Asian formula producers are expanding instant whole milk powder procurement as a base ingredient, driven by demographic expansion and rising per-capita dairy consumption in Vietnam and Indonesia.
- Spray-drying automation:Advanced nozzle atomization and inline moisture sensing are reducing protein denaturation rates, enabling processors to command manufacturing premiums for high-solubility instant powder grades.
Market Restraints
- Energy cost volatility:Natural gas and electricity input swings destabilize spray-drying economics, forcing processors to absorb margin compression or pass through costs to price-sensitive institutional buyers.
- New Zealand supply concentration:Fonterra's dominance of global grass-fed whole milk powder creates single-source vulnerability for premium-positioned brands dependent on consistent New Zealand-origin certification.
- Plant-based dairy substitution:Oat and pea protein isolates are capturing share in emergency nutrition programs and food manufacturing applications where reconstitution properties are less critical.
Strategic Opportunities
- Vietnam domestic production scaling:Vinamilk's expansion of powder manufacturing capacity positions the country as a regional export hub serving ASEAN markets with reduced tariff exposure.
- Organic certification tailwinds:European clean-label procurement policies and North American retailer sustainability mandates are expanding margin pools for certified organic whole milk powder grades.
- E-commerce direct distribution:Food ingredient marketplaces are disintermediating traditional dairy broker networks, enabling mid-size processors to access institutional buyers without established trade relationships.
Industry Challenges
- Spray-drying engineering talent scarcity:Specialized expertise in thermal process optimization and powder flow characteristics is concentrated among retiring cohorts, constraining facility expansion timelines.
- REACH compliance documentation:European chemical safety data requirements for cleaning agents and processing aids are extending certification cycles, delaying product launches for export-oriented processors.
- Cold chain infrastructure gaps:Reconstituted whole milk powder distribution in tropical climates requires packaging innovation to prevent caking and lipid oxidation during humid storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole Milk Powder Market |
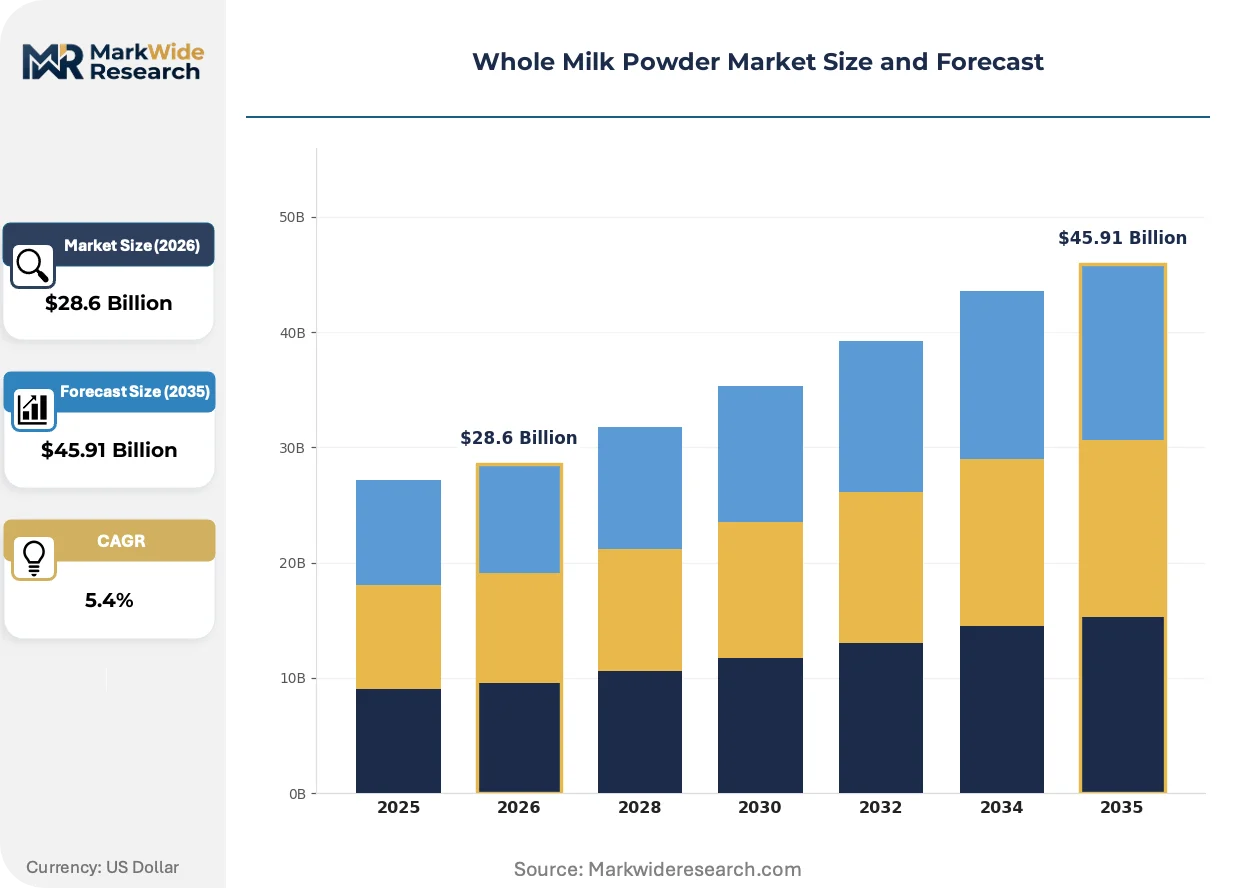
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Whole Milk Powder, Regular Whole Milk Powder, Fat-Reduced Whole Milk Powder, Organic Whole Milk Powder End Use: Dairy Products, Bakery Products, Confectioneries, Infant Formula Packaging Type: Plastic Bags, Cartons, Bulk Containers, Sachets Distribution Channel: Supermarkets, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | Lactalis Ingredients, Nestle SA, Fonterra Co-operative Group, Vinamilk, Westland Milk Products, Arla Foods amba, Dairy Farmers of America, Saputo, Amul (GCMMF), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole Milk Powder Market Strategic Shifts & Innovations
Processing technology convergence and regulatory chemistry mandates are reconfiguring how whole milk powder quality is verified, certified, and traded across import-dependent and self-sufficient dairy regions.
Membrane filtration pre-concentration is collapsing energy requirements for spray-drying operations by reducing water load prior to thermal dehydration. Mid-size European processors are retrofitting reverse osmosis and nanofiltration stages into existing lines, cutting natural gas consumption per ton of powder output and enabling compliance with EU Green Deal emissions benchmarks without full facility replacement.
REACH chemical standards are restricting acceptable cleaning agent formulations in European dairy powder facilities, forcing processors to validate alternative sanitizers that maintain microbiological limits without chlorinated compound residues. Infant formula ingredient suppliers face the strictest purity verification requirements, with German and Dutch processors investing in inline spectroscopic detection to document compliance for Chinese NMPA import audits.
Direct procurement contracting between dairy cooperatives and infant formula manufacturers is narrowing as large processors consolidate supply relationships. Southeast Asian formula brands now source predominantly through processor-direct channels rather than cooperative spot markets, compressing price discovery transparency and locking in volume commitments that favor established supplier-processor networks over emerging dairy regions.
Whole Milk Powder Market Segmentation
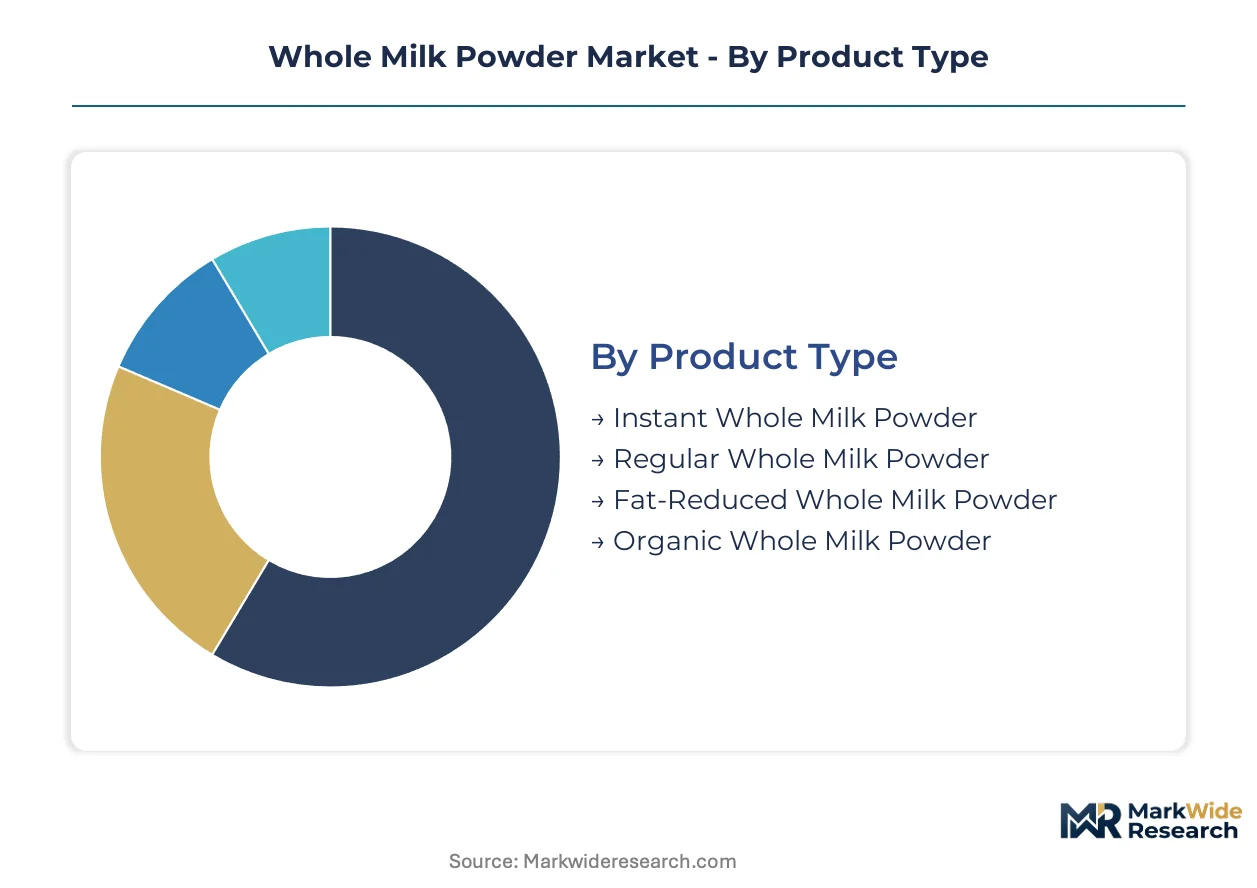
Whole milk powder segmentation reveals how processing technology, end-use specifications, and distribution economics partition commercial opportunity across distinct value tiers. Procurement patterns diverge sharply between commodity food manufacturing and premium infant nutrition applications.
Product Type:
Cost tier differentiation separates commodity-grade powders from premium instant and organic certifications that command manufacturing premiums.
- Instant Whole Milk Powder:Agglomerated particles with enhanced solubility through steam-leaching or re-wet agglomeration processes. Infant formula manufacturers across Vietnam and Indonesia concentrate procurement here as spray-drying automation improves particle uniformity for rapid reconstitution.
- Organic Whole Milk Powder:Sourced from grass-fed herds under certified organic protocols with documented feed and veterinary records. European clean-label procurement policies and North American retailer sustainability mandates are expanding margin pools for this grade.
- Regular Whole Milk Powder:Standard spray-dried product without agglomeration treatment serving price-sensitive food manufacturing and emergency nutrition programs.
- Fat-Reduced Whole Milk Powder:Partial fat removal through centrifugal separation prior to drying, targeting bakery and confectionery applications where lower fat content improves shelf stability.
Instant whole milk powder commands the established base. The steepest expansion runs through organic whole milk powder.
End Use:
Application requirements range from basic reconstitution properties to stringent microbiological limits that reshape supplier qualification criteria.
- Infant Formula:The most demanding specification tier requiring protein structure preservation, fat globule integrity, and documented absence of contaminants. China's NMPA and India's FSSAI enforce progressively stricter purity verification for imported base ingredients.
- Dairy Products:Recombined milk, yogurt, and cheese production in regions lacking fluid milk infrastructure. Southeast Asian processors leverage powder for consistent protein and fat standardization.
- Bakery Products:Bread, pastry, and biscuit manufacturing where powder provides water-binding and browning functionality without cold chain dependency.
- Confectioneries:Chocolate, caramel, and milk-based candy applications requiring specific particle size distribution for texture control.
Infant formula anchors premium value extraction. The fastest volume gains are concentrating in dairy products recombination.
Packaging Type:
Volume scale and handling economics determine packaging selection from single-serve sachets to bulk pneumatic discharge systems.
- Bulk Containers:Intermediate bulk containers and flexible intermediate bulk containers for industrial food manufacturing with pneumatic conveying systems. Large processors in New Zealand and Europe standardize on this format for ocean freight efficiency.
- Sachets:Single-serve 20-30 gram packets for foodservice and institutional feeding programs in tropical climates where humidity control prevents caking.
- Plastic Bags:Multi-layer laminated bags with nitrogen flushing for retail and small-scale institutional distribution.
- Cartons:Paperboard-based packaging with moisture barriers targeting premium retail positioning in European and North American markets.
Bulk containers dominate industrial procurement. Sachets are climbing fastest as foodservice penetration expands in humid tropical markets.
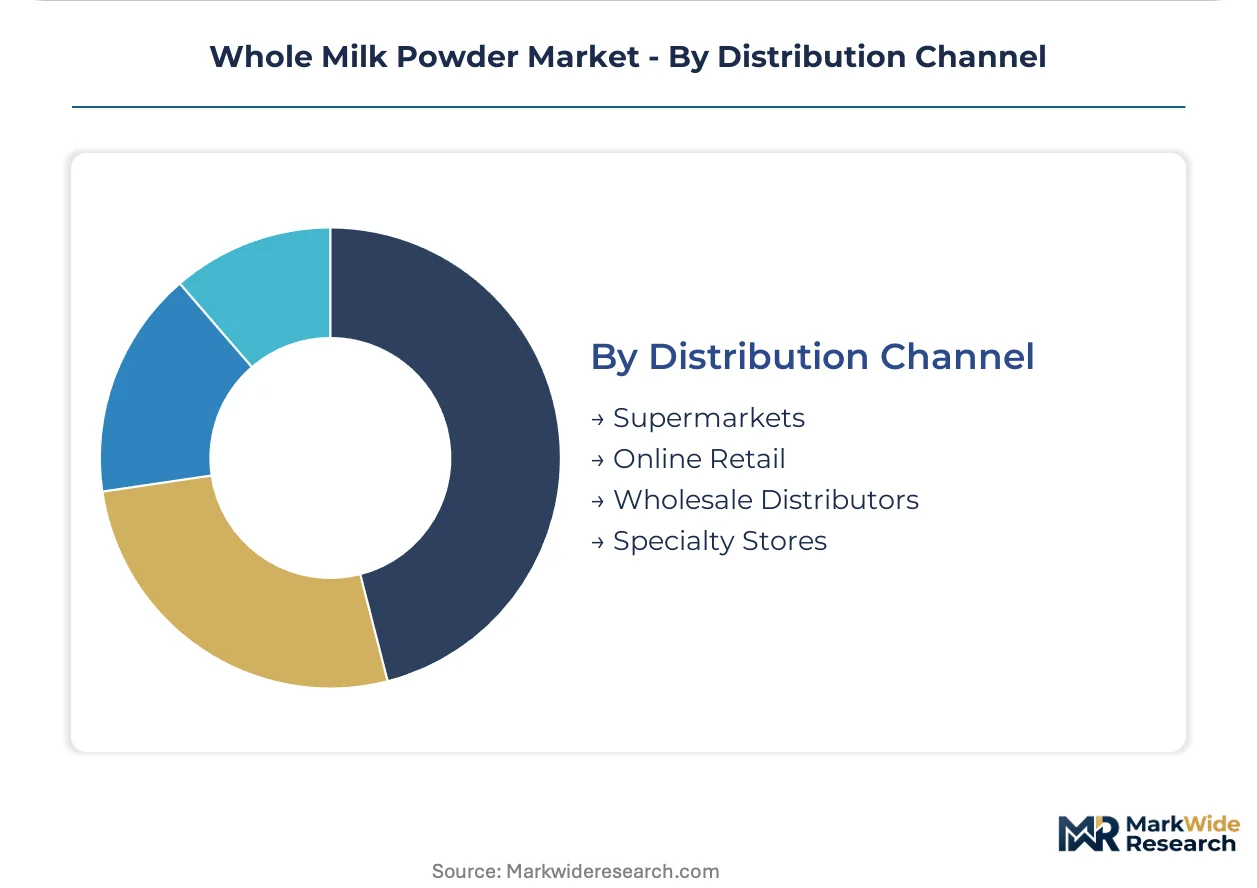
Distribution Channel:
Customer type and order scale fragment access pathways between established dairy broker networks and emerging direct procurement platforms.
- Wholesale Distributors:Traditional dairy ingredient traders maintaining regional inventory positions and credit relationships with mid-size food manufacturers. Fonterra and Arla lock in multi-year supply agreements through this channel.
- Online Retail:Food ingredient marketplaces and B2B platforms disintermediating broker networks, enabling mid-size processors to access institutional buyers without established trade relationships.
- Supermarkets:Retail grocery chains carrying consumer-packaged powder for household reconstitution in markets with intermittent cold chain reliability.
- Specialty Stores:Organic and health food retailers targeting clean-label consumers with certified organic and grass-fed positioning.
Wholesale distributors retain the volume base. Online retail is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European processing standards while Fonterra's New Zealand operations set grass-fed certification benchmarks for Asian import markets. Infant formula demand concentrates procurement relationships across distinct regulatory environments.
New Zealand
Fonterra Co-operative Group processes the majority of global grass-fed whole milk powder exports from Canterbury and Waikato dairy belts. The country's Ministry for Primary Industries enforces strict dairy export certification protocols aligned with Chinese NMPA import requirements. Spray-drying facilities in Christchurch and Edendale anchor premium powder production for Southeast Asian formula manufacturers.
China
Demographic policy shifts and per-capita dairy consumption expansion sustain base ingredient demand for domestic infant formula production. The NMPA escalates purity verification requirements for imported whole milk powder through documented contaminant testing and supplier qualification audits. Processing clusters in Heilongjiang and Inner Mongolia scale recombined milk production to reduce import dependency.
Vietnam
Vinamilk's domestic powder manufacturing expansion targets ASEAN export markets with reduced tariff exposure versus New Zealand-origin supply. The Ministry of Health enforces national food safety standards for dairy powder microbiological limits through provincial market surveillance. Ho Chi Minh City processing facilities concentrate instant whole milk powder output for regional infant formula manufacturers.
Germany
REACH chemical standards and EU F-Gas refrigerant mandates reshape cleaning agent specifications and spray-drying equipment replacement cycles across Bavarian and North Rhine-Westphalia dairy belts. The Federal Office of Consumer Protection and Food Safety coordinates with EFSA on dairy powder contaminant monitoring. Membrane filtration retrofits in Allgäu processing facilities cut natural gas consumption per ton of organic-certified powder output.
India
Amul's village-level collection network dominates organized dairy channel procurement for domestic powder production and limited export consignments. The FSSAI enforces progressively stricter microbiological limits on dairy powders entering retail and institutional channels through state-level food safety commissioners. Gujarat and Maharashtra processing clusters standardize spray-dried output for bakery and confectionery recombination applications.
Whole Milk Powder Market Key Industry Players
Farmer-owned cooperatives and publicly listed dairy conglomerates split the market into distinct governance structures with divergent capital allocation priorities. Consolidation pressure compresses mid-tier processor margins while scale advantages concentrate in vertically integrated sourcing networks. Strategic archetypes separate grass-fed premium specialists from commodity-scale recombination suppliers and emerging regional export platforms. Multi-year supply agreements and processing capacity expansion represent the dominant competitive moves reshaping procurement access.
Among cooperative-structured processors, Fonterra Co-operative Group and Arla Foods amba exemplify farmer-owned governance models that anchor premium grass-fed positioning in Asian import markets. Dairy Farmers of America represents the scale-driven consolidation archetype across North American supply relationships. Lactalis Ingredients and Nestle SA occupy positions within the diversified dairy conglomerate tier, leveraging cross-category procurement leverage and integrated brand distribution. Vinamilk anchors the emerging regional export platform archetype, scaling domestic Vietnamese production to capture ASEAN market share with reduced logistics cost exposure versus traditional Oceania supply routes.
| Leading Market Players |
|---|
| Lactalis Ingredients |
| Nestle SA |
| Fonterra Co-operative Group |
| Vinamilk |
| Westland Milk Products |
| Arla Foods amba |
| Dairy Farmers of America |
| Saputo |
| Amul (GCMMF) |
| Others |
Cost & Logistics Intelligence
Single-source dependency on New Zealand-origin grass-fed certification widens pricing tier spreads between premium-positioned infant formula grades and commodity recombination powders while compressing procurement alternatives for Asian manufacturers seeking consistent supply.
Pricing Analysis
The customization-premium spread separates instant whole milk powder with documented protein structure preservation from standard spray-dried grades lacking agglomeration treatment. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale. Cost compression in commodity recombination tiers is intensifying because natural gas input volatility destabilizes spray-drying economics. Institutional food manufacturers exhibit highest price sensitivity, while infant formula producers absorb premiums for microbiological compliance documentation.
Supply Chain Analysis
Export-control regimes through China's NMPA purity verification requirements and India's FSSAI microbiological limits constrain flow velocity for European and Oceania-origin supply. New Zealand, Germany, and Vietnam anchor global powder production capacity. Raw material flows draw from Canterbury dairy belts, Bavarian organic herds, and Mekong Delta collection networks. Single-source vulnerability concentrates in Fonterra's grass-fed sourcing dominance. Distribution runs through wholesale dairy broker networks locking in multi-year supply agreements with Southeast Asian formula manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized spray-drying engineering expertise is retiring faster than training pipelines replenish, creating a capability bottleneck that constrains facility expansion timelines across mid-size European and Asian processors.
For Market Incumbents: Insulate premium positioning by deepening backward integration into grass-fed herd certification and locking in exclusive multi-year supply agreements with Vietnamese and Indonesian formula manufacturers before Vinamilk scales regional export capacity. Anchor defensive moats through membrane filtration retrofit investments that cut energy intensity per ton of organic-certified output. For New Entrants and Emerging Players: Mid-size organic whole milk powder production in Eastern European dairy belts represents the most penetrable entry point, exploiting EU Green Deal equipment replacement subsidies and REACH compliance gaps among retiring processor cohorts. E-commerce food ingredient marketplaces offer direct channel access to institutional buyers without established broker relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processor-processor acquisition targets with captive organic certification and installed membrane filtration capacity. Long-term viability hinges on energy efficiency positioning rather than scale alone. Watch NMPA audit intensity escalation as the inflection signal for premium-grade margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Reverse osmosis pre-concentration cuts natural gas consumption per ton in EU F-Gas regulated facilities. |
| Organic Certification Investment | Documented grass-fed protocols unlock European clean-label procurement and North American retailer mandates. |
| Multi-Year Supply Agreement | Fonterra and Arla lock in Southeast Asian formula manufacturers, compressing spot market access. |
| Spray-Drying Automation Upgrade | Inline moisture sensing reduces protein denaturation rates for instant powder premium capture. |
| Regional Export Hub Establishment | Vinamilk's Vietnam scaling targets ASEAN markets with reduced tariff exposure versus Oceania routes. |
Research Approach
Operator-level perspectives from spray-drying facility engineers, infant formula procurement directors, dairy cooperative supply managers, and FSSAI state food safety commissioners anchored the qualitative base. Primary interview insights combined with secondary validation from EU dairy trade statistics, China customs import records, Fonterra annual disclosures, and EFSA contaminant monitoring reports. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Scenario-bracketing around EU F-Gas refrigerant transition timelines, NMPA audit intensity escalation, and Vietnam domestic production scaling anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product type, end-use application, packaging format, and regional production hub. CAGRs derived from installed capacity expansion schedules, demographic dairy consumption elasticity, and regulatory compliance cost pass-through assumptions. Energy price volatility and organic feed certification availability served as key forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, euro-yuan exchange rates, or ASEAN tariff schedules would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption curves. Material shifts in China's NMPA import purity requirements or Fonterra's grass-fed supply allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Milk Protein Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
North America A2 Milk Market
Dairy Products
US Cheese Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Condensed Milk Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
United States Dairy Market
Dairy Products
GCC Cheese Market
Dairy Products
Cream Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Natural Cheese Market