
 GCC Cheese Market | 2026-2036
GCC Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Cheese Market Intelligence
Multi-source dairy procurement is shifting toward vertically integrated supply chains across the GCC. Almarai Company Ltd sustains dominant manufacturing scale through captive milk sourcing and extensive cold-chain networks. FrieslandCampina leverages its European dairy heritage to anchor premium cheese positioning in UAE and Saudi retail channels. Arla Foods competes on cooperative-owned supply transparency, appealing to health-conscious Gulf consumers.
Cheese comprises coagulated milk proteins separated from whey, with fat content, moisture levels, and aging duration defining functional properties for melting, spreading, or table consumption. Cheddar and Mozzarella occupy the largest volume share in GCC food service due to pizza and burger menu ubiquity, while Cream Cheese captures expanding retail demand driven by home baking trends and breakfast category growth. Fat Content segmentation shows Full Cream variants leading value pools in traditional channels, though Reduced Fat alternatives are gaining shelf space in Saudi and UAE supermarkets responding to dietary guidance from national health ministries.
Gulf Standardization Organization food safety protocols, Saudi Food and Drug Authority import requirements, and UAE Ministry of Climate Change and Environment labeling rules collectively shape product registration timelines and formulation compliance costs. SFDA enforcement of stricter microbiological limits is forcing reformulation investments among imported cheese brands. Stakeholders must monitor evolving halal certification reciprocity agreements between GCC states and non-member suppliers to anticipate border clearance advantages.
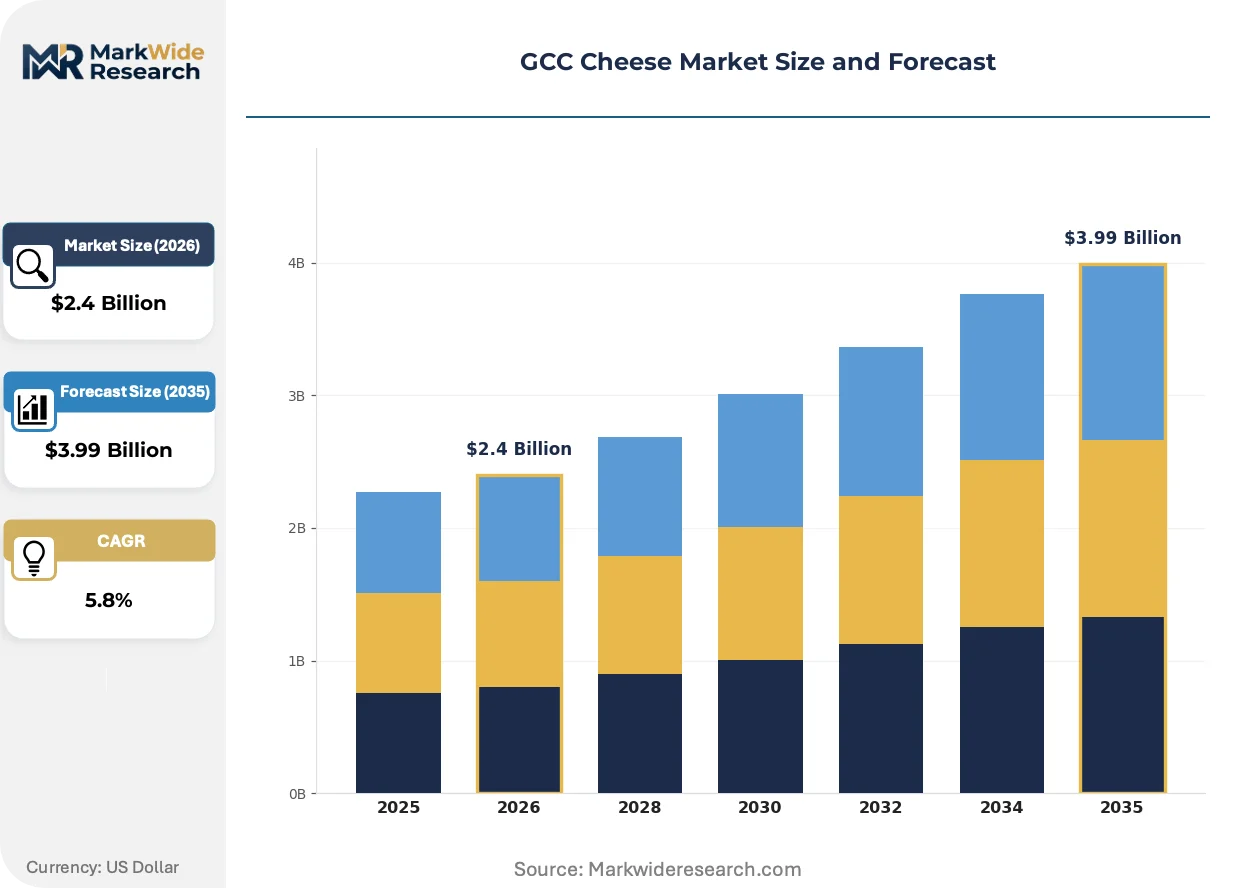
Market Dynamics
Gulf Standardization Organization harmonization of food safety protocols is compressing import timelines and forcing local dairy capacity expansion across Saudi Arabia, the UAE, and Kuwait.
Growth Catalysts
- SFDA Microbiological Standards:Stricter enforcement of Saudi Food and Drug Authority limits is accelerating domestic cheese manufacturing investments to bypass extended border clearance protocols.
- Foodservice Menu Diversification:Saudi and UAE restaurant chains are expanding cheese procurement for fusion cuisine and premium burger offerings, pulling volume through cold-chain distribution networks.
- Home Baking Category Expansion:Cream cheese demand is surging in UAE retail channels as consumers replicate Western-style desserts and breakfast items.
Market Restraints
- Fresh Milk Supply Concentration:GCC cheese production depends on captive dairy herds in Saudi Arabia's Al Kharj region, creating geographic vulnerability to heat stress and feed cost volatility.
- Import Dependency for Specialty Varieties:Aged European cheeses require extended Gulf Standardization Organization registration timelines, limiting premium product availability in Dubai and Riyadh.
- Refrigerated Logistics Cost Structure:Cold-chain infrastructure gaps in Oman and Bahrain inflate landed costs for temperature-sensitive fresh cheese categories.
Strategic Opportunities
- Kuwait and Qatar Underpenetration:Premium cheese distribution remains concentrated in Saudi Arabia and the UAE, creating whitespace for cold-chain operators to establish hub-and-spoke networks in emerging foodservice markets.
- Halal Certification Reciprocity:Evolving mutual recognition agreements between GCC states and Southeast Asian suppliers are streamlining border clearance for certified imports.
- Functional Cheese Positioning:Protein-fortified and probiotic variants are capturing shelf space in Saudi supermarkets responding to Ministry of Health dietary guidance.
Industry Challenges
- Refrigerated Warehouse Capacity Scarcity:Dubai and Jeddah cold storage facilities face utilization pressure from competing pharmaceutical and fresh produce demand, compressing cheese inventory windows.
- Multi-Jurisdiction Label Compliance:Divergent UAE Ministry of Climate Change and Environment and SFDA nutritional disclosure rules force dual packaging runs for cross-border retail distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Cheese Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Feta, Cream Cheese End User: Retailers, Restaurants, Food Service, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Fat Content: Low Fat, Full Cream, Reduced Fat, Creamy |
| Companies Covered | Savola Foods, FrieslandCampina, Almarai Company Ltd, Saputo Inc, Groupe Lactalis, National Agricultural Development Company, Arla Foods, The Kraft Heinz Company, Al Jouf Dairy Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Cheese Market Strategic Shifts & Innovations
Technology adoption and regulatory compression are reshaping how cheese manufacturers, distributors, and foodservice operators configure supply chains and product portfolios across the GCC.
Extended-shelf-life processing technologies are electrifying fresh cheese logistics by enabling ambient-temperature distribution windows. Saudi dairy processors are adopting membrane filtration and advanced pasteurization systems to reduce cold-chain dependency for cream cheese and labneh variants. This capability compression is opening secondary city distribution in the Kingdom without refrigerated transport infrastructure.
Gulf Standardization Organization food safety protocol harmonization is mandating unified microbiological testing standards across member states. Imported cheese brands now face consolidated compliance documentation requirements rather than jurisdiction-specific filings. European and New Zealand suppliers are restructuring GCC export operations around single-laboratory certification to satisfy Saudi Food and Drug Authority and UAE Ministry of Climate Change and Environment joint acceptance criteria.
Foodservice procurement consolidation is compressing supplier relationships as Saudi and UAE restaurant groups centralize cheese purchasing through contracted dairy distributors. Independent pizzeria and burger operators in Riyadh and Dubai are surrendering direct import relationships in favor of integrated supply agreements with Al Kharj-based processors. This channel consolidation is most visible in Dubai's hospitality sector, where hotel groups now specify single-source cheese supply across property portfolios.
GCC Cheese Market Segmentation
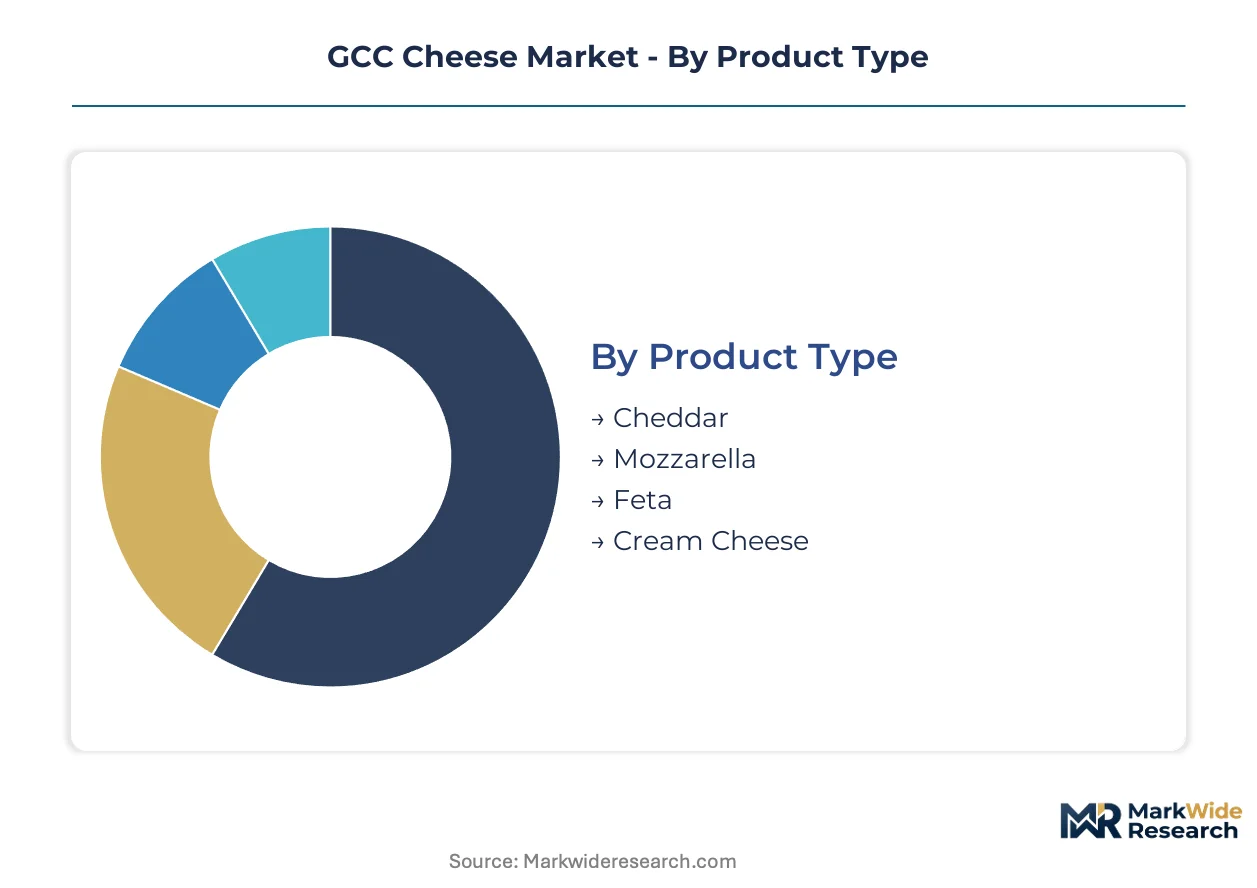
Cheese procurement patterns across Saudi Arabia and the UAE diverge sharply by channel and application, requiring manufacturers to configure distinct formulation, packaging, and logistics specifications for each segment cluster.
Product Type:
Supply concentration in Al Kharj-based processing facilities favors high-volume varieties with standardized production protocols.
- Cheddar:Firm, aged cow's milk cheese with controlled moisture and fat content enabling consistent melting performance. Riyadh-Jeddah corridor quick-service restaurants specify Cheddar for burger and sandwich applications, with procurement volume tied to chain expansion timelines.
- Mozzarella:Pasta filata-style cheese with high moisture and stretch characteristics essential for pizza preparation. Dubai's foodservice hub concentrates demand from Italian and fusion concepts, where pizzeria operators prioritize shredability and browning control.
- Feta:Brined curd cheese with crumbly texture and tangy flavor profile. Mediterranean restaurant concepts in Abu Dhabi and Doha drive import-heavy procurement.
- Cream Cheese:Fresh, unripened soft cheese with high fat content and spreadable consistency. UAE retail channels show expanding home baking applications.
Today's leader: Cheddar. Tomorrow's challenger: Cream Cheese.
End User:
Cost tier differentiation separates commodity volume buyers from premium specification customers.
- Retailers:Supermarket chains and hypermarkets requiring extended shelf-life packaging, bilingual labeling compliance, and promotional slotting fees. Saudi Arabia's Panda and UAE's Lulu anchor procurement with private-label development programs.
- Restaurants:Full-service dining concepts specifying cheese for table service and plated applications. Dubai's hotel restaurant sector demands consistent portion control and origin documentation.
- Food Service:Institutional caterers, airline suppliers, and contract food operators. Volume concentrates in Riyadh corporate catering and UAE airline catering facilities.
- Households:Direct consumer purchases through retail and e-commerce channels. Saudi Arabia's young demographic drives snacking and breakfast category expansion.
Food Service commands current volume. Households show steepest expansion trajectory.
Distribution Channel:
Geographic reach constraints shape channel viability for fresh versus aged cheese categories.
- Online:E-commerce platforms and grocery delivery applications. UAE's Noon and Saudi Arabia's Talabat expand cold-chain delivery coverage for premium varieties.
- Supermarkets:Modern trade retail with dedicated dairy refrigeration. Riyadh and Jeddah hypermarkets allocate expanding shelf space to imported specialty cheeses.
- Specialty Stores:Gourmet food retailers and delicatessens. Dubai's Mall of the Emirates and Riyadh's Boulevard clusters concentrate high-margin positioning.
- Wholesale:Cash-and-carry and foodservice distributors. Al Kharj-based processors dominate B2B supply to restaurant groups.
Supermarkets retain dominance. Online channels gain share fastest.
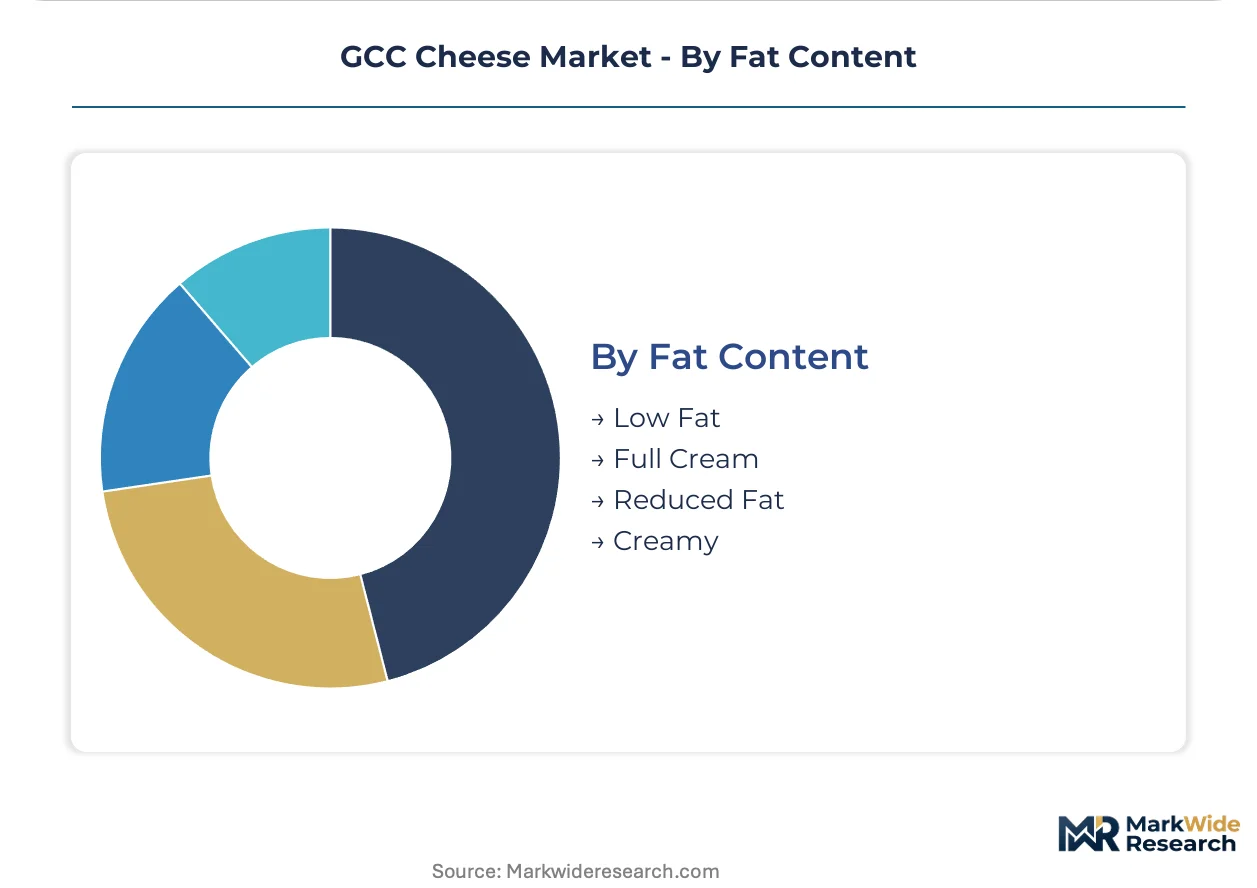
Fat Content:
Application requirements and health positioning create distinct margin structures across fat tiers.
- Low Fat:Reduced fat content formulations targeting calorie-conscious consumers. Saudi Ministry of Health dietary guidance expands retail placement.
- Full Cream:Standard fat content delivering maximum flavor and texture performance. Traditional channels and foodservice specifications favor this tier.
- Reduced Fat:Intermediate fat positioning balancing taste and health claims. UAE supermarkets allocate promotional support.
- Creamy:High fat content variants for indulgence positioning and specific culinary applications. Dessert and baking segments drive demand.
Full Cream maintains volume leadership. Reduced Fat climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cheese manufacturing capacity across Gulf Cooperation Council states as compliance cost differentials widen between import-dependent and production-capable jurisdictions.
Saudi Arabia
Domestic dairy herds in the Al Kharj region supply captive milk for cheddar and mozzarella production serving Riyadh-Jeddah corridor quick-service restaurants. SFDA microbiological standards enforcement is accelerating local manufacturing investments to bypass extended border clearance protocols. The Kingdom's foodservice procurement consolidation is compressing supplier relationships around vertically integrated processors.
United Arab Emirates
Dubai's hospitality sector drives premium cheese demand from hotel restaurant groups specifying single-source supply across property portfolios. UAE Ministry of Climate Change and Environment labeling rules shape product registration timelines alongside GSO harmonization efforts. The emirate's cold-chain infrastructure expansion supports distribution of temperature-sensitive fresh cheese categories to secondary cities.
Kuwait
Premium cheese distribution remains underpenetrated relative to Saudi Arabia and the UAE, creating whitespace for cold-chain operators establishing hub-and-spoke networks. The country's national food safety authority aligns with GSO protocols while maintaining jurisdiction-specific import documentation requirements. Kuwait City's emerging foodservice market is pulling volume through contracted dairy distributors rather than direct import relationships.
Qatar
Airline catering facilities and institutional food operators concentrate demand for standardized cheese portions with consistent origin documentation. The Qatar General Organization for Standard and Metrology participates in GSO harmonization while enforcing supplementary halal certification requirements. Doha's Mediterranean restaurant concepts drive import-heavy procurement of brined and aged varieties.
Oman
Cold-chain infrastructure gaps inflate landed costs for temperature-sensitive fresh cheese categories, favoring ambient-stable processed alternatives in retail channels. The country's national standards body implements GSO microbiological testing standards with extended compliance timelines for smaller importers. Muscat's supermarket chains allocate limited shelf space to imported specialty cheeses relative to regional hubs.
GCC Cheese Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue functional positioning and halal-certified specialty lines. Market structure consolidates around three to four vertically integrated dairy groups controlling captive milk supply and cold-chain distribution networks. Strategic archetypes include: scale-driven commodity processors, European heritage premium importers, and cooperative-owned transparency specialists. Dominant competitive moves encompass backward integration into dairy herd operations and portfolio diversification toward protein-fortified variants.
Within the scale-driven tier, Almarai Company Ltd and National Agricultural Development Company anchor domestic manufacturing capacity through Al Kharj-based processing infrastructure. FrieslandCampina represents the European heritage importer archetype, leveraging cooperative structure to position premium variants in UAE and Saudi retail channels. Arla Foods occupies the transparency-specialist position, appealing to health-conscious Gulf consumers through cooperative-owned supply chain disclosure.
| Leading Market Players |
|---|
| Savola Foods |
| FrieslandCampina |
| Almarai Company Ltd |
| Saputo Inc |
| Groupe Lactalis |
| National Agricultural Development Company |
| Arla Foods |
| The Kraft Heinz Company |
| Al Jouf Dairy Company |
| Others |
Cost & Logistics Intelligence
Extended-shelf-life processing adoption across Saudi Arabia's Al Kharj dairy cluster compresses cold-chain expenditure while concentrating procurement leverage among processors with membrane filtration capabilities. This technological shift simultaneously reduces per-unit logistics costs and reinforces pricing power for vertically integrated manufacturers serving Riyadh-Jeddah corridor quick-service restaurants.
Pricing Analysis
Distributor margin layers in GCC cheese supply separate captive-processor direct contracts from import-dependent wholesale channels. Three-tier pricing structure across premium European heritage, standard domestic cheddar-mozzarella, and economy processed variants reflects fat content grading and halal certification tier. Pricing pressure stems from refrigerated warehouse scarcity in Dubai and Jeddah compressing inventory windows and forcing expedited logistics premiums. Foodservice operators show highest price sensitivity due to menu cost targets, while hotel groups demonstrate lowest sensitivity given single-source supply mandates.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised cheese shipments remain underdeveloped across Oman and Bahrain, forcing write-off absorption by importers. Supply concentrates in Saudi Arabia's Al Kharj region, the Netherlands, and New Zealand, with fresh milk sourcing anchored in captive desert dairy herds. Raw material dependencies include alfalfa feed imports, packaging films, and starter cultures. Single-source vulnerability runs through Al Kharj milk supply exposed to heat stress and feed cost volatility. Distribution runs through cold-chain hub-and-spoke networks radiating from Dubai and Jeddah to secondary GCC cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC cheese demand functions as a regulatory compounder where Gulf Standardization Organization microbiological harmonization accelerates domestic manufacturing investment to bypass extended import clearance timelines.
For Market Incumbents: Deploy backward integration into captive dairy herd expansion to secure milk supply against feed cost volatility and heat stress exposure. Consolidate channel control through exclusive supply agreements with Saudi and UAE restaurant groups centralizing procurement. Counter emerging entrant pressure from Southeast Asian halal-certified suppliers by accelerating GSO joint acceptance certification for single-laboratory testing. For New Entrants and Emerging Players: Begin with Kuwait and Qatar foodservice whitespace where cold-chain infrastructure gaps have suppressed premium cheese availability relative to Saudi Arabia and UAE penetration levels. Target Mediterranean restaurant concepts in Doha and Abu Dhabi demanding import-heavy feta and aged variety procurement underserved by Al Kharj-based processors. Pursue contracted distributor relationships rather than direct import positioning to bypass established wholesale relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale dairy processors lacking membrane filtration capabilities but holding GSO-compliant production infrastructure ripe for technology retrofit. Five-to-ten-year viability hinges on regulatory arbitrage closure as import compliance costs converge across GCC member states. Monitor halal certification reciprocity agreement expansion between GCC states and Southeast Asian suppliers as inflection signal for import-dependent business model compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Hub-and-spoke network buildout in Kuwait and Qatar unlocks premium cheese distribution to underserved foodservice markets. |
| Membrane Filtration Technology Adoption | Extended-shelf-life processing reduces refrigerated transport dependency for cream cheese variants in Saudi secondary cities. |
| Halal Certification Reciprocity Pursuit | Mutual recognition agreements with Southeast Asian suppliers streamline border clearance and compress registration timelines. |
| Functional Cheese Portfolio Diversification | Protein-fortified and probiotic variants capture shelf space responding to Saudi Ministry of Health dietary guidance. |
| Foodservice Procurement Consolidation | Exclusive supply agreements with Riyadh and Dubai restaurant groups lock out competing distributors through volume commitments. |
Research Approach
Direct dialogue with dairy processing executives, cold-chain logistics operators, foodservice procurement directors, and retail category managers grounded primary intelligence. Secondary validation drew from Gulf Standardization Organization protocol documentation, Saudi Food and Drug Authority regulatory filings, UAE Ministry of Climate Change and Environment labeling guidelines, customs trade data, and industry association dairy production statistics. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Bottom-up segmentation analysis modeled product type, fat content tier, end-user channel, and distribution format across the projection horizon. Cheddar and mozzarella volume estimates derived from quick-service restaurant chain expansion timelines and pizza concept penetration rates. Cream cheese trajectory incorporated home baking category growth indicators and breakfast consumption pattern shifts. CAGR derivation synthesized historical production data with regulatory milestone impact assessment.
Several conditions sit outside the modeled scope, including unforeseen Gulf Standardization Organization protocol amendments, extreme climate events disrupting Al Kharj dairy operations, and abrupt halal certification reciprocity reversals. Forecasts reflect assumptions regarding cold-chain infrastructure buildout pacing and foodservice procurement consolidation continuity. Practitioners should monitor SFDA enforcement intensity and refrigerated warehouse utilization rates in Dubai and Jeddah for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Drinkable Yogurt Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Low Fat Butter Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Whipping Cream Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Cheese Shreds Market
Dairy Products
Green Tea Butter Market
Dairy Products
Sweet Whey Market
Dairy Products
Halloumi Cheese Market