
 Ready-To-Whip Toppings Market | 2026-2036
Ready-To-Whip Toppings Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Whip Toppings Market Analytics
European dairy processing capacity is restructuring as plant-based ingredient streams gain share in ready-to-whip production. Rich's Products Corporation leverages its frozen dessert infrastructure to anchor North American foodservice supply. ADM competes through emulsifier and oilseed processing integration that sustains cost advantages across whipped and dairy-free formats. Palsgaard A/S specializes in plant-based stabilizer systems that extend functionality into clean-label topping applications.
Ready-to-whip toppings are aerated, emulsified preparations—typically containing vegetable fats, sugars, stabilizers, and propellants—designed to maintain volumetric structure and mouthfeel under frozen or refrigerated distribution. Whipped cream and dairy-free toppings occupy the largest volume positions, though chocolate and flavored variants capture disproportionate margin pools in premium café and bakery channels. The HoReCa distribution channel concentrates procurement scale, while online retail segments grow fastest as direct-to-consumer formats and subscription bakery kits expand refrigerated last-mile capabilities.
FDA standards govern GRAS status for propellants and emulsifiers in U.S.-manufactured toppings, while EFSA and REACH frameworks in Europe restrict certain hydrocolloid and aerosol chemistries. The EU F-Gas Regulation phases down HFC propellant use, forcing reformulation toward mechanical whipping or compressed gas alternatives. Stakeholders must monitor regulatory divergence between North American and European propellant regimes when planning cross-border product platforms and capital allocation for manufacturing assets.
Market Dynamics
Propellant chemistry restrictions under the EU F-Gas Regulation are forcing wholesale reformulation of aerosol-based ready-to-whip toppings, compressing margins for manufacturers reliant on HFC-driven distribution while creating first-mover advantages for mechanical whipping systems.
Growth Catalysts
- HoReCa dessert menu upgrades:Bakery chains and quick-service restaurants in Germany, the United States, and Japan are expanding flavored and dairy-free topping SKUs to capture premium beverage and pastry margins.
- REACH-compliant emulsifier innovation:ECHA restrictions on certain hydrocolloid chemistries are accelerating adoption of plant-based stabilizer systems that extend clean-label functionality.
- Refrigerated last-mile infrastructure:Direct-to-consumer subscription bakery kits and online retail channels are creating new volume pools through cold-chain logistics investments.
Market Restraints
- Vegetable fat price volatility:Palm and coconut oil input costs fluctuate with Southeast Asian weather patterns and biofuel policy shifts, compressing formulation economics.
- Propellant supply concentration:HFC alternatives and compressed gas systems rely on limited European and North American specialty chemical suppliers, creating bottleneck risk.
- Technical shelf-life trade-offs:Mechanical whipping systems sacrifice 15-30% ambient stability versus aerosol formats, constraining foodservice inventory flexibility.
Strategic Opportunities
- Clean-label certification premiums:USDA Organic and EU organic seal adoption allows pricing stratification against conventional vegetable-fat toppings in premium café channels.
- Chocolate and flavor-variant white space:Premium bakery and specialty coffee operators under-index in flavored topping attachment rates versus vanilla and dairy-free bases.
- Compressed gas propellant convergence:Nitrous oxide and carbon dioxide blending technologies are opening reformulation pathways for manufacturers seeking F-Gas compliance without mechanical system capex.
Industry Challenges
- Aerosol formulation chemistry expertise:The transition from HFC propellants demands rare combinations of emulsion science and gas-liquid equilibrium engineering that outstrip current talent pools.
- Cross-border regulatory divergence:FDA GRAS determinations for alternative propellants lag EFSA and REACH timelines, complicating unified product platform development for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Whip Toppings Market |
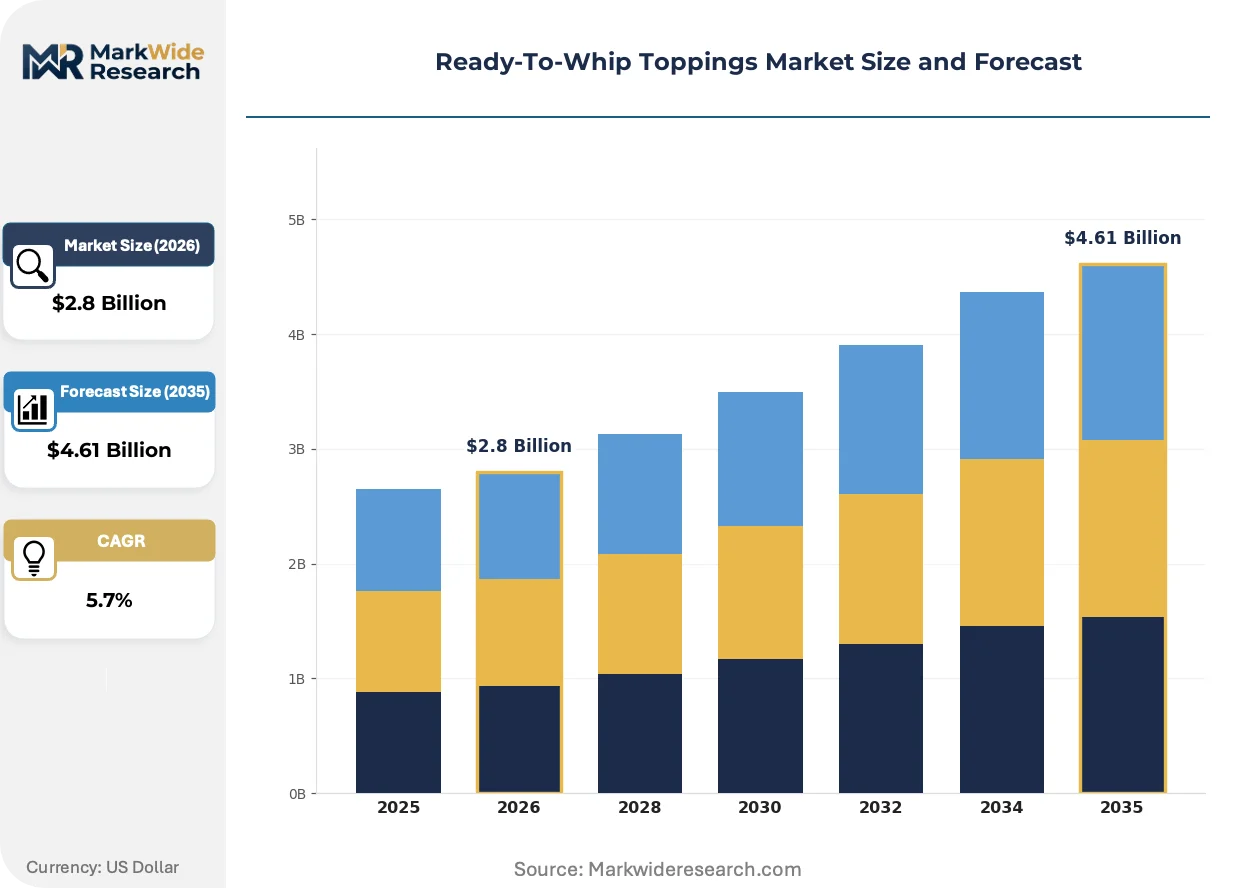
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipped Cream, Dairy-Free Toppings, Chocolate Toppings, Flavored Toppings Application: Desserts, Beverages, Baking, Ice Cream Distribution Channel: Supermarkets, Online Retail, Convenience Stores, HoReCa Customer Type: Individual Consumers, Restaurants, Cafés, Catering Services |
| Companies Covered | Rich's Products Corporation, Peak Food LLC, ADM, Barry Callebaut, Cargill, BASF SE, Palsgaard A/S, Ashland, Zentis GmbH and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Whip Toppings Market Evolving Landscape
Formulation science and distribution technology are converging to reshape how aerated toppings achieve structural stability, with regulatory pressure on propellant chemistry acting as the dominant forcing function across all innovation vectors.
Mechanical whipping systems using nitrogen-injection technology are modularizing production lines previously dedicated to aerosol filling. Foodservice operators in Germany and Japan are retrofitting dessert stations with countertop dispensing equipment that eliminates propellant dependency entirely. This hardware shift is compressing demand for traditional aerosol can manufacturing while expanding recurring revenue streams for equipment and gas supply contracts.
The EU F-Gas Regulation's phasedown schedule is accelerating HFC propellant replacement across all aerosol food categories. Manufacturers face compressed reformulation timelines as 2024-2027 reduction targets tighten, with EFSA novel food consultations creating additional approval bottlenecks for alternative chemistries. Dairy-free topping segments are responding fastest due to their higher margin tolerance for ingredient cost increases.
Direct procurement relationships between bakery chains and topping manufacturers are displacing traditional distributor intermediaries in the United States and Germany. Large foodservice operators are negotiating volume commitments directly with Rich's Products Corporation and ADM for customized flavor and fat-profile specifications. This channel compression is most visible in quick-service restaurant dessert programs where menu standardization across hundreds of locations justifies dedicated supply contracts.
Ready-To-Whip Toppings Market Segmentation
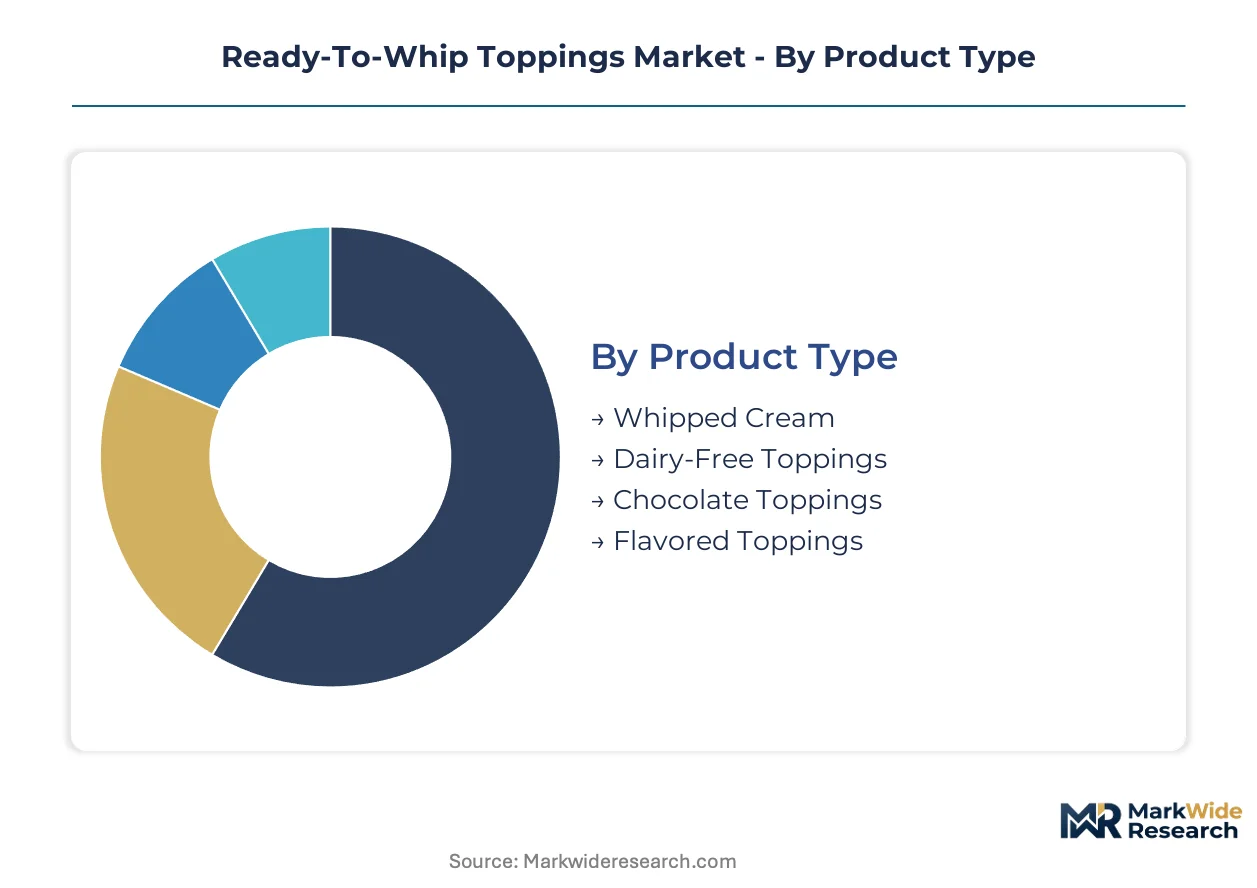
Ready-to-whip toppings fragment across four structural dimensions that determine formulation priorities, cold-chain requirements, and margin capture. Product type dictates fat chemistry and propellant selection. Application governs aeration density and freeze-thaw stability. Distribution channel shapes packaging format and shelf-life engineering. Customer type determines volume scale and customization tolerance.
Product Type:
Supply concentration in vegetable fat processing and propellant systems creates divergent margin structures across formulation platforms.
- Whipped Cream:Dairy-fat emulsions stabilized with hydrocolloids and delivered via aerosol or mechanical systems. Demand concentrates in German and United States bakery chains where traditional dessert profiles dominate procurement specifications, though HFC propellant restrictions under EU F-Gas Regulation compress margin flexibility for aerosol formats.
- Dairy-Free Toppings:Coconut, palm, or sunflower oil bases with tailored melting curves for vegan and lactose-intolerant segments. Premium café channels in Japan and Germany absorb reformulation cost premiums for clean-label stabilizer systems, creating the steepest expansion trajectory as plant-based ingredient streams scale.
- Chocolate Toppings:Cocoa-fat emulsions requiring precise tempering compatibility with dessert applications.
- Flavored Toppings:Vanilla, caramel, and fruit-infused variants targeting beverage attachment rates in quick-service restaurants.
Today's leader: Whipped Cream. Tomorrow's challenger: Dairy-Free Toppings.
Application:
End-use thermal stress and aeration requirements segment the market by functional performance tier rather than commodity volume.
- Desserts:Pastry and cake applications demand structural stability across freeze-thaw cycles and refrigerated display conditions. United States foodservice operators specify high-overrun formulations for visual volume in bakery case presentations, driving consolidation around mechanical whipping systems that eliminate propellant dependency.
- Beverages:Hot and cold drink toppings require rapid dissolution and controlled melt rates. Japanese specialty coffee chains prioritize flavored variants with precise sweetness modulation, expanding fastest as beverage menu complexity deepens attachment rate opportunities.
- Baking:Ingredient-grade toppings integrated into batters and frostings before thermal processing.
- Ice Cream:Frozen dessert inclusions and sundae applications with extended stability at sub-zero temperatures.
Desserts command current volume. Beverages are climbing the fastest.
Distribution Channel:
Last-mile temperature control and packaging format requirements create distinct competitive moats across channel archetypes.
- HoReCa:Foodservice direct procurement with dedicated supply contracts and customized specifications. German and United States bakery chains negotiate volume commitments directly with manufacturers for fat-profile and flavor customization, consolidating procurement scale away from distributor intermediaries.
- Online Retail:Direct-to-consumer subscription formats and specialty bakery kits requiring refrigerated last-mile infrastructure. Cold-chain logistics investments in Japan and Germany are expanding addressable geography for premium and organic variants, gaining share fastest as digital grocery penetration deepens.
- Supermarkets:Mass retail with standardized SKUs and ambient or refrigerated shelf placement.
- Convenience Stores:Impulse-oriented single-serve formats with limited cold storage capacity.
HoReCa holds current dominance. Online Retail is expanding most quickly.
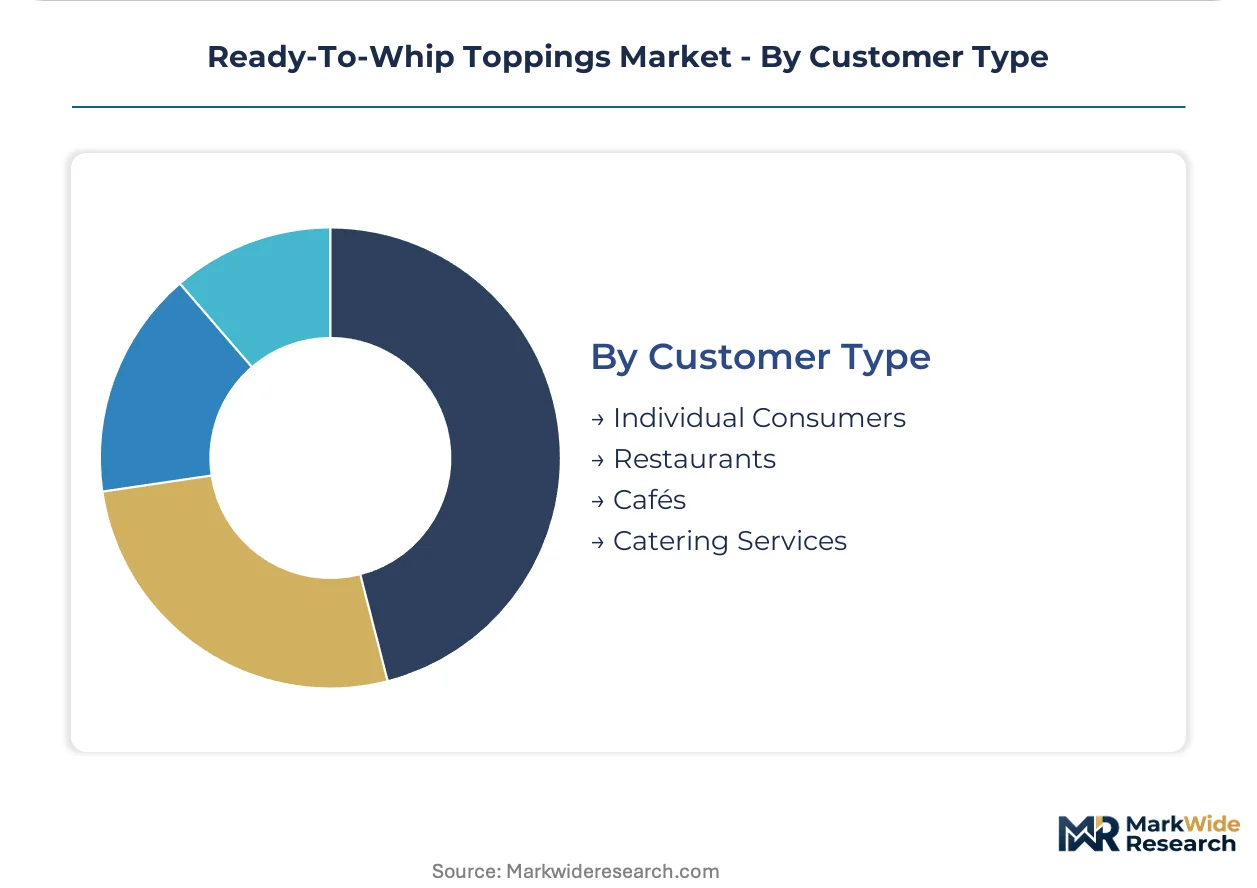
Customer Type:
Volume scale and technical specification tolerance segment procurement relationships across buyer archetypes.
- Restaurants:Quick-service and casual dining operators with standardized menu specifications across location networks. United States chains demand consistent overrun and flavor profiles at multi-ton volumes, justifying captive formulation development and direct manufacturer relationships.
- Cafés:Specialty coffee and premium bakery operators with high attachment rate sensitivity and customization appetite. German independent cafés drive demand for organic-certified and flavored variants, expanding fastest as beverage premiumization accelerates topping experimentation.
- Individual Consumers:Household purchasing through retail and online channels with convenience and price sensitivity.
- Catering Services:Event and institutional foodservice with batch-scale requirements and transport stability needs.
Restaurants anchor procurement scale. Cafés are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between EU F-Gas compliance costs and North American GRAS flexibility is redirecting capital toward mechanical whipping system deployments in lower-compliance-cost jurisdictions.
United States
Quick-service restaurant chains in the Southeast and Midwest are retrofitting dessert stations with nitrogen-injection equipment to bypass propellant chemistry constraints entirely. FDA GRAS determinations for compressed gas alternatives lag European timelines, creating temporary formulation flexibility for domestic manufacturers. Chicago and Dallas foodservice clusters concentrate procurement scale for customized fat-profile specifications.
Germany
Bakery chains in Bavaria and North Rhine-Westphalia are absorbing premium pricing for REACH-compliant emulsifier systems to maintain clean-label positioning. The EU F-Gas Regulation's 2024-2027 phasedown targets are accelerating HFC propellant replacement faster than neighboring markets. Hamburg's refrigerated logistics hub is expanding cold-chain capacity for direct-to-consumer subscription formats.
Japan
Specialty coffee operators in Tokyo and Osaka are driving flavored topping attachment rates with precise sweetness modulation requirements. METI guidance on sustainable packaging is pressuring aerosol format reductions in favor of mechanical dispensing. The Kansai region's dairy processing infrastructure is reconfiguring for plant-based ingredient streams.
United Kingdom
Independent café networks in London and the Southeast are demanding organic-certified variants at volume premiums that justify dedicated supply contracts. Post-Brexit divergence from EU F-Gas timelines creates transitional uncertainty for cross-border product platforms. Manchester's food manufacturing corridor is attracting mechanical whipping equipment investments.
Canada
Health Canada's PMRA consultations on aerosol propellant alternatives are proceeding in parallel with EPA frameworks, preserving North American regulatory alignment. Ontario's dairy processing sector is piloting dairy-free topping production for export to U.S. foodservice operators. Toronto's HoReCa procurement networks are consolidating direct manufacturer relationships.
Ready-To-Whip Toppings Market Competitive Landscape
North American producers anchor one tier with frozen dessert infrastructure and foodservice scale; European specialists hold formulation chemistry advantages under REACH and F-Gas regulatory pressure. The vendor base separates into three strategic archetypes: integrated agribusiness conglomerates with oilseed and emulsifier assets, regional dairy processors with frozen distribution networks, and specialty ingredient houses with plant-based stabilizer expertise. Capacity expansion and direct procurement contract negotiations constitute the dominant competitive moves.
Within the integrated agribusiness tier, ADM and Cargill exemplify upstream control over vegetable fat and emulsifier supply chains that sustains cost positioning across both dairy and dairy-free formats. Rich's Products Corporation occupies a position as a North American frozen dessert infrastructure anchor with foodservice direct procurement relationships. Palsgaard A/S represents the European specialty ingredient archetype with plant-based stabilizer systems engineered for clean-label compliance.
| Leading Market Players |
|---|
| Rich's Products Corporation |
| Peak Food LLC |
| ADM |
| Barry Callebaut |
| Cargill |
| BASF SE |
| Palsgaard A/S |
| Ashland |
| Zentis GmbH and Co. KG |
| Others |
Value Network & Pricing Analysis
Vegetable fat input costs originating from Southeast Asian palm and coconut oil processing flow through formulation economics into three-tier pricing structures across premium, standard, and economy levels, with REACH-compliant emulsifier premiums capturing margin in German bakery chains while compressed gas propellant investments pressure mid-tier manufacturer returns.
Pricing Analysis
Distributor margin compression in HoReCa channels feeds into direct-to-manufacturer contract negotiations that bypass traditional intermediaries. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—USDA Organic and EU organic seals command 15-25% uplifts in Japanese specialty coffee channels—while cost compression in aerosol formats intensifies because HFC propellant replacement investments outstrip near-term price recovery. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu specifications across location networks, whereas premium café operators absorb reformulation premiums for clean-label positioning.
Supply Chain Analysis
Specialized emulsion chemist availability in Hamburg, Chicago, and Osaka manufacturing corridors constrains production line expansion for mechanical whipping system deployment. Supply concentrates in Germany, the United States, and Japan for finished topping production, with raw material dependencies on Malaysian palm oil fractions, Indonesian coconut derivatives, and North American nitrous oxide propellant supply. Single-source vulnerability in European compressed gas propellant alternatives creates bottleneck risk as EU F-Gas Regulation phasedown accelerates. Distribution runs through direct procurement relationships between bakery chains and manufacturers, displacing traditional foodservice distributor intermediaries in volume-intensive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in mechanical whipping equipment recurring revenue streams and clean-label certification premiums, with EU F-Gas Regulation compliance costs filtering price-tolerant buyers toward reformulation-ready suppliers.
For Market Incumbents: Lock in direct procurement relationships with United States quick-service restaurant chains before channel compression completes, and anchor German bakery chain supply through REACH-compliant emulsifier certification investments that emerging competitors cannot replicate rapidly. Mechanical whipping system deployment in Japan and Germany creates captive equipment-and-gas supply contracts that defend against aerosol-format substitution threats. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for compressed gas propellant blending expertise that incumbent aerosol manufacturers lack. Target online retail subscription formats in Japan and Germany where refrigerated last-mile infrastructure investments lag demand growth, and pursue white-label supply relationships with direct-to-consumer bakery kit operators seeking customized fat-profile specifications. For Investors and Strategic Acquirers: Consolidation pressure builds where mechanical whipping equipment expertise overlaps with plant-based stabilizer formulation capabilities across European and North American assets. Long-term viability favors integrated agribusiness conglomerates with captive vegetable fat and emulsifier supply chains over pure-play topping manufacturers exposed to input cost volatility. Watch for inflection signals in FDA GRAS determination timelines for alternative propellants that would unlock unified trans-Atlantic product platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Whipping System Deployment | Eliminates EU F-Gas Regulation compliance costs while creating recurring gas supply revenue streams in Germany. |
| REACH-Compliant Emulsifier Certification | Secures clean-label positioning premiums in Bavarian bakery chains facing ECHA hydrocolloid restrictions. |
| Direct HoReCa Procurement Relationships | Bypasses distributor margin compression in United States quick-service restaurant dessert program consolidation. |
| Compressed Gas Propellant Blending | Opens reformulation pathways for F-Gas compliance without mechanical system capital expenditure requirements. |
| Online Retail Cold-Chain Expansion | Captures subscription bakery kit growth in Japan and Germany through refrigerated last-mile infrastructure investments. |
Research Methodology
Coverage spans Germany, the United States, Japan, the United Kingdom, and Canada, with primary inputs from each market combining interviews with foodservice procurement directors, emulsion R&D scientists, bakery chain category managers, and refrigerated logistics operators with secondary validation from EU F-Gas Regulation implementation timelines, FDA GRAS determination databases, EFSA novel food consultation records, and trade flow data from customs authorities. Bottom-up volume modeling triangulates against top-down market sizing across the projection horizon.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, application, distribution channel, and customer type segmentation dimensions, with CAGRs derived from regression analysis of historical penetration rates adjusted for regulatory phase-in schedules and equipment replacement cycles. Forecast inputs incorporate mechanical whipping system adoption curves, propellant chemistry approval timelines, and plant-based ingredient stream scaling trajectories.
Revisions become necessary when EU F-Gas Regulation phasedown acceleration, FDA GRAS determination delays, or Southeast Asian vegetable fat supply disruptions materialize beyond baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Casual Marinated Products Market
Processed Foods
Global Potato Flake Market
Processed Foods
Butter Crisco Market
Processed Foods
Processed Superfruits Market
Processed Foods
Egg Powder Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Egg White Cubes Market
Processed Foods
Industrial Margarine Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Processed Meat Market
Processed Foods
Low Fat Soups Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Coffee Creamer Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
North America Soup Market