
 South America Soup Market | 2026-2036
South America Soup Market Size, Share, and Industry Trends Forecast 2026-2036
South America Soup Market Analytics
Multi-source procurement for vegetable bases and protein inputs is realigning how manufacturers balance cost stability against supply resilience. Nestlé S.A. leverages its regional processing footprint to secure consistent access to local legume suppliers. Unilever PLC anchors its portfolio through dedicated dry-mix facilities in Brazil and Argentina. Kraft Heinz Company competes by sustaining long-term contracts with Andean vegetable processors.
Soup comprises liquid or semi-liquid food preparations typically containing water, stock, or milk combined with solids such as vegetables, meats, or legumes, processed through thermal treatment and often preserved via retort canning, aseptic filling, or dehydration to achieve shelf stability from several months to multiple years. Its primary commercial purpose spans both retail household consumption and food service channels requiring scalable, labor-minimizing meal solutions. Instant soup commands volume leadership due to low unit cost and minimal preparation requirements, while ready-to-eat soup captures expanding margin pools as chilled distribution networks penetrate Brazilian and Colombian urban centers. Dry soup maintains entrenched demand in price-sensitive Andean markets where water boiling remains standard practice.
ANVISA governs nutritional labeling and sodium thresholds across Brazil, Argentina's national food safety authority enforces comparable additive restrictions, and MERCOSUR technical regulations harmonize cross-border trade standards for processed foods. These frameworks elevate reformulation costs for exporters while creating compliance barriers for non-regional suppliers. Stakeholders must monitor evolving sodium reduction mandates and bi-national MERCOSUR protocol updates to anticipate formulation requirements and sourcing adjustments.
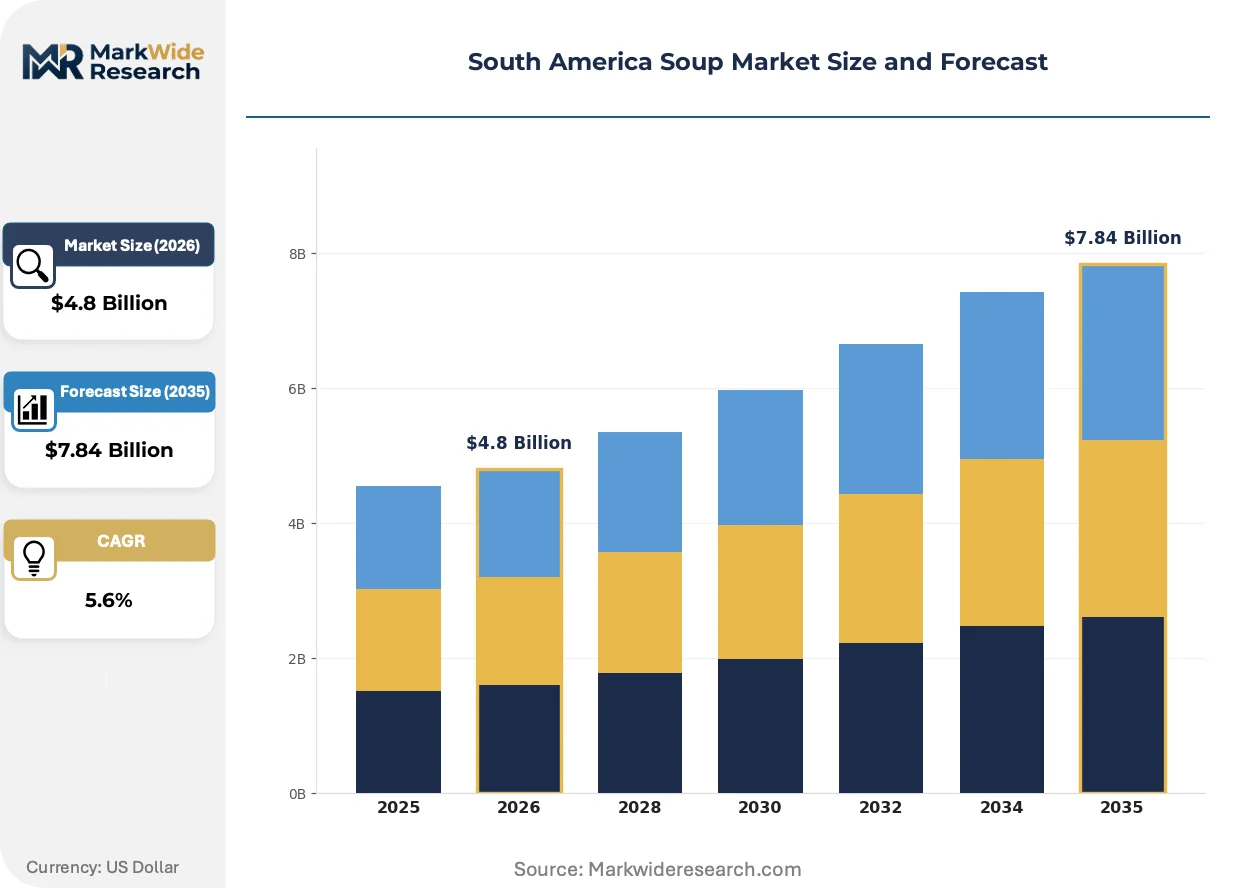
Market Dynamics
ANVISA's sodium reduction mandates are forcing wholesale recipe reformulation across Brazilian manufacturing lines, compressing margin structures while opening first-mover advantages for compliant producers.
Growth Catalysts
- ANVISA Labeling Mandates:Brazil's updated nutritional disclosure rules push manufacturers toward reduced-sodium portfolios, creating competitive differentiation for early reformulators.
- Cold-Chain Expansion:Chilled distribution infrastructure in São Paulo and Buenos Aires unlocks fresh soup formats previously constrained by spoilage risk.
- Urban Household Concentration:Dual-income families in southeastern Brazilian corridors drive demand for ready-to-eat meal solutions requiring minimal preparation time.
Market Restraints
- Legume Price Volatility:Regional dependency on Argentine and Brazilian bean harvests exposes cost structures to climate-driven supply shocks.
- MERCOSUR Compliance Friction:Cross-border technical regulations create documentation burdens for exporters moving product between member states.
- Fresh Format Limitations:Shelf-life constraints restrict chilled soup distribution to major metropolitan areas with reliable cold-chain coverage.
Strategic Opportunities
- Colombian Urban Penetration:Bogotá and Medellín chilled retail networks remain underdeveloped relative to southern cone capitals.
- Plant-Protein Convergence:Blending traditional legume bases with emerging pea-protein isolates targets flexitarian consumer segments.
- E-Commerce Direct Channels:Subscription-based soup delivery bypasses traditional retail slotting fees in Brazilian metropolitan markets.
Industry Challenges
- Sodium Reduction Expertise Gap:Food science talent capable of maintaining flavor profiles at lower salt concentrations commands premium compensation in São Paulo.
- Retort Line Retrofitting Costs:Existing canning facilities require capital-intensive upgrades to process reformulated low-acid recipes.
- Legacy Distributor Integration:Traditional wholesale networks resist chilled product handling protocols, forcing parallel logistics builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Soup Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Soup, Canned Soup, Dry Soup, Ready-to-Eat Soup Ingredient Type: Vegetable, Meat, Seafood, Legume Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Packaging Type: Plastic Containers, Tetra Packs, Cans, Pouches |
| Companies Covered | Campbell Soup Company, Nestlé S.A., Unilever PLC, Kraft Heinz Company, General Mills, Ajinomoto Co., Inc., Nissin Foods Holdings Co., Ltd., Quala, Conagra Brands, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Soup Market Evolving Landscape
Reformulation science and distribution technology are converging to reshape competitive positioning across the southern cone, with regulatory pressure acting as the primary accelerant of product-level change.
High-pressure processing is overtaking conventional thermal treatment for chilled soup preservation. Brazilian retailers in São Paulo and Rio de Janeiro are adopting HPP-equipped facilities at accelerating pace. This technology is overtaking retort canning for premium-positioned fresh formats by extending shelf life without flavor degradation.
MERCOSUR technical harmonization protocols are reducing cross-border certification duplication for processed food exporters. Argentine and Brazilian regulators coordinate additive threshold alignments through bi-national working groups. Chilled soup manufacturers targeting both markets benefit from streamlined compliance pathways.
Urban convenience-store penetration is compressing traditional supermarket dominance for single-serve soup purchases. Brazilian petrol-station retail chains now stock ambient and chilled formats alongside prepared foods. This channel rotation is most visible in São Paulo's extended metropolitan zone where commute patterns favor grab-and-go consumption.
South America Soup Market Segmentation
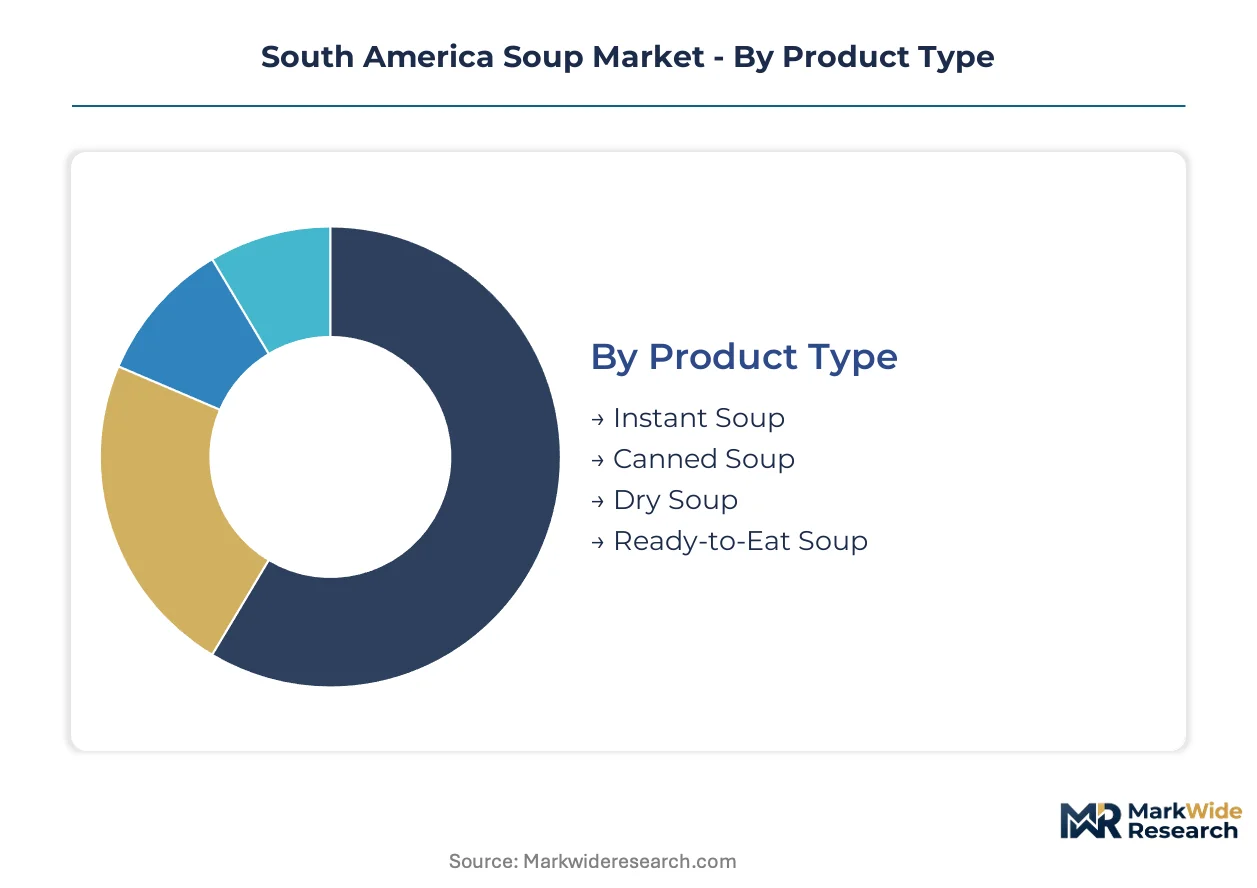
Soup manufacturers in South America align product architecture with distinct consumption occasions and infrastructure constraints. Each segmentation axis reveals divergent margin structures and distribution requirements across Brazilian, Argentine, and Colombian markets.
Product Type:
Preparation technology determines shelf-life economics and cold-chain dependency across southern cone manufacturing.
- Instant Soup:Dehydrated formulations requiring only hot water activation dominate volume in price-sensitive Andean corridors. Brazilian urban households in São Paulo's periphery favor single-serve sachets for workplace consumption.
- Canned Soup:Retort-processed metal packaging delivers multi-year ambient stability. Argentine consumers in Buenos Aires metropolitan zone sustain entrenched demand for traditional vegetable and meat varieties despite sodium reformulation pressures from ANVISA-aligned standards.
- Dry Soup:Concentrated bouillon and noodle blocks target markets where boiling water access exceeds refrigeration penetration. Colombia's mountainous interior municipalities rely on this format due to intermittent electricity supply.
- Ready-to-Eat Soup:Chilled aseptic or HPP-treated products command premium positioning. São Paulo and Rio de Janeiro cold-chain expansion enables fresh-format penetration where spoilage risk once prohibited distribution.
Instant soup leads on scale; ready-to-eat soup leads on momentum.
Ingredient Type:
Input sourcing geography shapes cost volatility and reformulation flexibility for Brazilian and Argentine processors.
- Vegetable:Tomato, pumpkin, and squash bases concentrate processing in Argentina's Córdoba agricultural belt. ANVISA sodium mandates are forcing vegetable-soup reformulation toward potassium-chloride blends without flavor degradation.
- Meat:Beef and chicken broth formulations anchor Argentine consumption patterns. Brazilian processors in Paraná state face input cost pressure from feed-price fluctuations affecting poultry supply contracts.
- Seafood:Shrimp and fish-based varieties concentrate in Chilean and Peruvian export-oriented production. Limited penetration in Brazil's interior reflects cold-chain gaps and taste preference divergence.
- Legume:Black bean, lentil, and chickpea soups leverage regional harvest advantages. Argentine bean crop variability exposes manufacturers to margin compression during drought cycles.
Vegetable formulations capture the broadest addressable base; legume variants are climbing the fastest on protein-positioning trends.
Distribution Channel:
Channel selection dictates packaging format, margin retention, and promotional investment intensity across metropolitan corridors.
- Supermarkets:Hypermarket and supermarket chains in São Paulo, Buenos Aires, and Bogotá control ambient soup volume. Slotting fees and promotional calendar compliance compress net margins for mid-tier brands.
- Online Retail:E-commerce penetration accelerates in Brazilian metropolitan zones where subscription models bypass retail gatekeepers. Chilled soup remains constrained by last-mile temperature control limitations.
- Convenience Stores:Petrol-station retail chains across southeastern Brazil now stock single-serve formats for commuter consumption. This channel rotation favors ambient and retort-pouched products with extended unrefrigerated display tolerance.
- Food Service:Institutional kitchens and quick-service restaurants in urban Colombia demand bulk-format dehydrated bases. Labor-cost minimization drives soup concentrate adoption over scratch preparation.
Supermarkets retain volume leadership; online retail is gaining share fastest on direct-to-consumer margin recovery.
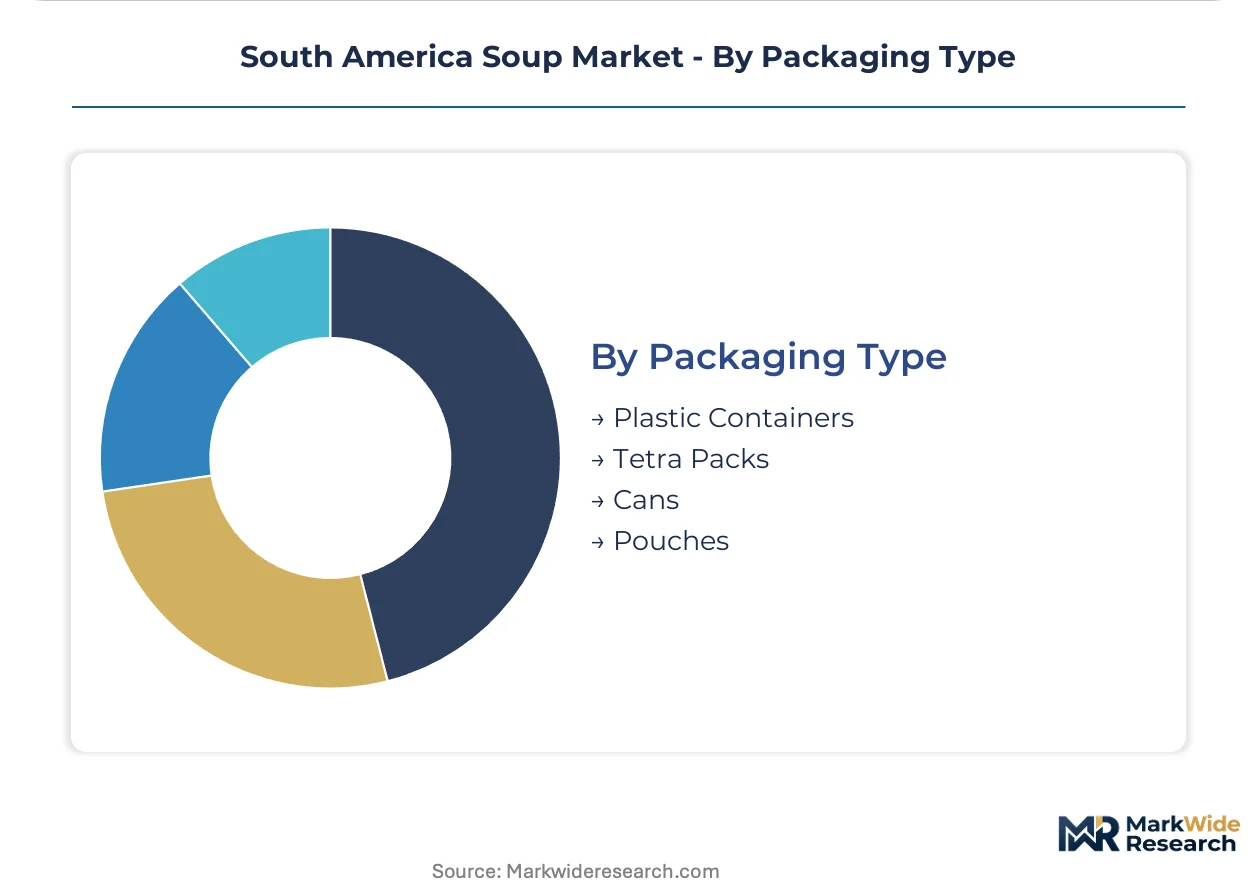
Packaging Type:
Material selection balances shelf-life extension, logistics cube efficiency, and regulatory compliance across MERCOSUR trade corridors.
- Plastic Containers:Polypropylene tubs dominate chilled ready-to-eat formats in São Paulo refrigerated retail. ANVISA migration testing requirements elevate compliance costs for imported resin formulations.
- Tetra Packs:Aseptic carton technology enables ambient-stable vegetable and legume soups without retort flavor degradation. Brazilian processors in Minas Gerais are retrofitting lines for carton filling to access export markets.
- Cans:Three-piece and two-piece metal containers retain cost leadership for high-acid vegetable varieties. Argentine canning facilities face capital-intensive upgrades for low-sodium recipe compatibility.
- Pouches:Retort and spouted flexible formats reduce logistics weight versus rigid alternatives. Colombian convenience-store penetration favors pouch geometry for shelf-space efficiency.
Cans maintain scale dominance; Tetra Packs show the steepest expansion trajectory on premium-format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints across the southern cone. Brazil's ANVISA sodium mandates impose higher compliance costs than Argentine standards, prompting some processors to shift reformulation-heavy production toward Buenos Aires corridors while retaining distribution hubs in São Paulo.
Brazil
ANVISA's updated labeling disclosures and sodium thresholds drive wholesale recipe reformulation across southeastern manufacturing corridors. São Paulo state's cold-chain infrastructure expansion enables fresh-format penetration previously blocked by spoilage constraints. Campinas and Sorocaba industrial zones host retrofitting investments for low-sodium retort line compatibility.
Argentina
Buenos Aires metropolitan households sustain entrenched demand for traditional meat and vegetable soup varieties despite cross-border regulatory alignment pressures. The national food safety authority enforces additive restrictions comparable to Brazilian standards through bi-national MERCOSUR working groups. Córdoba's agricultural belt concentrates tomato and legume processing for regional export.
Colombia
Bogotá and Medellín urban corridors exhibit underdeveloped chilled retail networks relative to southern cone capitals, creating first-mover opportunities for cold-chain investors. The national health regulator maintains distinct additive thresholds outside MERCOSUR harmonization protocols. Cali's food processing cluster specializes in dry-format production for mountainous interior municipalities with intermittent electricity supply.
Chile
Santiago's retail sophistication supports premium-positioned fresh soup formats through expanding HPP-equipped distribution facilities. The national economic development agency incentivizes processed food export capacity through targeted credit lines. Valparaíso port infrastructure enables seafood-based soup exports leveraging Pacific coast harvest advantages.
Peru
Lima's food service sector drives institutional demand for concentrated soup bases in quick-service restaurant applications. The national quality and sanitation regulator enforces standards for processed foods distinct from MERCOSUR technical regulations. Arequipa's agricultural valleys supply quinoa and native potato inputs for differentiated regional formulations.
South America Soup Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chilled-format specialization and direct-to-consumer channels. The market exhibits moderate consolidation with multinational food conglomerates anchoring volume leadership alongside regional specialists commanding niche positioning. Three archetypes dominate: diversified global packaged-food conglomerates with regional processing footprints; regional specialists leveraging local legume and vegetable supply relationships; and emerging direct-to-consumer brands bypassing traditional retail gatekeepers. Competitive intensity centers on sodium-compliant reformulation speed and cold-chain partnership depth.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever PLC exemplify scale-driven positioning through dedicated dry-mix facilities and regional procurement networks. Kraft Heinz Company occupies a position between global scale and regional sourcing integration. These anchors represent varying approaches to ANVISA compliance cost absorption and MERCOSUR cross-border logistics coordination.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Nestlé S.A. |
| Unilever PLC |
| Kraft Heinz Company |
| General Mills |
| Ajinomoto Co., Inc. |
| Nissin Foods Holdings Co., Ltd. |
| Quala |
| Conagra Brands |
| Others |
Value Network & Pricing Analysis
Supermarket chains in São Paulo and Buenos Aires anchor volume procurement and enforce slotting-fee structures that compress net margins for mid-tier soup brands. This buyer concentration forces manufacturers to absorb ANVISA compliance costs while maintaining retail price points across ambient, chilled, and dry-format portfolios.
Pricing Analysis
Retailer markup layers dominate final shelf pricing, with hypermarket chains extracting promotional calendar compliance as a condition of distribution access. Price differentiation stratifies across sodium-compliant premium tiers, standard reformulated lines, and economy dry-mix formats. Pricing pressure stems from ANVISA-mandated recipe reformulation raising input costs without corresponding retail price elasticity. Price-sensitive Andean municipalities favor dehydrated sachets, while São Paulo dual-income households absorb chilled-format premiums.
Supply Chain Analysis
Direct-to-food-service channels handle institutional bulk demand through concentrate and dehydrated base formats. Manufacturing concentrates in Brazil, Argentina, and Colombia, with Córdoba's agricultural belt feeding regional tomato and legume inputs. Raw material dependencies rest on Argentine bean harvests, Brazilian poultry supply contracts, and Andean vegetable processors. Single-source vulnerability runs through climate-exposed legume crops. Distribution runs through traditional wholesale networks resisting chilled-product handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America soup market reads as a late-cycle quality story, with urban household demand shifting toward HPP-preserved fresh formats commanding sustained margin premiums over ambient alternatives.
For Market Incumbents: Anchor sodium-compliant reformulation leadership through captive food-science talent acquisition in São Paulo. Deepen backward integration into Andean vegetable processing to insulate margin structures from Argentine harvest volatility. Cold-chain partnership exclusivity with Rio de Janeiro and Bogotá distributors defends against emerging chilled-format specialists. For New Entrants and Emerging Players: Convenience-store chains in Brazil's extended metropolitan zones offer the most penetrable channel for single-serve ambient and retort-pouched launches. Colombian chilled retail networks remain underdeveloped relative to southern cone infrastructure. Subscription-based direct-to-consumer models bypass São Paulo supermarket slotting fees. For Investors and Strategic Acquirers: Regional packaged-food conglomerates are the most active acquirer in this space, targeting sodium-compliant reformulation capabilities and cold-chain logistics assets. The long-term viability window favors processors with ANVISA-aligned portfolios and HPP-equipped facilities. The signal to watch is MERCOSUR technical harmonization progress accelerating cross-border manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium-Compliant Reformulation | ANVISA mandates force recipe overhaul, creating first-mover advantage for compliant Brazilian producers. |
| HPP Infrastructure Investment | High-pressure processing adoption in São Paulo unlocks fresh-format shelf-life extension without thermal degradation. |
| Cold-Chain Partnership Expansion | Direct alliances with refrigerated distributors in Bogotá and Medellín capture underpenetrated Colombian urban demand. |
| Direct-to-Consumer Channel Launch | Subscription models bypass traditional retail gatekeepers and recover margin compression from supermarket slotting fees. |
| Andean Vegetable Processor Integration | Upstream control over Córdoba and Peruvian agricultural inputs reduces exposure to Argentine legume price volatility. |
Research Methodology
Bottom-up household consumption modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with brand managers, category buyers at Brazilian and Argentine retailers, supply planners at regional processors, and channel sales heads inform demand-side assumptions. Secondary validation draws from ANVISA regulatory filings, MERCOSUR technical protocol documents, customs trade records, and Nielsen retail audit data. Triangulation between end-use extrapolation and supply-side verification ensures cross-consistency.
Input-output matrices map ingredient cost trajectories, cold-chain infrastructure penetration rates, and regulatory compliance cost burdens against volume and value outputs across the projection horizon. Segmentation dimensions include preparation technology, ingredient base, distribution channel, and packaging format. CAGRs derive from regression analysis of historical consumption patterns adjusted for ANVISA implementation timelines and urban household formation rates. Forecast inputs incorporate sodium-reduction R&D expenditure trends and HPP equipment installation data.
Revisions become necessary when ANVISA mandates accelerate beyond modeled implementation schedules, Argentine legume harvests experience sustained climate disruption, or MERCOSUR harmonization protocols stall. Forecasts reflect documented assumptions about cold-chain expansion pacing and urban income growth trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Egg Powder Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Vegetable Market
Processed Foods
Low Fat Soups Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Broth Market
Processed Foods
Europe Soup Market
Processed Foods
Processed Egg Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
South America Processed Meat Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Processed Cashew Market
Processed Foods
Block Margarine Market