
 Processed Potatoes Market | 2026-2036
Processed Potatoes Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Potatoes Market Analysis
Premium-grade frozen fry specifications is rotating toward higher solids content and longer cut profiles. McCain Foods Limited leverages vertical integration from seed selection through distribution to sustain consistent supply across North American and European operations. Lamb Weston Holdings, Inc. anchors its competitive position through specialized processing lines dedicated to quick-service restaurant formats. J.R. Simplot Company differentiates via proprietary potato varieties bred for fry color stability and oil absorption control.
Processed potatoes encompass tubers subjected to washing, peeling, cutting, blanching, drying, frying, or freezing to achieve defined moisture content, reducing sugar levels below specified thresholds, and texture parameters suitable for extended shelf stability. The primary commercial purpose centers on delivering standardized, labor-saving inputs to food service operators and retail consumers with minimal preparation requirements. Frozen fries command the largest value pool within product type segmentation, while dehydrated potatoes represent the fastest-expanding category driven by camping, military, and emergency food applications. Distribution channel dynamics reveal food service as the dominant volume pathway, though online retail is gaining traction as direct-to-consumer frozen shipping logistics mature.
The USDA sets grading standards for processed potato identity and defect tolerances, while FDA regulations govern acrylamide mitigation strategies and labeling requirements for fried potato products. EU EFSA guidelines on process contaminants and national cold chain standards in major producing countries collectively elevate capital requirements for new processing entrants. Stakeholders must monitor evolving acrylamide thresholds and carbon intensity disclosures as these frameworks tighten product specifications and facility compliance obligations.
Market Dynamics
The EU F-Gas Regulation is forcing refrigeration retrofits across frozen potato processing facilities, while Brazilian food service infrastructure expansion concentrates demand growth in specific metropolitan corridors. Cold chain efficiency mandates are simultaneously elevating capital barriers and reshaping competitive positioning among established processors.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-global-warming-potential refrigerants are accelerating equipment replacement cycles in frozen fry production facilities, creating upgrade demand across European processing plants.
- Brazilian food service modernization:Quick-service restaurant chain expansion in São Paulo and Rio de Janeiro corridors is pulling frozen potato volume into Latin America's largest consumer market.
- Dehydrated potato formats:Military ration specifications and emergency food stockpiling requirements from national defense agencies are expanding shelf-stable product applications.
Market Restraints
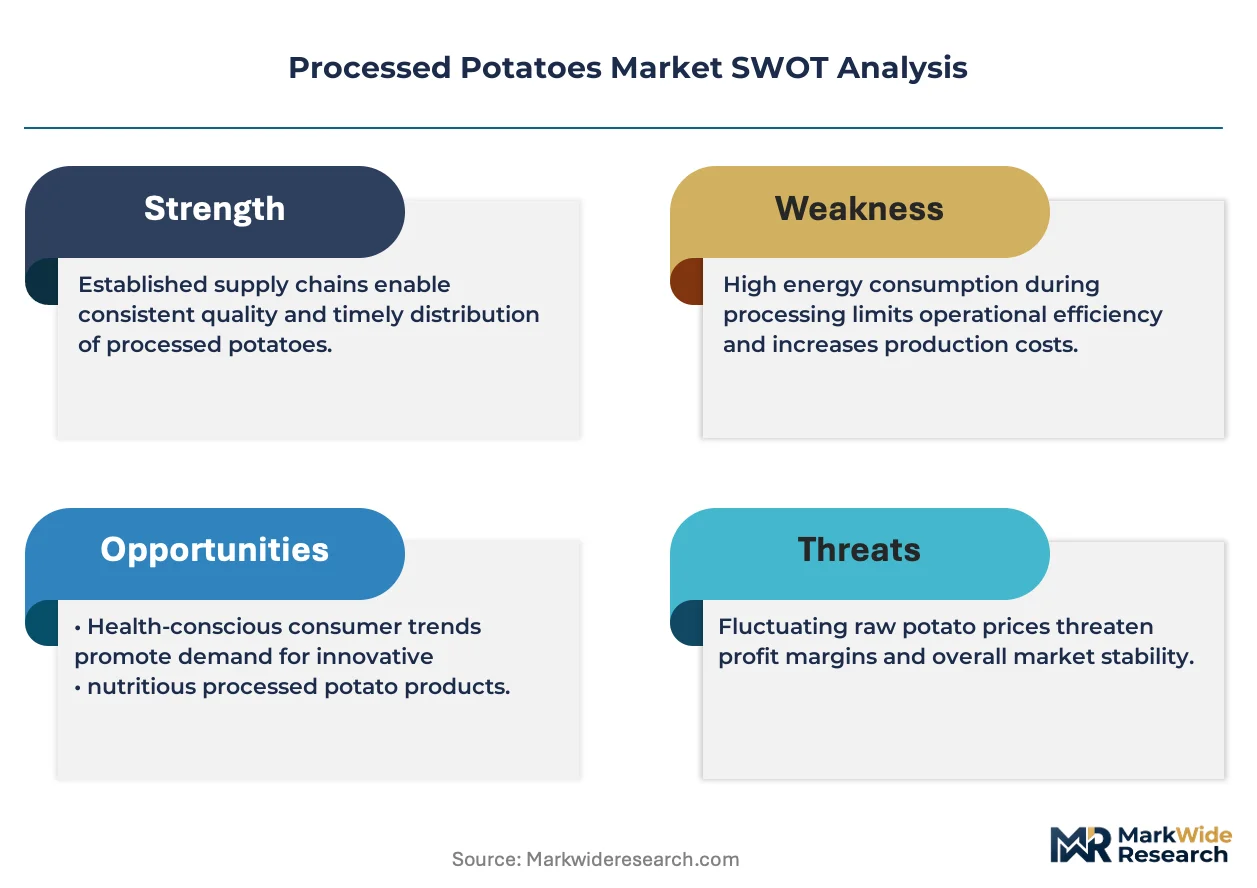
- Input cost volatility:Natural gas prices directly govern blanching and frying energy economics, creating margin compression during supply shocks.
- Processing concentration:Frozen fry capacity clusters in Idaho, Washington, and the Netherlands, exposing buyers to regional weather and logistics disruptions.
- Acrylamide thresholds:FDA mitigation guidance and EFSA process contaminant limits are tightening fry color specifications and reject rates.
Strategic Opportunities
- Direct-to-consumer frozen shipping:Insulated packaging innovations are enabling online retail channels to bypass traditional food service distribution.
- Indian cold chain development:Food processing PLI scheme incentives are attracting processing investment into potato-growing states.
- Specialty cut formats:Crinkle-cut and wedge profiles for premium casual dining are commanding price premiums over standard straight-cut fries.
Industry Challenges
- Refrigeration technician scarcity:F-Gas certified service personnel shortages are extending equipment downtime during peak harvest windows.
- Legacy ERP integration:Cold chain traceability software deployment faces data migration friction with decades-old production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Potatoes Market |
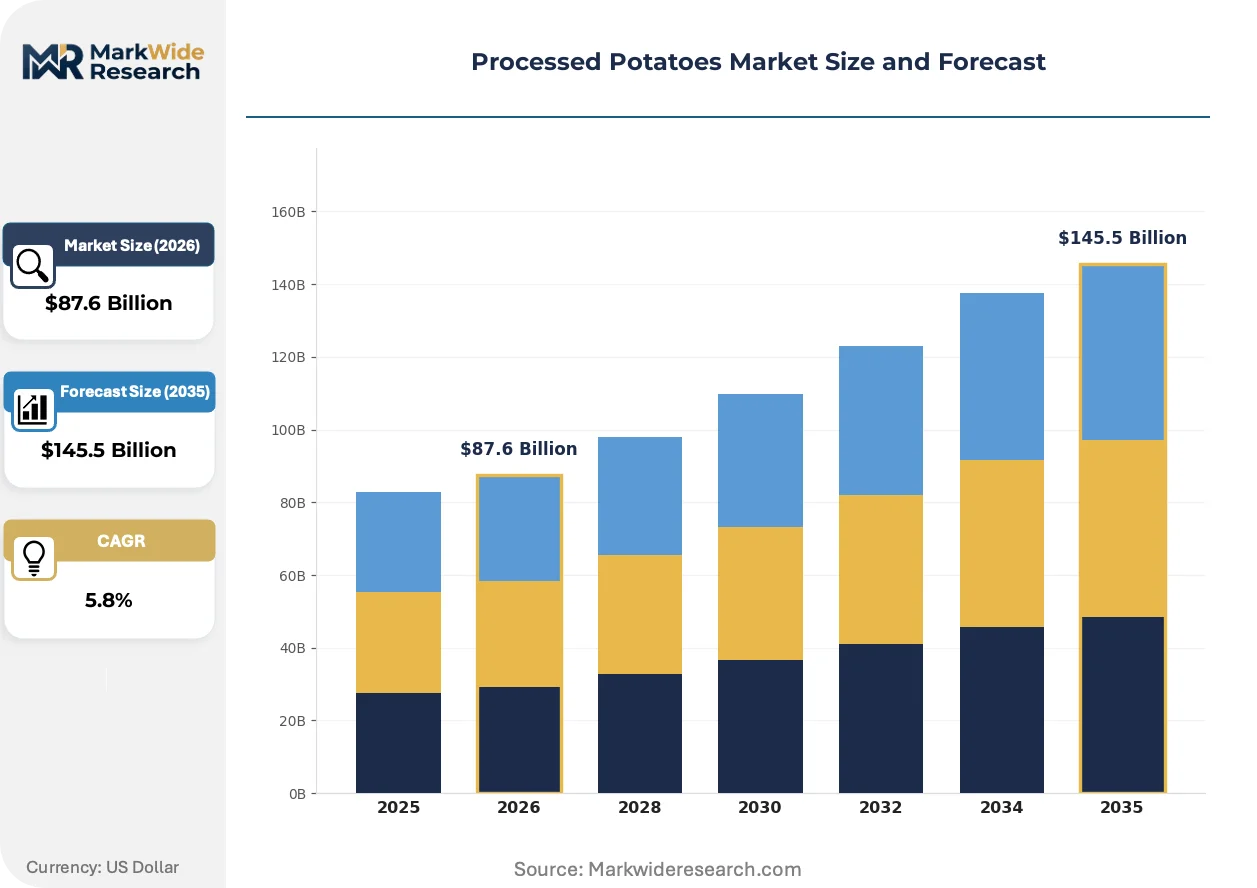
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fries, Dehydrated Potatoes, Mashed Potatoes, Potato Chips Packaging Type: Bags, Boxes, Cans, Vacuum Sealed Distribution Channel: Retail Stores, Online Retail, Food Service, Food Processing End User: Households, Restaurants, Food Manufacturers, Cafeterias |
| Companies Covered | Aviko B.V., Idahoan Foods, McCain Foods Limited, Agristo, Farm Frites International, Lamb Weston Holdings, Inc., Cavendish Farms Corporation, Intersnack Group GmbH, J.R. Simplot Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Potatoes Market Emerging Trajectories
Pulse electric field processing and advanced sorting optics are compressing traditional processing steps. Sustainability disclosure requirements are embedding carbon accounting into product specifications. These forces are reconfiguring capital deployment and procurement criteria across the value chain.
High-pressure processing for fresh-cut potato products is displacing thermal blanching in premium salad and refrigerated side dish applications. European retail chains are adopting these lines to meet clean-label positioning requirements. The technology is compressing energy consumption per unit while extending refrigerated shelf life without chemical preservatives.
REACH chemical authorization procedures are restricting certain oil stabilizers and coating additives previously common in par-fry operations. Processors are reformulating surface treatments to maintain crispness standards under revised substance restrictions. German and Dutch facilities face the tightest compliance timelines, accelerating substitution toward enzymatic and physical surface modification methods.
Quick-service restaurant chains are consolidating frozen fry suppliers into multi-year volume agreements with embedded sustainability metrics. This procurement concentration is displacing spot-market purchasing and fragmenting the remaining spot volume among secondary processors. The shift is most visible in North American and Western European contract structures, where carbon intensity disclosures now accompany price negotiations.
Processed Potatoes Market Segmentation
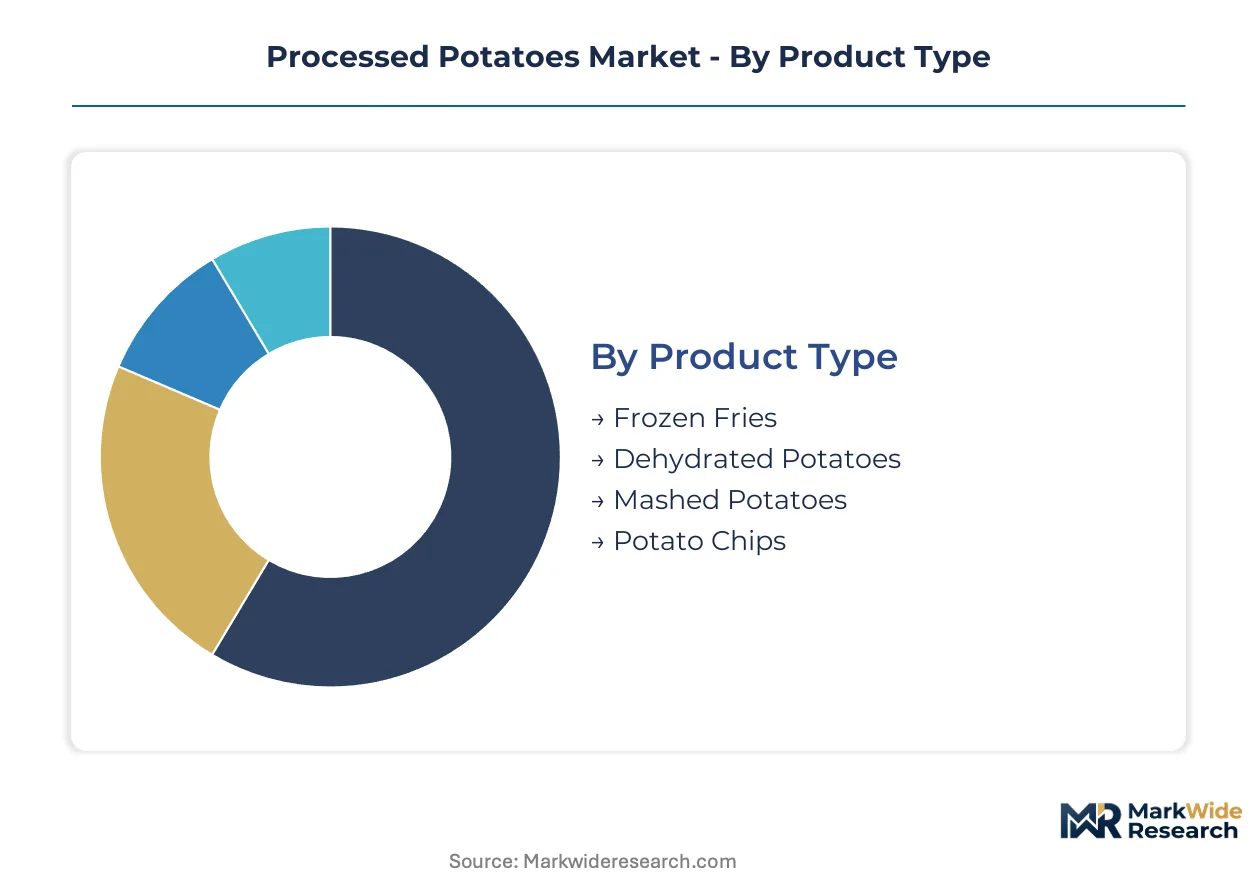
Processed potato segments flow through distinct channel economics. Frozen fries dominate food service procurement. Dehydrated formats serve institutional stockpiling. Channel-mix variations determine margin structures and capital intensity requirements across each segment.
Product Type:
Frozen fries and dehydrated potatoes anchor distinct distribution pathways. Quick-service chains pull frozen volume through dedicated cold chain logistics. Military and emergency agencies source dehydrated formats through institutional procurement frameworks.
- Frozen Fries:Par-fried and blast-frozen strips with defined solids content and cut geometry specifications. Quick-service restaurant chains in Brazil and North America concentrate procurement into multi-year supply agreements with embedded sustainability metrics.
- Dehydrated Potatoes:Flakes, granules, and powder forms with moisture reduced below ten percent for shelf stability. National defense agencies and camping equipment suppliers are expanding stockpiling programs, driving the steepest expansion trajectory among product types.
- Mashed Potatoes:Reconstituted flake and powder blends targeting retail convenience segments.
- Potato Chips:Thin-sliced fried snacks with regional flavor variations dominating retail shelf placement.
By volume, frozen fries lead. By growth pace, dehydrated potatoes are climbing the fastest.
Packaging Type:
Packaging formats align with shelf-life requirements and distribution temperature regimes. Frozen segments demand insulated structures. Ambient-stable dehydrated products utilize barrier films and rigid containers.
- Bags:Multi-layer polymer films with oxygen barrier properties for frozen fry retail packs and dehydrated potato pouch formats.
- Boxes:Corrugated structures with wax or polymer coatings for food service bulk shipments and institutional dehydrated potato deliveries.
- Cans:Metal containers with nitrogen flushing for extended-shelf-life dehydrated potato storage in emergency stockpiles.
- Vacuum Sealed:High-barrier flexible structures displacing traditional formats in premium retail and direct-to-consumer frozen shipping channels.
Bags and boxes together handle the majority of tonnage. Vacuum sealed formats are gaining share fastest in premium positioning.
Distribution Channel:
Channel structure determines price realization and working capital intensity. Food service contracts run on annual or multi-year frameworks. Online retail requires specialized frozen logistics investments.
- Food Service:Direct procurement by quick-service chains, casual dining groups, and institutional cafeterias with specification-controlled supply agreements. Brazilian metropolitan corridor expansion is pulling volume growth into Latin America's largest consumer market.
- Retail Stores:Supermarket and hypermarket placement with promotional calendar dependencies and private-label competition.
- Online Retail:Direct-to-consumer frozen shipping enabled by insulated packaging innovations and last-mile cold chain maturation.
- Food Processing:Business-to-business ingredient supply for prepared meal manufacturers and snack compounders.
Food service channels move the largest absolute volume. Online retail is expanding most quickly as logistics infrastructure matures.
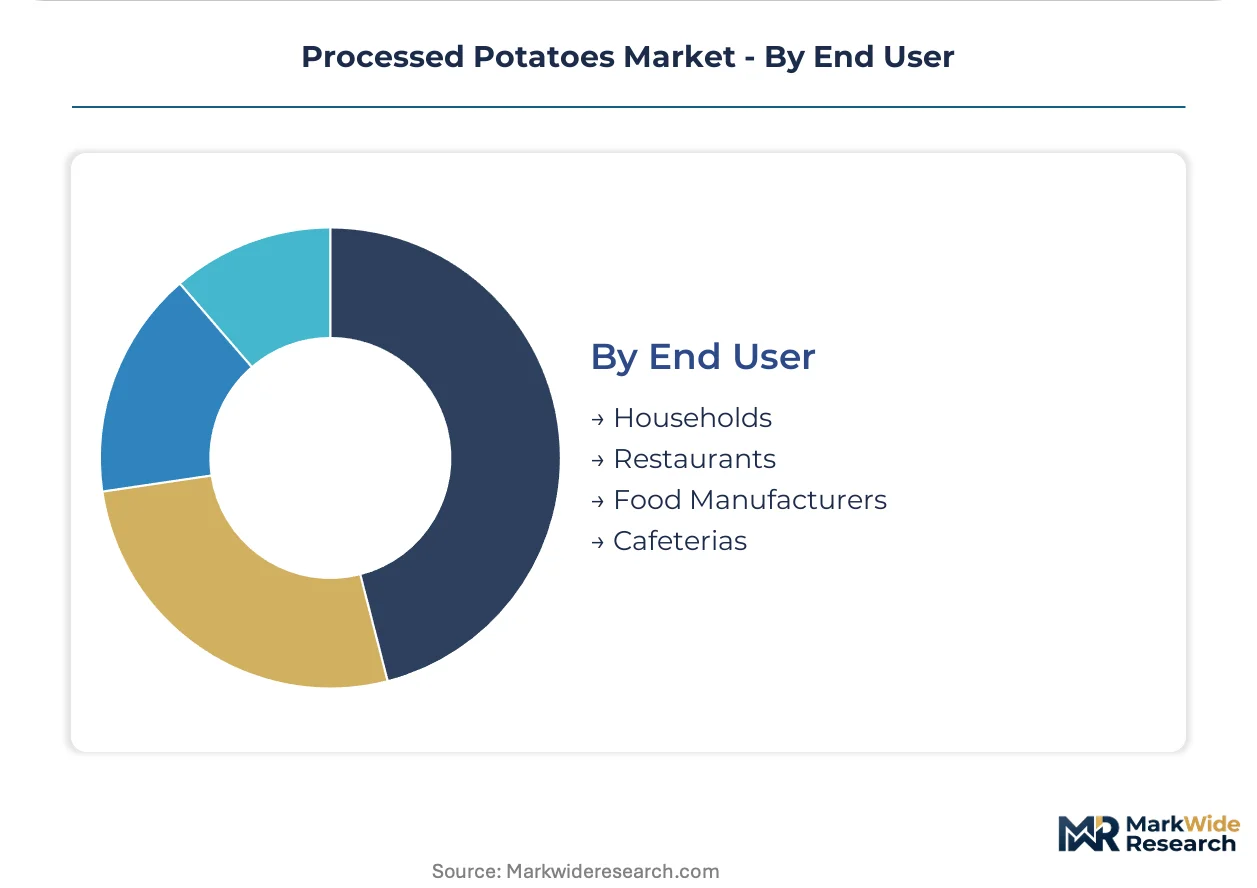
End User:
End-user concentration shapes product specification and service requirements. Restaurants demand consistency at scale. Households respond to convenience positioning and price promotion.
- Restaurants:Quick-service chains and casual dining operators requiring standardized fry performance across locations with minimal labor input.
- Households:Retail consumers purchasing frozen and shelf-stable formats for home preparation convenience.
- Food Manufacturers:Ingredient buyers integrating dehydrated potato derivatives into prepared meals, snacks, and bakery applications.
- Cafeterias:Institutional feeding operations in schools, hospitals, and corporate facilities with cost-controlled procurement mandates.
Restaurants absorb the highest volume share. Food manufacturers are pulling dehydrated potato growth fastest through ingredient substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium exports frozen fry volume to quick-service chains across Germany and France through dedicated cold chain corridors. Dutch processors supply dehydrated formats to military procurement agencies in the United Kingdom and Scandinavia. These trade flows concentrate processing investment in the Low Countries while pulling demand growth into Southern European and Latin American metropolitan markets.
United States
Idaho and Washington processing clusters supply frozen fries to quick-service chains throughout North America. The USDA enforces grading standards for processed potato identity and defect tolerances. McCain Foods Limited operates integrated production from seed selection through distribution across these Pacific Northwest facilities.
Netherlands
Frozen fry capacity concentrates in Dutch facilities serving German and Belgian quick-service expansion. The EU F-Gas Regulation mandates lower-global-warming-potential refrigerant retrofits across these processing plants. Farm Frites International anchors production in the Noord-Brabant corridor with specialized lines for food service formats.
Germany
Dehydrated potato demand from military ration programs and emergency stockpiling agencies is expanding processing volume. REACH chemical authorization restricts certain oil stabilizers and coating additives in par-fry operations. Intersnack Group GmbH exemplifies the snack-focused processor archetype with operations concentrated in North Rhine-Westphalia.
Brazil
Quick-service restaurant chain expansion in São Paulo and Rio de Janeiro corridors is pulling frozen potato volume into Latin America's largest consumer market. ANVISA governs food safety standards for imported processed potato products. Lamb Weston Holdings, Inc. has positioned processing capacity to serve this Brazilian metropolitan demand concentration.
India
Food processing PLI scheme incentives are attracting dehydration investment into potato-growing states. The FSSAI regulates processed food labeling and safety standards for domestic and export markets. Maharashtra and Gujarat processing clusters are expanding cold chain infrastructure to reduce post-harvest losses and enable frozen fry production.
Processed Potatoes Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and vertical integration dimensions. The processed potatoes sector exhibits tiered concentration with multinational frozen fry processors occupying scale-driven positions while regional dehydration specialists serve institutional and retail niches. Three archetypes dominate: integrated seed-to-distribution operators, dedicated quick-service contract manufacturers, and diversified agribusiness conglomerates with potato processing divisions. Capacity expansion and backward integration into proprietary potato varieties represent the dominant competitive moves as processors defend margin positions against input cost volatility.
Within the integrated multinational tier, McCain Foods Limited and Lamb Weston Holdings, Inc. exemplify scale-driven competitive positioning through captive supply chain control. J.R. Simplot Company occupies a distinct specialization position with emphasis on proprietary breeding programs. Among European private specialists, Aviko B.V. and Agristo represent the continental processor archetype with concentrated frozen fry capacity in the Low Countries. Idahoan Foods anchors the North American dehydration segment with shelf-stable format expertise. Cavendish Farms Corporation and Farm Frites International sit within the mid-scale integrated tier serving regional quick-service procurement.
| Leading Market Players |
|---|
| Aviko B.V. |
| Idahoan Foods |
| McCain Foods Limited |
| Agristo |
| Farm Frites International |
| Lamb Weston Holdings, Inc. |
| Cavendish Farms Corporation |
| Intersnack Group GmbH |
| J.R. Simplot Company |
| Others |
Supply Flow & Price Mechanics
Multi-year volume agreements with embedded sustainability metrics lock in frozen fry supply access and price visibility for quick-service chains across North American and European procurement corridors. These contracts displace spot-market purchasing and fragment remaining spot volume among secondary processors.
Pricing Analysis
Conventional par-fry technology and next-generation pulse electric field processing command divergent price premiums in premium casual dining applications. Three-tier pricing structure across premium, standard, and economy levels separates specialty cut formats from commodity straight-cut fries based on solids content and length specifications. Pricing pressure stems from natural gas volatility governing blanching and frying energy economics. Quick-service chains exhibit highest price sensitivity through consolidated procurement, while premium casual dining operators absorb premiums for performance consistency.
Supply Chain Analysis
The United States and the Netherlands anchor frozen fry production through Idaho-Washington and Noord-Brabant processing clusters. Potato tuber supply draws from contract farming arrangements in named growing regions, while refrigerant systems and specialized cutting equipment feed from European and North American equipment manufacturers. Single-source vulnerability concentrates in F-Gas certified technician pools extending equipment downtime risk. Distribution runs through dedicated cold chain logistics serving quick-service restaurant formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The processed potatoes sector faces high-growth disruption as EU F-Gas Regulation mandates accelerate equipment replacement cycles and reshape capital deployment across European processing facilities.
For Market Incumbents: Secure captive potato supply through contract farming expansion in Idaho and Washington growing regions to defend against input cost volatility. Invest in pulse electric field processing lines to meet clean-label positioning requirements from European retail chains. Prioritize F-Gas certified technician training programs to reduce harvest window downtime exposure. For New Entrants and Emerging Players: EU organic certification fast-track offers entry pathway into premium retail segments demanding clean-label dehydrated formats. Target Indian dehydration capacity expansion under food processing PLI scheme incentives as most penetrable geography. Pursue direct-to-consumer frozen shipping channel development through insulated packaging partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale integrated processors with backward integration into proprietary potato varieties and established quick-service contract relationships. Five-to-ten year viability hinges on carbon intensity disclosure capabilities aligning with procurement mandate evolution. Monitor acrylamide threshold tightening signals as inflection indicator for reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Varieties | Breeding programs at J.R. Simplot Company anchor fry color stability and oil absorption control specifications. |
| F-Gas Refrigeration Retrofit | EU Regulation mandates lower-global-warming-potential equipment across Dutch and German processing plants. |
| Direct-to-Consumer Channel Launch | Insulated packaging innovations enable online retail bypass of traditional food service distribution structures. |
| Specialty Cut Format Expansion | Crinkle-cut and wedge profiles command price premiums in premium casual dining procurement. |
| Dehydrated Capacity Buildout | Military ration specifications from national defense agencies expand shelf-stable product applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with quick-service procurement directors, frozen fry plant managers, dehydration facility engineers, cold chain logistics coordinators, and retail category buyers. Secondary validation drew from USDA grading standards documentation, EU EFSA process contaminant guidelines, FDA acrylamide mitigation guidance, customs trade flow records, and SEC filings from listed processors. Bottom-up volume modeling triangulated against top-down market sizing across product type and channel dimensions.
Across the analysis window, projections incorporate product type segmentation by frozen fry, dehydrated, mashed, and chip formats alongside packaging type, distribution channel, and end-user dimensions. CAGRs were derived from regression analysis of historical volume trajectories and forward scenario weighting. Industry-specific forecast inputs include quick-service restaurant chain expansion timelines, cold chain infrastructure investment flows, and military stockpiling program specifications.
Decision-makers should treat outputs as directional under sustained quick-service procurement concentration and regulatory tightening assumptions; material deviation in natural gas price regimes or acrylamide threshold revisions would warrant model refresh. Recalibration cycles align with material shifts in EU F-Gas implementation timelines and Brazilian food service infrastructure development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Fermented Foods Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Coffee Creamer Market
Processed Foods
Egg Powder Market
Processed Foods
Egg White Cubes Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
Soup & Broth Market
Processed Foods
Apple Butter Market
Processed Foods
Global Potato Flake Market
Processed Foods
United States Ice Cream Market
Processed Foods
Chocolate Filling Market
Processed Foods
Low Moisture Food Market
Processed Foods
Fruit Processing Market
Processed Foods
Yogurt Dip Market