
 Low Fat Puddings Market | 2026-2036
Low Fat Puddings Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Puddings Market Analytics
Asset-light co-manufacturing partnerships is tilting competitive dynamics toward brands that outsource production while retaining formulation control. Nestle leverages its global dairy supply network to secure consistent milk protein inputs for reduced-fat lines. Danone anchors its position through probiotic-infused pudding variants that merge digestive health claims with fat reduction. Kraft Heinz competes via private-label manufacturing contracts that supply retailer-owned low-fat dessert brands.
Low fat puddings are dairy or plant-based dessert products containing reduced butterfat or alternative lipid content, typically manufactured through homogenization and controlled shear processes to maintain creamy mouthfeel without full-fat emulsion stability; they serve commercial and retail markets seeking indulgent formats within calorie-controlled diets. The frozen form segment leads volume as freezer-aisle placement drives impulse purchases across mainstream retail channels. Health food stores represent the fastest-growing distribution channel as specialized retailers curate clean-label and allergen-free pudding assortments for dedicated wellness shoppers. The chocolate product type occupies the largest margin pool due to premium positioning and higher willingness-to-pay for cocoa-intensive reduced-fat formulations.
FDA nutrition labeling rules and EFSA health claim regulations shape permissible fat-content thresholds and front-of-pack communication across North American and European markets. The USDA National Organic Program and EU organic certification standards further constrain ingredient sourcing for premium low-fat pudding lines. Stakeholders must monitor evolving sugar-reduction mandates that frequently accompany fat-reformulation policies and determine whether dual-nutrient reformulation investments will preserve shelf space access.
Market Dynamics
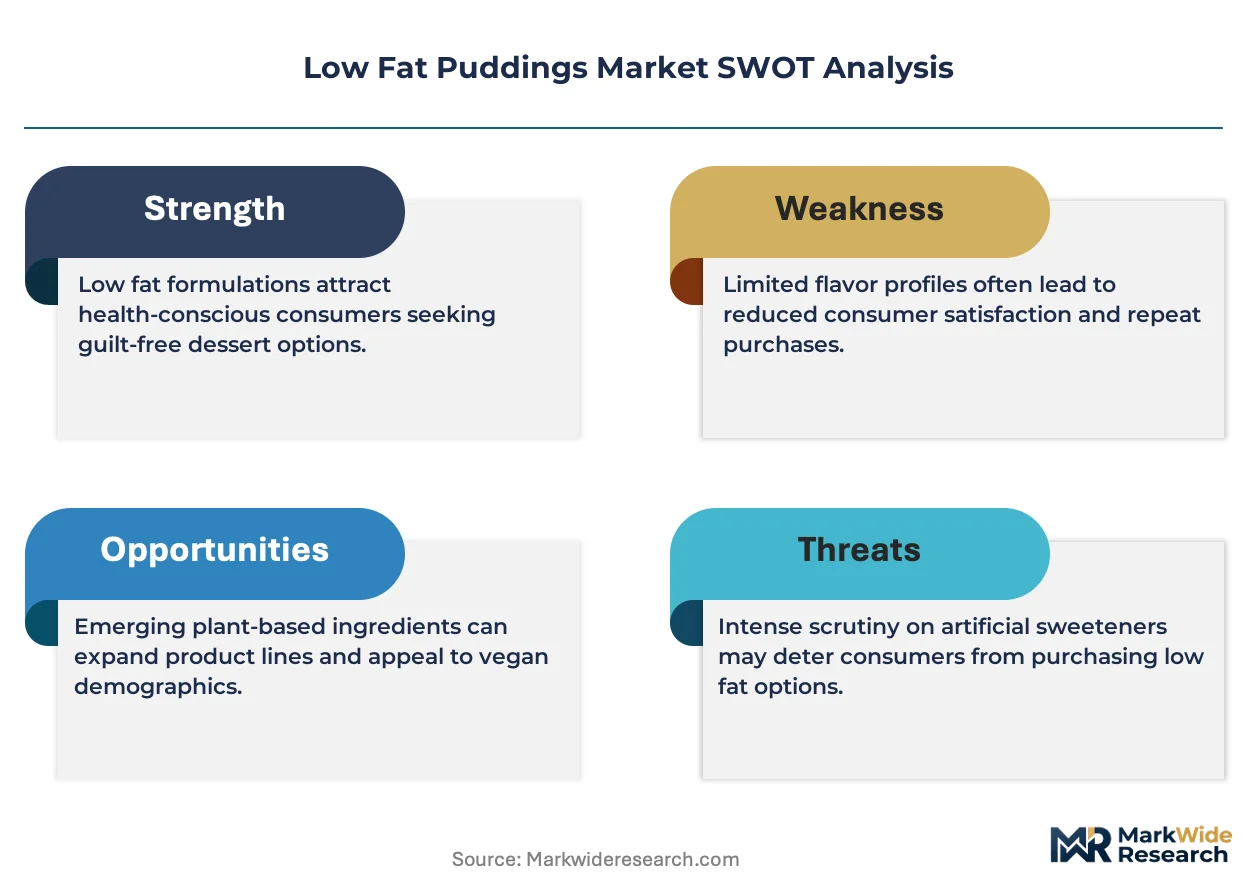
Clean-label formulation mandates from FDA and EFSA are forcing dairy dessert manufacturers to abandon synthetic stabilizers, triggering widespread reformulation cycles that reshape ingredient sourcing and production economics across refrigerated and frozen pudding lines.
Growth Catalysts
- EFSA Health Claim Framework:Permissible fat-content thresholds enable front-of-pack communication that drives consumer trial in European retail channels.
- Probiotic Infusion Technology:Functional ingredient convergence merges digestive wellness positioning with reduced-fat dessert formats in health-conscious segments.
- United States:Sustained refrigerated and frozen dessert consumption patterns anchor volume demand through mainstream grocery and club channels.
Market Restraints
- Milk Protein Input Volatility:Global dairy commodity fluctuations compress margins on reduced-fat lines dependent on concentrated protein isolates.
- Clean-Label Transition Costs:Natural stabilizer systems require 15-40% higher ingredient spend versus legacy synthetic alternatives.
- Substitution Pressure from Plant-Based Desserts:Oat and almond-based puddings capture lactose-intolerant and flexitarian consumers.
Strategic Opportunities
- Germany:Premium organic low-fat pudding segments remain underpenetrated relative to conventional dairy dessert maturity.
- Health Food Store Channel Expansion:Specialized wellness retailers curate allergen-free assortments with higher per-unit economics.
- USDA National Organic Program:Certification tailwinds support price premiums for ingredient-constrained premium lines.
Industry Challenges
- Dual-Nutrient Reformulation Complexity:Simultaneous fat and sugar reduction degrades mouthfeel without advanced emulsion engineering.
- Clean-Label Certification Timelines:USDA organic and Non-GMO Project verification cycles extend 8-14 months, delaying shelf space access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Puddings Market |
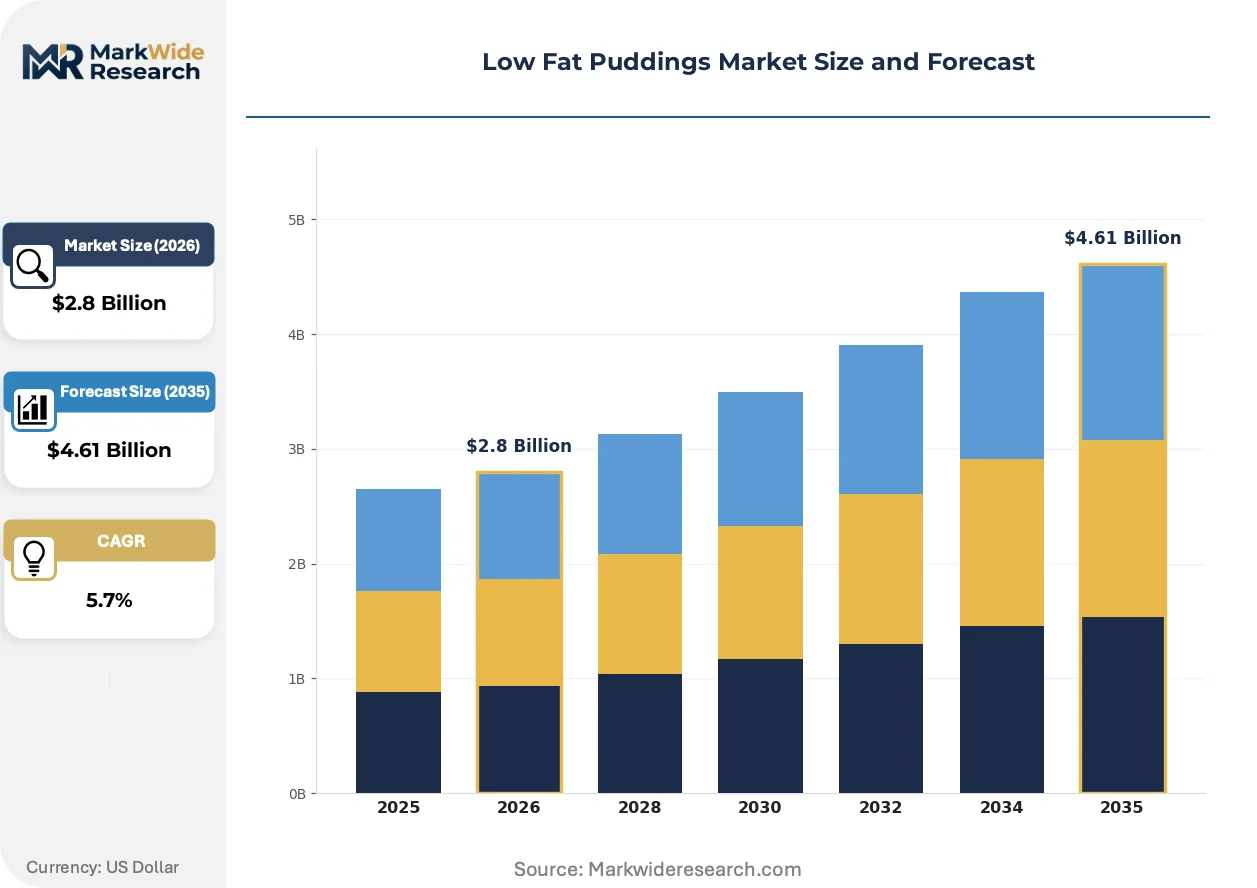
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Vanilla, Caramel, Strawberry Form: Ready-to-Eat, Powder, Liquid, Frozen Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Consumer Type: Health-Conscious, Weight Watchers, Children, Diabetics |
| Companies Covered | Nestle, Danone, Unilever, Kraft Heinz, Mondelez International, General Mills, The Hershey Company, Breyers, Yasso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Puddings Market Evolving Landscape
Advanced emulsion technologies and shifting retail procurement models are compressing traditional competitive advantages while elevating formulation science as the primary value determinant in reduced-fat dessert manufacturing.
Microfluidization homogenization systems achieve sub-micron fat globule distribution without full-fat emulsion stability, enabling creamy texture replication at 30-50% reduced butterfat content. Premium private-label manufacturers in Germany and Japan are adopting these systems at accelerated replacement cycles. Conventional scraped-surface heat exchanger methods are rendering obsolete for mid-tier pudding production.
EU F-Gas Regulation phase-down mandates are accelerating refrigeration infrastructure upgrades across frozen dessert distribution networks. Cold-chain operators face compressed capital deployment timelines to maintain freezer-aisle placement in mainstream retail. Chocolate-intensive reduced-fat formulations face disproportionate exposure due to temperature-sensitive cocoa butter crystallization requirements.
Health food store buyers now demand complete ingredient provenance documentation before assortment inclusion, replacing traditional slotting-fee negotiations. This procurement evolution elevates clean-label pudding suppliers while marginalizing conventional brands lacking supply chain transparency. Japan's metropolitan wellness retail clusters exhibit the most pronounced certification-driven preference compression.
Low Fat Puddings Market Segmentation
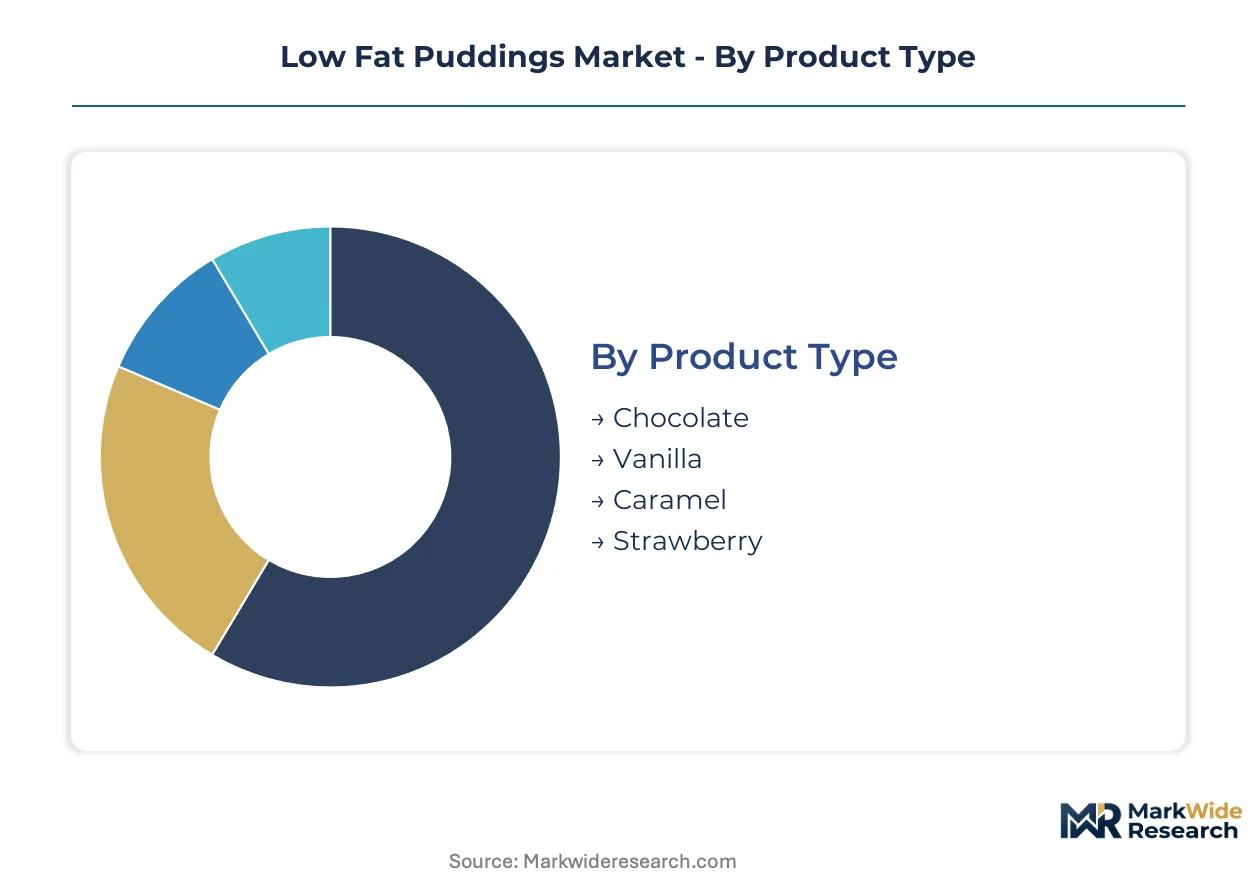
Segmentation in low fat puddings reveals how formulation requirements diverge across consumption occasions and buyer priorities. Manufacturers calibrate fat-replacement systems, sweetness profiles, and packaging formats to match distinct channel and user expectations without crossing into adjacent dessert categories.
Product Type:
Use-case spectrum spans indulgence-driven cocoa formats through fruit-forward options targeting permissibility positioning.
- Chocolate:Cocoa-intensive formulations leverage alkalized powder and reduced-fat cocoa butter to replicate mouthfeel at lower butterfat percentages. United States retail channels concentrate demand for premium dark chocolate variants where EFSA health claim thresholds enable front-of-pack fat reduction messaging.
- Vanilla:Base formulations serve as carriers for functional ingredient integration including probiotic cultures and protein fortification. German refrigerated dessert buyers favor vanilla as a neutral canvas for clean-label ingredient experimentation.
- Caramel:Maillard-reaction flavor systems require careful thermal processing to prevent fat separation during reduced-butterfat reformulation.
- Strawberry:Fruit particulate suspension demands modified starch stabilizers that comply with USDA National Organic Program restrictions on synthetic additives.
Established volume favors chocolate; emerging adoption favors vanilla as functional ingredient convergence accelerates.
Form:
Processing intensity and cold-chain requirements create distinct margin architectures across the format matrix.
- Frozen:Aseptic freezing and controlled nucleation preserve emulsion stability through distribution networks subject to EU F-Gas Regulation compliance timelines. Japan's metropolitan retail clusters anchor volume through convenience store freezer placement.
- Ready-to-Eat:Refrigerated cup formats dominate impulse purchase occasions in United States club and grocery channels where grab-and-go positioning commands shelf space premiums.
- Powder:Dehydrated mixes reduce logistics costs for export markets but require consumer reconstitution skill that limits penetration beyond home-baking enthusiasts.
- Liquid:Beverage-adjacent formats target on-the-go consumption but face formulation constraints maintaining viscosity without full-fat suspension systems.
Frozen formats command the steepest expansion trajectory in Asian convenience retail; powder concentrates in European home-prep segments.
Distribution Channel:
Channel selection determines certification requirements, pricing architecture, and ingredient disclosure depth.
- Health Food Stores:Specialized wellness retailers demand complete supply chain documentation and exclude synthetic stabilizers from assortment consideration. Per-unit economics exceed mainstream channels by 40-60% due to curation premiums and smaller case volumes.
- Supermarkets:Mainstream grocery placement requires slotting fee structures and promotional calendar alignment that favors scale manufacturers with national distribution infrastructure.
- Online Retail:Direct-to-consumer fulfillment enables subscription models for specialized diet segments but requires insulated packaging investment for temperature-sensitive formats.
- Convenience Stores:Limited refrigeration space restricts assortment to single-serve ready-to-eat formats with extended shelf life through ultra-high temperature processing.
Supermarkets anchor current volume; health food stores are climbing the fastest as procurement shifts toward provenance-verified sourcing.
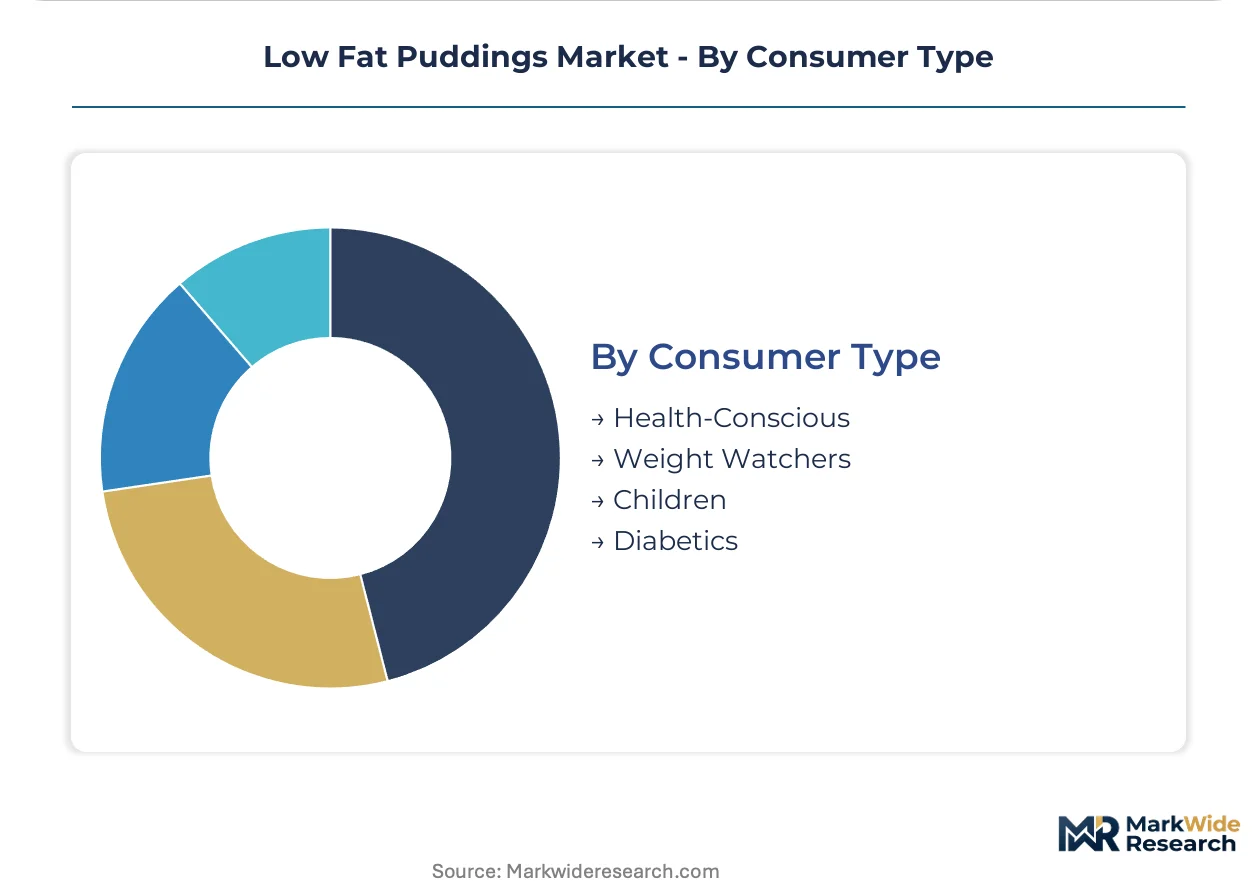
Consumer Type:
Dietary restriction severity and nutritional literacy shape formulation complexity and label communication strategies.
- Health-Conscious:Flexitarian buyers prioritize clean-label ingredient lists over absolute calorie minimization, accepting modest fat content for recognizable stabilizer systems.
- Weight Watchers:Calorie-accounting consumers demand precise portion control and front-of-pack numerical transparency that conflicts with European packaging aesthetic preferences.
- Children:Pediatric-oriented formulations face dual constraints from FDA nutrition labeling requirements for added sugars and parent purchasing skepticism toward artificial colorants.
- Diabetics:Glycemic management needs force simultaneous fat and carbohydrate reduction that degrades texture without advanced emulsion engineering or alternative sweetener systems.
Health-conscious buyers dominate current volume; diabetic-targeted formulations show the steepest R&D investment intensity as dual-nutrient reformulation capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling rules and EFSA health claim frameworks are accelerating reformulation investments across major dairy dessert markets. Clean-label mandates from these regulators reshape permissible fat-content thresholds and front-of-pack communication strategies.
United States
Refrigerated and frozen dessert consumption patterns anchor volume demand through mainstream grocery and club channels. FDA nutrition labeling requirements for added sugars constrain pediatric-oriented formulation strategies. Metropolitan retail clusters in the Northeast and California drive clean-label procurement shifts toward provenance-verified sourcing.
Germany
Premium organic low-fat pudding segments remain underpenetrated relative to conventional dairy dessert maturity. EFSA health claim regulations enable front-of-pack fat reduction messaging that drives consumer trial. Bavaria and North Rhine-Westphalia host accelerated adoption of microfluidization homogenization systems among private-label manufacturers.
Japan
Metropolitan wellness retail clusters exhibit the most pronounced certification-driven preference compression. METI standards and consumer labeling requirements shape permissible formulation claims. Tokyo and Osaka convenience store freezer placement anchors frozen format volume through impulse purchase occasions.
United Kingdom
Health food store channel expansion concentrates in London and Southeast England with specialized wellness retailers curating allergen-free assortments. FSA guidance on clean-label stabilizers pressures manufacturers to abandon synthetic alternatives. Midlands manufacturing bases face compressed capital deployment timelines for EU F-Gas Regulation compliance.
France
Chocolate-intensive reduced-fat formulations face disproportionate exposure due to temperature-sensitive cocoa butter crystallization requirements. ANSM oversight of functional ingredient claims constrains probiotic-infused pudding positioning. Île-de-France retail networks prioritize supply chain transparency documentation over traditional slotting-fee negotiations.
Low Fat Puddings Market Competitive Landscape
On the supply side, the industry is consolidating around global dairy conglomerates with captive protein supply networks and specialized wellness-oriented challengers with clean-label credentials. Three strategic archetypes dominate: scale-driven multinationals leveraging global dairy supply networks, functional wellness specialists merging digestive health claims with fat reduction, and private-label manufacturers capturing retailer-owned brand contracts. Dominant competitive moves include asset-light co-manufacturing partnerships that outsource production while retaining formulation control, and accelerated refrigeration infrastructure upgrades to maintain freezer-aisle placement under tightening environmental regulations.
Among the scale-driven multinationals, Nestle leverages its global dairy supply network to secure consistent milk protein inputs, while Danone anchors its position through probiotic-infused pudding variants. Kraft Heinz occupies a distinct position via private-label manufacturing contracts that supply retailer-owned low-fat dessert brands. These three players exemplify the competitive tension between captive supply chain control and outsourced production flexibility reshaping margin structures across refrigerated and frozen pudding lines.
| Leading Market Players |
|---|
| Nestle |
| Danone |
| Unilever |
| Kraft Heinz |
| Mondelez International |
| General Mills |
| The Hershey Company |
| Breyers |
| Yasso |
| Others |
Value Network & Pricing Analysis
Overcapacity in European dairy processing facilities is compressing ingredient margins and forcing suppliers toward volume-commitment contracts that lock in pricing stability for reformulated pudding lines. This utilization dynamic rewards manufacturers with captive milk protein supply while squeezing asset-light brands dependent on spot-market stabilizer procurement.
Pricing Analysis
Certification level creates the primary spread across low fat pudding tiers, with USDA Organic and Non-GMO Project verification commanding 40-60% premiums over conventional formulations. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label ingredient depth and cold-chain investment intensity. Cost compression in mid-tier private-label segments is intensifying because retailer procurement teams are consolidating supplier rosters. Health-conscious flexitarian buyers show lowest price sensitivity, while weight-watchers in club channels resist premiums beyond single-digit percentage spreads.
Supply Chain Analysis
Co-manufacturing concentration among German and Japanese dairy processors holds roughly half of specialized reduced-fat pudding capacity, with Nestle and Danone retaining in-house production for probiotic-infused lines. Milk protein isolates, natural stabilizer systems, and temperature-controlled packaging constitute the critical input trinity. Single-source vulnerability runs through concentrated natural stabilizer suppliers in Southern Europe. Distribution runs through refrigerated and frozen logistics networks subject to EU F-Gas Regulation compliance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as health food store procurement shifts disaggregate demand across dozens of clean-label specialists rather than consolidating around three national brands. This demand-side splintering creates defendable niches for formulation-focused challengers.
For Market Incumbents: Pre-empt private-label erosion by securing exclusive organic milk supply contracts in Bavaria and California before retailer-owned brands capture shelf space. Accelerate microfluidization homogenization deployment to maintain texture advantages as oat-based substitutes improve mouthfeel parity. Backward integration into natural stabilizer cultivation hedges against 15-40% ingredient cost inflation from clean-label mandates.
For New Entrants and Emerging Players: Germany's premium organic segment offers the most penetrable white space, with underdeveloped challenger presence relative to conventional dairy dessert saturation. Health food store channels in Tokyo and London accept smaller case volumes with 40-60% per-unit economics premiums. Direct-to-subscription models bypass slotting-fee barriers while building provenance documentation that satisfies wellness retailer procurement committees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across frozen format manufacturing as EU F-Gas Regulation compliance forces refrigeration infrastructure replacement. Five-to-ten year viability favors asset-light co-manufacturing specialists with established clean-label credentials over legacy synthetic-stabilizer dependent operators. Watch for accelerated adoption curves in diabetic-targeted dual-nutrient formulations as signal of advanced emulsion engineering capability maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Natural stabilizer sourcing agreements with USDA-certified suppliers secure health food store placement. |
| Microfluidization Capacity Investment | Sub-micron homogenization systems replicate full-fat mouthfeel at 30-50% reduced butterfat content. |
| Organic Certification Acceleration | USDA National Organic Program verification compresses 8-14 month timelines to capture shelf space. |
| Probiotic Infusion R&D | Functional ingredient convergence merges digestive health claims with reduced-fat positioning. |
| Health Food Store Channel Expansion | Specialized wellness retailers curate allergen-free assortments with superior per-unit economics. |
Research Methodology
Initial hypotheses were tested against primary input from dairy processing plant managers, health food store category buyers, refrigerated logistics operators, and clean-label ingredient procurement leads and refined through secondary validation. FDA nutrition labeling databases, EFSA health claim registers, USDA National Organic Program certification records, and EU F-Gas Regulation compliance filings anchored quantitative baselines. Bottom-up volume triangulation across form, flavor, and channel segments converged with top-down value estimates from trade flow analysis.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, form, distribution channel, and consumer dietary restriction severity. CAGRs were derived from fitted growth curves applied to channel-specific adoption rates and reformulation investment cycles. Milk protein input cost volatility and clean-label stabilizer supply expansion curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based dessert specialists or accelerated FDA sugar-reduction mandates would shift outcomes beyond modeled ranges. Quarterly review of health food store procurement documentation requirements and EU F-Gas Regulation infrastructure deployment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Europe Egg Powder Market
Processed Foods
North America Ice Cream Market
Processed Foods
Broth Market
Processed Foods
Potato Soup Market
Processed Foods
Soup Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Processed Peanut Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Processed Cashew Market
Processed Foods
Processed Beef Market
Processed Foods
United States Ice Cream Market
Processed Foods
Europe Soup Market
Processed Foods
Spreadable Fats Market
Processed Foods
Margarine Market