
 Romania Renewable Energy Market | 2026-2036
Romania Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Renewable Energy Market Outlook
Multi-source procurement from domestic and cross-border developers is expanding across Romania's renewable energy landscape. Hidroelectrica leverages its legacy hydropower portfolio to anchor baseload supply contracts. Enel Green Power Romania competes through distributed solar installations targeting commercial rooftops. CEZ controls significant wind capacity in the Dobrogea region, sustaining its position through operational scale.
Romania renewable energy encompasses electricity generation systems converting solar irradiance, wind kinetic energy, biomass organic matter, and hydropower potential into grid-deliverable power, with utility-scale photovoltaic plants typically deploying monocrystalline silicon modules exceeding 500 Wp per panel and onshore wind turbines rated between 2.5 MW and 4.5 MW. The technology dimension shows hydropower occupying mature baseload status while solar and wind capture expansion capital. End-user segmentation reveals industrial offtakers driving volume through corporate renewable power purchase agreements. Installation-type dynamics favor on-grid configurations given Romania's grid interconnection with ENTSO-E, though hybrid systems are gaining traction for industrial self-consumption.
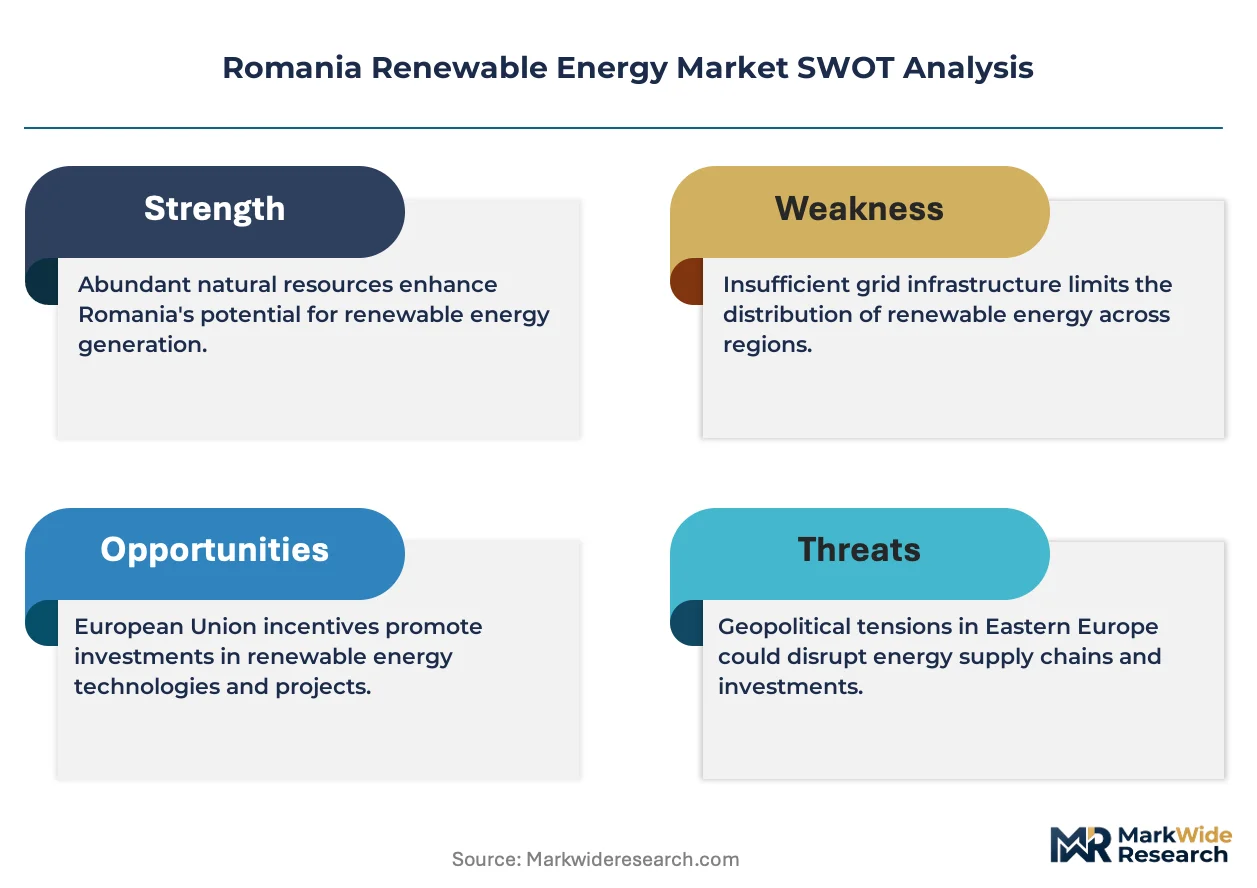
Romania's energy regulator ANRE implements feed-in tariff mechanisms and grid connection priority rules shaped by EU Renewable Energy Directive transposition. The country's national climate law and Recovery and Resilience Plan disbursement frameworks condition project finance access and permitting timelines. Stakeholders must monitor auction schedule density and grid reinforcement commitments to align development pipelines with offtake certainty.
Market Dynamics
Corporate power purchase agreements from automotive and food processing sectors are pulling project development toward industrial clusters, compressing offtake timelines and reshaping where developers site capacity. This demand concentration is forcing grid planners to accelerate reinforcement schedules in the Dobrogea wind belt and Banat solar corridor.
Growth Catalysts
- National Recovery and Resilience Plan funding:The disbursement framework conditions project finance access on accelerated permitting timelines, compressing development cycles for utility-scale solar and wind installations.
- Industrial offtaker demand:Automotive and food processing buyers are scaling corporate renewable power purchase agreements, creating volume anchors that de-risk capital commitments for developers.
- Monocrystalline silicon module efficiency gains:Panels exceeding 500 Wp per unit are reducing land-use intensity for utility-scale photovoltaic plants in the western Banat solar corridor.
Market Restraints
- Grid connection queue congestion:ANRE's priority rules create bottlenecks for projects in the Dobrogea wind belt where transmission reinforcement lags behind generation capacity additions.
- Land-use competition with agriculture:Prime solar sites in western Romania overlap with intensive farming zones, triggering zoning disputes that extend permitting timelines.
- Balancing cost volatility:Intermittency from wind and solar expansion increases ancillary service charges that erode project economics for merchant-exposed developers.
Strategic Opportunities
- Hybrid system deployment:Co-located solar-plus-storage configurations targeting industrial self-consumption are opening revenue streams outside regulated tariff structures.
- Biomass organic matter valorization:Agricultural residue supply chains in southern Romania remain underdeveloped relative to available feedstock volumes.
- Cross-border offtake to Hungary:Grid interconnection capacity with ENTSO-E neighbors creates arbitrage potential for Romanian renewable certificates.
Industry Challenges
- Grid code compliance engineering:ENTSO-E connection standards require specialized inverter configuration expertise that remains scarce in the Romanian labor market.
- Permitting timeline unpredictability:Environmental impact assessments for projects near Natura 2000 sites face review backlogs that destabilize construction scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Renewable Energy Market |
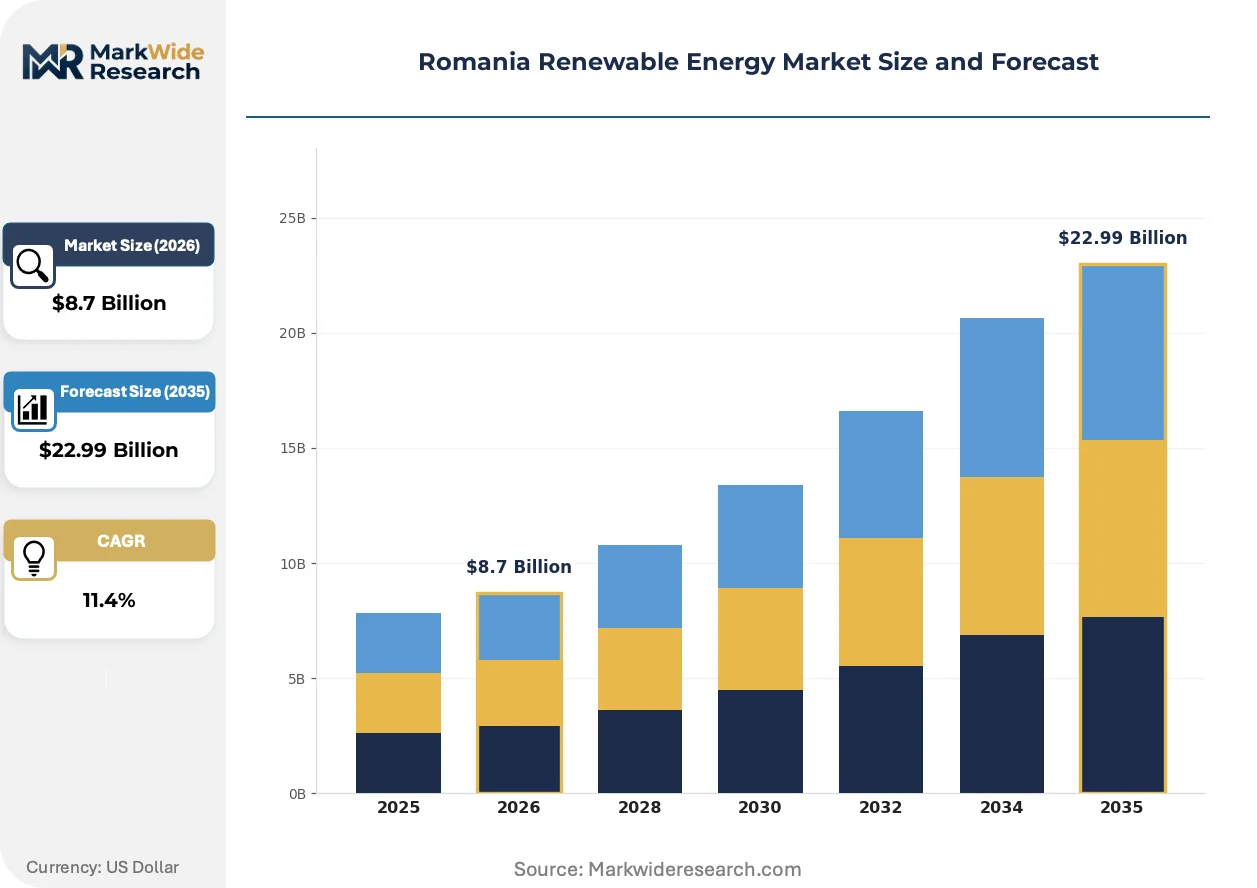
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower End User: Residential, Commercial, Industrial, Government Installation Type: On-grid, Off-grid, Hybrid, Distributed Service Type: Consulting, Equipment Supply, Maintenance, Financing |
| Companies Covered | Hidroelectrica, Enel Green Power Romania, Energias de Portugal, OMV Petrom, Enery, Siemens Gamesa Renewable Energy, CEZ, EDP Renewables, Rezolv Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Renewable Energy Market Strategic Shifts
Distributed generation architectures are fragmenting the traditional utility-centric model, creating new competitive arenas for equipment suppliers and service providers. Technology convergence and procurement evolution are compressing established value chain boundaries.
String inverter technology paired with module-level power electronics is decentralizing fault isolation and performance optimization in commercial rooftop installations. Mid-sized manufacturing facilities in Cluj-Napoca and Timișoara are adopting these configurations to bypass grid connection delays. This architecture is decentralizing maintenance accountability from central utility operators toward building facility managers.
ANRE's transposition of the EU Renewable Energy Directive into national auction schedules is mandating technology-neutral competitive bidding for new capacity allocations. Industrial offtakers are leveraging this framework to secure long-term price hedges through direct PPA structures. Solar developers in the Banat corridor are responding by optimizing project configurations for merchant price exposure rather than tariff dependency.
Aggregated procurement consortia among food processing cooperatives are displacing single-buyer bilateral contracting for renewable supply. These buyer pools concentrate volume commitments that attract developer attention and improve term negotiations. The pattern is most visible in southern Romania where agricultural processing clusters coordinate seasonal energy demand profiles.
Romania Renewable Energy Market Segmentation
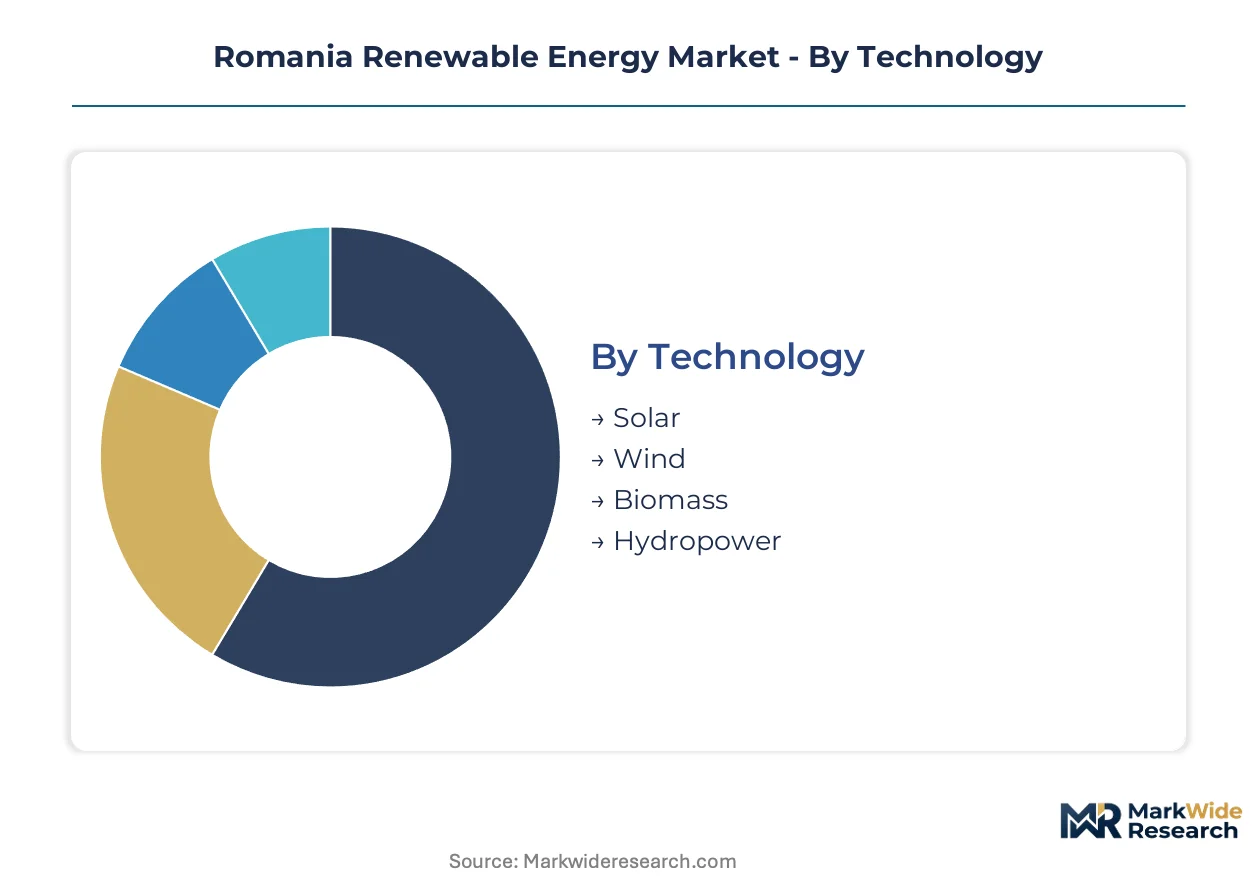
Technology choice determines project economics and regulatory access across Romania's renewable landscape. End-user profiles and installation configurations further condition capital deployment patterns and service requirements.
Technology:
Standardized utility-scale designs dominate solar and wind, while hydropower and biomass require site-specific engineering adaptation.
- Solar:Monocrystalline silicon modules exceeding 500 Wp per panel reduce land-use intensity for utility-scale plants. Demand concentrates in the western Banat solar corridor where industrial offtakers from automotive and food processing sectors anchor corporate power purchase agreements.
- Wind:Onshore turbines rated between 2.5 MW and 4.5 MW characterize the Dobrogea wind belt installations. CEZ and other developers target this region despite grid connection queue congestion from ANRE priority rules.
- Biomass:Agricultural residue supply chains in southern Romania remain underdeveloped relative to available feedstock volumes from intensive farming zones.
- Hydropower:Hidroelectrica leverages legacy baseload assets for supply contract anchoring, with mature assets requiring refurbishment rather than greenfield development.
Most installed capacity flows through Hydropower. Expansion is steepest in Solar.
End User:
Volume scale and contract duration separate industrial buyers from fragmented residential demand.
- Industrial:Automotive manufacturers and food processing cooperatives scale corporate renewable power purchase agreements, creating volume anchors that de-risk developer capital commitments and compress offtake timelines.
- Commercial:Mid-sized manufacturing facilities in Cluj-Napoca and Timișoara adopt distributed solar configurations to bypass grid connection delays through self-consumption architectures.
- Residential:Individual household installations remain limited by financing access and net metering policy uncertainty under ANRE frameworks.
- Government:Public sector procurement channels National Recovery and Resilience Plan funding into municipal infrastructure and administrative building retrofits.
Industrial offtakers command the largest aggregate contract values. Commercial adoption is climbing the fastest as rooftop economics improve.
Installation Type:
Grid interconnection availability and regulatory tariff structures determine configuration choice.
- On-grid:Utility-scale solar and wind plants interconnect with Romania's ENTSO-E synchronized network, accessing feed-in tariff mechanisms and auction-scheduled capacity allocations.
- Hybrid:Solar-plus-storage configurations target industrial self-consumption outside regulated tariff structures, opening merchant revenue streams for developers in grid-constrained zones.
- Distributed:Commercial rooftop installations fragment accountability toward building facility managers through string inverter and module-level power electronics architectures.
- Off-grid:Remote agricultural and industrial sites in mountainous or delta regions deploy standalone systems where transmission extension costs exceed generation asset investment.
On-grid configurations absorb the majority of capital deployment. Hybrid systems are gaining share fastest as battery cost curves improve.
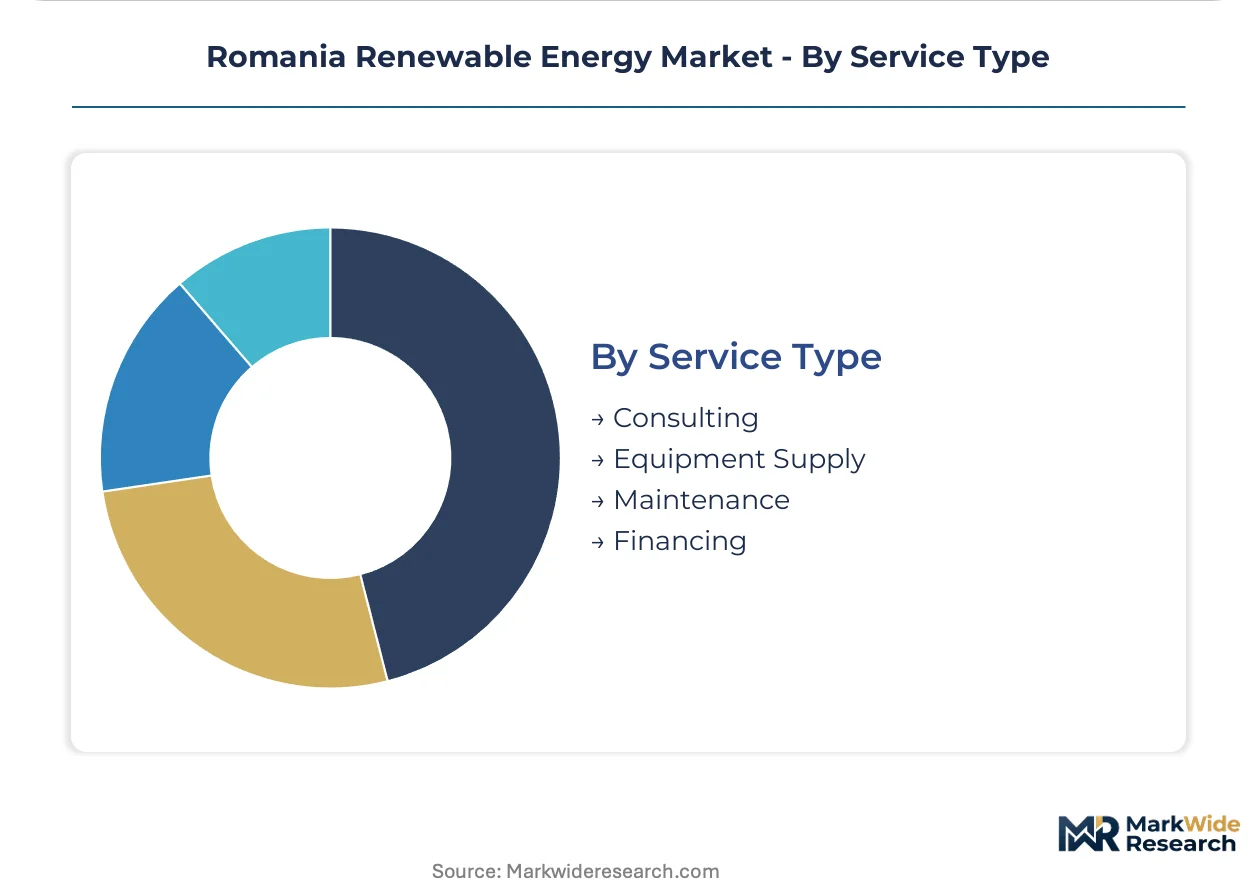
Service Type:
Margin structure and customer relationship intensity vary sharply across the service value chain.
- Equipment Supply:Module and turbine vendors compete on efficiency specifications and delivery timelines, with monocrystalline silicon technology and 4+ MW wind turbines commanding premium positioning.
- Financing:Project finance access conditions on National Recovery and Resilience Plan disbursement frameworks and accelerated permitting timelines, structuring non-recourse debt for utility-scale developments.
- Consulting:Environmental impact assessment and grid code compliance engineering face labor market scarcity for ENTSO-E connection standard expertise.
- Maintenance:Decentralized fault isolation through module-level power electronics shifts service accountability from central utility operators toward distributed asset managers.
Equipment Supply captures the largest revenue pool. Financing services are expanding most quickly as institutional capital flows accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting renewable energy investment toward jurisdictions with streamlined permitting and grid access protocols. Romania's National Recovery and Resilience Plan disbursement framework compresses development cycles relative to neighboring markets, attracting cross-border capital from developers facing slower administrative timelines elsewhere.
Dobrogea Wind Belt
Onshore wind installations concentrate in southeastern Romania where turbine density exceeds grid reinforcement capacity. ANRE priority rules create connection queue congestion that extends project commissioning timelines. CEZ and EDP Renewables anchor development portfolios in Constanța and Tulcea counties despite transmission bottlenecks.
Banat Solar Corridor
Utility-scale photovoltaic deployment clusters in western Romania near Timișoara and Arad industrial zones. Automotive manufacturers from Reșița and food processing cooperatives anchor corporate power purchase agreements. Land-use competition with intensive agriculture triggers zoning disputes that extend environmental permitting.
Transylvania Distributed Generation
Commercial rooftop solar adoption accelerates in Cluj-Napoca and Brașov manufacturing corridors. Mid-sized facilities deploy string inverter architectures to bypass grid connection delays through self-consumption models. Module-level power electronics decentralize maintenance accountability toward facility managers.
Southern Agricultural Biomass Zone
Agricultural residue supply chains remain underdeveloped across Călărași and Ialomița counties despite available feedstock volumes. Organic matter valorization projects face fragmented collection logistics and seasonal supply variability. Hidroelectrica evaluates co-firing opportunities at legacy hydropower-adjacent facilities.
Danube Delta Off-Grid Applications
Remote sites in Tulcea and Brăila deploy standalone renewable systems where transmission extension costs exceed generation asset investment. Tourism and fishing cooperatives adopt solar-plus-storage configurations outside regulated tariff structures. Hybrid architectures open merchant revenue streams in grid-constrained zones.
Romania Renewable Energy Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid system specialization and distributed generation niches. The Romanian market structures around three archetypes: legacy state-backed hydropower incumbents, international utility-scale developers with regional portfolios, and domestic mid-cap specialists targeting industrial self-consumption. Consolidation pressure concentrates among wind asset holders in Dobrogea where grid constraints favor operational scale. Strategic moves center on portfolio diversification into solar-plus-storage configurations and corporate PPA origination capabilities.
Among state-affiliated energy groups, Hidroelectrica anchors baseload supply contracts through legacy hydropower assets. International developers Enel Green Power Romania and CEZ exemplify the utility-scale archetype with distributed solar and concentrated wind portfolios respectively. Rezolv Energy occupies a position within the emerging specialist tier targeting hybrid system deployment for industrial offtakers.
| Leading Market Players |
|---|
| Hidroelectrica |
| Enel Green Power Romania |
| Energias de Portugal |
| OMV Petrom |
| Enery |
| Siemens Gamesa Renewable Energy |
| CEZ |
| EDP Renewables |
| Rezolv Energy |
| Others |
Value Chain & Pricing Dynamics
Polysilicon spot price indices from BloombergNEF cascade through Romanian solar project economics, compressing developer margins when silicon feedstock costs spike and enabling aggressive tariff underbidding when polysilicon gluts emerge. This commodity volatility stratifies project returns across the Banat solar corridor, where land-use competition with agriculture forces developers to absorb input cost swings rather than pass them to industrial offtakers.
Pricing Analysis
Input-cost pass-through from module and turbine suppliers drives contract pricing volatility for Romanian renewable developers. Long-term power purchase agreements with automotive and food processing buyers anchor revenue stability, while merchant-exposed projects face price erosion from balancing cost volatility and grid code compliance engineering premiums. Price differentiation hinges on certification tier—projects with EU Green Deal alignment command premium terms—and volume scale, with aggregated procurement consortia securing tighter pricing. Industrial offtakers exhibit lowest price sensitivity due to carbon accounting requirements, whereas commercial rooftop adopters in Cluj-Napoca and Timișoara face acute budget constraints from self-financed installations.
Supply Chain Analysis
CE marking and ENTSO-E grid code certification gate equipment supply for Romanian renewable projects, filtering out non-compliant module and inverter vendors. Manufacturing concentration in China, Vietnam, and Malaysia for monocrystalline silicon modules and power electronics creates single-source vulnerability when geopolitical disruptions constrain container shipping through Suez corridors. Raw material dependencies on polysilicon, rare earth magnets for turbine generators, and lithium-ion cells for hybrid storage configurations expose developers to commodity price swings. Distribution runs through EPC contractors with Romanian execution capability, who bundle equipment procurement with construction management for utility-scale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's National Recovery and Resilience Plan disbursement timelines offer 12-18 month regulatory arbitrage against Hungarian and Bulgarian permitting delays, attracting cross-border developer capital seeking faster project commissioning windows.
For Market Incumbents: Extend operational scale advantages in the Dobrogea wind belt by securing early-mover grid connection priority through ANRE queue positioning before transmission reinforcement bottlenecks worsen. Consolidate fragmented commercial rooftop service capabilities in Transylvania to defend against emerging distributed generation specialists. Backward integration into battery storage system assembly hedges hybrid project margin compression from imported lithium-ion cell price volatility. For New Entrants and Emerging Players: Enter via agricultural residue supply chain aggregation in Călărași and Ialomița counties, where biomass organic matter valorization remains structurally underdeveloped relative to available feedstock volumes. Target industrial self-consumption configurations for food processing cooperatives with seasonal demand profiles, bypassing grid connection delays through solar-plus-storage architectures. Partner with Romanian EPC contractors lacking in-house storage integration expertise to accelerate market penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid system developers possessing corporate PPA origination capabilities and grid-constrained zone project pipelines. Long-term viability centers on portfolios with merchant price exposure hedging and storage co-location economics. Watch ANRE auction schedule density and grid reinforcement commitment announcements as inflection indicators for construction timeline certainty.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate PPA Origination | Industrial offtaker demand from automotive manufacturers anchors developer capital commitments. |
| Hybrid System Deployment | Solar-plus-storage configurations open merchant revenue streams outside ANRE tariff structures. |
| Grid Connection Priority Securing | ANRE queue positioning determines project commissioning timelines in Dobrogea wind belt. |
| Agricultural Residue Supply Chain | Biomass feedstock aggregation in southern Romania addresses valorization infrastructure gaps. |
| Cross-Border Certificate Arbitrage | ENTSO-E interconnection enables Hungarian offtake for Romanian renewable certificate trading. |
Study Parameters
Direct dialogue with IPP project developers, EPC contractors, utility planning officers at Transelectrica, and industrial energy procurement managers grounded qualitative findings in execution realities across Romania's renewable landscape. Secondary validation drew from ANRE auction disclosure databases, ENTSO-E ten-year network development plans, EU Recovery and Resilience Facility disbursement tracking, and corporate PPA announcement registries. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated against stakeholder interview consensus.
Market sizing outputs reflect capacity installation forecasts across technology, end-user, and installation-type dimensions over the projection horizon, with CAGRs derived from regression analysis of historical deployment rates against policy incentive trajectories. Segmentation modeling incorporated fuel source, generation capacity tier, regulatory framework, and regional grid type variations. Key inputs included polysilicon price forward curves, grid reinforcement commitment schedules, and industrial electricity demand projections from automotive and food processing sectors.
Inputs from ANRE regulatory filings and ENTSO-E network planning documents were available through the study window; gaps in real-time grid connection queue depth data introduce uncertainty bands around project commissioning timeline assumptions. Forecasts reflect documented permitting acceleration assumptions under National Recovery and Resilience Plan frameworks. A model refresh is warranted upon material change in EU renewable energy directive transposition timelines or grid code compliance engineering labor market conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Marine Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Hybrid Power System Market