
 In-Pipe Hydroelectric System Market | 2026-2036
In-Pipe Hydroelectric System Market Size, Share, and Industry Trends Forecast 2026-2036
In-Pipe Hydroelectric System Market Insights
Performance-based maintenance contracts is restructuring how vendors monetize in-pipe installations, shifting revenue from hardware sales to recurring service agreements. Rentricity Inc. leverages its early mover position in North American municipal contracts. Natel Energy Inc. sustains technology leadership through its fish-safe turbine architecture. Lucid Energy Inc. anchors project development capabilities across Pacific Northwest water districts.
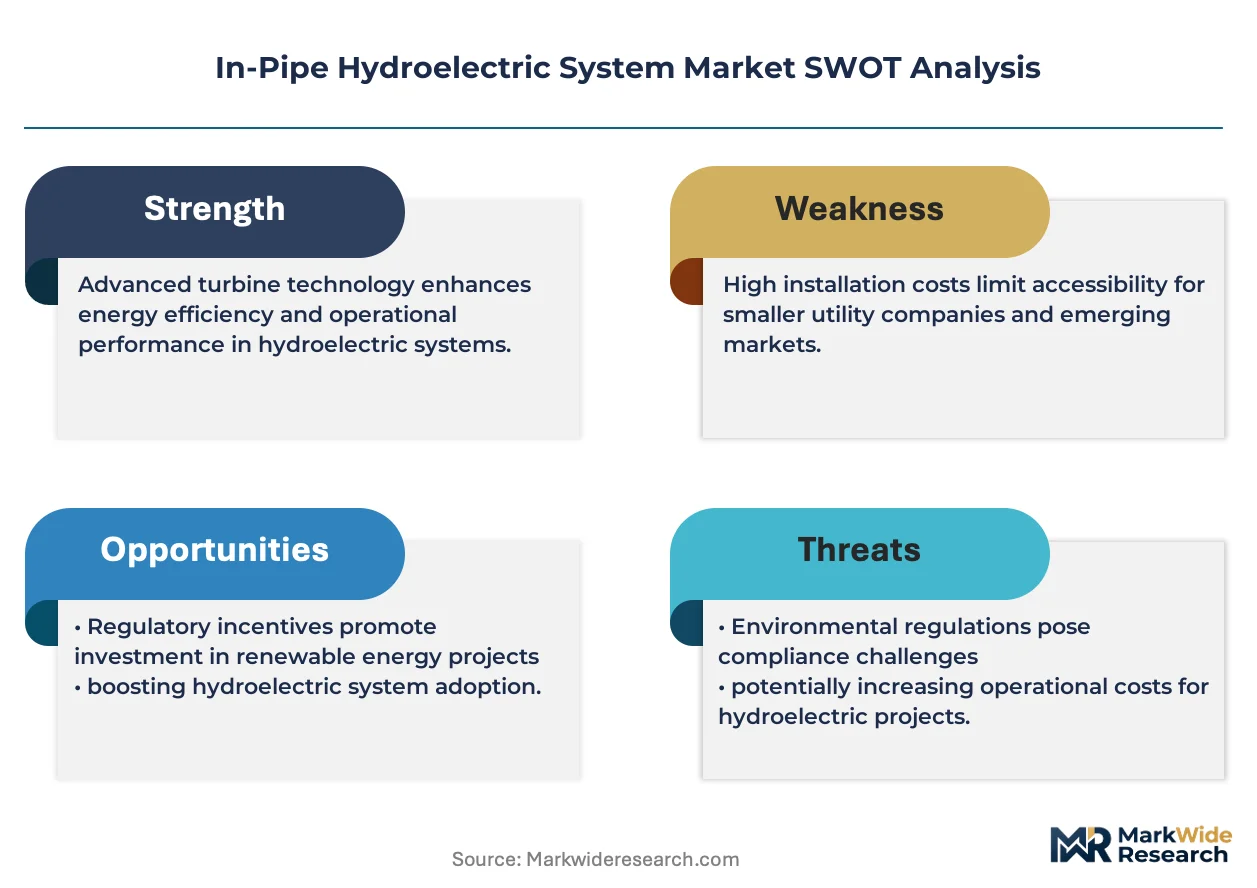
An in-pipe hydroelectric system harvests kinetic energy from pressurized water flowing through existing pipelines, typically generating 1-100 kW per installation via compact reaction or impulse turbines without disrupting supply operations. Municipal Water Supply applications command the largest installed base due to predictable flow regimes and utility-scale procurement processes, while Industrial Processes segments offer the fastest expansion trajectory as food and chemical plants seek captive renewable generation. Retrofit installations dominate current revenue as aging pipeline infrastructure across developed markets creates embedded deployment opportunities.
The U.S. EPA and state-level public utility commissions shape product certification requirements and interconnection standards for distributed pipeline generation. The EU Green Deal and F-Gas Regulation indirectly steer investment toward water-sector energy efficiency retrofits. Stakeholders must monitor evolving net metering rules and pipeline safety codes that determine where turbine insertion remains permissible.
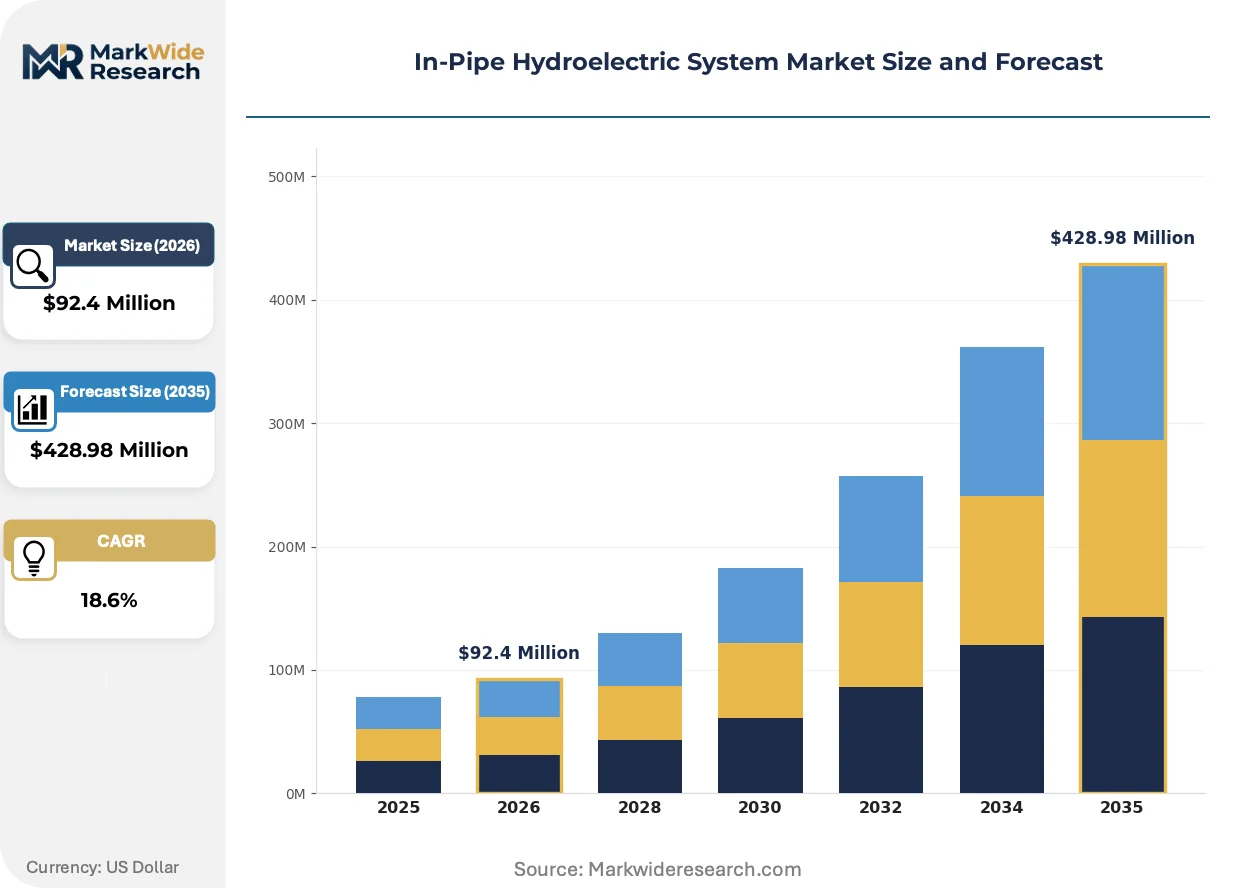
Market Dynamics
Performance-based maintenance contracts are restructuring vendor economics in the in-pipe hydroelectric system market, displacing upfront hardware sales with recurring revenue streams tied to energy output guarantees.
Growth Catalysts
- EPA Water Infrastructure Mandates:The U.S. Environmental Protection Agency's energy efficiency directives for municipal water systems create procurement pressure for distributed generation retrofits.
- California Water District Stress:Drought-driven electricity cost spikes in California's municipal water utilities accelerate turbine deployment in high-pressure transmission lines.
- Compact Reaction Turbines:Advances in fish-safe, low-head turbine architectures expand deployable pipeline pressure ranges without flow disruption.
Market Restraints
- Stainless Steel Input Volatility:Turbine housing fabrication depends on specialty steel grades subject to commodity price swings and supply chain bottlenecks.
- Pipeline Safety Code Friction:Municipal water codes in multiple U.S. states restrict mechanical insertions in potable water lines pending case-by-case waivers.
- Pump-Storage Substitution:Grid-scale battery installations and pumped hydro projects compete for utility renewable energy procurement budgets.
Strategic Opportunities
- Industrial Process Heat Recovery:Food processing and chemical plants with captive high-pressure water loops represent untapped captive generation demand.
- EU Green Deal Tailwinds:The European Union's water-sector energy efficiency retrofit incentives open procurement channels in Germany, Netherlands, and Denmark.
- Smart Grid Convergence:Integration of in-pipe generation data with SCADA and AMI platforms creates bundled service offerings for utility buyers.
Industry Challenges
- Certification Timeline Compression:NSF/ANSI 61 potable water contact certification and FERC small hydro exemptions create multi-month approval bottlenecks.
- Legacy SCADA Integration Complexity:Municipal water utilities operate heterogeneous control systems requiring custom protocol bridges for turbine monitoring.
- Specialized Technician Scarcity:Deployment and maintenance demand cross-trained crews fluent in both hydropower mechanics and water utility operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Pipe Hydroelectric System Market |
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $428.98 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Impulse Turbine, Turgo Turbine, Pelton Wheel, Archimedes Screw Application: Municipal Water Supply, Irrigation Systems, Industrial Processes, Wastewater Treatment End User: Utilities, Commercial Buildings, Agricultural Sector, Public Institutions Installation Type: Retrofit, New Construction, Modular Systems, Hybrid Solutions |
| Companies Covered | Rentricity Inc., Lucid Energy Inc., Natel Energy Inc., Hydrospin Monitoring Solutions Ltd., HSI (Hydro Systems Inc.), Waterotor Energy Technologies Inc., Leviathan Energy, Xinda Green Energy Co. Limited, Tecnoturbines SL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Pipe Hydroelectric System Market Trends and Innovations
Digital twin modeling and predictive analytics are transforming how vendors guarantee turbine performance, shifting contractual risk from buyers to suppliers through real-time condition monitoring.
Computational fluid dynamics-optimized blade geometries are rewriting efficiency benchmarks for low-head, high-flow municipal applications. Water utilities in the Pacific Northwest are piloting these designs in 24-inch transmission mains. The technology is rewriting project finance structures by expanding bankable output ranges into previously marginal pressure regimes.
The EU F-Gas Regulation is accelerating refrigerant phase-out timelines that indirectly steer industrial cooling water loop operators toward energy efficiency retrofits including in-pipe generation. Chemical plants in the Netherlands face compliance-driven capex decisions that favor integrated renewable generation. Food processing facilities with high-pressure clean-in-place systems represent the fastest-adopting vertical under this regulatory pressure.
Energy-as-a-service contracting is displacing traditional equipment purchase models across North American municipal procurement. Water districts in California and Texas now request 10-year performance guarantees with zero upfront capital. This model concentrates vendor risk but locks in decade-long revenue streams and service dependencies.
In-Pipe Hydroelectric System Market Segmentation
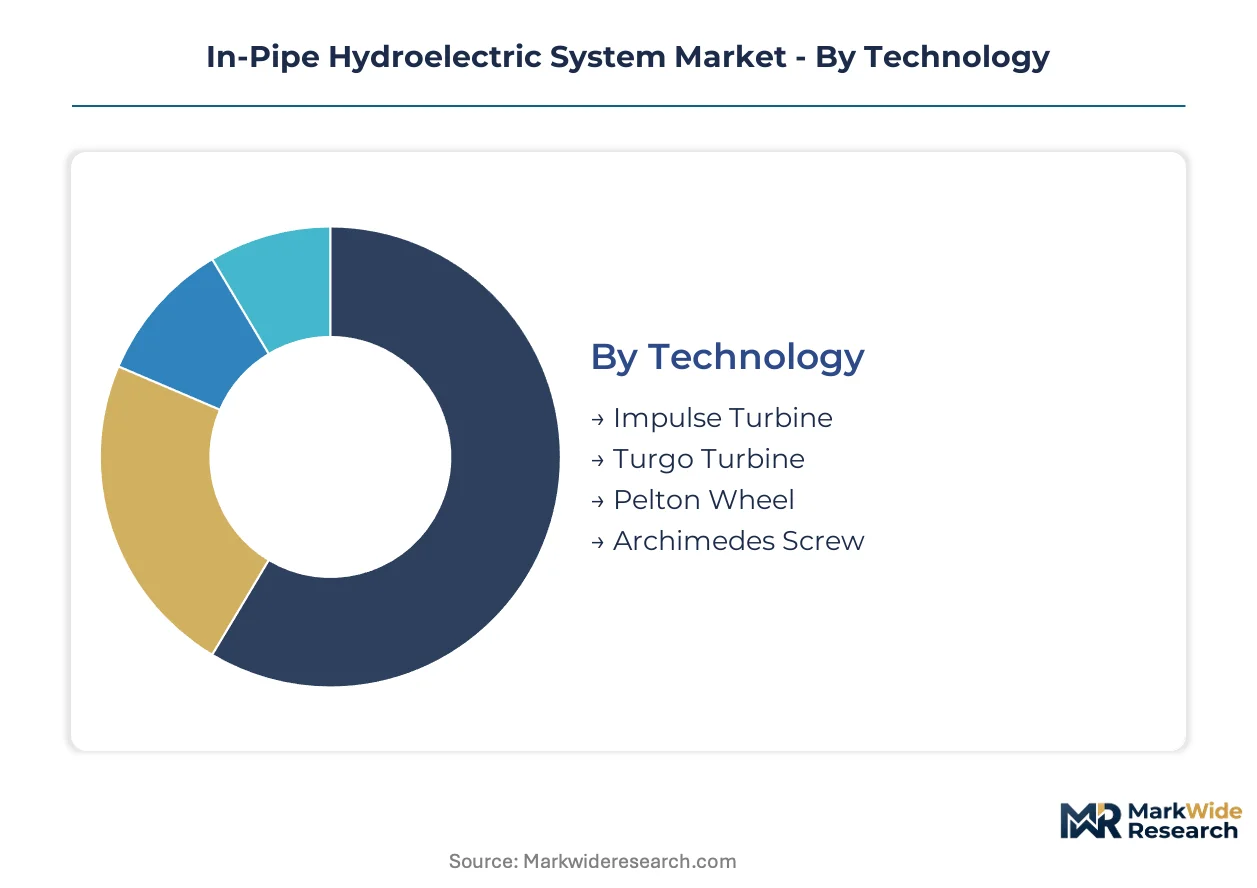
Technology selection determines turbine efficiency across varying pressure differentials and flow velocities. Application context dictates regulatory compliance requirements and procurement timelines. Understanding these segment boundaries clarifies where vendor capabilities align with buyer specifications.
Technology:
Turbine architecture defines extractable energy density and fish-safe operational thresholds.
- Impulse Turbine:High-velocity water jets strike bucket-shaped blades mounted on a rotating runner, optimizing performance in high-head, low-flow pipeline configurations. Municipal water utilities in California's Sierra Nevada foothills deploy these units where elevation drops exceed 50 meters, leveraging the EPA's energy efficiency mandates to secure project financing.
- Turgo Turbine:Inclined jet entry angles reduce runner diameter requirements while maintaining impulse efficiency, enabling compact installations in space-constrained vaults. Industrial process applications in Texas chemical plants favor Turgo designs for their reduced cavitation risk in intermittent-flow clean-in-place systems.
- Pelton Wheel:Double-cup buckets split water jets to balance axial thrust loads, extending bearing life in continuous-duty installations.
- Archimedes Screw:Open-trough helical blades rotate slowly with minimal fish mortality, satisfying FERC environmental review thresholds in Pacific Northwest salmon-bearing watersheds.
Impulse Turbine leads on scale; Turgo Turbine leads on momentum.
Application:
End-use environment shapes flow predictability and maintenance access economics.
- Municipal Water Supply:Predictable diurnal flow patterns in treated water transmission mains enable accurate output forecasting and long-term power purchase agreements. Water districts across Arizona, Colorado, and Nevada install in-pipe units at pressure-reducing valve stations, converting previously dissipated head into grid-exportable electricity under state renewable portfolio standards.
- Industrial Processes:Captive high-pressure loops in food processing and chemical manufacturing offer behind-the-meter generation with avoided transmission charges. Facilities in the Netherlands leverage EU Green Deal efficiency incentives to retrofit cooling water circuits, accelerating payback periods through combined heat and power integration.
- Irrigation Systems:Seasonal flow variability requires modular turbine sizing matched to crop cycle demands.
- Wastewater Treatment:Corrosive effluent chemistry demands specialized coatings and extended maintenance intervals.
Municipal Water Supply anchors installed capacity; Industrial Processes climbs fastest.
End User:
Procurement sophistication and capital availability diverge sharply across buyer categories.
- Utilities:Regulated water and electric utilities deploy in-pipe generation through integrated resource planning processes, securing FERC small hydro exemptions and state interconnection approvals. California's largest water wholesaler structures 20-year energy-as-a-service contracts that transfer operational risk to turbine vendors while retaining carbon offset claims.
- Commercial Buildings:High-rise developments in New York City and Chicago incorporate in-pipe units within municipal pressure zones, satisfying local building energy performance standards through on-site renewable generation.
- Agricultural Sector:Irrigation districts in California's Central Valley pilot cooperative ownership models to spread capital costs across multiple pumping cooperatives.
- Public Institutions:University campuses and military installations leverage federal sustainability mandates to justify demonstration projects.
Utilities dominate procurement volume; Commercial Buildings expand most quickly.
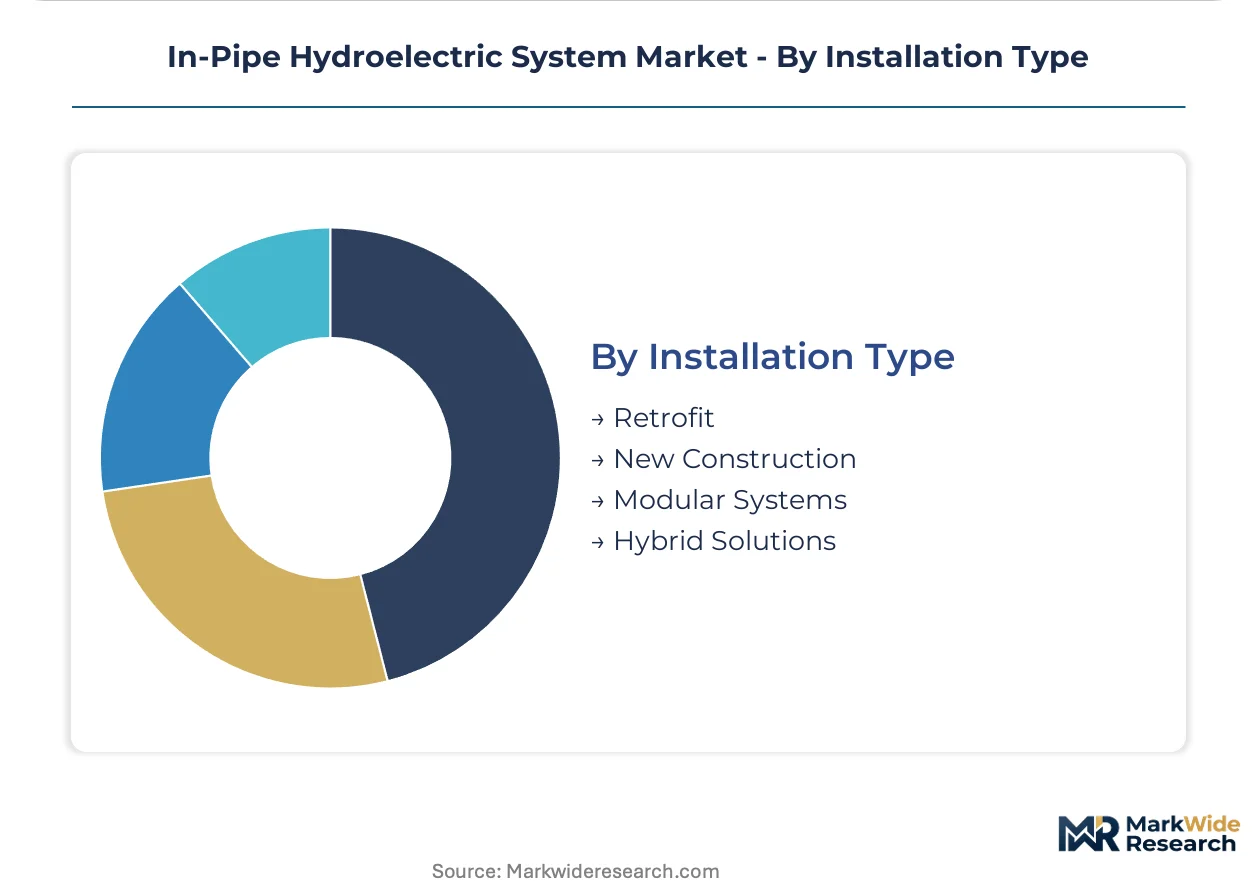
Installation Type:
Deployment context determines project complexity and revenue recognition timing.
- Retrofit:Insertion into existing pressure-reducing stations exploits embedded infrastructure without pipeline replacement, minimizing civil works costs. Aging cast-iron mains in the northeastern United States present targeted opportunities where structural integrity permits mechanical insertion without integrity testing delays.
- New Construction:Greenfield water treatment plants and transmission projects specify in-pipe generation during design phase, optimizing turbine sizing for anticipated flow regimes and integrating electrical interconnection from project inception.
- Modular Systems:Skid-mounted turbine packages reduce field assembly time for rapid deployment in emergency infrastructure projects.
- Hybrid Solutions:Battery-coupled installations buffer intermittent flow variations, stabilizing grid interconnection voltage profiles.
Retrofit commands current revenue; New Construction gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in installed in-pipe capacity, though Dutch industrial retrofits are closing the deployment gap through EU efficiency mandates.
United States
California water districts drive municipal procurement through drought-driven electricity cost spikes. The EPA's energy efficiency directives for water infrastructure accelerate FERC small hydro exemption filings. Pacific Northwest salmon-bearing watersheds pilot fish-safe Archimedes screw installations near Portland and Seattle.
Germany
Industrial cooling water loops in chemical plants offer captive generation opportunities under EU Green Deal retrofit incentives. The F-Gas Regulation accelerates refrigerant phase-out timelines that steer capital toward efficiency investments. Rhine-Ruhr industrial clusters deploy Turgo turbines in space-constrained clean-in-place systems.
Netherlands
Food processing facilities with high-pressure water circuits represent the fastest-adopting vertical segment. National water-sector efficiency programs subsidize turbine insertion at pressure-reducing stations. Rotterdam and Eindhoven chemical corridors integrate in-pipe generation with combined heat and power systems.
United Kingdom
Commercial high-rise developments in London incorporate in-pipe units within municipal pressure zones to satisfy building energy performance standards. The Environment Agency streamlines abstraction licensing for pipeline generation retrofits. Thames Water and regional utilities pilot energy-as-a-service contracts transferring operational risk to vendors.
Canada
Municipal water utilities in Ontario and British Columbia exploit aging cast-iron transmission mains for retrofit installations without pipeline replacement. Provincial renewable portfolio standards create procurement pressure for distributed generation. Vancouver and Toronto water districts structure long-term power purchase agreements around predictable diurnal flow patterns.
In-Pipe Hydroelectric System Market Competitive Landscape
Top-tier vendors anchor municipal utility contracts through performance guarantees, while mid-tier specialists pursue industrial process applications with compact turbine architectures. The market exhibits tiered consolidation around early movers with FERC certification experience and regional fabrication capabilities. Three archetypes dominate: full-service project developers, component-specialist fabricators, and energy-as-a-service operators. Competitive moves concentrate on strategic partnerships with water infrastructure contractors and technology licensing agreements for fish-safe blade geometries.
Within the North American project development tier, Rentricity Inc. and Lucid Energy Inc. exemplify full-service positioning through municipal contract concentration. Natel Energy Inc. occupies a technology-leadership archetype, representing the fish-safe turbine architecture segment. Xinda Green Energy Co. Limited anchors the Asia-Pacific fabrication vector, while Tecnoturbines SL exemplifies European specialist positioning in compact reaction turbine supply.
| Leading Market Players |
|---|
| Rentricity Inc. |
| Lucid Energy Inc. |
| Natel Energy Inc. |
| Hydrospin Monitoring Solutions Ltd. |
| HSI (Hydro Systems Inc.) |
| Waterotor Energy Technologies Inc. |
| Leviathan Energy |
| Xinda Green Energy Co. Limited |
| Tecnoturbines SL |
| Others |
Pricing and Supply Chain Analysis
Cross-trained hydropower-water utility technicians concentrated in Germany's Rhine-Ruhr corridor and California's Central Valley create labor-cost spreads that separate premium-tier turbine installations from economy retrofit offerings. EPA certification timelines and FERC exemption processing costs further stratify vendor pricing tiers across municipal procurement channels.
Pricing Analysis
Capacity additions in China's specialty steel forging sector are reshaping price floors for turbine housing fabrication, compressing margins for European and North American fabricators. Three-tier pricing structure across premium, standard, and economy levels reflects NSF/ANSI 61 certification grade and fish-safe blade geometry complexity. Pricing pressure stems from stainless steel commodity volatility and extended FERC approval timelines. Municipal water utilities exhibit highest price sensitivity due to constrained capital budgets, while industrial process buyers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Specialty stainless steel supply rests on German, Japanese, and Chinese metallurgical producers with ASME-certified forging capabilities. Precision bearing assemblies and fish-safe blade coatings draw from Swiss and Dutch specialty chemical manufacturers. Single-source vulnerability concentrates in FERC-certified turbine casting facilities with potable water contact approvals. Distribution runs through water infrastructure EPC contractors and direct municipal procurement channels with multi-year maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable revenue streams, with EPA energy efficiency mandates for water infrastructure creating procurement pull-through across drought-stressed U.S. water districts.
For Market Incumbents: Deploy performance-based contracting to lock in decade-long service dependencies and transfer operational risk from municipal buyers. Deepen backward integration into stainless steel forging to buffer commodity volatility exposure. Counter grid-scale battery substitution threats by emphasizing distributed generation's transmission charge avoidance and carbon offset verification. For New Entrants and Emerging Players: Digital channel partnerships with water infrastructure monitoring platforms offer low-friction customer acquisition routes. Industrial process heat recovery in Netherlands and Germany food processing corridors represents the most penetrable white space. Position around EU Green Deal compliance-driven capex decisions with turnkey retrofit packages and rapid NSF/ANSI 61 certification pathways. For Investors and Strategic Acquirers: Water utility infrastructure funds are the most active acquirer in this space, consolidating vendor portfolios to capture energy-as-a-service recurring revenue. Five-to-ten year viability hinges on FERC small hydro exemption processing efficiency and state net metering rule stability. Acquisition target archetype: mid-tier fabricators with existing potable water certifications and Pacific Northwest municipal contract concentration. Watch California Public Utilities Commission interconnection standard revisions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FERC Small Hydro Exemption Fast-Track | Compresses approval timelines from 18 months to 6 months for municipal utilities. |
| Performance-Based Maintenance Contracting | Locks Rentricity and Lucid Energy into 10-20 year recurring revenue streams. |
| Fish-Safe Turbine Architecture Licensing | Natel Energy monetizes salmon-bearing watershed deployment rights across Pacific Northwest. |
| EU Green Deal Retrofit Incentive Capture | Netherlands and Germany chemical plants accelerate turbine deployment for compliance. |
| SCADA-AMI Platform Integration | Creates bundled smart grid offerings for California and Texas water districts. |
Research Methodology
Multiple input streams — utility planning officer interviews, EPC contractor project databases, FERC exemption filings, and EPA water infrastructure grant disclosures — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged municipal water utility directors, industrial plant engineers, turbine OEM procurement leads, and aftermarket service heads across the United States, Germany, Netherlands, and Canada. Secondary validation drew from EIA distributed generation statistics, IEA water-sector energy efficiency reports, EU Green Deal implementation tracking, and customs records for stainless steel turbine component trade flows. Bottom-up project pipeline aggregation and top-down regulatory mandate sizing were cross-checked for triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include turbine architecture type, application environment, end-user procurement sophistication, and installation context. CAGRs were derived from fitted adoption curves against regulatory milestone timelines and utility capital expenditure cycle analysis. Industry-specific forecast inputs incorporated California drought-driven electricity cost trajectories and EU F-Gas Regulation compliance deadline clustering.
The model assumes a particular technology adoption path; alternative pathways for compact reaction turbine efficiency gains would alter the outlook. Forecasts reflect embedded assumptions around EPA mandate enforcement continuity and stainless steel price normalization. Regulatory rulemaking delays, pipeline safety code friction in additional U.S. states, and grid-scale battery cost breakthroughs constitute specific revision risks. A small set of triggers — FERC exemption processing time trends, California net metering rule changes, and EU Green Deal subsidy allocation rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Global Green Energy Market