
 Solar PV and Wind Energy Market | 2026-2036
Solar PV and Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV and Wind Energy Market Insights
Chinese polysilicon and wafer producers is recalibrating capacity expansion timelines after price volatility across the solar value chain. LONGi Green Energy leverages in-house ingot-to-module production to sustain margin capture through manufacturing scale. Vestas Wind Systems anchors European turbine supply with specialized offshore platform development. First Solar competes through thin-film cadmium telluride technology that differentiates its product from crystalline silicon alternatives.
Solar PV and wind energy systems convert electromagnetic radiation and kinetic atmospheric energy into grid-compatible electricity through photovoltaic cells and aerodynamic rotor assemblies, with utility-scale installations typically exceeding 5 MWac capacity and offshore wind turbines now surpassing 15 MW nameplate ratings. The technology dimension spans monocrystalline modules dominating utility-scale procurement, thin-film alternatives occupying distributed commercial rooftops where weight constraints apply, and vertical axis designs navigating niche urban environments. Application segmentation reveals utility-scale projects controlling capital deployment volumes while residential rooftop installations positions fastest penetration in markets with net metering frameworks.
The United States IRA production tax credit and investment tax credit structures shape project finance viability, while the EU Green Deal and F-Gas Regulation constrain refrigerant-intensive manufacturing processes. China's MIIT governs polysilicon capacity allocation and module efficiency standards through GB certification requirements. Stakeholders must monitor how divergent subsidy phase-out schedules across Washington, Brussels, and Beijing reshape competitive positioning for capital-intensive manufacturing investments.
Market Dynamics
Hybrid renewable procurement is compressing development timelines as utilities seek co-located solar and wind assets with shared grid infrastructure and single interconnection queues.
Growth Catalysts
- Production Tax Credit Extension:The IRA in the United States guarantees project finance viability for wind developers through 2032, stabilizing long-term revenue projections.
- Polysilicon Cost Collapse:Chinese wafer oversupply has driven module prices to historic lows, accelerating utility-scale deployment in price-sensitive emerging markets.
- Offshore Wind Lease Rounds:Coastal states in the United States and North Sea jurisdictions are auctioning seabed rights with accelerated permitting timelines.
Market Restraints
- Critical Mineral Concentration:Rare earth processing for permanent magnet generators concentrates in Chinese smelters, creating supply vulnerability for turbine manufacturers.
- Interconnection Queue Bottlenecks:Grid operators in the United States face multi-year backlogs for renewable project studies, delaying commercial operation dates.
- Interest Rate Sensitivity:Capital-intensive projects with 25-year power purchase agreements face margin compression when central bank rates elevate weighted average cost of capital.
Strategic Opportunities
- Agrivoltaics Expansion:Dual-use solar installations on agricultural land in Germany and France qualify for differentiated feed-in tariffs while preserving soil productivity.
- Floating Offshore Platforms:Deep-water wind technology unlocks capacity off the coast of Japan and California where fixed-bottom foundations prove uneconomical.
- Green Hydrogen offtake:Electrolyzer projects in India and Saudi Arabia are contracting dedicated renewable supply, creating new demand verticals outside wholesale electricity markets.
Industry Challenges
- High-Voltage Technician Shortage:Grid-scale inverter commissioning and substation construction face labor constraints as electrification demand competes for skilled electricians.
- Module Recycling Infrastructure:End-of-life crystalline silicon panels are accumulating faster than EU WEEE directive compliance infrastructure can process, creating liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV and Wind Energy Market |
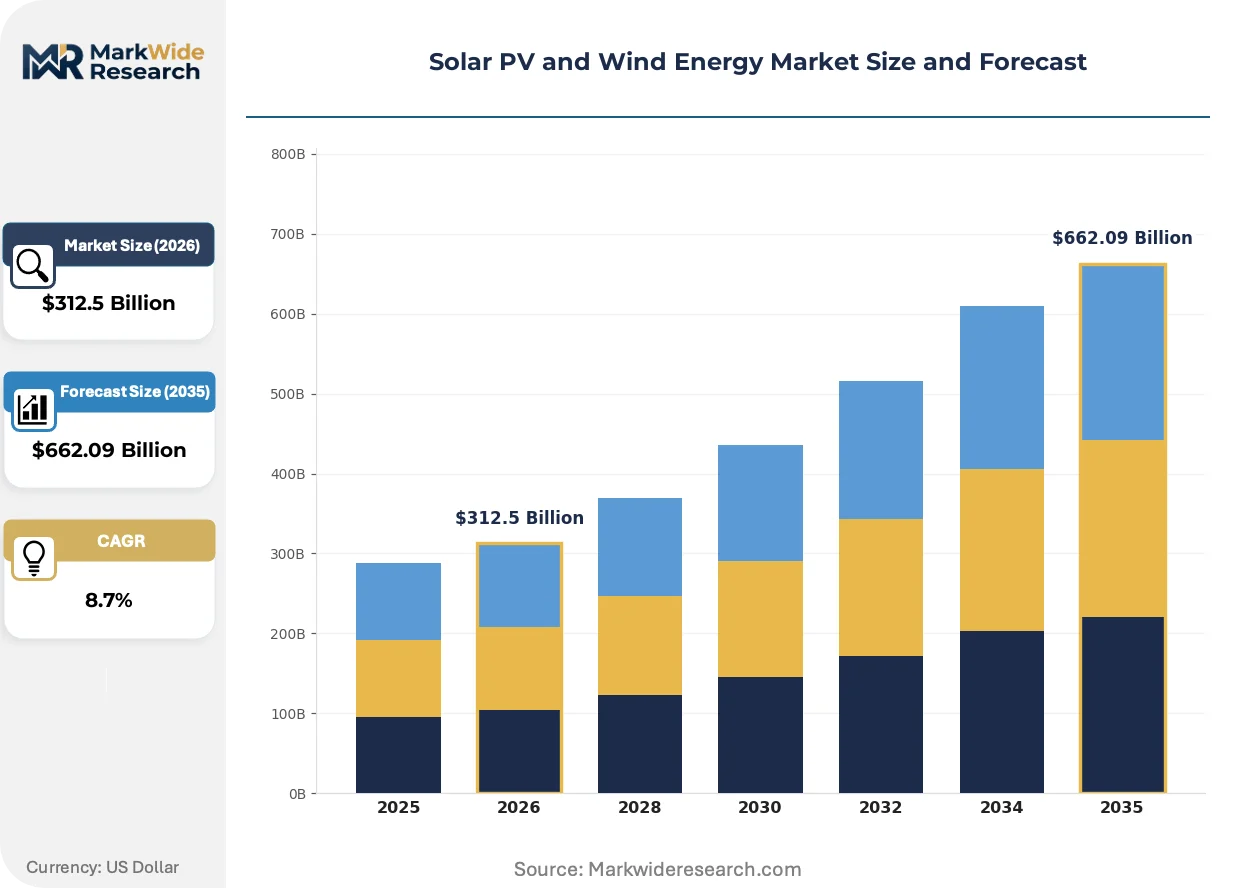
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $662.09 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Vertical Axis Application: Utility-Scale, Residential, Commercial, Off-Grid End User: Energy Producers, Government, Agriculture, Industrial Installation: Rooftop, Ground-Mounted, Offshore, Onshore |
| Companies Covered | NextEra Energy, Jinko Solar, JA Solar, Sungrow, First Solar, LONGi Green Energy, Vestas Wind Systems, ACWA Power, Adani Green Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV and Wind Energy Market Trends and Innovations
Technology trajectories in renewable energy are converging on standardization and factory fabrication, reducing field construction labor while enabling faster project replication.
Containerized battery energy storage systems are modularizing alongside solar and wind generation, allowing developers to procure pre-integrated power blocks that compress installation schedules from months to weeks. Industrial off-takers in manufacturing and data center verticals are specifying these integrated packages to minimize engineering procurement construction risk. This standardization is compressing balance-of-plant costs and enabling non-specialized contractors to execute complex hybrid projects.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in semiconductor manufacturing and heat pump production, indirectly constraining polysilicon purification equipment supply chains that rely on fluorinated gases. European module assemblers are retrofitting facilities to accommodate alternative chemistries. This regulatory pressure is accelerating investment in fluorine-free process technologies by equipment manufacturers serving the solar value chain.
Corporate power purchase agreements are displacing traditional utility procurement as the dominant demand channel for new renewable capacity, with technology firms and industrial conglomerates contracting directly with project developers. This bilateral contracting is fragmenting buyer concentration and forcing developers to maintain origination teams capable of structuring complex virtual and sleeved transactions. The United States and Northern Europe represent the most mature markets for this procurement evolution.
Solar PV and Wind Energy Market Segmentation
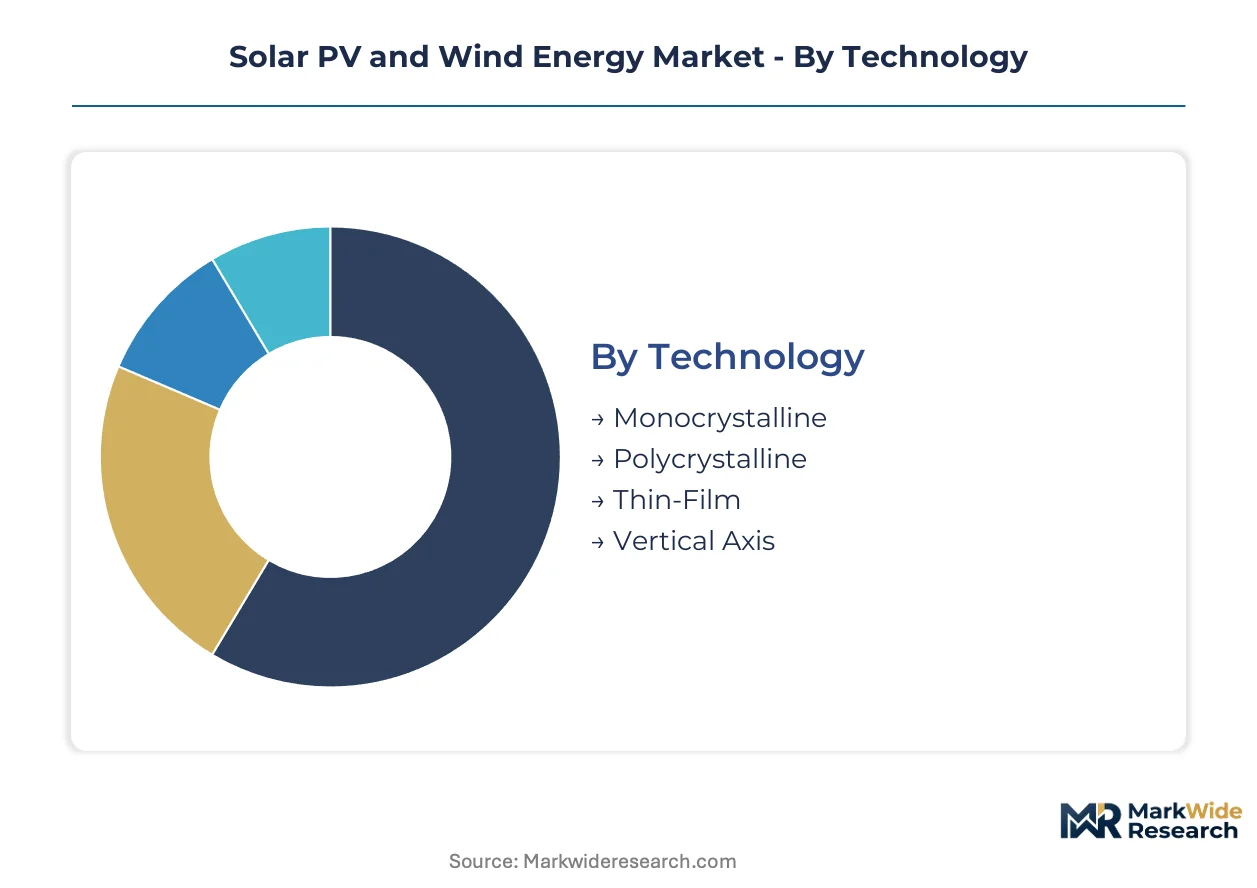
Technology choices in solar PV and wind energy determine capital efficiency, land use intensity, and grid integration complexity across deployment scenarios. Procurement patterns diverge sharply between price-sensitive emerging markets prioritizing lowest levelized cost and developed economies optimizing for domestic content requirements and supply chain resilience.
Technology:
Capital allocation efficiency separates winning technology bets from stranded manufacturing commitments.
- Monocrystalline:PERC and TOPCon cell architectures deliver conversion efficiencies exceeding 22% in mass production, commanding premium pricing in space-constrained installations. Chinese wafer producers in Xinjiang and Sichuan provinces dominate ingot pulling capacity, though the EU CBAM is reshaping import cost structures for European project developers.
- Thin-Film:Cadmium telluride and CIGS chemistries reduce embodied energy in manufacturing and perform better in high-temperature, low-light conditions. First Solar's Ohio manufacturing complex supplies utility-scale pipelines in the United States where domestic content bonuses under the IRA amplify cost competitiveness against imported crystalline alternatives.
- Polycrystalline:Multi-crystalline ingots retain residual demand in price-sensitive distributed markets where module efficiency matters less than upfront capital outlay.
- Vertical Axis:Darrieus and Savonius rotor designs navigate turbulent urban wind regimes where horizontal axis turbines face siting constraints.
Monocrystalline leads on scale; thin-film leads on momentum in markets with domestic manufacturing incentives.
Application:
Grid connection economics and offtake contract structures determine viable project scales.
- Utility-Scale:Installations exceeding 5 MWac aggregate capital in single locations with dedicated substations and high-voltage interconnection. Developers in India and Saudi Arabia are contracting gigawatt-scale portfolios with sovereign wealth funds seeking inflation-hedged infrastructure exposure.
- Residential:Rooftop systems under 20 kW leverage net metering frameworks and behind-the-meter consumption arbitrage. German households deploy battery-coupled installations under the EEG feed-in tariff successor regime, while Australian households optimize for high retail electricity spreads.
- Commercial:C&I offtakers with predictable load profiles use on-site generation to hedge volatile wholesale market exposure.
- Off-Grid:Mini-grids and standalone systems serve remote mining camps and rural electrification programs where transmission extension proves uneconomical.
Utility-scale commands capital deployment volumes; residential gains share fastest where retail rate structures reward self-consumption.
End User:
Risk tolerance and procurement sophistication vary dramatically across buyer categories.
- Energy Producers:IPPs and utilities manage renewable portfolios against baseload obligations and renewable portfolio standards. Orsted and Equinor develop offshore wind pipelines with 25-year contracted revenue streams backed by investment-grade offtakers.
- Government:Public procurement vehicles including green tariffs and sovereign guarantees de-risk capital-intensive infrastructure for private developers.
- Agriculture:Dual-use agrivoltaic installations in France and Japan qualify for differentiated tariffs while preserving agricultural land classification.
- Industrial:Data center operators and semiconductor fabs contract dedicated renewable supply to meet Scope 2 emissions targets and secure power for energy-intensive processes.
Energy producers anchor procurement volumes; industrial offtakers are expanding most quickly as corporate sustainability commitments harden into capital allocation filters.
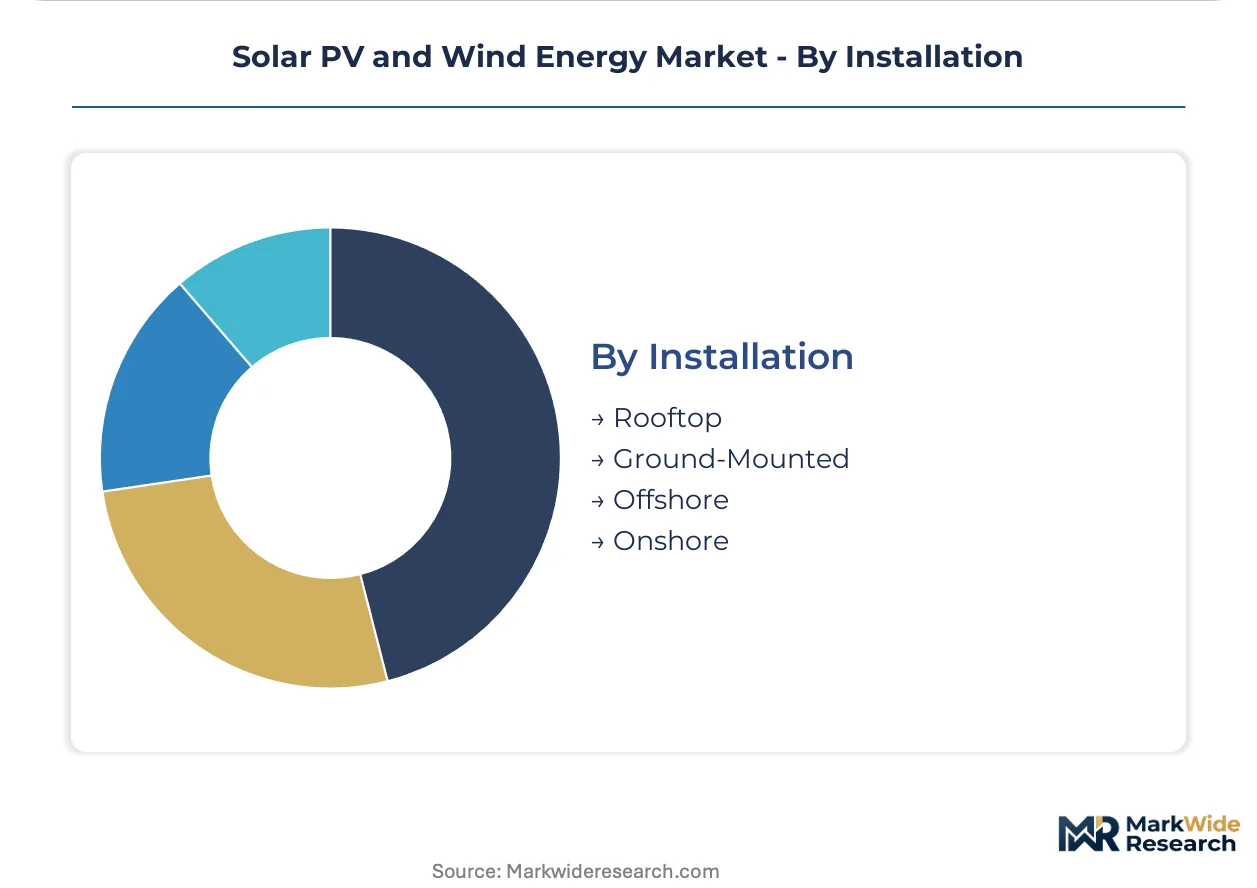
Installation:
Foundation and mounting systems represent 15-25% of project capital cost with limited standardization across terrain categories.
- Ground-Mounted:Fixed-tilt and single-axis tracking structures dominate utility-scale solar deployment on flat terrain with favorable geotechnical conditions. Tracking systems in Spain and Chile optimize for high direct normal irradiance with algorithmic backtracking to minimize row-to-row shading.
- Offshore:Fixed-bottom monopiles and floating semi-submersible platforms access higher capacity factor wind resources with reduced visual and noise impacts. Lease rounds in the North Sea and United States Atlantic coast are accelerating with streamlined environmental review processes.
- Rooftop:Ballasted and penetrating mounting systems adapt to structural load limits and waterproofing requirements in commercial building portfolios.
- Onshore:Tubular steel towers and concrete hybrid designs reach hub heights exceeding 150 meters to capture wind speed gradients.
Ground-mounted leads on scale; offshore shows the steepest expansion trajectory as floating foundation technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital migrates toward jurisdictions where production tax credits and streamlined permitting compress project development costs. The IRA in the United States and the EU Green Deal industrial policy create divergent compliance cost structures that reshape manufacturing location decisions. Polysilicon purification and turbine assembly capacity is concentrating where regulatory arbitrage maximizes return on capital.
United States
Utility-scale developers in Texas and California are contracting gigawatt-scale hybrid portfolios with investment-grade offtakers. The IRA production tax credit extension through 2032 guarantees project finance viability for wind developers. Vestas Wind Systems anchors turbine supply from its Colorado assembly facility serving the Great Plains wind corridor.
China
Polysilicon and wafer producers in Xinjiang and Sichuan provinces dominate ingot pulling capacity after price volatility forced capacity recalibration. MIIT governs module efficiency standards through GB certification requirements. LONGi Green Energy leverages in-house ingot-to-module production in Xi'an to sustain margin capture through manufacturing scale.
Germany
Agrivoltaic installations in Bavaria and Brandenburg qualify for differentiated feed-in tariffs while preserving agricultural land classification. The EU F-Gas Regulation constrains refrigerant-intensive manufacturing processes for polysilicon purification equipment. Industrial off-takers in the Rhine-Ruhr cluster contract dedicated renewable supply to meet Scope 2 emissions targets.
India
Gigawatt-scale solar parks in Rajasthan and Gujarat attract sovereign wealth fund capital seeking inflation-hedged infrastructure exposure. The PLI scheme incentivizes domestic module assembly capacity expansion. Adani Green Energy develops utility-scale pipelines with 25-year power purchase agreements backed by state distribution companies.
Saudi Arabia
Green hydrogen electrolyzer projects in NEOM are contracting dedicated renewable supply, creating demand verticals outside wholesale electricity markets. ACWA Power develops gigawatt-scale solar and wind portfolios with long-term offtake contracts. The kingdom's renewable procurement is displacing traditional utility channels as the dominant demand driver.
Solar PV and Wind Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue floating offshore platforms and agrivoltaic specializations. The market structures around three tiers: integrated polysilicon-to-module manufacturers, pure-play turbine assemblers, and hybrid project developers. Strategic archetypes include scale-driven cost leaders, technology-differentiated specialists, and geographic niche players. Dominant competitive moves center on backward integration into polysilicon supply and strategic partnerships for offshore lease access.
Among integrated Chinese manufacturers, LONGi Green Energy and Jinko Solar exemplify scale-driven archetypes with in-house production spanning ingots to modules. First Solar occupies a differentiated position as a thin-film specialist with domestic manufacturing in the United States. Vestas Wind Systems anchors European turbine supply with specialized offshore platform development. These three companies represent distinct competitive vectors: cost leadership through vertical manufacturing control, technology differentiation through alternative chemistries, and geographic anchoring through regional assembly presence.
| Leading Market Players |
|---|
| NextEra Energy |
| Jinko Solar |
| JA Solar |
| Sungrow |
| First Solar |
| LONGi Green Energy |
| Vestas Wind Systems |
| ACWA Power |
| Adani Green Energy |
| Others |
Pricing and Supply Chain Analysis
Captive polysilicon production across Chinese wafer manufacturers anchors both supply security and margin control in solar module markets, with Xinjiang and Sichuan ingot pulling capacity feeding directly into tier-one module assembly lines. This upstream integration insulates integrated producers from spot market volatility while compressing pricing power for pure-play assemblers dependent on merchant wafer supply.
Pricing Analysis
Distributor margin compression runs through the crystalline silicon value chain as Chinese module exporters bypass traditional European distributors to serve utility-scale developers directly. Project-based long-term offtake contracts dominate utility procurement, with price differentiation driven by module efficiency tier and domestic content certification under the IRA. Cost compression in monocrystalline PERC modules is intensifying because of wafer oversupply, while emerging market utilities show the highest price sensitivity and investment-grade corporate offtakers the least.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Rotterdam and Long Beach reshapes landed cost calculations for module importers, with containerized battery energy storage systems adding weight and dimensional complexity to renewable cargo movements. Polysilicon purification and wafer slicing concentrate in China, turbine nacelle assembly in Denmark and Spain, and inverter manufacturing in Germany and the United States. Rare earth processing for permanent magnet generators rests on Chinese smelter capacity, creating single-source vulnerability for Vestas and Siemens Gamesa. Distribution runs through EPC contractors and direct developer relationships rather than traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar PV and Wind Energy Market compounds steadily as utility procurement of hybrid renewable assets hardens into standard practice, with the IRA production tax credit extension and EU Green Deal industrial policy anchoring decade-long capital deployment visibility.
For Market Incumbents: Acquire offshore wind lease portfolios to secure development optionality ahead of floating foundation cost curves. LONGi Green Energy and Jinko Solar should expand ingot pulling capacity in low-carbon electricity regions to meet EU CBAM compliance requirements and defend margin position against thin-film competitors accessing IRA domestic content bonuses. Grid interconnection queue bottlenecks represent the critical threat to project delivery timelines.
For New Entrants and Emerging Players: Begin with agrivoltaic specializations in France and Germany where differentiated feed-in tariffs preserve agricultural land classification and reduce permitting friction. Floating offshore platforms off Japan and California offer the most penetrable technology frontier, with direct contracting to industrial hydrogen electrolyzer projects providing a go-to-market angle outside wholesale electricity market participation.
For Investors and Strategic Acquirers: Roll-up economics work for regional hybrid project developers because interconnection queue positions and offtake relationships concentrate in fragmented local markets with high barriers to entry. Five-to-ten year infrastructure holds align with power purchase agreement durations and tax credit monetization schedules. Watch FERC interconnection reform rulemaking as the inflection signal for development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Gigawatt-scale solar parks in Rajasthan attract sovereign wealth fund capital seeking inflation-hedged exposure. |
| Power Purchase Agreement | Corporate offtakers in data center verticals contract directly with developers to meet Scope 2 targets. |
| Technology Licensing | Thin-film cadmium telluride licensing expands First Solar's addressable market beyond captive manufacturing. |
| Backward Integration into Polysilicon | Wafer producers in Sichuan secure ingot supply against Xinjiang origin restrictions under EU forced labor regulations. |
| Green Certification Program | Module assemblers retrofit facilities to meet EU F-Gas Regulation phase-down of hydrofluorocarbon process gases. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA generation data, IEA renewable market reports, FERC interconnection queue filings, and project development databases. Bottom-up capacity installation tracking and top-down policy impact modeling were triangulated to reconcile segment-level figures.
Segment-weighting approaches distributed value and volume across technology type, project scale tier, application segment, and regional regulatory framework. CAGRs were derived from regression analysis of historical deployment trajectories adjusted for policy incentive schedules and manufacturing cost curves. Forecast inputs incorporated polysilicon spot price indices, turbine OEM order backlogs, and interconnection queue velocity metrics across the analysis window.
Several conditions sit outside the modeled scope, including unannounced subsidy phase-out schedules, breakthrough storage technology disruption, and trade policy shifts affecting module import tariffs. Forecasts reflect documented assumptions about IRA credit continuity and EU Green Deal implementation pace. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market