
 Insulated Cup Sleeves Market | 2026-2036
Insulated Cup Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Cup Sleeves Market Foresight
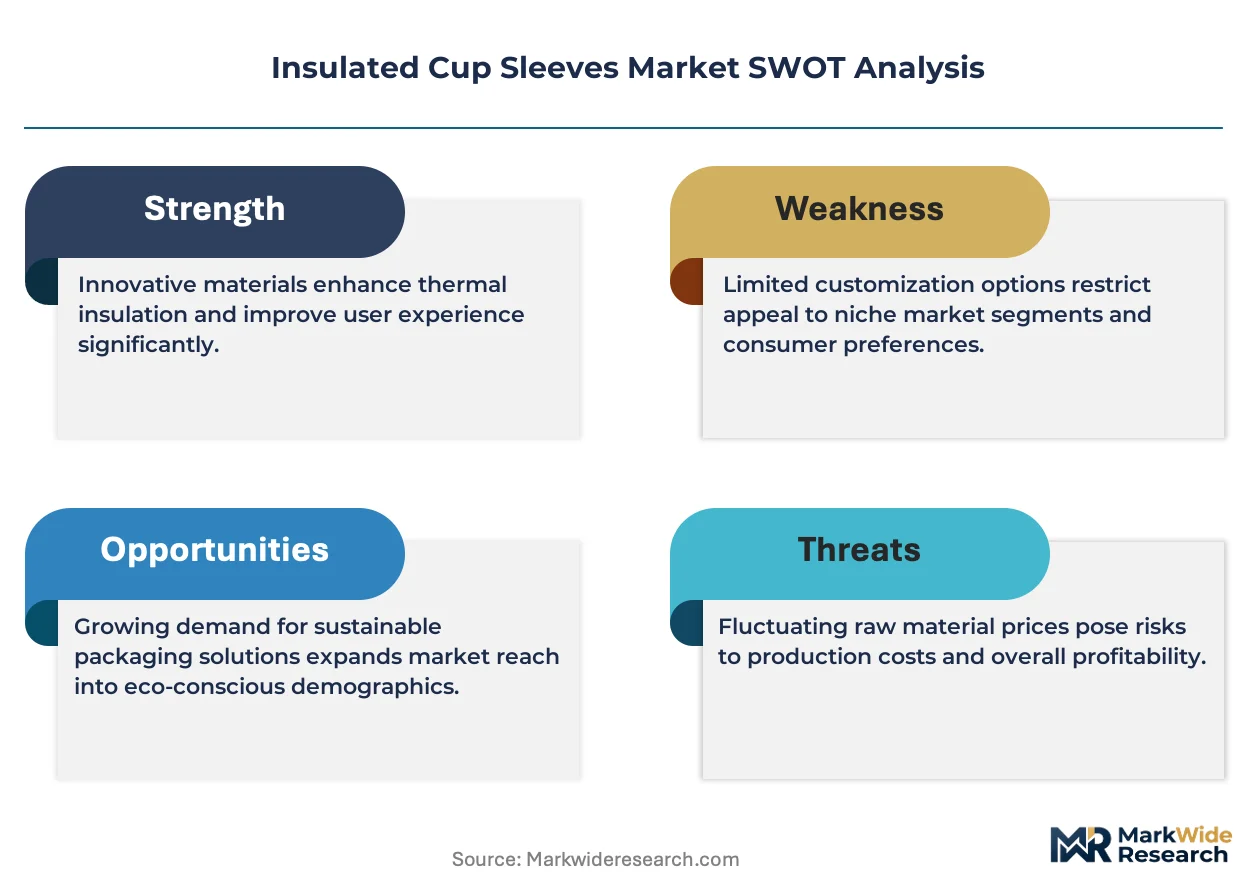
The split between premium reusable neoprene sleeves and commodity single-use cardboard wraps is hardening as beverage chains tier their sustainability commitments. WestRock Company anchors the North American cardboard segment through integrated pulp-to-sleeve manufacturing. Mondi Group leverages European paperboard expertise to supply quick-service restaurants with recyclable fiber solutions. Sok-It specializes in branded neoprene designs that command direct-to-consumer pricing online.
Insulated cup sleeves are thermal barriers constructed from materials such as corrugated kraft paper, closed-cell neoprene foam, or woven textile composites, engineered to maintain beverage temperature and protect hands from heat transfer. The cardboard segment leads unit volume due to foodservice disposables demand, while neoprene commands margin pools through repeat-use positioning and customization. Application demand concentrates in hot beverages, though food delivery growth is expanding cold-drink sleeve adoption for condensation control. Size segmentation shows custom formats growing fastest as corporate branding programs proliferate.
FDA food-contact substance regulations govern material safety for U.S. distribution, while the EU Packaging and Packaging Waste Directive shapes recyclability targets across European supply chains. Compliance with compostability certifications such as BPI or TÜV OK Compost is becoming a baseline requirement for institutional procurement. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in regional composting infrastructure partnerships or pivot toward durable reusable formats with take-back programs.
Market Dynamics
The EU Single-Use Plastics Directive is forcing a material pivot across foodservice supply chains, compressing demand for petroleum-based foam sleeves while elevating fiber-based and reusable alternatives. This regulatory pressure is concentrating procurement decisions among large beverage chains and institutional buyers.
Growth Catalysts
- Municipal composting mandates:Cities including San Francisco and Seattle require BPI-certified foodservice disposables, creating procurement specifications that favor kraft paper and molded fiber sleeves over conventional plastics.
- Quick-service restaurant expansion:Coffeehouse chains are scaling reusable sleeve programs with deposit-return mechanisms, building repeat-use infrastructure that locks in supplier relationships.
- Closed-cell neoprene foam:This material commands premium positioning through thermal performance and customization potential, absorbing margin pools as direct-to-consumer channels expand.
Market Restraints
- Pulp price volatility:Kraft paper input costs fluctuate with global softwood markets, squeezing converters who lack backward integration into pulp supply.
- Chinese manufacturing concentration:Neoprene sleeve assembly clusters in Guangdong and Zhejiang provinces, exposing brands to logistics disruption and tariff exposure.
- Technical limitation in cold-drink performance:Cardboard sleeves absorb condensation poorly compared to synthetic barriers, limiting adoption in iced beverage delivery applications.
Strategic Opportunities
- Underpenetrated cold-drink sleeve demand:Food delivery platform growth in India creates whitespace for condensation-control solutions tailored to tropical climates.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz mandates take-back programs, enabling sleeve-as-a-service business models with recurring revenue streams.
- QR-code-enabled traceability:Converging digital printing and blockchain verification allows brands to document material provenance, satisfying corporate ESG reporting requirements.
Industry Challenges
- Composting certification timelines:BPI and TÜV OK Compost testing cycles extend 6-12 months, delaying product launches and freezing formulation iteration.
- Integration complexity with legacy cup formats:Sleeve converters must maintain dimensional compatibility across multiple cup taper angles and rim diameters, fragmenting tooling investments.
- Skill gap in bio-based polymer processing:PLA and PHA sleeve production requires extrusion expertise scarce in traditional paper-converting regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Cup Sleeves Market |
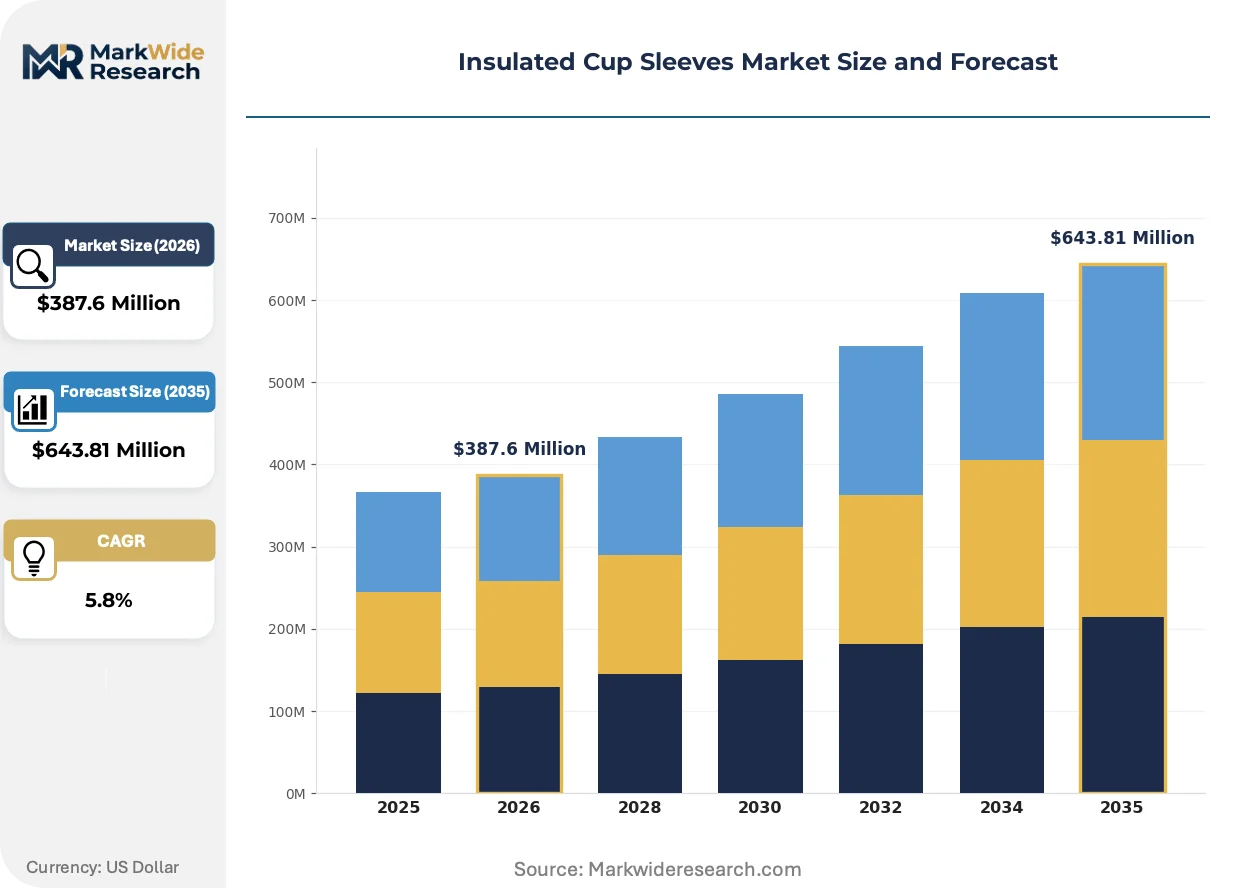
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Neoprene, Silicone, Cardboard, Fabric Application: Hot Beverages, Cold Drinks, Food Delivery, Events Size: Standard, Large, Mini, Custom Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Trucks |
| Companies Covered | WestRock Company, Smurfit Kappa Group, Mondi Group, Sok-It, Graphic Packaging International, Sabert Corporation, Huhtamaki, Genpak, Novolex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Cup Sleeves Market Shifts & Advancements
Material science advances and digital manufacturing are compressing development cycles while regulatory pressure accelerates substitution away from conventional petroleum-based barriers. These forces are reshaping competitive positioning across both commodity and premium sleeve tiers.
Molded pulp technology is absorbing investment from major packaging converters seeking drop-in replacements for expanded polystyrene. Starbucks and Dunkin' are piloting fiber-based sleeves with integrated lids across thousands of locations. This transition is absorbing margin from foam incumbents while creating captive demand for regional pulp suppliers.
REACH restrictions on microplastics are compelling European sleeve manufacturers to eliminate synthetic binding agents in fiber formulations. The European Chemicals Agency enforcement timeline is compressing reformulation windows to 18 months. Quick-service restaurants in France and Germany are responding by consolidating procurement around TÜV-certified compostable specifications.
Corporate buyers are consolidating sleeve procurement through direct platform contracts with manufacturers, bypassing traditional distribution intermediaries. Foodservice management companies like Compass Group and Sodexo are unbundling sleeve supply from broader disposables agreements. This pattern is most visible in the United States, where institutional buyers leverage scale to mandate custom branding and certified compostability.
Insulated Cup Sleeves Market Segmentation
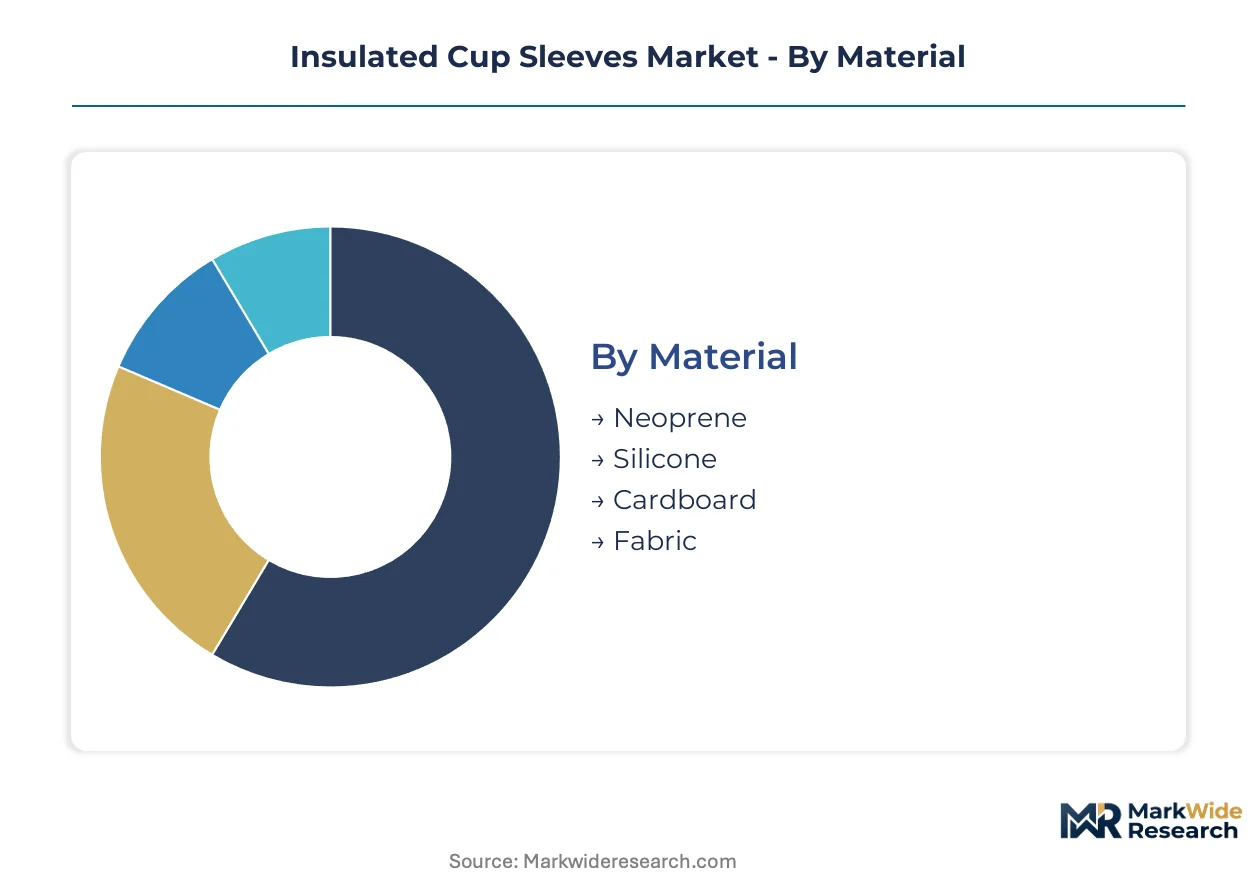
Insulated cup sleeve procurement splits sharply between disposable foodservice contracts and premium reusable retail channels. Material selection drives margin structure, while application context dictates performance specifications and certification requirements.
Material:
Supply concentration clusters around pulp-based converters in the southeastern United States and neoprene fabricators in East Asian manufacturing zones.
- Cardboard:Corrugated kraft paper with clay or starch coatings dominates institutional procurement. Quick-service restaurants in the United States specify BPI-certified formats to satisfy municipal composting mandates in San Francisco, Seattle, and Portland.
- Neoprene:Closed-cell synthetic rubber foam delivers thermal insulation across 500-plus wash cycles. Direct-to-consumer brands leverage digital printing for customization, commanding price multiples over disposable alternatives through repeat-use positioning.
- Silicone:Platinum-cured elastomer sleeves fold flat for portability. Food-grade formulations meet FDA food-contact substance regulations for U.S. distribution.
- Fabric:Woven textile composites incorporate recycled polyester or organic cotton. Specialty retailers stock these for gift and corporate branding programs.
Today's leader: Cardboard. Tomorrow's challenger: Neoprene.
Application:
Cost tiers separate commodity hot-beverage wraps from premium condensation-control solutions for delivery logistics.
- Hot Beverages:Coffee and tea service generates baseline demand across foodservice, office, and hospitality channels. Heat-transfer protection specifications center on surface temperature reduction.
- Cold Drinks:Iced beverage sleeves address condensation control for delivery platforms. Tropical climate expansion in India and Southeast Asia drives specialized synthetic barrier adoption.
- Food Delivery:Third-party logistics operators specify sleeves maintaining temperature integrity across 30-60 minute transit windows. Custom sizing accommodates diverse cup formats.
- Events:Stadium and festival procurement favors low-unit-cost cardboard for single-session use. Volume discounts structure competitive bidding.
Volume concentrates in hot beverages. Margin pools shift toward cold-drink applications.
Size:
Customer type fragmentation forces converters to maintain tooling for multiple taper angles and rim diameters.
- Standard:Fits 12-16 ounce cups from major quick-service chains. Tooling amortization across billions of units supports lowest per-piece cost.
- Large:Accommodates 20-24 ounce formats popular in drive-through channels. Demand tracks super-size beverage program rollouts.
- Mini:Targets espresso and cortado cups. Specialty coffee chains specify these for premium positioning.
- Custom:Corporate branding programs drive fastest expansion. Digital printing enables short-run production with 2-week turnaround.
Standard sizes anchor volume. Custom formats gain share fastest.
Distribution Channel:
Geography shapes channel strategy, with urban density favoring direct procurement and suburban sprawl sustaining retail intermediaries.
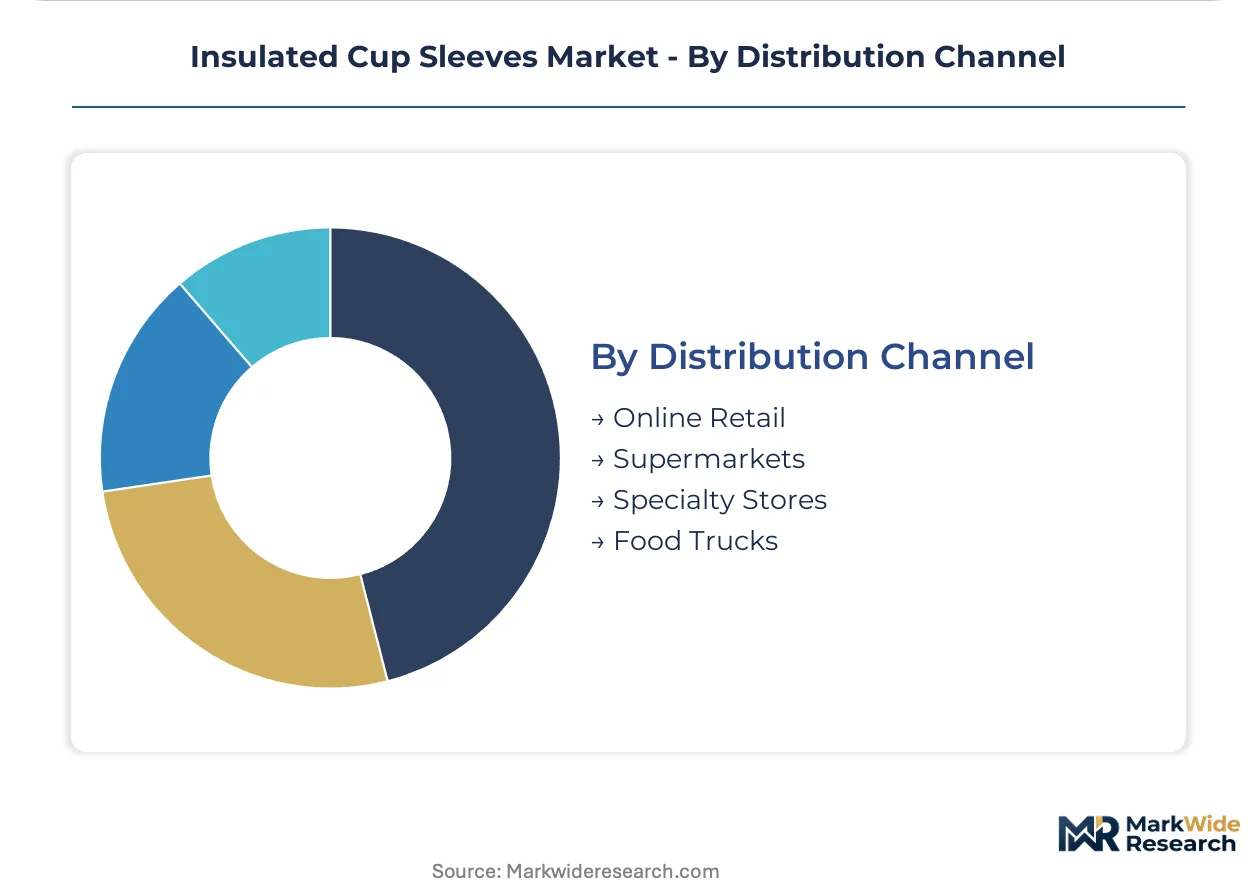
- Online Retail:Direct-to-consumer platforms enable customization and subscription models. Neoprene and silicone segments concentrate here.
- Supermarkets:Mass-market cardboard sleeves stock alongside disposable tableware. Price competition structures private-label penetration.
- Specialty Stores:Kitchenware and gift channels stock premium reusable formats. Brand discovery drives impulse purchase.
- Food Trucks:Mobile operators procure sleeves through foodservice distributors. Limited storage favors compact, high-unit-count packaging.
Foodservice distributors dominate volume. Online retail captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement volume for disposable cardboard sleeves, while Germany drives regulatory specification for compostable fiber formats across European foodservice chains.
United States
Quick-service restaurants and coffeehouse chains anchor sleeve demand through centralized procurement platforms. Municipal composting mandates in San Francisco, Seattle, and Portland require BPI-certified foodservice disposables, filtering supplier qualification. Integrated pulp-to-sleeve manufacturing clusters in the southeastern states supply major beverage chains with corrugated kraft formats.
Germany
The Verpackungsgesetz mandates extended producer responsibility for packaging take-back, accelerating sleeve-as-a-service business models. ECHA enforcement of REACH microplastic restrictions compresses reformulation timelines for fiber binding agents to eighteen months. Industrial converters in North Rhine-Westphalia and Baden-Württemberg supply quick-service restaurants with TÜV-certified compostable specifications.
China
Neoprene sleeve assembly concentrates manufacturing capacity in Guangdong and Zhejiang provinces for export to North American and European consumer markets. The country's national environmental regulator enforces dual carbon goals that elevate energy costs for synthetic foam production. Shenzhen and Dongguan fabricators serve direct-to-consumer brands with digital printing customization capabilities.
India
Food delivery platform expansion in Mumbai, Bangalore, and Delhi-NCR generates whitespace demand for condensation-control solutions in tropical climates. The Bureau of Indian Standards governs food-contact material safety for imported and domestically produced sleeves. Maharashtra and Karnataka states host emerging molded fiber converter investments targeting quick-service restaurant supply contracts.
United Kingdom
Corporate catering and hospitality channels drive custom branding programs for reusable neoprene and fabric sleeves. The UK's packaging waste regulations align with EU circular economy targets post-Brexit, shaping recyclability requirements. Greater London and the Southeast concentrate specialty retail distribution for premium consumer formats.
Insulated Cup Sleeves Market Competitive Landscape
Top-tier vendors anchor integrated pulp and paperboard supply chains, while specialized neoprene fabricators and regional converters occupy mid-tier and niche positions. The market structure splits between scale-driven commodity producers and customization-focused premium specialists. Three archetypes dominate: vertically integrated paperboard conglomerates, direct-to-consumer neoprene brands, and contract converters serving institutional foodservice. Competitive moves concentrate on backward integration into pulp supply and geographic expansion of composting certification coverage.
Within the integrated paperboard tier, WestRock Company and Mondi Group exemplify scale-driven supply chain control. Sok-It occupies a position in the premium reusable segment. These three entities represent the spectrum from commodity volume through branded direct-to-consumer positioning.
| Leading Market Players |
|---|
| WestRock Company |
| Smurfit Kappa Group |
| Mondi Group |
| Sok-It |
| Graphic Packaging International |
| Sabert Corporation |
| Huhtamaki |
| Genpak |
| Novolex |
| Others |
Supply & Pricing Matrix
Municipal composting mandates in San Francisco, Seattle, and Portland are forcing quick-service restaurants to specify BPI-certified kraft paper sleeves, compelling converters to absorb certification costs and compressing margins on institutional contracts while creating pricing power for certified suppliers.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for molded fiber alternatives. Three-tier pricing structure across premium neoprene, certified fiber, and commodity cardboard segments anchors the market. Price differentiation rests on compostability certification grade and customization depth. Cost compression in the cardboard tier is intensifying because pulp price volatility squeezes non-integrated converters. Quick-service restaurant procurement teams exhibit highest price sensitivity, while direct-to-consumer neoprene buyers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang provinces for neoprene sleeve assembly. Raw material flows draw from Canadian softwood pulp, Malaysian petrochemical feedstocks, and Chinese synthetic rubber production. Tariff exposure on Chinese-manufactured neoprene creates structural risk for brands dependent on East Asian assembly. Distribution runs through foodservice distributors for institutional volume, direct-to-consumer platforms for premium reusable formats, and specialty retail channels for corporate gifting programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated cup sleeves market functions as a stable compounder, with regulatory substitution mandates providing predictable demand tailwinds across foodservice procurement cycles.
For Market Incumbents: Acquire regional pulp supply assets to secure backward integration into kraft paper production. Lock in BPI and TÜV OK Compost certification coverage across all manufacturing facilities before ECHA enforcement compresses reformulation windows. Defensive positioning requires preemptive capacity in molded fiber technology to capture Starbucks and Dunkin' pilot program expansion. For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany and France opens a window for fiber-based sleeve specialists to penetrate quick-service restaurant supply chains. Target condensation-control solutions for Indian food delivery platforms in Mumbai and Bangalore. Cold-drink sleeve applications for tropical climates represent the most penetrable whitespace. A direct platform contracting go-to-market angle bypasses traditional distributor intermediaries. For Investors and Strategic Acquirers: Asymmetric upside sits with neoprene fabricators possessing digital printing customization capabilities. The five-to-ten year viability window favors suppliers with dual certification coverage and reusable format portfolios. Acquisition target archetype: mid-tier converters with established quick-service relationships but lacking compostability credentials. Watch ECHA microplastic restriction enforcement timelines as inflection indicator for fiber binding agent reformulation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | BPI and TÜV OK Compost credentials unlock municipal procurement in San Francisco and Seattle. |
| Backward Integration into Pulp Supply | Captive softwood sourcing insulates converters from global pulp price volatility. |
| Direct-to-Consumer Platform Launch | Digital printing customization commands price multiples over disposable alternatives. |
| Cold-Drink Sleeve R&D Program | Condensation-control solutions capture whitespace in Indian and Southeast Asian delivery markets. |
| Extended Producer Responsibility Partnership | Take-back program infrastructure aligns with Germany's Verpackungsgesetz mandates. |
Research Methodology
Multiple input streams — executive interviews with foodservice procurement directors, technical discussions with pulp converters, and regulatory tracking across ECHA and FDA frameworks — were reconciled against secondary validation from customs records, SEC filings of integrated paperboard producers, and municipal composting ordinance databases. Primary engagement covered quick-service restaurant supply chain managers, foodservice distributor category buyers, neoprene fabricator operations leads, and sustainability officers at major beverage chains. Bottom-up unit demand estimates and top-down market sizing were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated material type, application context, size format, and distribution channel dimensions. CAGRs were derived from trend extrapolation moderated by regulatory phase-in schedules and procurement contract renewal cycles. Forecast inputs included pulp futures pricing, quick-service restaurant expansion pipelines, and municipal composting mandate adoption curves.
Revisions become necessary when ECHA enforcement timelines accelerate, major beverage chains pivot procurement specifications, or pulp price volatility exceeds historical bands. Forecasts reflect documented assumptions about regulatory adoption and buyer consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Beveled Bottles Market