

Beverage Packaging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Packaging Machine Market Insights
Aftermarket service revenue is tilting toward predictive maintenance contracts as OEMs seek recurring income streams. Krones AG leverages its global installed base to sustain long-term service agreements across bottling plants. Sidel Group differentiates through aseptic filling technology leadership, while GEA Group anchors its position in dairy and alcoholic beverage processing systems. Tetra Pak competes by controlling carton packaging know-how from material science through shelf-ready formats.
Beverage packaging machines integrate mechanical, pneumatic, and control systems to fill, seal, label, and wrap containers at speeds exceeding 60,000 units per hour for high-volume carbonated lines. These systems execute precise volumetric or gravimetric dosing, hermetic sealing, and contamination-free handling to preserve product shelf stability and regulatory compliance. Filling machines command the largest installed base due to their centrality in every production line, while aseptic systems for juices and dairy drinks represent the fastest-expanding margin pool as cold-chain alternatives gain preference. PET bottle handling equipment dominates volume given lightweighting trends and recyclability mandates, though aluminum can lines are accelerating with craft beer and sparkling water proliferation.
FDA food contact regulations in the United States, EU MDR machinery safety directives, and China's GB standards for food machinery collectively shape equipment design, material selection, and validation protocols for market access. The EU Green Deal's packaging waste targets are forcing redesigns toward mono-material compatibility and reduced energy consumption per packaged unit. Stakeholders must monitor how deposit-return scheme expansions across European markets and North American states reshape container format demand and corresponding machine specifications.
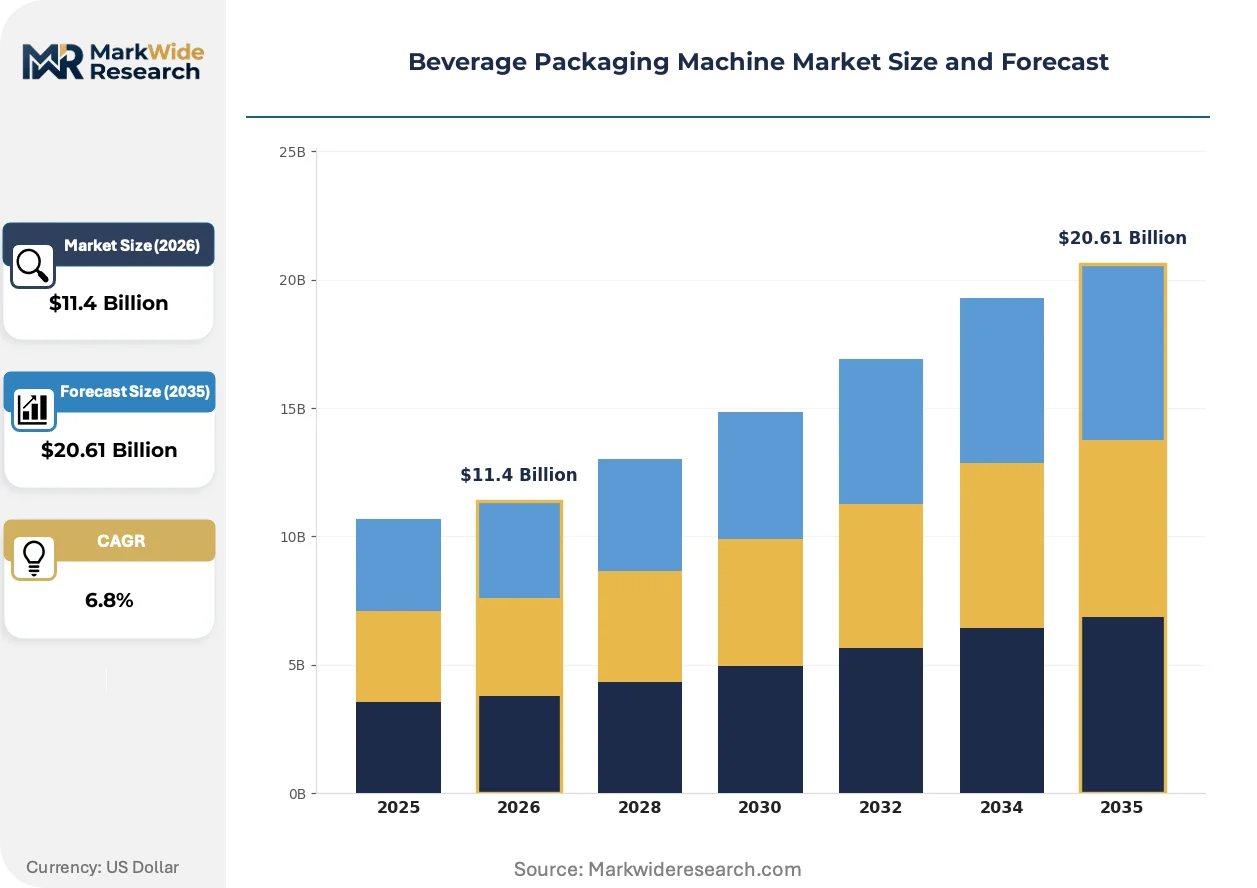
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles as bottlers face refrigerant phase-down mandates and energy-efficiency thresholds that obsolete legacy filling systems before end-of-life.
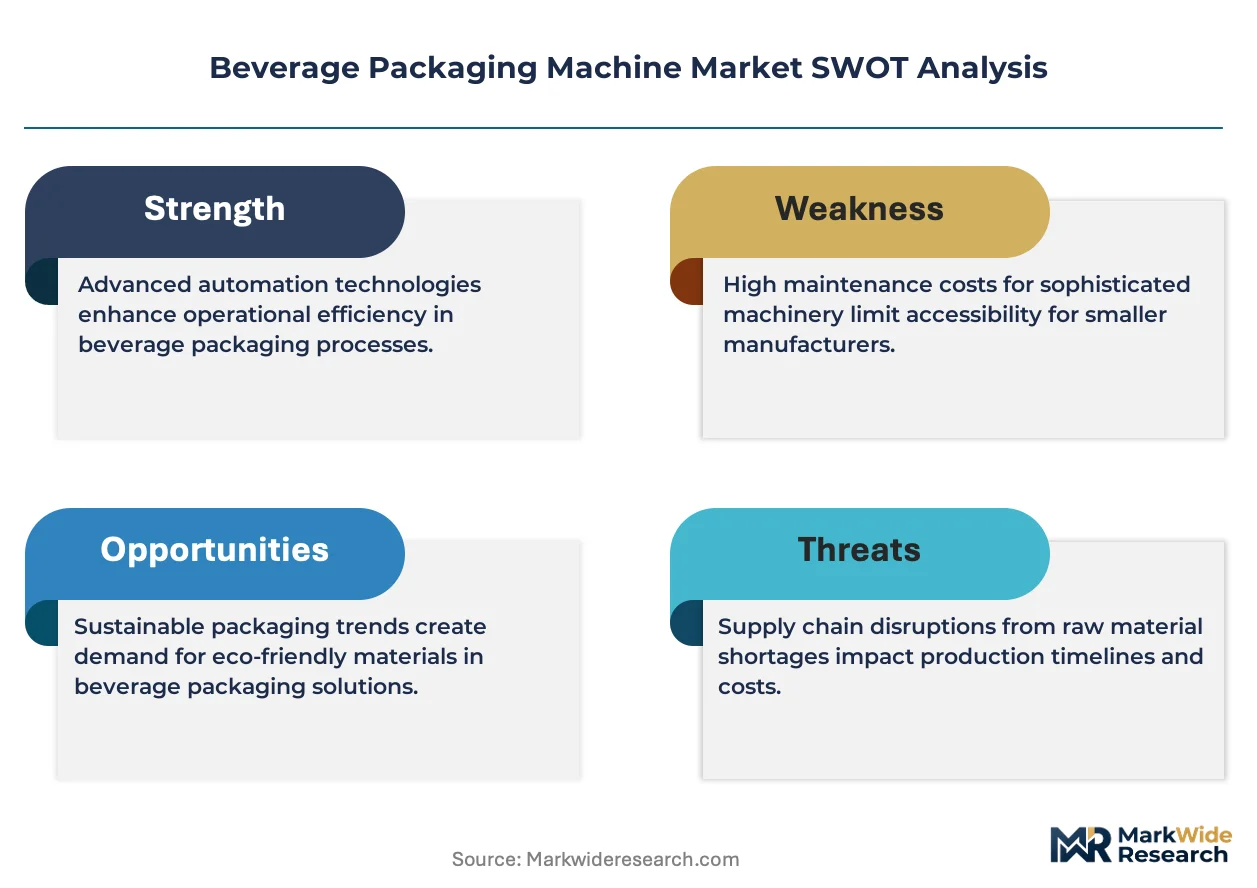
Growth Catalysts
- Carbonated Soft Drink Throughput Pressure:Bottlers in high-volume markets are automating lines to hit 60,000+ units per hour, pulling demand for integrated filling-sealing-labeling systems.
- EU Green Deal Packaging Waste Targets:Mono-material compatibility mandates are forcing equipment redesigns that favor suppliers with modular retrofit capabilities.
- Aseptic Cold-Chain Alternatives:Juice and dairy processors are adopting ambient-stable aseptic filling to reduce refrigeration dependency, expanding the addressable machine base.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L price swings compress OEM margins on custom-fabricated contact surfaces and extend quotation validity periods.
- German Component Supply Concentration:Precision pneumatic valves and servo drives cluster in Baden-Württemberg and Bavaria, creating single-source exposure for non-European builders.
- CE-MDR Validation Timelines:Extended machinery safety certification cycles delay revenue recognition for new aseptic platform launches.
Strategic Opportunities
- India PLI Scheme for Food Processing:Domestic beverage manufacturing incentives are creating localized demand for mid-speed filling lines previously served by used European equipment.
- Predictive Maintenance Contract Unbundling:Sensor-enabled uptime guarantees are displacing traditional break-fix service models among multi-site bottling groups.
- Aluminum Can Line Conversion:Sparkling water and craft beer format shifts are opening retrofit demand at legacy PET-dedicated facilities.
Industry Challenges
- Mechatronics Skill Scarcity:Bottling plants struggle to hire technicians fluent in both pneumatic troubleshooting and PLC programming for integrated lines.
- Legacy System Integration Friction:Brownfield sites face protocol mismatches when connecting new IoT-enabled fillers to 1990s-era SCADA architectures.
- Dual Certification Burden:Exporters must simultaneously validate FDA food contact compliance and EU MDR machinery safety, doubling documentation overhead.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Packaging Machine Market Trends and Innovations
Digital thread technologies are collapsing the boundary between machine commissioning and continuous optimization, enabling real-time parameter adjustment that was previously locked at startup.
Edge computing architectures are digitizing filling line control by embedding analytics directly at the servo drive level. High-volume carbonated bottlers in Germany and the United States are deploying these systems to compress changeover times and reduce giveaway from volumetric drift. The technology is digitizing maintenance scheduling by replacing fixed-interval servicing with condition-based triggers derived from vibration and temperature signatures.
REACH restrictions on per- and polyfluoroalkyl substances are forcing gasket and seal material substitutions in aseptic filling environments. Equipment builders are validating alternative elastomers that maintain microbial barrier properties without fluorinated compounds. Dairy and extended-shelf-life juice processors in the European Union face the tightest compliance deadlines and are accelerating qualification timelines for modified machine specifications.
Buyer consolidation among multinational beverage groups is compressing vendor negotiation cycles and unbundling after-sales contracts from initial equipment sales. Large bottlers in North America are separating maintenance procurement from capital expenditure committees, creating discrete purchasing events that favor specialized service providers over full-line OEMs. This pattern is most pronounced in carbonated soft drink and bottled water operations with centralized procurement functions.
Beverage Packaging Machine Market Segmentation
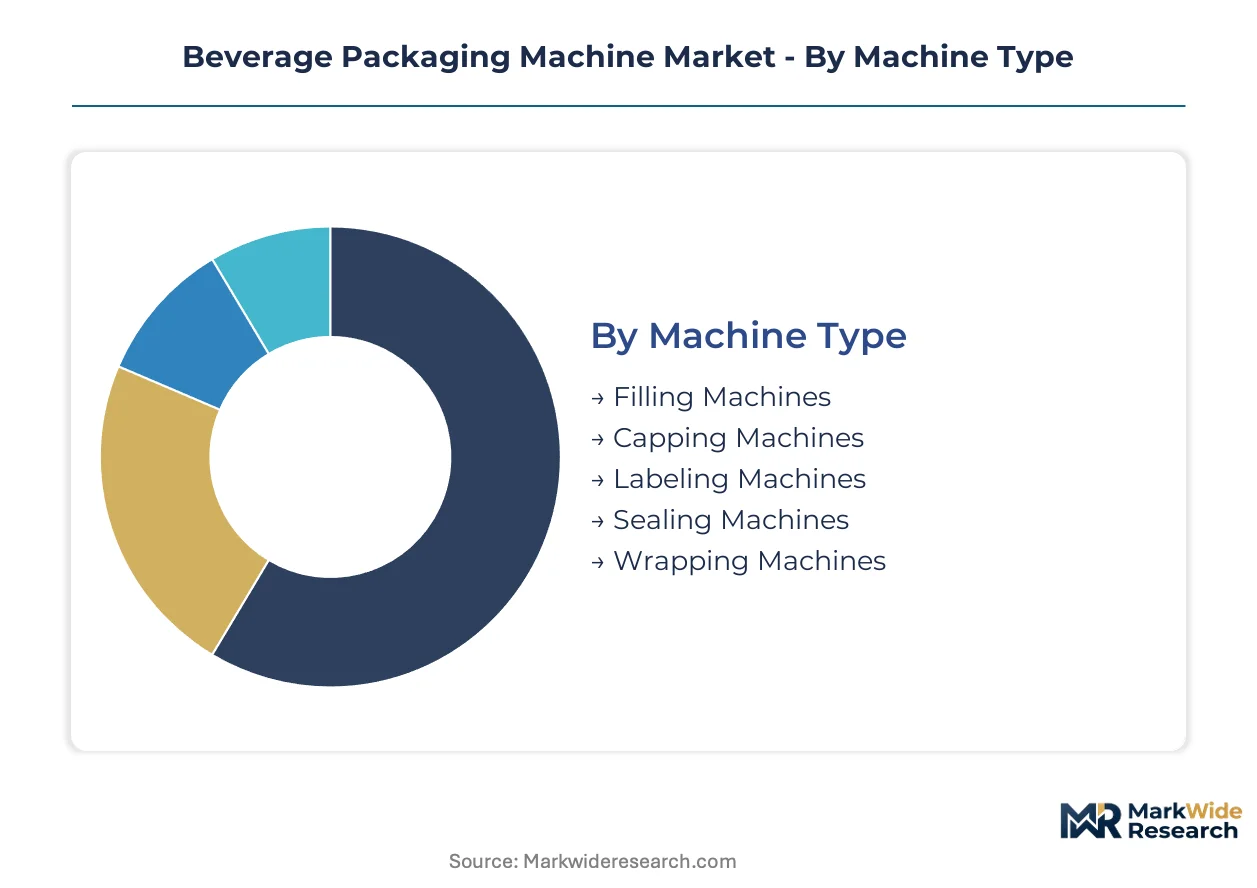
Beverage packaging machine segmentation reveals how equipment specifications diverge across container formats, liquid properties, and production scale. Machine builders configure dosing precision, sterilization protocols, and changeover automation differently for carbonated lines versus aseptic dairy systems. Understanding these segment boundaries helps suppliers allocate R&D resources and target aftermarket services.
Machine Type:
Equipment selection spans a functional spectrum from liquid dosing through final palletization, with each stage imposing distinct mechanical and control requirements.
- Filling Machines:Volumetric and gravimetric dosing systems execute precise liquid measurement at line speeds exceeding 60,000 units per hour for carbonated applications. German bottling plants in Bavaria anchor demand for integrated filling-sealing units as throughput pressure intensifies.
- Capping Machines:Torque-controlled sealing heads secure container integrity against pressure retention needs in sparkling water and beer formats. Aluminum can line conversions in the United States are pulling demand for twist-off and crown cork variants.
- Labeling Machines:Pressure-sensitive and sleeve application systems accommodate shrink-sleeve growth in premium beverage segments. Cold-glue alternatives persist in cost-sensitive emerging markets.
- Sealing Machines:Induction and conduction heat-sealing technologies preserve hermetic barriers for extended-shelf-life products. Dairy processors in the European Union prioritize validated seal integrity for ambient distribution.
- Wrapping Machines:Shrink bundling and tray packing systems consolidate multi-unit formats for retail distribution. E-commerce-ready packaging is forcing faster changeover capabilities in secondary packaging lines.
The dominant share belongs to Filling Machines, while Capping Machines is closing the gap fastest.
Packaging Material:
Material selection drives equipment design through container rigidity, thermal tolerance, and recyclability mandates.
- PET Bottles:Stretch blow molding integration and lightweighting-compatible handling systems dominate high-volume carbonated and water lines. EU Green Deal mono-material targets are accelerating PET recycling infrastructure investments.
- Aluminum Cans:Necking and flanging equipment accommodates thinner wall specifications as canmakers reduce metal content. Craft beer proliferation in the United States and Germany is expanding can line retrofit demand.
- Glass Bottles:Heavy-duty conveyor systems and ionized air rinsing protect returnable bottle circuits in premium beer and wine segments. Deposit-return scheme expansions across European markets sustain refurbishment economics.
- Tetra Pak:Aseptic carton forming and longitudinal sealing equipment controls material science from liquid packaging board through shelf-ready formats. Juice and dairy processors in India leverage carton ambient stability to bypass cold-chain limitations.
- Pouches:Spouted and fitment-equipped flexible formats require specialized filling nozzles and ultrasonic sealing. Sports nutrition and ready-to-drink coffee applications are gaining trial in North American convenience channels.
PET Bottles commands the largest installed base, though Aluminum Cans is expanding most quickly.
Application:
Liquid chemistry and shelf-stability requirements dictate sterilization intensity, gas flushing, and packaging atmosphere control.
- Carbonated Drinks:Counter-pressure filling systems maintain CO₂ saturation while preventing foam loss at high speeds. Bottlers in Germany and the United States automate lines to hit throughput targets above 60,000 units per hour.
- Juices & Concentrates:Hot-fill and aseptic alternatives compete for shelf-stable positioning without refrigeration dependency. EU F-Gas Regulation energy thresholds favor aseptic systems that eliminate cold-chain refrigerants.
- Bottled Water:Gravity and vacuum filling suffices for non-carbonated formats, with lightweight PET driving neck finish standardization. Still water commoditization compresses equipment margin pools.
- Alcoholic Beverages:Oxygen exclusion and cork/crown compatibility vary across beer, wine, and spirits segments. Craft brewery fragmentation in the United States sustains demand for mid-speed flexible lines.
- Dairy Drinks:Extended-shelf-life aseptic filling for milk and flavored dairy demands hydrogen peroxide sterilization and sterile air overpressure. REACH restrictions on fluorinated compounds are forcing gasket material substitutions in European installations.
Carbonated Drinks retains the dominant share, while Juices & Concentrates is climbing the fastest.
End User:
Procurement sophistication and lifecycle management expectations diverge across ownership structures and scale.
- Beverage Manufacturers:Integrated multinational groups unbundle capital expenditure from aftermarket contracts, creating discrete purchasing events. Predictive maintenance guarantees are displacing traditional break-fix service models.
- Contract Packagers:Multi-brand tolling operations prioritize rapid format changeover and flexible line configurations. India PLI scheme incentives are creating localized demand for mid-speed filling lines.
- Private Labelers:Retail-controlled brands balance equipment cost discipline against quality parity with national equivalents. Centralized procurement functions compress vendor negotiation cycles.
- Bottling Plants:Franchise-owned operations depend on concentrate supplier specifications for equipment compatibility. Brownfield sites face protocol mismatches when integrating IoT-enabled fillers with legacy SCADA architectures.
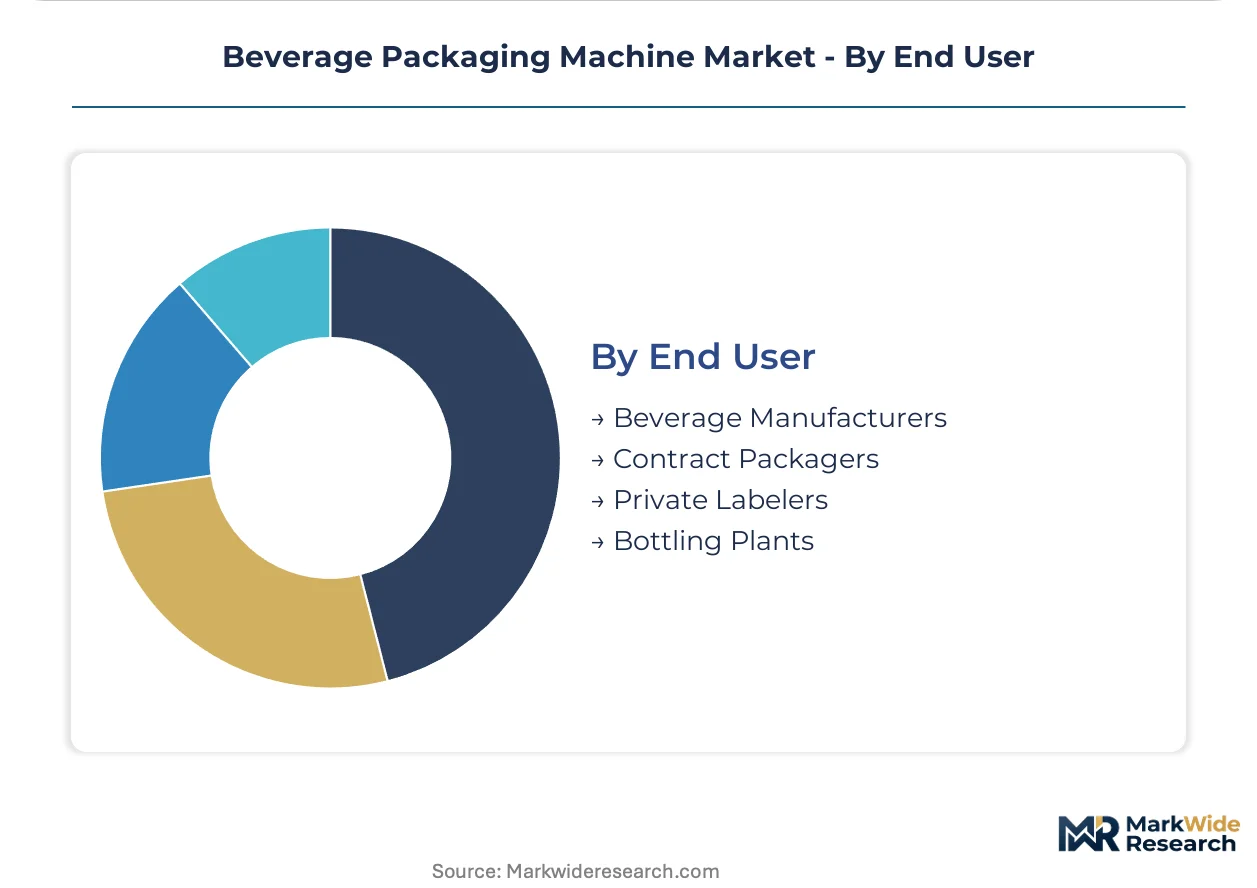
Beverage Manufacturers holds the dominant share, while Contract Packagers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German bottlers absorb premium equipment costs for throughput gains, while Indian contract packagers prioritize mid-speed lines that balance automation with capital discipline.
Germany
Carbonated soft drink bottlers in Bavaria and Baden-Württemberg automate lines to exceed 60,000 units per hour. The EU F-Gas Regulation compresses replacement cycles for energy-intensive filling systems. Krones AG and GEA Group anchor manufacturing clusters around Munich and Düsseldorf, supplying integrated filling-sealing units across European markets.
United States
Craft beer and sparkling water proliferation accelerates aluminum can line conversions at legacy PET facilities. FDA food contact regulations shape material selection and validation protocols for market access. Chicago and Milwaukee bottling corridors deploy predictive maintenance contracts as beverage manufacturers unbundle aftermarket procurement from capital expenditure committees.
India
Domestic beverage manufacturing incentives under the PLI scheme displace used European equipment with localized mid-speed filling lines. FSSAI standards for food machinery compliance reshape equipment specifications for juice and dairy processors. Maharashtra and Gujarat industrial zones concentrate contract packaging demand as multi-brand tolling operations expand capacity.
China
GB standards for food machinery govern equipment design and validation for domestic and export markets. MIIT dual carbon goals pressure bottlers toward reduced energy consumption per packaged unit. Yangtze River Delta manufacturing bases supply PET handling equipment for lightweighting-compatible lines serving carbonated and bottled water segments.
Brazil
ANVISA pharmaceutical-grade validation requirements extend to extended-shelf-life dairy and juice aseptic systems. São Paulo state bottlers balance equipment cost discipline against quality parity with multinational brands. Minas Gerais and Rio Grande do Sul host emerging contract packaging clusters serving private-label retail brands.
Beverage Packaging Machine Market Competitive Landscape
Capability concentration sits with full-line OEMs commanding integrated system architectures; scale advantage sits with regional fabricators serving price-sensitive emerging markets. The vendor base organizes around three strategic archetypes: European precision-engineering houses with global installed bases, Asian cost-optimized builders capturing mid-speed segments, and North American packaging conglomerates consolidating through serial acquisition. Dominant competitive moves include predictive maintenance contract unbundling to secure recurring revenue streams, and aluminum can line retrofit offerings targeting format shift demand.
Within the European precision tier, Krones AG exemplifies the full-line OEM archetype with its Bavarian manufacturing base and extensive service infrastructure. GEA Group occupies a comparable position in dairy and alcoholic beverage processing systems. Sidel Group represents specialized aseptic technology leadership, anchoring the premium segment for ambient-stable juice and dairy applications. Tetra Pak sits within the material-integrated packaging archetype, controlling carton know-how from liquid packaging board through shelf-ready formats.
| Leading Market Players |
|---|
| GEA Group |
| KHS Group |
| Krones AG |
| Sidel Group |
| Tetra Pak |
| Syntegon Technology |
| Coesia |
| ProMach |
| Barry-Wehmiller Companies |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp corridor freight costs transmit stainless steel price volatility from German precision-component clusters to bottling plants across the European Union, compressing margins on custom-fabricated contact surfaces while amplifying price differentiation between full-line OEMs and regional fabricators.
Pricing Analysis
Predictive maintenance contract tiers now anchor lifetime value capture, with sensor-enabled uptime guarantees displacing traditional break-fix models across multi-site bottling groups. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales bundling intensity and certification grade, with CE-MDR validation timelines extending quotation validity periods. Cost compression in mid-speed segments intensifies because Indian PLI scheme incentives localize demand previously served by used European equipment. Contract packagers in emerging markets exhibit highest price sensitivity; integrated multinational beverage manufacturers absorb premium equipment costs for throughput gains above 60,000 units per hour.
Supply Chain Analysis
Supplier-financing facilities from Baden-Württemberg pneumatic valve manufacturers extend payment terms to 90 days, easing working capital pressure for Asian cost-optimized builders. Precision servo drives and Grade 316L stainless steel contact surfaces draw from Germany, Italy, and Japan, with component qualification protocols tethered to FDA food contact and EU MDR machinery safety dual certification. Single-source vulnerability concentrates in Bavarian precision pneumatic suppliers, exposing non-European builders to extended lead time risk. Distribution runs through OEM direct sales for full-line systems and specialized distributors for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions; dual FDA-EU certification requirements and extended validation timelines create switching costs that lock in established supplier relationships.
For Market Incumbents: Entrench position by deepening predictive maintenance contract penetration to secure recurring revenue streams against emerging specialized service providers. Add certified retrofit capacity in India to capture PLI scheme-driven demand before regional fabricators scale. Invest in REACH-compliant elastomer validation to preempt gasket material substitution disruption from fluorinated compound restrictions. For New Entrants and Emerging Players: India's contract packaging corridors offer the most penetrable white-space, where mid-speed filling line demand outstrips localized supply under PLI scheme incentives. Target aluminum can line conversion projects at legacy PET-dedicated facilities in North America, where format shift demand runs ahead of OEM retrofit capacity. Pursue sensor-enabled predictive maintenance unbundling as the primary go-to-market angle to bypass capital expenditure committee gatekeeping. For Investors and Strategic Acquirers: Regional aftermarket service specialists with captive technician networks present the most compelling acquisition target archetype, given mechatronics skill scarcity and predictive maintenance contract displacement trends. Long-term viability rests on installed base density and service contract renewal rates rather than equipment shipment cyclicality. Watch for CE-MDR certification backlog clearance as the signal indicating inflection in new platform launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Unbundling | Sensor-enabled uptime guarantees displace break-fix models among multi-site bottling groups. |
| Aluminum Can Line Retrofit Offering | Format shift demand from sparkling water and craft beer proliferation opens legacy PET facility conversions. |
| REACH-Compliant Elastomer Validation | Alternative gasket materials preserve microbial barrier properties without fluorinated compounds. |
| India PLI Scheme Localization | Domestic manufacturing incentives displace used European equipment with mid-speed filling lines. |
| Edge Computing Control Architecture | Embedded servo drive analytics compress changeover times for high-volume carbonated bottlers in Germany. |
Research Methodology
Cross-validation between maintenance director interviews at multi-site bottling groups and OEM aftermarket service heads anchors the qualitative findings on predictive maintenance contract displacement. Plant engineers, procurement leads at beverage manufacturers, and regulatory affairs specialists provided primary input on CE-MDR validation timelines and dual certification burden impacts. Secondary validation drew from EU F-Gas Regulation implementation reports, FDA food contact guidance documents, and India PLI scheme administrative data. Bottom-up line-by-line demand modeling and top-down macroeconomic factor adjustment ensured triangulation integrity.
Calibration against historical replacement cycle data and stainless steel price elasticity patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span machine type, packaging material, application liquid chemistry, and end-user procurement sophistication, with regional regulatory cluster effects modeled separately. CAGRs derive from installed base expansion rates and aftermarket service revenue conversion assumptions. EU Green Deal packaging waste target compliance costs and F-Gas Regulation energy threshold impacts feed directly into replacement demand modeling.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian cost-optimized builders or specialized predictive maintenance service providers would shift outcomes. Macroeconomic deviation, regulatory acceleration of refrigerant phase-downs, or breakthrough aseptic sterilization technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.