
 Urine Flow Meters Market | 2026-2036
Urine Flow Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Flow Meters Market Outlook
The capital-intensity divergence between high-end electromagnetic system manufacturers and basic pressure-sensor assembly houses is redrawing competitive boundaries in urine flow diagnostics. Laborie leverages its integrated urodynamics platform to anchor premium hospital contracts across North America and Europe. MEDKONSULT Medical Technology competes through specialized distribution in Central European outpatient clinics, while Medica S.p.A. sustains manufacturing scale in tabletop systems for Mediterranean public health networks.
Urine flow meters measure voiding volume and flow rate during micturition, typically employing gravimetric load cells or ultrasound transit-time sensors with accuracy thresholds of ±2% to support clinical urodynamic assessment. Handheld and portable configurations dominate ambulatory and home care deployment, whereas continuous flow systems command higher margins in research and nephrology settings. Electromagnetic technology leads in precision-critical urology applications, while pressure sensor platforms occupy cost-sensitive clinic segments where reimbursement constraints limit capital expenditure.
FDA 510(k) premarket notification requirements shape product development timelines and clinical validation burdens for devices entering the United States, while the EU Medical Device Regulation (MDR) imposes stricter post-market surveillance and notified body oversight on European market access. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification in both jurisdictions. Stakeholders must weigh regulatory pathway complexity against addressable patient volume when prioritizing geographic expansion or technology platform investments.
Market Dynamics
Connected diagnostic platforms are compressing replacement cycles for standalone urine flow meters as urology clinics in Germany and hospital networks across the United States Midwest consolidate procurement around integrated urodynamics systems.
Growth Catalysts
- EU MDR post-market surveillance mandates:Stricter notified body oversight accelerates hospital upgrades to certified electromagnetic flow systems, displacing legacy pressure-sensor devices in tertiary care settings.
- Ambulatory surgery center expansion:Outpatient urology clinics in Central Europe drive portable handheld configurations for same-day diagnostic workflows.
- Gravimetric load cell miniaturization:Advances in precision weighing technology enable home care deployment with clinical-grade accuracy thresholds.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing dependence on Chinese refining capacity creates input cost volatility for electromagnetic sensor manufacturers.
- FDA 510(k) documentation tightening:Extended clinical validation timelines for digital urology equipment delay market entry for novel transit-time ultrasound platforms.
- Disposable catheter substitution:Single-use urodynamic catheters in cost-sensitive Mediterranean public health networks displace capital-intensive reusable flow meter systems.
Strategic Opportunities
- Home care reimbursement expansion:Remote patient monitoring codes in United States Medicare create new channel economics for Bluetooth-enabled portable units.
- AI-assisted waveform analysis:Machine learning convergence with ultrasound transit-time sensors enables automated obstruction pattern recognition without specialist interpretation.
- Polish outpatient clinic network growth:Underpenetrated Central European urology infrastructure offers first-mover positioning for tabletop system distributors.
Industry Challenges
- ISO 13485 quality management certification:Small-scale pressure-sensor assembly houses face 12-18 month compliance timelines to qualify for hospital procurement frameworks.
- Legacy urodynamics platform integration:Electromagnetic flow meters must interface with proprietary data formats from installed base systems in North American academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Flow Meters Market |
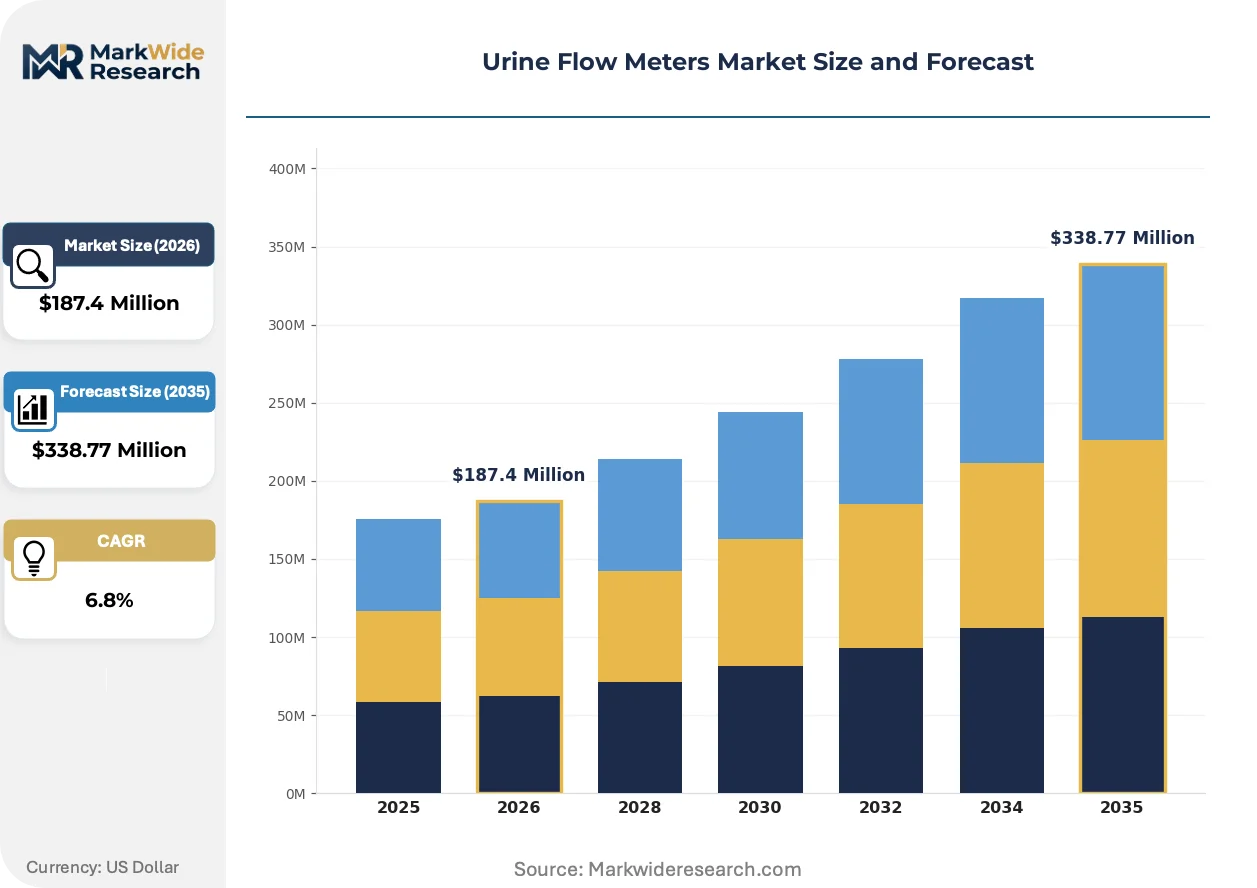
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Table-Top, Continuous Flow End User: Hospitals, Clinics, Home Care, Laboratories Technology: Ultrasound, Electromagnetic, Pressure Sensor, Thermal Application: Urology, Nephrology, Diagnostics, Research |
| Companies Covered | Laborie, MEDKONSULT Medical Technology, Medica S.p.A., Apex Meditech, Dantec Dynamics, Best Smart Medical, HC Italia, Santron Meditronic, Schippers Medizintechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Flow Meters Market Strategic Shifts
Digital connectivity standards and sensor fusion architectures are reconfiguring how voiding diagnostics integrate into broader urological care pathways, with implications for device form factors and service delivery models.
Electromagnetic flow measurement is fragmenting the premium diagnostic segment as manufacturers embed multi-parameter sensing into compact catheter-compatible housings. Tertiary care hospital networks in the United States Southeast adopt these platforms for combined pressure-flow studies. The technology is fragmenting historical boundaries between standalone flow meters and full urodynamics workstations.
EU MDR Article 10 general safety and performance requirements now mandate clinical evidence portfolios for Class IIa urology devices, extending notified body review timelines. German urology clinics front-load procurement decisions to secure legacy device inventories before certificate expiration deadlines. Mediterranean public health networks delay purchasing until MDR-designated body capacity stabilizes.
Hospital procurement committees now bundle urine flow diagnostics with comprehensive urodynamics service contracts, unbundling capital equipment from per-test consumable pricing. Independent urology clinics in Central Europe resist this shift, favoring device ownership with lower lifetime cost profiles. The tension concentrates most visibly in Poland and Czech Republic outpatient markets where reimbursement rates favor capital efficiency over operational flexibility.
Urine Flow Meters Market Segmentation
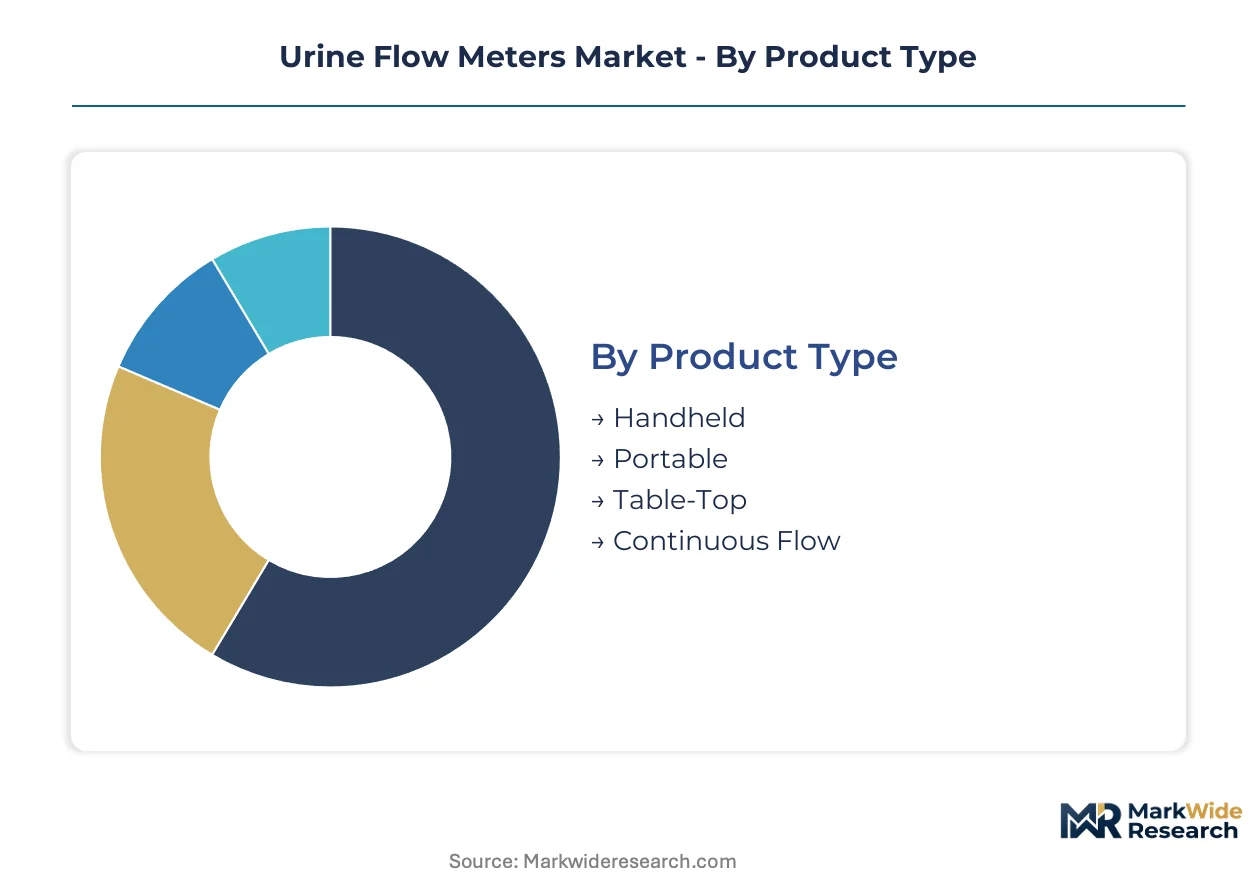
Product configuration, sensing technology, and care setting interact to determine margin structure and replacement dynamics in urine flow diagnostics. Procurement committees evaluate these trade-offs against reimbursement codes and integration requirements.
Product Type:
Portable configurations face the most acute substitution pressure from smartphone-connected weighing systems in home care, while continuous flow systems remain insulated by research protocol requirements.
- Handheld:Battery-operated units with gravimetric load cells deploy in ambulatory surgery centers for same-day diagnostic workflows. Demand concentrates in Polish and Czech outpatient clinics where reimbursement favors capital ownership over service contracts.
- Portable:Bluetooth-enabled devices with clinical-grade accuracy thresholds capture Medicare remote patient monitoring codes in the United States. Southeast hospital networks consolidate procurement around these units for satellite clinic deployment.
- Table-Top:Fixed-installation systems serve Mediterranean public health networks with constrained capital budgets.
- Continuous Flow:Research-grade electromagnetic platforms command premium pricing in nephrology and academic medical centers.
Portable systems anchor the volume base while continuous flow configurations gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital procurement from reimbursement-constrained clinic segments.
- Hospitals:Tertiary care networks in the United States Midwest and Southeast bundle flow diagnostics with comprehensive urodynamics service contracts. Electromagnetic platforms dominate where combined pressure-flow studies require precision instrumentation.
- Clinics:German urology clinics front-load procurement of connected diagnostic devices ahead of EU MDR certificate expiration deadlines.
- Home Care:Gravimetric load cell miniaturization enables clinical-grade accuracy in patient-operated settings.
- Laboratories:Research protocols specify continuous flow electromagnetic systems for longitudinal voiding studies.
Hospitals anchor the volume base while home care expands most quickly.
Technology:
Supply concentration in rare earth processing creates input cost volatility that reshapes competitive boundaries between sensing architectures.
- Ultrasound:Transit-time sensors with automated waveform analysis enable obstruction pattern recognition without specialist interpretation. FDA 510(k) documentation tightening delays market entry for novel platforms in the United States.
- Electromagnetic:Neodymium-dependent precision systems displace legacy pressure-sensor devices in EU tertiary care settings under MDR post-market surveillance mandates.
- Pressure Sensor:Basic assembly houses face 12-18 month ISO 13485 compliance timelines to qualify for hospital procurement frameworks.
- Thermal:Niche research applications in temperature-compensated flow measurement occupy limited commercial footprint.
Electromagnetic technology anchors the volume base while ultrasound climbs the fastest.
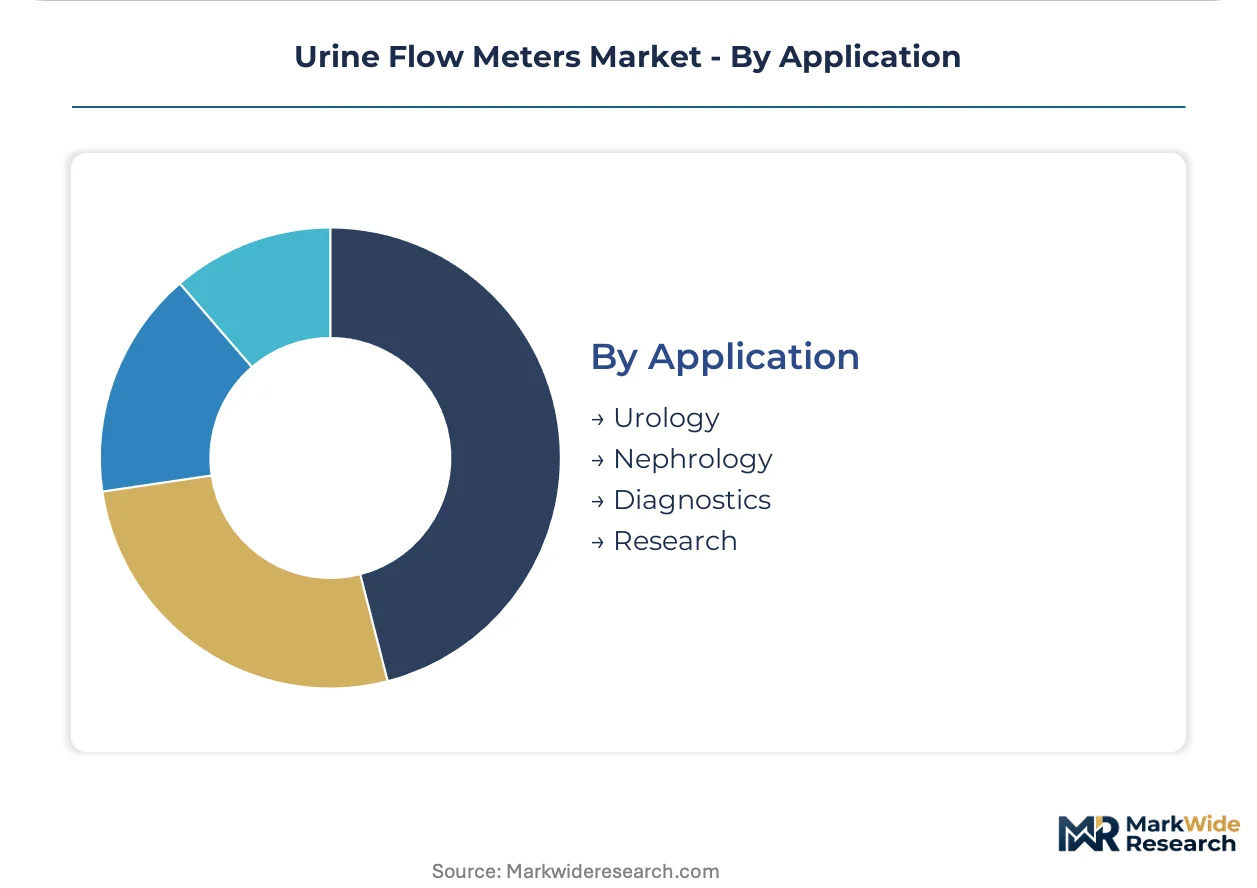
Application:
Maturity differentiation separates established urology protocols from emerging AI-assisted diagnostic pathways.
- Urology:Integrated urodynamics platforms consolidate standalone flow meter replacement cycles in North American and European hospital networks.
- Nephrology:Precision-critical applications specify electromagnetic measurement for renal function monitoring in academic medical centers.
- Diagnostics:Outpatient workflows in Central Europe drive portable handheld adoption for same-day assessment.
- Research:Continuous flow systems with proprietary data format compatibility command premium positioning in longitudinal studies.
Urology anchors the volume base while diagnostics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in urine flow diagnostics tilt toward net importing in high-reimbursement markets while manufacturing concentrates in European precision-device clusters. Currency-adjusted procurement costs widen price gaps between German-engineered electromagnetic systems and Asian-assembled pressure-sensor alternatives.
United States
Tertiary care hospital networks in the Midwest and Southeast bundle urodynamics service contracts with electromagnetic flow meter procurement. FDA 510(k) premarket notification requirements tighten documentation burdens for digital urology equipment entering the market. Boston and Minneapolis academic medical centers anchor research-grade continuous flow system demand for combined pressure-flow studies.
Germany
Urology clinics front-load connected diagnostic device procurement ahead of EU MDR certificate expiration deadlines. Stricter notified body oversight under MDR Article 10 accelerates hospital upgrades to certified electromagnetic flow systems. Bavaria and North Rhine-Westphalia concentrate manufacturing of precision load cells and sensor housings for tabletop system exports.
Italy
Mediterranean public health networks delay purchasing until MDR-designated body capacity stabilizes, constraining capital budget deployment. Disposable catheter substitution pressures reusable flow meter system demand in cost-sensitive procurement frameworks. Lombardy and Emilia-Romagna host assembly operations for mid-tier pressure-sensor devices serving Southern European clinics.
Poland
Outpatient clinic network growth drives handheld gravimetric system demand where reimbursement favors capital ownership over service contracts. Underpenetrated Central European urology infrastructure offers first-mover positioning for tabletop distributors. Warsaw and Krakow clusters concentrate procurement decision-making for regional hospital network consolidation.
China
Rare earth processing dependence for neodymium magnets creates input cost volatility rippling through electromagnetic sensor supply chains. NMPA regulatory pathways for Class II urology devices extend clinical validation timelines compared to legacy provincial approval routes. Yangtze River Delta manufacturing bases assemble pressure-sensor platforms for cost-sensitive export markets.
Urine Flow Meters Market Competitive Environment
Concentration sits with integrated urodynamics platform specialists anchoring premium hospital contracts across North American and European networks. The vendor base stratifies between high-end electromagnetic system manufacturers and basic pressure-sensor assembly houses serving reimbursement-constrained clinics. Three archetypes dominate: precision-device multinationals with full urodynamics portfolios, regional tabletop specialists with Mediterranean public health relationships, and emerging portable-device entrants targeting home care reimbursement expansion. Competitive moves center on M&A consolidation of sensor technology capabilities and strategic partnerships with urology clinic networks for integrated service contracts.
Among European-anchored precision-device manufacturers, Laborie, MEDKONSULT Medical Technology, and Medica S.p.A. represent distinct strategic positioning archetypes. Laborie exemplifies the integrated platform multinational with comprehensive urodynamics service bundling. MEDKONSULT Medical Technology GmbH occupies a position within Central European distribution-focused specialists. Medica S.p.A. anchors the Mediterranean manufacturing-scale tier for public health network supply.
| Leading Market Players |
|---|
| Laborie |
| MEDKONSULT Medical Technology |
| Medica S.p.A. |
| Apex Meditech |
| Dantec Dynamics |
| Best Smart Medical |
| HC Italia |
| Santron Meditronic |
| Schippers Medizintechnik |
| Others |
Value Chain & Pricing Dynamics
Long-term service bundling contracts lock in electromagnetic flow meter procurement for United States tertiary care networks while freezing price visibility for portable device segments exposed to spot component markets. German urology clinics front-load connected diagnostic purchases ahead of EU MDR deadlines, compressing negotiation windows for pressure-sensor assembly houses.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels based on ISO 13485 certification grade and after-sales service bundling. Electromagnetic platforms with full urodynamics integration command premium positioning against basic pressure-sensor alternatives. Pricing pressure stems from disposable catheter substitution in Mediterranean public health networks. Outpatient clinics in Central Europe exhibit highest price sensitivity due to reimbursement constraints favoring capital ownership.
Supply Chain Analysis
Inbound logistics costs through Yangtze River Delta ports create volatility ripples for neodymium magnet-dependent electromagnetic sensor manufacturers. Rare earth processing concentrates in China while precision load cell manufacturing clusters in Germany and sensor housing fabrication localizes in Italy. Single-source vulnerability sits with Chinese refining capacity for critical magnetic inputs. Distribution runs through specialized medical device distributors with hospital GPO relationships in North America and direct clinic sales networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in United States hospital network procurement committees and German urology clinic chains, fragmenting price-setting leverage for standalone device manufacturers.
For Market Incumbents: Shield premium positioning by deepening backward integration into neodymium magnet supply through long-term offtake agreements with Yangtze River Delta processors. Accelerate ISO 13485 certification pipelines for pressure-sensor assembly subsidiaries to qualify for hospital procurement frameworks before EU MDR deadlines compress qualified supplier pools. For New Entrants and Emerging Players: Lead with Bluetooth-enabled portable units targeting Medicare remote patient monitoring reimbursement expansion in United States Southeast satellite clinics. Polish outpatient networks offer lowest competitive density for gravimetric handheld systems where capital ownership models dominate service contracts. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors precision-device multinationals with full urodynamics portfolios over fragmented pressure-sensor assembly houses. Five-to-ten year viability hinges on electromagnetic technology convergence with AI-assisted waveform analysis. Watch FDA 510(k) clearance velocity for novel transit-time ultrasound platforms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Front-loaded procurement in German clinics ahead of notified body capacity constraints secures market positioning. |
| Neodymium Supply Agreement | Long-term rare earth offtake with Chinese processors insulates electromagnetic sensor cost structures. |
| Medicare Reimbursement Strategy | Remote patient monitoring code alignment unlocks portable device channel economics in United States. |
| AI Waveform Software Development | Machine learning integration with ultrasound transit-time sensors reduces specialist interpretation dependency. |
| Polish Distribution Partnership | First-mover clinic network relationships capture underpenetrated Central European urology infrastructure. |
Study Parameters
Initial hypotheses were tested against primary input from urology clinic procurement managers, hospital biomedical engineers, GPO contracts specialists, and medical device regulatory consultants and refined through secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS reimbursement code updates. Bottom-up demand modeling triangulated with top-down market sizing across product configuration, sensing technology, end-user setting, and geographic regulatory clusters.
Variance decomposition isolates volume and value drivers across the projection horizon through segmented elasticity modeling. Product type, technology platform, care setting, and regional reimbursement framework dimensions structure the analytical architecture. CAGRs derive from installed base replacement dynamics, reimbursement code expansion trajectories, and regulatory pathway timeline compression. Forecast inputs incorporate electromagnetic sensor cost curves and portable device miniaturization learning rates.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EU MDR notified body oversight regimes; material policy shifts would require re-modeling. Neodymium supply disruptions, Medicare remote monitoring code revisions, or MDR certificate expiration deadline extensions represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Robotic Services Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market