
 North America Outbound Medical Tourism Services Market | 2026-2036
North America Outbound Medical Tourism Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Outbound Medical Tourism Services Market Outlook
Aftermarket service revenue from post-procedure follow-up and complication management is narrowing as a distinct margin pool, with providers increasingly bundling these costs into upfront package pricing. Bumrungrad International Hospital anchors its competitive position through JCI-accredited facilities and dedicated international patient coordinators. Medical Tourism Corporation leverages extensive hospital networks across Latin America and Asia to sustain referral volume. Apollo Hospital Enterprise Limited dominates complex cardiac and orthopedic procedures through its Chennai and Hyderabad super-specialty centers.
Outbound medical tourism services encompass the arrangement, facilitation, and delivery of elective and semi-urgent healthcare procedures performed outside a patient's home country, typically involving pre-travel consultation, procedure scheduling, accommodation logistics, and post-operative repatriation care. Cosmetic surgery and dental procedures attract the highest individual patient volumes due to substantial cost differentials relative to North American pricing, while fertility treatments represent the fastest-growing service type as domestic restrictions and wait times drive cross-border demand. Package deals and facilitator services capture the most favorable margin pools by aggregating opaque hospital pricing, travel logistics, and insurance coordination into transparent bundled offerings. Direct booking channels remain limited to experienced repeat patients with established provider relationships.
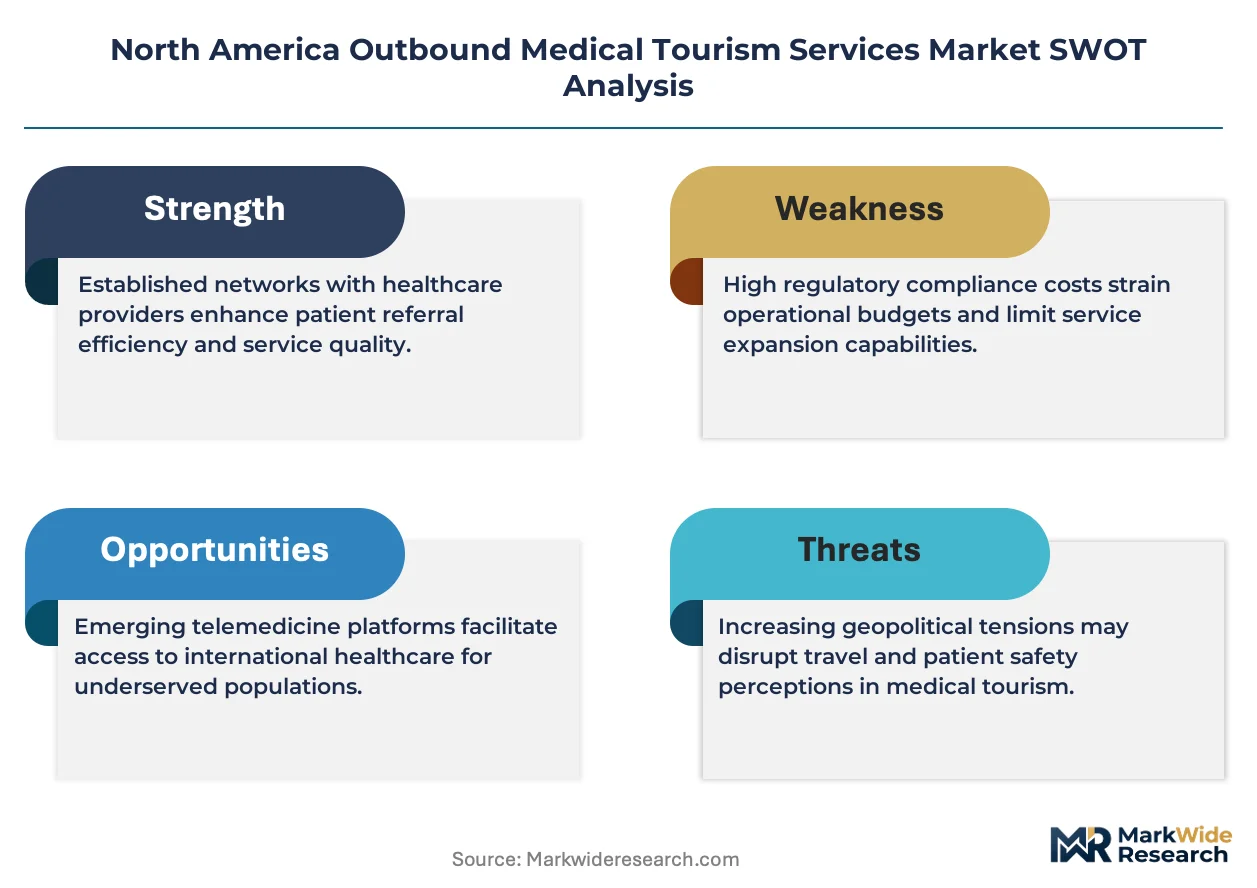
FDA oversight of medical device standards and biologic product quality indirectly shapes patient confidence in offshore procedures using imported implants and pharmaceuticals. HIPAA privacy frameworks complicate electronic health record transfers between North American originators and foreign treatment facilities, creating operational friction that facilitators must navigate. Mexico's COFEPRIS registration requirements and Thailand's Ministry of Public Health hospital licensing standards determine which facilities qualify for international patient programs. Stakeholders must monitor evolving state-level insurance reimbursement policies and accreditation portability agreements that could either legitimize or constrain cross-border care financing models.
Market Dynamics
High-deductible health plans and coverage gaps under the Affordable Care Act are compressing domestic care access, redirecting elective procedure demand toward accredited offshore facilities that bundle transparent pricing with travel logistics.
Growth Catalysts
- Cost-containment mandates:Corporate wellness programs now explicitly authorize cross-border care for scheduled procedures, channeling employee volumes through pre-vetted hospital networks in Mexico and Costa Rica.
- Thailand's Ministry of Public Health licensing:Stringent facility accreditation standards for international patient programs build payer confidence, accelerating insurer pilot programs for covered offshore treatment.
- Fertility treatment restrictions:Domestic wait times and regulatory limitations on assisted reproductive technologies propel patients toward jurisdictions with permissive frameworks and immediate availability.
Market Restraints
- HIPAA friction:Privacy framework incompatibilities complicate electronic health record transfers between US originators and foreign treatment facilities, creating documentation delays and liability exposure.
- Implant supply concentration:FDA-cleared medical devices and biologic products for offshore procedures remain concentrated among US and EU manufacturers, limiting cost arbitrage on hardware-intensive interventions.
- COFEPRIS registration timelines:Mexico's pharmaceutical and device approval processes extend facility qualification periods, constraining rapid network expansion for nearshore programs.
Strategic Opportunities
- Central American corridor development:Costa Rica and Panama offer underpenetrated capacity for cardiac and orthopedic recovery tourism, with shorter flight times than Asian alternatives.
- Telemedicine integration:Pre-operative consultation and post-operative monitoring via remote platforms reduce required travel duration, opening the market to time-constrained professional segments.
- State-level reimbursement pilots:Experimental Medicaid waivers and public employee benefit programs in select US states may legitimize cross-border care financing, creating template policies for broader adoption.
Industry Challenges
- International patient coordination:Facilitators face persistent talent scarcity in multilingual care navigation and complex case logistics, degrading service consistency at scale.
- JCI accreditation maintenance:Joint Commission International standards require continuous facility investment and documentation, pressuring margin structures for mid-tier hospital partners.
- Complication management liability:Post-procedure adverse events occurring after patient repatriation create jurisdictional ambiguity in malpractice coverage and follow-up responsibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Outbound Medical Tourism Services Market |
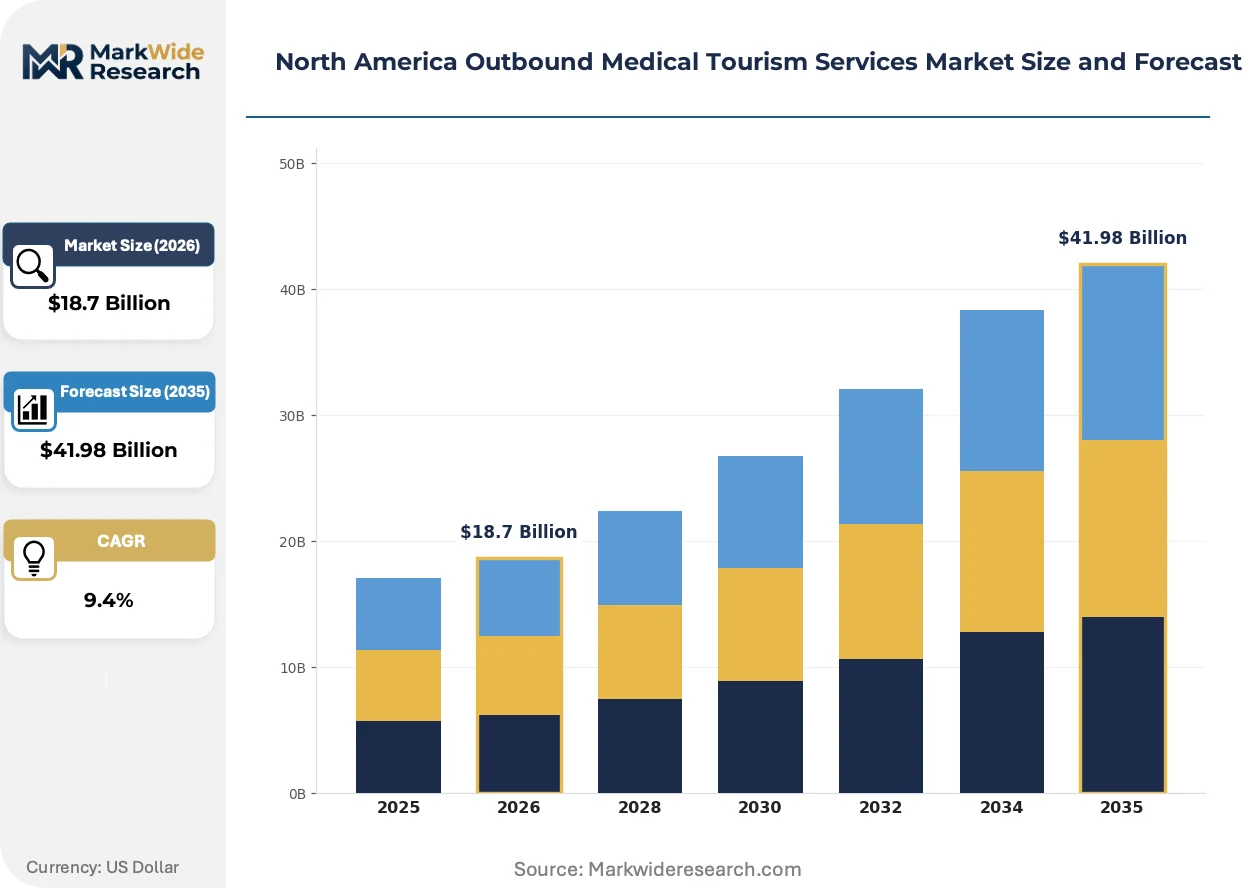
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Procedures, Fertility Treatments, Orthopedic Surgery Delivery Model: Direct Booking, Package Deals, Facilitator Services, Insurance Coverage End User: Individuals, Corporations, Insurance Companies, Travel Agents Destination Type: Developing Countries, Emerging Markets, Developed Countries, Others |
| Companies Covered | Apollo Hospital Enterprise Limited, Bumrungrad International Hospital, KPJ Healthcare Berhad, Christus Muguerza Hospital, WorldMed Assist, Mednamaste, Global Medical Tourism Inc., Medical Tourism Corporation, Universal Medical Travel, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Outbound Medical Tourism Services Market Strategic Shifts
Digital platforms are restructuring how patients discover, compare, and commit to offshore care, replacing opaque broker relationships with algorithmic matching and verified outcome transparency.
Telemedicine infrastructure is hybridizing pre-operative assessment and post-discharge monitoring into continuous care loops that span borders. US-based employers with self-funded health plans are piloting integrated platforms that connect employees to Costa Rican and Mexican facilities for bundled procedures. This convergence compresses the traditional facilitator intermediary layer, transferring margin capture to technology-enabled payers and hospital systems with direct digital reach.
HIPAA compliance frameworks are tightening documentation standards for cross-border electronic health record exchanges. The US Department of Health and Human Services has issued guidance clarifying Business Associate Agreement requirements for offshore data processors, forcing facilitators to restructure vendor contracts. Facilitators serving US patient volumes are responding by investing in encrypted, jurisdictionally segmented data architectures that satisfy both domestic privacy mandates and foreign hospital operational needs.
Employer-sponsored health benefit designs are rotating procurement authority toward specialized cost-containment vendors that manage offshore care as a covered benefit category. Large self-insured employers in manufacturing and hospitality sectors are displacing traditional insurance administrators with medical tourism-specific third-party administrators. This shift is most visible in Texas and Florida, where high uninsured rates and proximity to Mexican border facilities create favorable economics for pilot programs.
North America Outbound Medical Tourism Services Market Segmentation
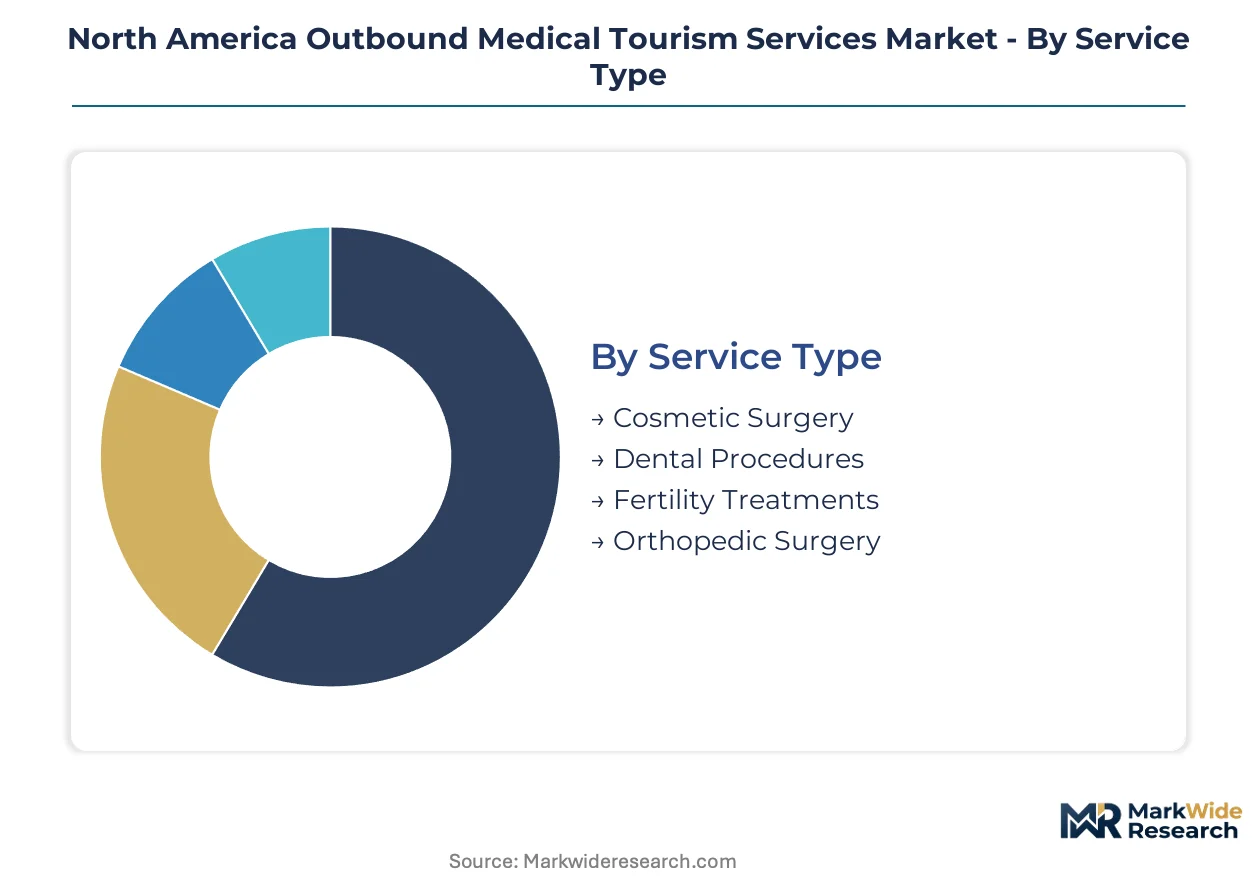
Segmentation in outbound medical tourism services reveals how patient risk tolerance, price sensitivity, and care complexity determine channel selection and destination matching. Understanding these divides enables facilitators and payers to design targeted offerings that align procedure types with appropriate logistics and financing structures.
Service Type:
Mature segments with established cost arbitrage dominate current volumes, while emerging categories driven by regulatory gaps and domestic access constraints are accelerating most quickly.
- Cosmetic Surgery:Elective aesthetic procedures including rhinoplasty, liposuction, and breast augmentation command substantial patient flows due to 60-80% cost differentials versus domestic pricing. Demand concentrates in Mexico and Thailand where JCI-accredited facilities bundle procedures with recovery resort accommodations, driven by Instagram-era appearance standards and limited US insurance coverage.
- Dental Procedures:Complex restorative work, implants, and full-mouth reconstructions attract retirees and uninsured workers seeking same-day turnaround at border clinics. Texas and Arizona patients drive volume into Tijuana and Los Algodones corridor facilities, motivated by Medicare's exclusion of dental benefits and domestic specialist wait times.
- Fertility Treatments:In-vitro fertilization and egg freezing services are climbing the fastest as domestic age restrictions, embryo storage limits, and single-parent prohibitions push patients toward permissive jurisdictions.
- Orthopedic Surgery:Joint replacements and spinal procedures attract self-funded employers and cash-pay patients seeking bundled pricing transparency absent from US hospital billing.
Cosmetic surgery retains volume leadership; fertility treatments hold the steepest expansion curve.
Delivery Model:
Channel structure reflects patient sophistication and risk appetite, with consolidated offerings capturing margin from fragmented direct arrangements.
- Package Deals:Bundled offerings aggregating hospital fees, accommodation, ground transport, and complication insurance into single-price contracts. Corporate wellness programs in Texas and Florida channel employee volumes through pre-negotiated packages with Costa Rican and Mexican hospital networks, eliminating reimbursement friction and surprise billing exposure.
- Facilitator Services:Intermediary coordination spanning provider vetting, medical record translation, travel logistics, and post-operative follow-up scheduling. Medical Tourism Corporation and similar entities sustain referral volume through hospital network breadth across Latin America and Asia, capturing margin from opacity reduction and liability buffering.
- Direct Booking:Experienced repeat patients with established provider relationships bypass intermediaries to negotiate directly with foreign hospitals, compressing facilitator margins.
- Insurance Coverage:Experimental payer pilots and self-funded employer carve-outs treating offshore care as in-network benefits remain limited but expanding.
Package deals dominate transaction volume; insurance coverage models are gaining share fastest as pilot programs mature.
End User:
Buyer sophistication spans uninformed first-time patients to institutional purchasers with dedicated procurement functions.
- Individuals:Self-directed patients researching procedures through digital platforms and patient forums, typically funding through savings or medical credit products. Uninsured and underinsured Americans facing high-deductible plan thresholds dominate this segment, with search intensity peaking in border states and retirement corridors.
- Corporations:Self-insured employers in manufacturing, hospitality, and logistics sectors authorizing cross-border care as explicit cost-containment strategy. These entities displace traditional insurance administrators with medical tourism-specific third-party administrators, channeling scheduled procedures through pre-vetted hospital networks.
- Insurance Companies:Traditional payers experimenting with narrow offshore networks for elective procedures, constrained by HIPAA friction and malpractice jurisdiction concerns.
- Travel Agents:Niche operators bundling medical appointments with leisure travel components, serving affluent patients seeking discretion and concierge experience.
Individual patients retain volume leadership; corporate purchasers are expanding their procurement footprint fastest.
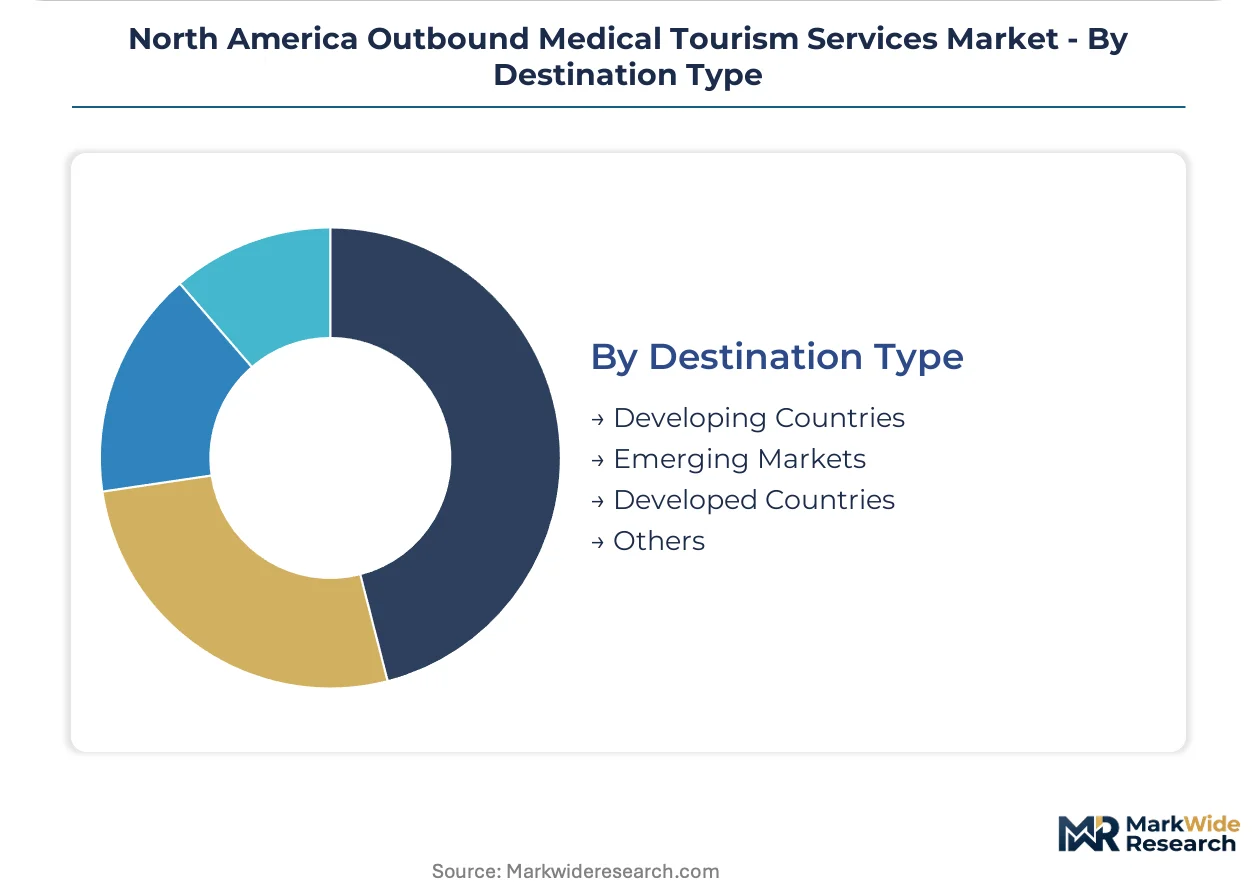
Destination Type:
Facility location determines cost structure, regulatory environment, and repatriation logistics for complication management.
- Developing Countries:Nearshore Mexico and Central American facilities offering 50-70% cost savings with minimal flight duration and timezone alignment. COFEPRIS registration requirements and JCI accreditation maintenance determine facility qualification for international patient programs.
- Emerging Markets:Thailand and selected Southeast Asian destinations combining established medical tourism infrastructure with vacation recovery positioning. Thailand's Ministry of Public Health licensing standards build payer confidence and accelerate insurer pilot program adoption.
- Developed Countries:Canadian and Western European facilities attracting patients seeking procedures unavailable or restricted domestically, particularly fertility and experimental interventions.
- Others:Niche destinations including Middle Eastern and South Asian facilities targeting specific diaspora populations and religiously-compliant care environments.
Developing countries retain volume leadership; emerging markets are capturing expanding share through accreditation investments and direct payer contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American geographies. Border-state patients exhibit extreme price sensitivity, driving volume into Mexican facilities, while coastal metropolitan buyers prioritize accreditation and concierge logistics over pure cost arbitrage.
United States
Texas and Florida patients generate disproportionate outbound volume through proximity to Mexican border clinics and high uninsured populations. HIPAA compliance requirements complicate electronic health record transfers to foreign facilities, creating documentation friction that facilitators must navigate. Houston and Miami serve as coordination hubs where medical tourism-specific third-party administrators manage employer-sponsored pilot programs.
Canada
Domestic wait times for elective procedures propel Canadians toward offshore alternatives, particularly for orthopedic and cardiac interventions. Health Canada maintains oversight of medical device standards that indirectly shape patient confidence in foreign facilities using imported implants. Toronto and Vancouver concentrate facilitator operations serving patients frustrated by provincial healthcare queue lengths.
Mexico
Nearshore positioning and COFEPRIS-registered facilities capture the majority of US outbound volume for dental and cosmetic procedures. Mexico's pharmaceutical and device approval processes extend facility qualification periods, constraining rapid network expansion. Tijuana and Los Algodones anchor the dental tourism corridor serving Arizona and California patients seeking same-day turnaround.
Costa Rica
JCI-accredited hospitals in San José attract cardiac and orthopedic recovery tourism with shorter flight times than Asian alternatives. The country's Ministry of Health licensing standards for international patient programs build payer confidence for corporate wellness carve-outs. Medical City Costa Rica exemplifies the integrated campus model combining surgical facilities with recovery resort amenities.
North America Outbound Medical Tourism Services Market Competitive Environment
Capability concentration sits with hospital operators possessing international accreditation and dedicated patient coordination infrastructure; scale advantage sits with facilitator networks aggregating opaque pricing across multiple jurisdictions. The market structures around three archetypes: destination hospital systems, intermediary facilitators, and employer-facing third-party administrators. Consolidation pressure favors hospital-facilitator vertical integration and direct digital booking platforms displacing traditional broker relationships.
Within the hospital operator tier, Bumrungrad International Hospital and Apollo Hospital Enterprise Limited exemplify accreditation-heavy positioning through JCI-certified facilities and super-specialty service lines. Medical Tourism Corporation occupies the facilitator archetype, sustaining referral volume through network breadth across Latin American and Asian destinations. These three entities represent contrasting geographic anchors—Southeast Asian, South Asian, and Americas-focused respectively—illustrating how regional specialization shapes competitive differentiation in patient sourcing and hospital partnership structures.
| Leading Market Players |
|---|
| Apollo Hospital Enterprise Limited |
| Bumrungrad International Hospital |
| KPJ Healthcare Berhad |
| Christus Muguerza Hospital |
| WorldMed Assist |
| Mednamaste |
| Global Medical Tourism Inc. |
| Medical Tourism Corporation |
| Universal Medical Travel |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in JCI-accredited Costa Rican cardiac facilities drives both supplier investment urgency and pricing power concentration among established hospital operators, while Mexican border clinics absorb price-sensitive overflow volume through lower fixed-cost structures.
Pricing Analysis
After-sales service revenue from post-procedure complication management and follow-up care drives lifetime value capture, with facilitators bundling these into upfront package contracts. Three-tier pricing structure across premium JCI-accredited facilities, standard COFEPRIS-registered hospitals, and economy border clinics reflects accreditation grade and complication insurance inclusion. Cost compression in the economy tier intensifies because Tijuana and Los Algodones dental clinics compete on same-day turnaround speed. Uninsured individuals seeking dental and cosmetic procedures exhibit extreme price sensitivity, while corporate wellness programs prioritize accreditation certainty over marginal cost savings.
Supply Chain Analysis
Upstream feedstock of FDA-cleared medical devices and biologic implants draws from US and EU manufacturing concentration, limiting cost arbitrage on hardware-intensive orthopedic and cardiac interventions. Mexico and Thailand anchor nearshore and offshore facility networks, with Costa Rica emerging as a Central American recovery tourism hub. Supply chain risk centers on single-source vulnerability for specialized implants and HIPAA-compliant electronic health record transfer infrastructure. Distribution runs through facilitator-mediated package deals, direct hospital booking platforms, and employer-facing third-party administrators piloting integrated digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America outbound medical tourism services represent early-cycle expansion, with corporate wellness program adoption and state-level reimbursement pilots accelerating penetration beyond traditional cash-pay individual segments.
For Market Incumbents: Pre-empt margin erosion from technology-enabled direct booking platforms by deepening hospital-facilitator vertical integration and securing exclusive JCI-accredited capacity in Costa Rica and Mexico. Invest in multilingual patient coordination talent pools to defend service consistency against digital intermediaries. HIPAA compliance infrastructure serves as a defensible moat against unqualified entrants. For New Entrants and Emerging Players: Pursue underpenetrated Central American cardiac and orthopedic recovery tourism corridors in Panama and Guatemala, where flight time advantages over Asian alternatives remain unexploited. Target corporate wellness programs in Texas and Florida manufacturing sectors with telemedicine-integrated pre-operative assessment platforms. Go-to-market leverage rests on direct employer contracting rather than consumer-facing digital acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among facilitator networks with locked-in corporate wellness contracts and multi-year hospital partnership agreements. Long-term viability across a five-to-ten-year horizon favors vertically integrated hospital-facilitator combinations with captive international patient coordination infrastructure. Acquisition priority targets JCI-accredited facility operators in nearshore geographies. The signal to watch is state Medicaid waiver expansion legitimizing cross-border care financing.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Integration | Pre-operative consultation platforms reduce required travel duration for time-constrained professional segments. |
| JCI Accreditation Investment | Joint Commission International certification builds payer confidence for corporate wellness pilot program inclusion. |
| Corporate Wellness Partnership | Direct contracting with self-funded employers displaces traditional insurance administrator intermediaries. |
| HIPAA-Compliant Data Architecture | Encrypted health record transfer infrastructure satisfies US privacy mandates for offshore care coordination. |
| Central American Corridor Development | Costa Rica and Panama capacity expansion captures cardiac recovery tourism with shorter flight times than Asia. |
Study Parameters
A standing panel of hospital international patient coordinators, corporate benefits directors, medical tourism facilitators, and cross-border care compliance attorneys provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against hospital accreditation databases, state-level insurance regulatory filings, and employer-sponsored health plan design documents. Bottom-up procedure volume estimates triangulated against top-down market sizing from payer pilot program disclosures.
Scenario-bracketing framed sensitivity analysis across the projection horizon, modeling service type segmentation by procedure complexity, delivery model by channel consolidation stage, and destination type by regulatory accreditation tier. CAGRs derived from procedure volume growth curves adjusted for corporate wellness program penetration rates and fertility treatment restriction-driven demand elasticity. Forecast inputs incorporated COFEPRIS registration timeline constraints and JCI accreditation maintenance investment requirements.
Macroeconomic conditions sit as an overlay; deviation in employer health benefit cost-containment mandates, state Medicaid waiver approvals, or international travel cost inflation would shift the trajectory. Forecasts reflect documented assumptions regarding HIPAA regulatory enforcement continuity and nearshore facility accreditation standards. Cross-checking against employer health plan procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market