
 Global Surgical Navigation System Market | 2026-2036
Global Surgical Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Navigation System Market Foresight
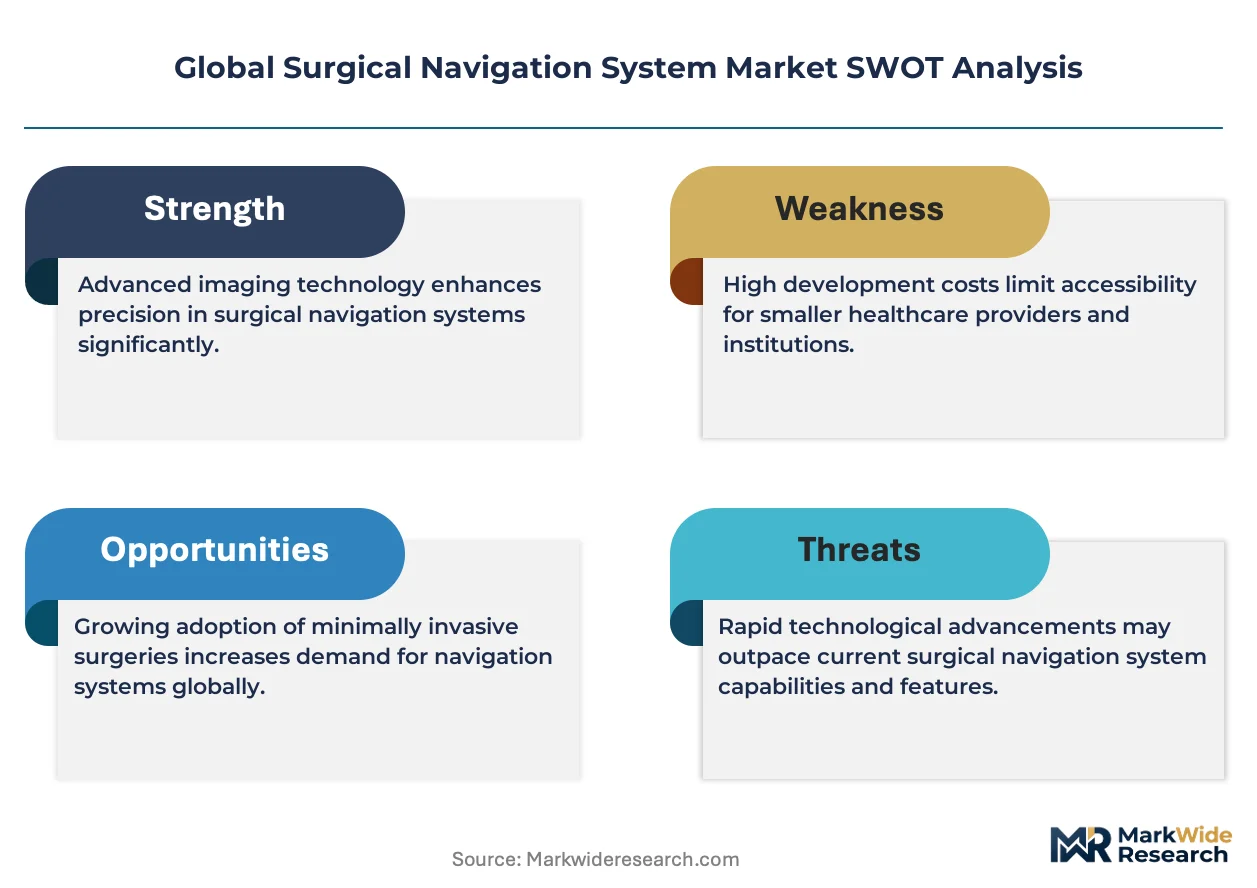
Modular platform bundling is restructuring procurement decisions across hospital systems. Medtronic leverages its spine-implant portfolio to anchor navigation hardware contracts. Stryker competes through its Mako robotic-arm ecosystem integrated with proprietary navigation software. Brainlab AG specializes in software-agnostic cranial platforms that navigate heterogeneous hospital IT environments.
A surgical navigation system comprises intraoperative tracking hardware, patient-registration software, and instrument-guidance interfaces that correlate real-time tool position against preoperative or intraoperative anatomical imaging with sub-millimetric accuracy. Optical systems utilize infrared camera arrays and reflective arrays attached to surgical instruments, while electromagnetic variants employ field generators and sensor-embedded tools for line-of-sight-free tracking. Optical navigation retains dominance in neurosurgery applications where cranial fixation permits unobstructed camera sightlines, whereas electromagnetic technology captures share in orthopedic surgery where surgeon hand positioning varies unpredictably. Augmented reality overlays are gaining fastest traction as headset-based visualization reduces monitor-dependency and streamlines operating room spatial configuration.
The FDA's 510(k) premarket notification process governs US commercial entry, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE marking in European markets. Japan's PMDA operates a phased review system that prioritizes novel navigation algorithms with demonstrated equivalence to predicate devices. Stakeholders must monitor reimbursement codification for navigation-assisted procedures across Medicare, national health services, and private payer frameworks to determine capital investment timing.
Market Dynamics
Modular platform bundling is restructuring procurement decisions across hospital systems, with spine and orthopedic implant portfolios now serving as anchors for navigation hardware contracts rather than standalone capital equipment sales.
Growth Catalysts
- FDA 510(k) Pathway:The streamlined premarket notification process accelerates commercial entry for computer-assisted surgical devices, reducing time-to-market for navigation platform upgrades.
- Aging Demographics in Developed Economies:Joint replacement volumes in the United States, Germany, and Japan create sustained demand for precision instrumentation in orthopedic departments.
- Augmented Reality Visualization:Headset-based surgical overlays reduce operating room spatial constraints and eliminate monitor-dependency during cranial and spinal procedures.
Market Restraints
- Electromagnetic Interference Limitations:Field generator-based tracking systems encounter accuracy degradation near metallic implants, constraining adoption in revision arthroplasty cases.
- Reimbursement Codification Gaps:Medicare and national health services lack consistent procedural codes for navigation-assisted surgeries, creating capital investment uncertainty.
- High Specialist Training Requirements:Sub-millimetric registration protocols demand extended learning curves for surgical teams, slowing deployment in community hospital settings.
Strategic Opportunities
- Software-Agnostic Platform Architecture:Cranial navigation systems interoperable with heterogeneous hospital IT environments capture share in multi-vendor imaging ecosystems.
- India's Expanding Private Hospital Infrastructure:Corporate hospital chains in Mumbai, Delhi, and Bangalore are investing in precision surgery capabilities to differentiate service offerings.
- EU Medical Device Regulation Clinical Evidence Requirements:MDR-mandated post-market surveillance creates competitive moats for manufacturers with established clinical data repositories.
Industry Challenges
- Optical Line-of-Sight Constraints:Infrared camera arrays require unobstructed instrument tracking, complicating adoption in crowded surgical fields and unpredictable hand positioning scenarios.
- Legacy Imaging Format Integration:Preoperative CT and MRI data standardization across PACS vendors creates registration workflow friction and delays intraoperative setup.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Navigation System Market |
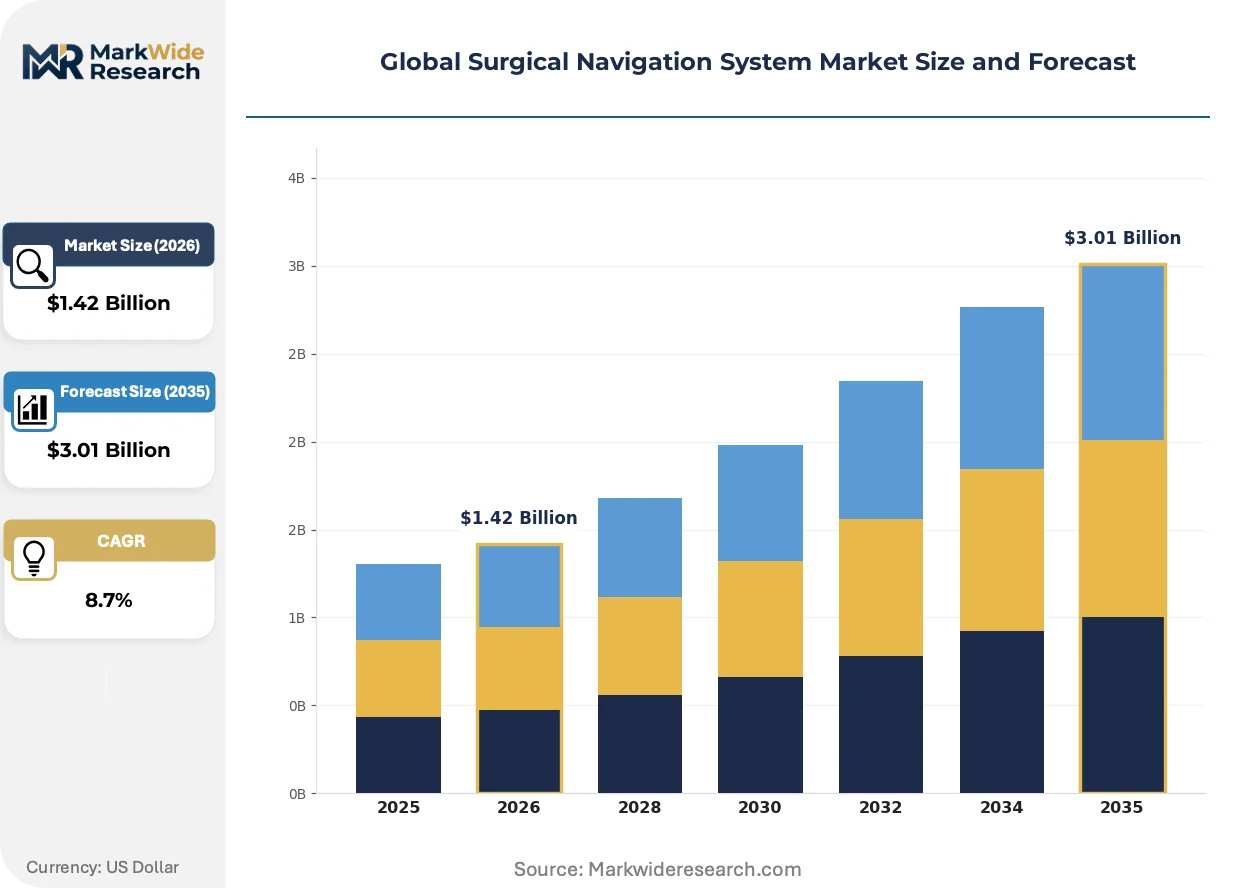
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, Electromagnetic, Hybrid, Ultrasound, Others Technology: 3D Imaging, Intraoperative CT, Fluoroscopy, Augmented Reality, Robotics Assistance Application: Neurosurgery, Orthopedic Surgery, ENT Surgery, Cardiovascular Procedures, Spinal Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes, Diagnostic Centers |
| Companies Covered | Medtronic, Stryker, Brainlab AG, Zimmer Biomet, B. Braun SE, Siemens Healthineers, GE HealthCare, KARL STORZ SE & Co. KG, Smith+Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Navigation System Market Shifts & Advancements
Real-time anatomical correlation capabilities are advancing through sensor miniaturization and algorithmic registration improvements, compressing the gap between preoperative imaging and intraoperative tissue deformation.
Machine learning-based predictive registration is integrating deformable tissue modeling into cranial navigation workflows. Neurosurgery departments at academic medical centers are deploying these algorithms to compensate for brain shift during tumor resection. The technology is integrating patient-specific biomechanical simulations that update instrument guidance in real-time as cerebrospinal fluid drainage alters anatomical geometry.
Japan's PMDA phased review system prioritizes novel navigation algorithms demonstrating equivalence to predicate devices. This regulatory architecture accelerates clearance for software-upgradable platforms while maintaining safety thresholds. European manufacturers are responding by structuring technical documentation to satisfy both PMDA equivalence criteria and EU MDR clinical evidence requirements simultaneously.
Hospital capital committees are consolidating vendor relationships through multi-year platform leases that bundle hardware, software maintenance, and procedural training. Traditional equipment purchasing departments are ceding authority to value analysis committees that evaluate total cost-per-procedure across navigation-assisted interventions. This shift is most pronounced in United States integrated delivery networks where orthopedic service line contracts span multiple facilities.
Global Surgical Navigation System Market Segmentation
Surgical navigation systems fragment across multiple technical and customer dimensions. Capital allocation priorities differ sharply between hardware-intensive tracking modalities and software-centric visualization platforms. Procurement committees evaluate segments through divergent lenses: upfront equipment cost, per-procedure consumables, training burden, and reimbursement capture potential.
Product Type:
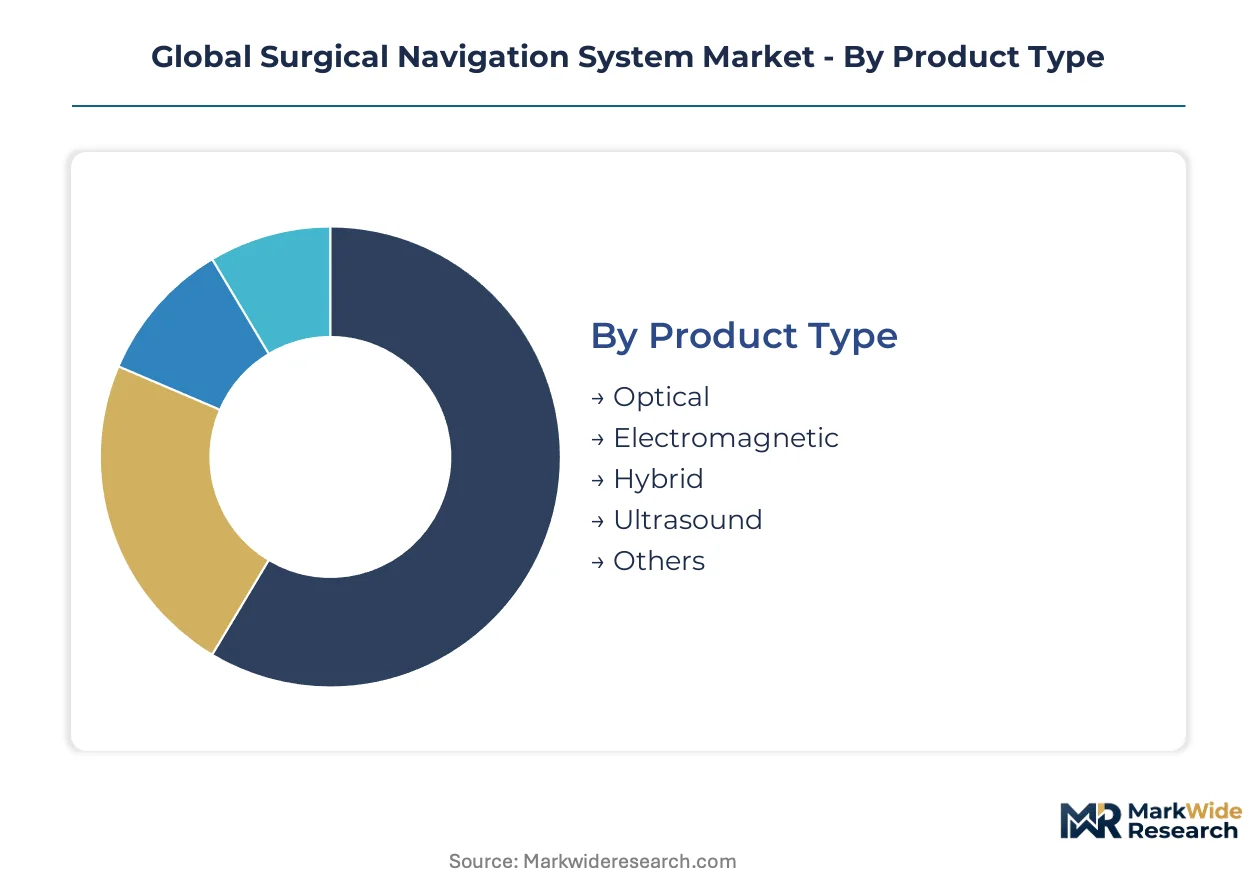
Capital-intensity varies dramatically across tracking modalities, with hybrid platforms demanding the highest upfront investment due to dual-sensor infrastructure and calibration complexity.
- Optical:Infrared camera arrays and reflective instrument arrays deliver sub-millimetric accuracy through direct line-of-sight tracking. Neurosurgery departments at academic medical centers in the United States and Germany anchor demand, driven by cranial fixation protocols that preserve unobstructed camera sightlines during tumor resection procedures.
- Electromagnetic:Field generators and sensor-embedded instruments enable tracking without visual contact, capturing share in orthopedic surgery where surgeon hand positioning varies unpredictably. Accuracy degradation near metallic implants constrains deployment in revision arthroplasty cases across hospital systems in Japan.
- Hybrid:Dual-modality platforms combine optical precision with electromagnetic flexibility for complex spinal procedures requiring both accuracy and positional freedom.
- Ultrasound:Real-time soft-tissue imaging integration supports breast biopsy and abdominal navigation with lower capital barriers than radiographic alternatives.
- Others:Emerging mechanical tracking and inertial measurement unit variants serve niche applications in resource-constrained settings.
Most installed capacity flows through Optical systems. Expansion is steepest in Electromagnetic platforms as orthopedic volumes climb in aging populations.
Technology:
Application urgency determines technology adoption velocity, with intraoperative imaging commanding premium pricing in time-critical neurosurgical workflows.
- 3D Imaging:Preoperative CT and MRI reconstruction enables patient-specific anatomical modeling with volumetric visualization. Neurosurgery departments prioritize this foundation layer for complex cranial approaches, though registration workflow friction across heterogeneous PACS vendors delays setup.
- Intraoperative CT:Mobile scanner integration provides real-time anatomical updates during prolonged procedures. Academic medical centers in Germany and Japan justify capital expenditure through case volume concentration and research protocol requirements.
- Fluoroscopy:C-arm navigation dominates spinal fusion workflows where bone-implant interface verification drives intraoperative decision-making.
- Augmented Reality:Headset-based visualization eliminates monitor dependency and streamlines operating room spatial configuration, gaining fastest traction in cranial applications.
- Robotics Assistance:Integrated arm systems with proprietary navigation software command premium positioning in orthopedic service line contracts.
Deployment concentrates in 3D Imaging infrastructure. Augmented Reality is climbing the fastest as hardware miniaturization reduces headset weight and latency.
Application:
Procedure reimbursement rates and implant attach rates shape segment profitability, with joint replacement workflows supporting navigation hardware amortization through bundled payments.
- Neurosurgery:Cranial navigation demands the highest accuracy specifications and commands premium system pricing. Brain shift compensation algorithms are integrating into academic center workflows in the United States and Japan, updating guidance as cerebrospinal fluid drainage alters anatomical geometry.
- Orthopedic Surgery:Knee and hip arthroplasty volumes drive the largest absolute system deployments. Hospital systems in Germany leverage navigation for alignment precision in value-based care contracts with statutory health insurers.
- ENT Surgery:Sinus and skull base procedures utilize compact navigation platforms with reduced footprint requirements for outpatient surgical suites.
- Cardiovascular Procedures:Electrophysiology and structural heart applications represent emerging adoption frontiers with distinct regulatory pathways.
- Spinal Surgery:Pedicle screw placement accuracy requirements support navigation penetration, though electromagnetic interference near prior implants creates workflow constraints.
System shipments concentrate in Orthopedic Surgery. Neurosurgery maintains the steepest expansion trajectory as deformable tissue modeling matures.
End User:
Capital availability and procedure volume concentration determine customer tier access, with integrated delivery networks extracting volume discounts unavailable to standalone facilities.
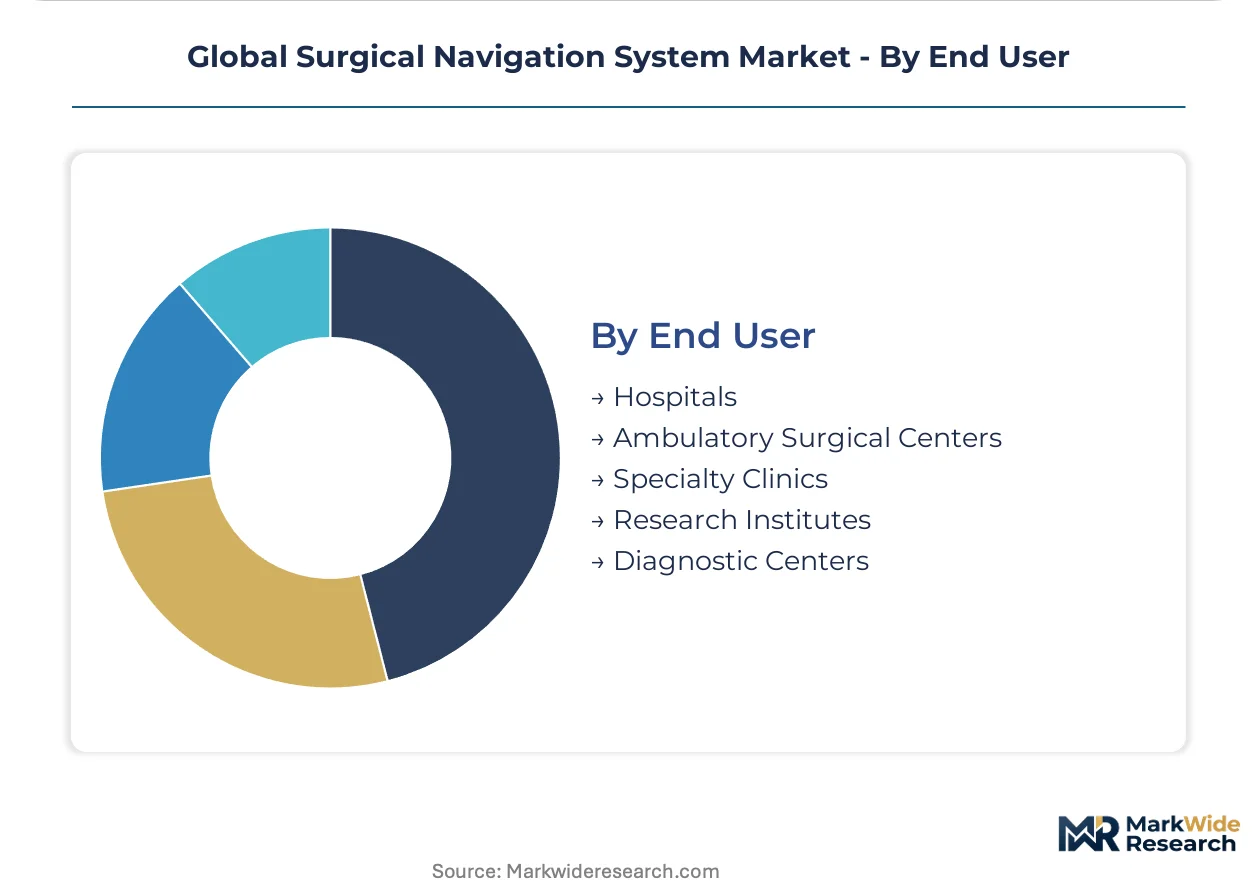
- Hospitals:Academic medical centers and community hospital systems represent the dominant installed base. Value analysis committees in United States integrated delivery networks now control navigation procurement, evaluating total cost-per-procedure across multi-facility orthopedic service lines.
- Ambulatory Surgical Centers:Outpatient joint replacement migration is creating navigation demand in freestanding settings with compressed capital cycles and rapid equipment turnover requirements.
- Specialty Clinics:ENT and spine-focused facilities deploy compact platforms with reduced training overhead for high-volume single-specialty workflows.
- Research Institutes:Algorithm development and clinical validation studies drive non-commercial system acquisitions with distinct funding mechanisms.
- Diagnostic Centers:Preoperative imaging and biopsy navigation support interventional radiology expansion into therapeutic procedures.
Revenue concentrates in Hospital contracts. Ambulatory Surgical Centers are gaining share fastest as outpatient migration accelerates in United States and German reimbursement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical navigation technology first achieved commercial scale in German neurosurgical centers during the early 1990s, establishing the clinical validation frameworks that subsequent regulatory systems adopted worldwide.
United States
Academic medical centers in Boston, Baltimore, and Rochester anchor system deployment for cranial tumor resection workflows. The FDA's 510(k) premarket notification pathway accelerates clearance timelines for algorithm-upgradable platforms. Integrated delivery networks in Texas and California now consolidate procurement across multi-facility orthopedic service lines, extracting volume discounts unavailable to standalone hospitals.
Germany
Statutory health insurer contracts for knee and hip arthroplasty drive navigation adoption for alignment precision in value-based reimbursement frameworks. The EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE marking, creating compliance moats for established manufacturers. Industrial clusters around Munich and Berlin host specialized surgical training centers that compress learning curves for registration protocols.
Japan
Aging demographics in Tokyo, Osaka, and Nagoya sustain joint replacement volumes that justify capital investment in precision instrumentation. The PMDA operates a phased review system prioritizing novel navigation algorithms demonstrating equivalence to predicate devices. Corporate hospital chains in Kansai region are integrating electromagnetic platforms for spinal fusion workflows where line-of-sight constraints complicate optical alternatives.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore invest in navigation capabilities to differentiate premium service offerings for medical tourism segments. The country's national medical device regulator aligns quality standards with international harmonization frameworks while streamlining import licensing for software-upgradable systems. Metro hospital clusters in Maharashtra and Karnataka concentrate training infrastructure for sub-millimetric registration protocols.
United Kingdom
National Health Service procurement frameworks emphasize total cost-per-procedure metrics that favor navigation platforms with reduced revision rates. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence requirements while introducing accelerated access pathways for innovative surgical devices. London and Manchester academic centers lead algorithm validation studies for deformable tissue modeling in neurosurgical applications.
Global Surgical Navigation System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-agnostic versus proprietary ecosystem dimensions. The vendor base stratifies between implant-anchored platform bundlers, standalone navigation specialists, and imaging-integrated conglomerates. Three archetypes dominate: spine-implant portfolio anchors, software-centric cranial platforms, and robotic-arm ecosystem integrators. M&A activity concentrates on algorithm developers with FDA-cleared deformable modeling capabilities, while strategic partnerships link hardware manufacturers to academic training networks.
Within the implant-anchored tier, Medtronic and Stryker exemplify platform bundling strategies that leverage spine and orthopedic portfolios to secure multi-year navigation contracts. Brainlab AG occupies a specialist position as a software-agnostic cranial platform provider interoperable with heterogeneous hospital IT environments. These three entities collectively represent the competitive vectors—implant integration, robotic ecosystem control, and software interoperability—that structure procurement negotiations across United States, German, and Japanese hospital systems.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Brainlab AG |
| Zimmer Biomet |
| B. Braun SE |
| Siemens Healthineers |
| GE HealthCare |
| KARL STORZ SE & Co. KG |
| Smith+Nephew |
| Others |
Supply & Pricing Matrix
Specialized optical engineering talent concentrated in southern Germany and the Boston corridor commands wage premiums that propagate through system manufacturing costs, widening spreads between premium navigation platforms and standard-tier alternatives.
Pricing Analysis
Platform-as-a-service contracts with multi-year hardware leasing and per-procedure software licensing anchor the dominant pricing structure across United States integrated delivery networks. Price differentiation hinges on FDA clearance tier and bundled training intensity, with 510(k) predicate-based systems commanding modest premiums over de novo pathways. Pricing pressure stems from hospital capital committee consolidation favoring total cost-per-procedure metrics over upfront equipment spend. Ambulatory surgical centers exhibit highest price sensitivity due to compressed capital cycles, while academic medical centers prioritize accuracy specifications over acquisition cost.
Supply Chain Analysis
Infrared sensor arrays and electromagnetic field generators rest on specialized component suppliers concentrated in Germany, Japan, and the United States. Precision optical lenses, rare-earth magnetic materials, and miniaturized inertial measurement units constitute critical input dependencies. Single-source vulnerability concentrates around German-engineered camera modules subject to export licensing friction. Distribution runs through authorized dealer networks with direct-to-hospital service contracts dominating in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical navigation system market compounds steadily as aging demographics in developed economies sustain joint replacement volumes that amortize precision instrumentation investments.
For Market Incumbents: Lock in hospital system relationships through multi-year platform leases bundling hardware, software maintenance, and procedural training to preempt substitution by software-agnostic competitors. Deepen backward integration into optical sensor manufacturing to defend margin position against component cost volatility and tariff exposure on German-sourced camera modules. For New Entrants and Emerging Players: Launch via software-only navigation algorithms compatible with heterogeneous hospital IT environments, bypassing capital-intensive hardware manufacturing. India's corporate hospital chains in Mumbai and Bangalore present the most penetrable geography, with electromagnetic platforms for spinal fusion offering the clearest white-space entry point against optical-dominant incumbents. For Investors and Strategic Acquirers: Implant-anchored platform bundlers are the most active acquirer in this space, seeking FDA-cleared deformable tissue modeling capabilities to complete robotic-arm ecosystems. Acquisition targets with established clinical data repositories under EU MDR post-market surveillance requirements offer durable competitive moats. Watch PMDA equivalence determinations for novel navigation algorithms as the signal for accelerated clearance velocity and valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates commercial entry for algorithm-upgradable platforms against de novo pathways. |
| CE Marking Pathway | EU MDR clinical evidence requirements create compliance moats for manufacturers with established surveillance infrastructure. |
| Hospital System Partnership | Multi-facility orthopedic service line contracts extract volume discounts unavailable to standalone community hospitals. |
| Software Companion Development | Machine learning-based predictive registration integrates deformable tissue modeling into cranial navigation workflows. |
| Reimbursement Strategy | Medicare and national health services codification for navigation-assisted procedures determines capital investment timing. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, biomedical engineers at academic medical centers, GPO contracts managers, and navigation platform sales directors grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, PMDA review summaries, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installed base estimates triangulated against top-down market sizing across tracking modalities and application segments.
Top-down macroeconomic drivers and bottom-up facility-level adoption curves structured the analytical lens across the analysis window. Segmentation modeling captured product type, technology, application, and end-user dimensions with regional regulatory cluster overlays. CAGRs derived from procedure volume trajectories, capital replacement cycles, and software upgrade frequencies in neurosurgery and orthopedic surgery workflows.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement codification delays and electromagnetic interference resolution timelines. Forecasts reflect assumptions around FDA clearance velocity, EU MDR compliance cost absorption, and Japan's PMDA equivalence criteria evolution. Reimbursement policy shifts, training infrastructure expansion rates, and algorithm validation study completion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Specimen Retrieval Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Pectus Bar System Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Global Pacemakers Market
Medical Devices
Smart Stairlift Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Global Retinoscopes Market