
 Power Generation Equipment MRO Market | 2026-2036
Power Generation Equipment MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Power Generation Equipment MRO Market Insights
Independent power producers is bifurcating demand away from legacy utility buyers as decentralized generation assets multiply across deregulated grids. Siemens Energy leverages its turbine service heritage to dominate high-value overhaul contracts for combined-cycle plants. General Electric anchors its position through predictive analytics platforms that reduce unplanned downtime for utility clients. Mitsubishi Heavy Industries competes on geographic reach, sustaining long-term service agreements across Asian thermal fleets.
Power generation equipment MRO encompasses the inspection, repair, overhaul, and testing of turbines, generators, transformers, and switchgear to restore operational efficiency and extend asset life beyond original design limits. Turbine maintenance demands the largest share of spend due to blade erosion, thermal fatigue, and clearance degradation in high-temperature gas paths. Preventive maintenance protocols capture the fastest-growing service category as operators shift from reactive breakdown fixes to scheduled interventions that optimize capacity factors. Emergency repair retains premium pricing power but contracts in absolute share as digital monitoring reduces catastrophic failure incidence.
The EPA enforces emissions compliance timelines that compel coal and gas plant operators to retrofit or retire, directly shaping MRO investment decisions for scrubber and turbine upgrades. The EU Green Deal and REACH chemical restrictions further constrain lubricant formulations and coating chemistries used in overhaul processes. OSHA lockout-tagout standards and ISO 55000 asset management frameworks govern worker safety and maintenance scheduling protocols across US and European facilities. Stakeholders must weigh stranded asset risk against life-extension economics as carbon intensity rules tighten and renewable alternatives reshape dispatch order.
Market Dynamics
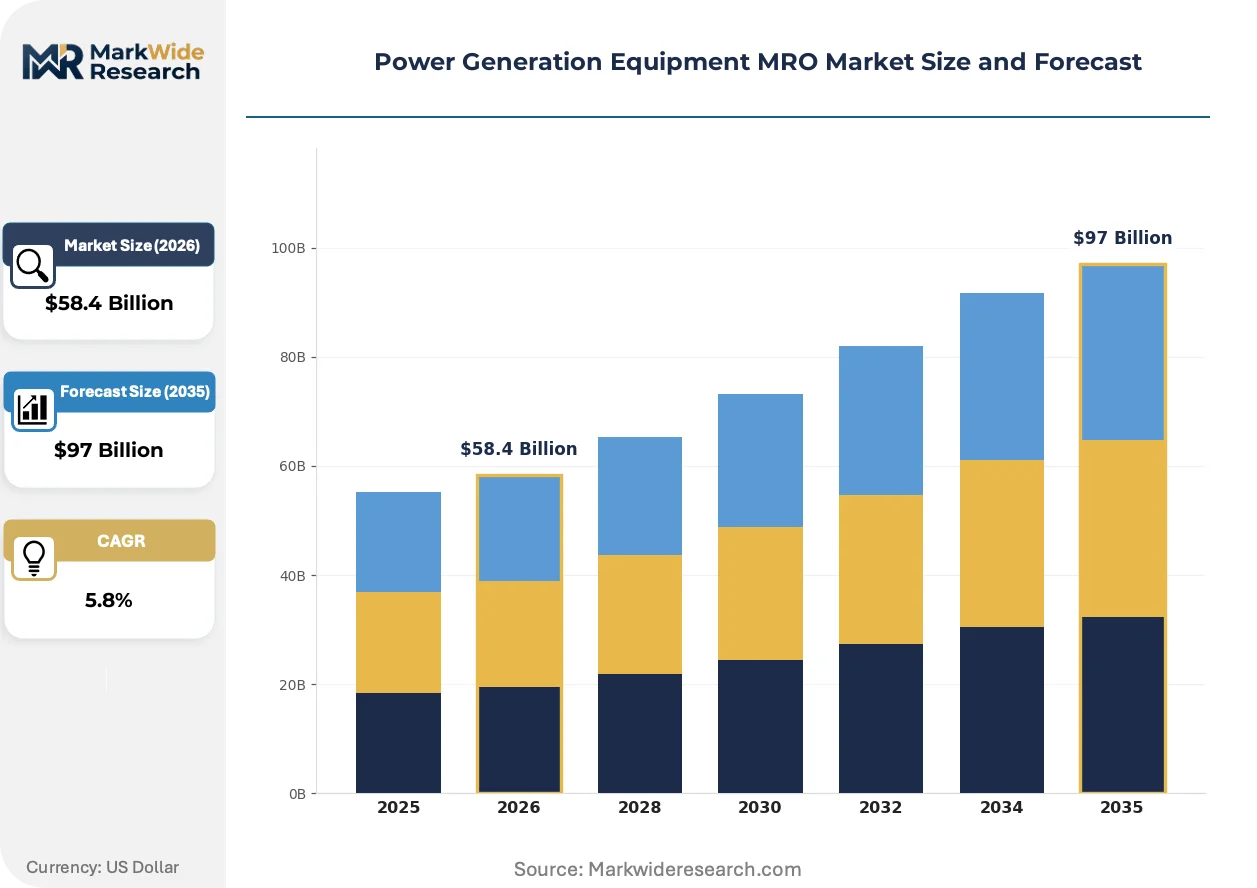
Decarbonization mandates and dispatch economics are forcing thermal plant operators to compress maintenance windows while extending asset life beyond original design specifications. This tension between reliability demands and carbon intensity rules defines current investment priorities across gas turbine and coal retrofit fleets.
Growth Catalysts
- EU Green Deal compliance deadlines:Coal and gas operators across Germany, Poland, and Italy must retrofit scrubbers and upgrade turbine efficiency to meet emissions caps, triggering intensive overhaul cycles.
- Independent power producers:IPPs operating decentralized combined-cycle plants in deregulated US and Australian grids are expanding maintenance budgets faster than traditional utilities, prioritizing availability over capital replacement.
- Digital predictive maintenance:Sensor networks and machine learning platforms are reducing catastrophic failure rates, converting emergency repair spend into scheduled preventive interventions with higher contractor margins.
Market Restraints
- Specialized alloy supply concentration:Superalloy forgings for hot gas path components concentrate among a limited set of European and Japanese suppliers, creating lead time volatility for blade and vane replacements.
- REACH chemical restrictions:ECHA regulations on chromium plating and solvent-based coatings constrain traditional repair processes, forcing qualification of alternative chemistries that extend overhaul timelines.
- Renewable substitution pressure:Solar and wind capacity additions in Spain, Chile, and Morocco are compressing thermal plant capacity factors, undermining the economic case for major turbine reinvestment.
Strategic Opportunities
- Small modular reactor MRO preparation:Nuclear utilities in Canada, the United Kingdom, and the United States are establishing maintenance frameworks for emerging SMR fleets, creating first-mover service contracts.
- Hydrogen turbine retrofits:OEMs and service providers are developing combustion system modifications for hydrogen blending, capturing upgrade revenue as operators pilot fuel switching under national hydrogen strategies.
- Remote monitoring platforms:Cloud-based diagnostic services are penetrating mid-sized thermal fleets in Southeast Asia and Latin America, opening subscription revenue streams beyond traditional time-and-material contracts.
Industry Challenges
- Turbine blade repair technician scarcity:Specialized welding and coating application skills for nickel-based superalloys face generational attrition, constraining overhaul shop throughput across North America and Western Europe.
- Legacy control system integration:Analog turbine governors and digital predictive platforms require complex middleware development, delaying digital transformation timelines for 1990s-vintage plants.
- Extended certification timelines:EPA and ECHA approval processes for new repair materials and processes stretch 18-36 months, mismatching procurement cycles with urgent outage schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Generation Equipment MRO Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Turbines, Generators, Transformers, Switchgear Maintenance Type: Predictive, Preventive, Corrective, Emergency Service Type: Repair, Overhaul, Inspection, Testing End User: Utilities, Industrial Plants, Renewable Facilities, Independent Power Producers |
| Companies Covered | Siemens Energy, General Electric, Mitsubishi Heavy Industries, Ansaldo Energia, Sulzer, MAN Energy Solutions, GE Vernova, ABB, EthosEnergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Generation Equipment MRO Market Trends and Innovations
Additive manufacturing is penetrating hot-section component repair, while regulatory frameworks accelerate fuel-flexibility investments. Service contracting models are simultaneously compressing and unbundling as operators seek granular control over maintenance spend.
Directed energy deposition and powder bed fusion processes are restoring worn turbine blades with nickel superalloy geometries matching OEM specifications. Major overhaul shops in Germany, Japan, and the United States are qualifying these techniques for production repair rather than prototyping. This capability is decomposing the traditional spare parts supply chain, enabling localized remanufacturing that shortens lead times from months to weeks.
The EPA's Good Neighbor Rule and state-level NOx regulations are compelling gas plant operators to evaluate low-emissions combustor retrofits and selective catalytic reduction installations. Compliance timelines concentrate investment in the 2026-2030 window for facilities in the Ohio River Valley and Texas ERCOT zones. Operators are bundling emissions hardware with hot gas path overhauls to minimize repetitive outage costs.
Long-term service agreements are fragmenting into modular, event-based contracts that separate inspection scope from repair execution and materials supply. IPPs and merchant generators in deregulated markets are driving this unbundling, using competitive tendering for each work package. This pattern is most advanced in the United Kingdom, Australia, and the PJM Interconnection, where asset owners retain direct procurement control over spare parts and subcontract labor separately.
Power Generation Equipment MRO Market Segmentation
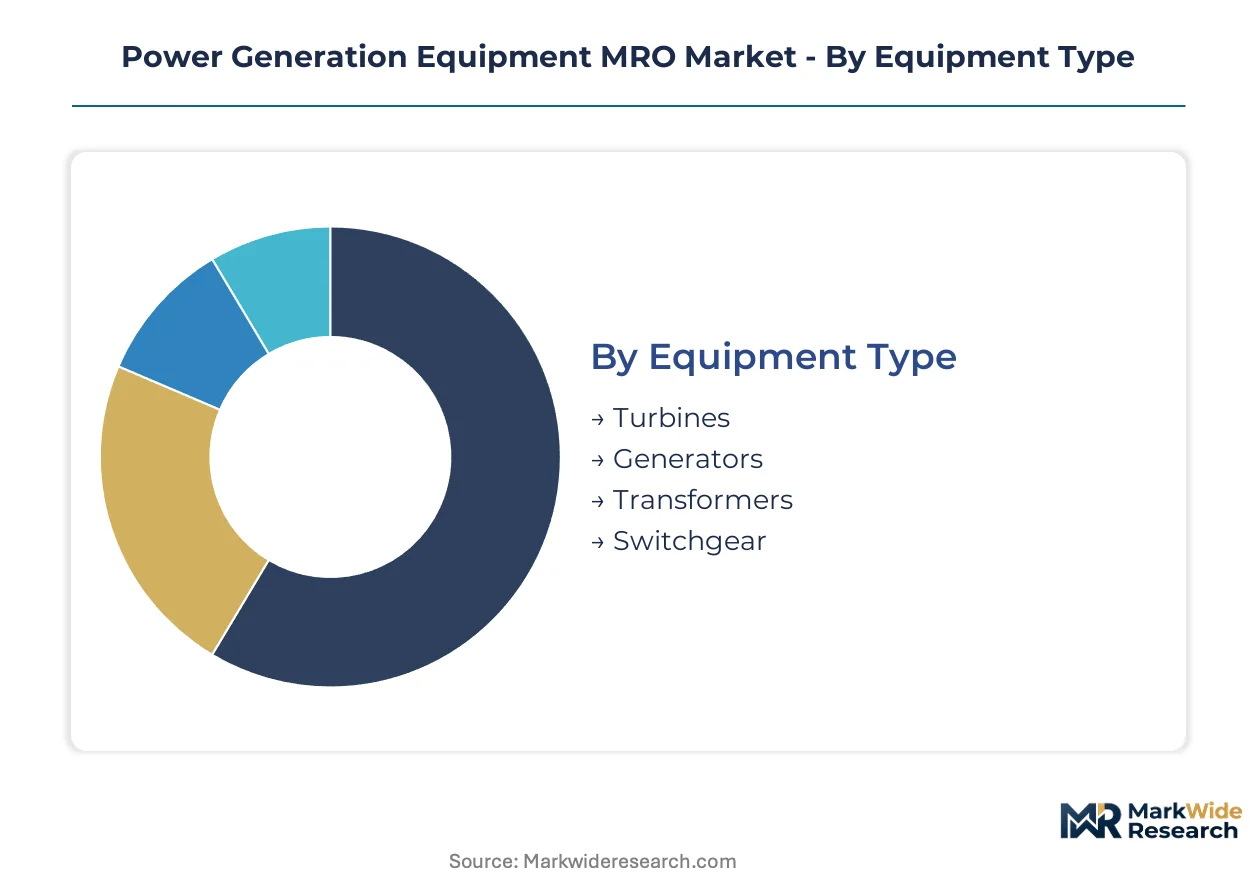
MRO procurement patterns diverge sharply across equipment categories and operational philosophies. Regulatory pressure on emissions compliance and asset life economics drives segmentation strategy for plant operators and service contractors alike.
Equipment Type:
EPA emissions timelines and EU Green Deal retrofit mandates concentrate investment differently across thermal asset classes.
- Turbines:Hot gas path components endure thermal fatigue, blade erosion, and clearance degradation in combined-cycle and simple-cycle configurations. German and US operators facing NOx regulations prioritize combustor retrofits alongside hot section overhauls. Established volume favors turbines; emerging adoption favors switchgear.
- Generators:Stator winding insulation systems and rotor field coils require periodic testing and rewinding to maintain output efficiency. Industrial captive power facilities in Japan sustain steady demand for generator maintenance amid grid reliability concerns.
- Transformers:Oil analysis, bushing replacement, and core inspections preserve transmission asset integrity across utility fleets.
- Switchgear:Circuit breaker mechanisms and protective relay systems demand arc-flash compliant maintenance protocols under OSHA standards.
Capital intensity and outage duration differentiate procurement cycles across equipment classes.
Maintenance Type:
Digital platform penetration reshapes how operators allocate spending across reactive and proactive intervention modes.
- Predictive:Sensor networks and machine learning algorithms forecast component degradation before functional failure, converting unplanned downtime into scheduled windows. Independent power producers in deregulated Australian and US markets deploy these systems to maximize capacity factor revenue. Established volume favors corrective; emerging adoption favors predictive.
- Preventive:Time-based inspections and component replacements follow OEM-recommended intervals to sustain design efficiency. REACH chemical restrictions on traditional coatings and lubricants complicate preventive protocol standardization across European facilities.
- Corrective:Post-failure repairs address identified defects after performance degradation or protective relay activation.
- Emergency:Catastrophic failure response commands premium labor rates and expedited logistics for forced outage recovery.
Contractor margins compress on corrective work while predictive engagements sustain pricing power through proprietary analytics.
Service Type:
Unbundling of long-term service agreements creates discrete procurement opportunities for specialized providers.
- Overhaul:Complete disassembly, component replacement, and reassembly of turbines and generators restore assets to OEM performance specifications. Additive manufacturing qualification for blade repair is shortening lead times in German and Japanese overhaul shops. Established volume favors repair; emerging adoption favors inspection.
- Repair:Component-level restoration addresses localized damage without full unit disassembly, optimizing outage duration for merchant generators.
- Inspection:Borescope examinations, non-destructive testing, and electrical diagnostic surveys identify maintenance requirements before commitment to repair scope.
- Testing:Protective relay calibration, transformer oil analysis, and turbine performance verification confirm operational readiness post-maintenance.
Modular contracting allows asset owners to separate diagnostic assessment from execution and materials procurement.
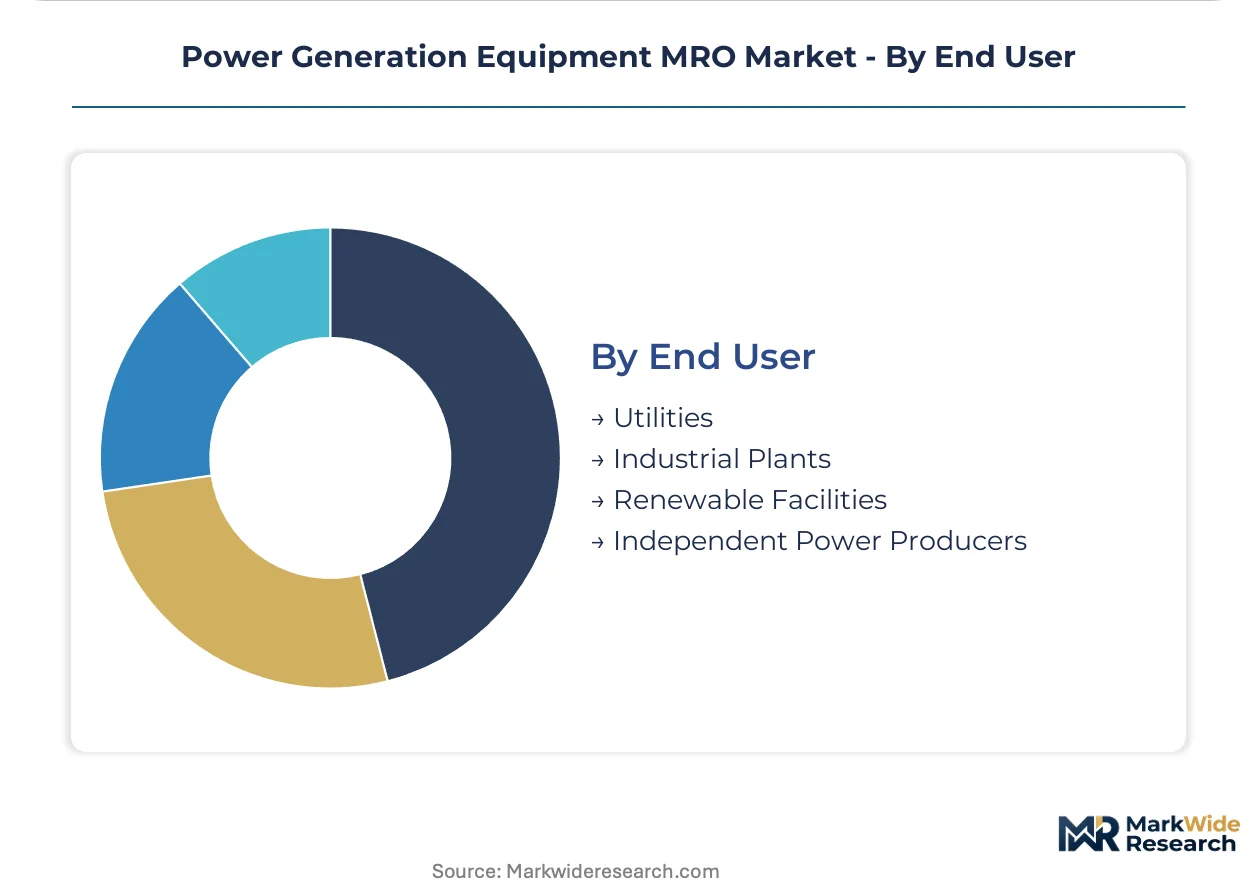
End User:
Ownership structure and dispatch economics determine maintenance budget scale and strategic priority.
- Independent Power Producers:Merchant and contracted generators in deregulated markets prioritize availability-based revenue optimization over capital replacement. IPPs in the PJM Interconnection and Australian NEM expand maintenance budgets faster than regulated utilities to sustain dispatch competitiveness. Established volume favors utilities; emerging adoption favors independent power producers.
- Utilities:Vertically integrated and distribution-only operators balance reliability obligations with rate-case recovery constraints on maintenance spending.
- Industrial Plants:Captive generation assets at refineries, chemical complexes, and manufacturing facilities require MRO continuity for process steam and electricity supply security.
- Renewable Facilities:Wind turbine gearboxes and solar inverter systems introduce distinct maintenance protocols separate from thermal asset experience.
Procurement autonomy varies with regulatory structure and balance sheet capacity across ownership categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent power producers in deregulated markets concentrate maintenance spending across Germany, the United States, and Japan, where aging thermal fleets face compressed overhaul cycles under tightening emissions rules.
United States
Merchant generators in the PJM Interconnection and Texas ERCOT zones expand preventive maintenance budgets to sustain dispatch competitiveness against renewable entrants. EPA Good Neighbor Rule compliance deadlines through 2026 concentrate scrubber and combustor retrofit investment in the Ohio River Valley. Houston hosts the densest cluster of gas turbine service contractors, where additive manufacturing qualification for blade repair is shortening outage durations.
Germany
Coal and lignite operators facing EU Green Deal phase-out timelines must compress major overhauls into shortened remaining asset life windows. ECHA REACH restrictions on chromium plating and solvent-based coatings force overhaul shops in the Ruhr industrial belt to qualify alternative chemistries. Berlin-based engineering consultancies are restructuring long-term service agreements into modular, event-based contracts for municipal utilities.
Japan
Industrial captive power facilities sustain steady generator maintenance demand amid grid reliability concerns following the 2011 Fukushima aftermath. METI carbon neutrality roadmaps are accelerating hydrogen turbine pilot programs that require combustion system modifications. Nagoya and Osaka industrial corridors concentrate hot gas path overhaul capacity for combined-cycle fleets serving manufacturing complexes.
United Kingdom
Merchant generators in the Balancing Mechanism market prioritize availability-based revenue optimization through predictive maintenance deployment. OFGEM price cap constraints on regulated utilities are shifting maintenance procurement toward competitive tendering for unbundled work packages. Aberdeen and Humberside clusters are developing offshore wind turbine MRO capabilities that leverage transferable skills from North Sea oil and gas decommissioning.
Australia
Independent power producers in the National Electricity Market face renewable substitution pressure that compresses capacity factors for thermal assets. AEMO reliability standards mandate minimum inertia services that sustain maintenance demand for synchronous generation. Brisbane and Sydney service hubs are penetrating mid-sized thermal fleets with cloud-based remote monitoring subscriptions beyond traditional time-and-material contracts.
Power Generation Equipment MRO Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with turbine OEM heritage, creating a tiered structure where full-service overhaul providers compete against specialized component repair shops. Strategic archetypes include predictive analytics platform operators, additive manufacturing-enabled remanufacturing specialists, and hydrogen retrofit capability developers. Competitive moves concentrate on unbundling long-term service agreements into modular contracts and establishing first-mover maintenance frameworks for small modular reactor fleets.
Within the OEM-heritage tier, Siemens Energy, General Electric, and Mitsubishi Heavy Industries occupy positions that exemplify distinct competitive vectors. Siemens Energy leverages its turbine service heritage to dominate high-value overhaul contracts for combined-cycle plants. General Electric anchors its position through predictive analytics platforms that reduce unplanned downtime for utility clients. Mitsubishi Heavy Industries competes on geographic reach, sustaining long-term service agreements across Asian thermal fleets.
| Leading Market Players |
|---|
| Siemens Energy |
| General Electric |
| Mitsubishi Heavy Industries |
| Ansaldo Energia |
| Sulzer |
| MAN Energy Solutions |
| GE Vernova |
| ABB |
| EthosEnergy |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German and Japanese overhaul shops creates scale economies that compress price floors for hot gas path component repair while elevating margins for emergency response services. This scale concentration shapes procurement patterns as independent power producers negotiate long-term service agreements against spot-market alternatives.
Pricing Analysis
Cost-plus contracts with labor rate indexation dominate turbine overhaul procurement, linking technician wages to regional manufacturing benchmarks. Price differentiation hinges on OEM certification tier and geographic proximity to service hubs, with ISO 55000-certified providers commanding premiums over independent shops. Pricing pressure stems from unbundling of long-term service agreements into modular, competitively tendered work packages. Merchant generators in deregulated markets exhibit highest price sensitivity, while utilities under rate-case recovery constraints prioritize reliability over unit cost.
Supply Chain Analysis
Germany and Japan anchor superalloy forging capacity for hot gas path components, while the United States concentrates additive manufacturing qualification for blade repair. Nickel-based superalloys, chromium plating chemistries, and ceramic thermal barrier coatings constitute critical input dependencies. Single-source vulnerability concentrates in European superalloy suppliers subject to ECHA REACH restrictions on traditional coating formulations. Distribution runs through OEM-authorized service networks and independent overhaul shops serving regional thermal fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
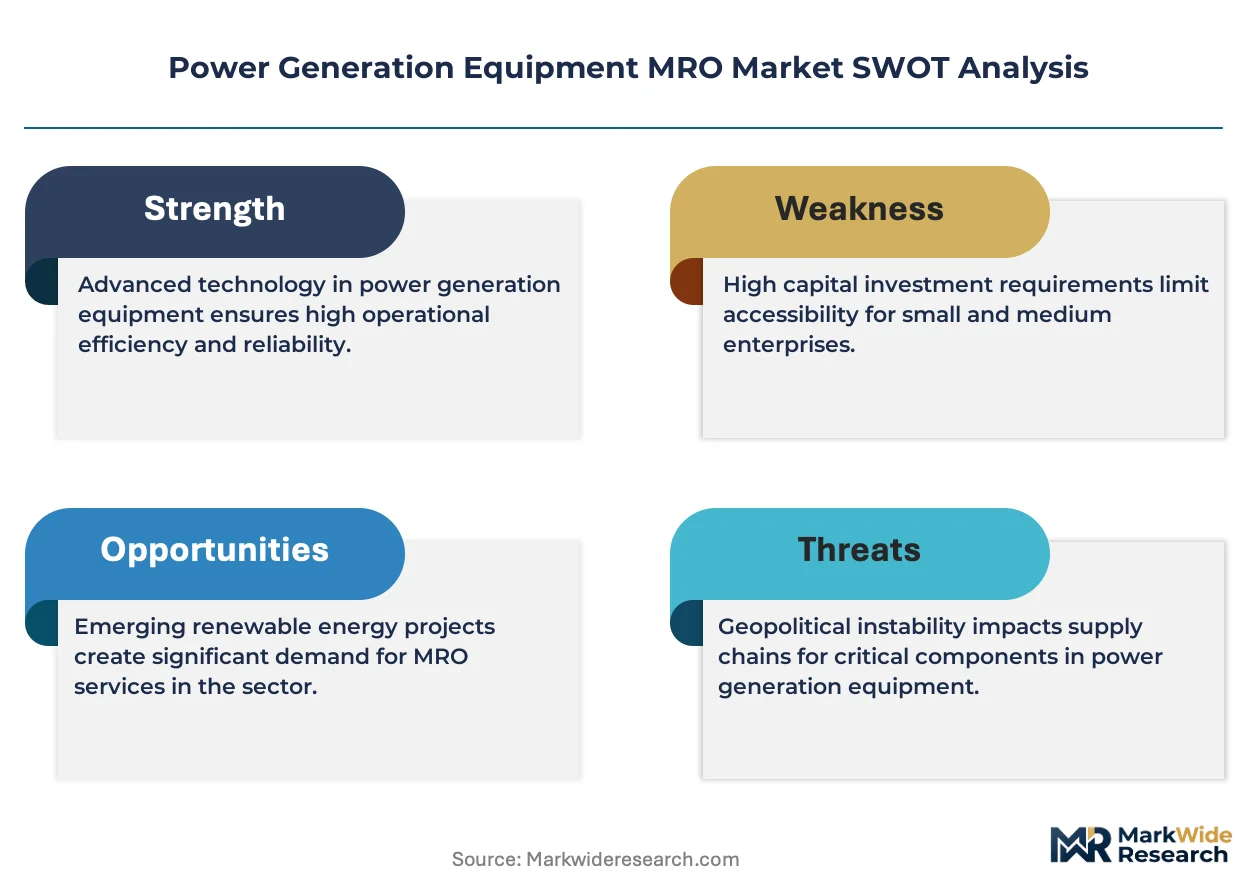
This market tracks a cyclical recovery as aging thermal fleets compress overhaul cycles under emissions compliance deadlines. Equipment age profiles and regulatory phase-out timelines create predictable maintenance demand windows.
For Market Incumbents: Fortify aftermarket service moats by deepening captive supply of superalloy components against emerging additive manufacturing competitors. Expand predictive analytics platform penetration to convert emergency repair revenue into higher-margin subscription contracts. Prioritize hydrogen turbine retrofit certification to capture upgrade revenue as fuel-switching pilots accelerate under national hydrogen strategies.
For New Entrants and Emerging Players: Remote monitoring platform penetration gaps among mid-sized Southeast Asian and Latin American thermal fleets offer white-space entry points. Target cloud-based diagnostic subscriptions for combined-cycle plants below 500MW capacity, where incumbent OEMs maintain weaker service presence. Pursue partnership models with regional engineering consultancies to bypass capital-intensive overhaul shop infrastructure requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive manufacturing-enabled remanufacturing specialists with qualified production repair capabilities. Long-term viability rests on service contracting models that survive thermal asset retirement waves through transferable skills to small modular reactor and hydrogen infrastructure maintenance. Monitor EPA and ECHA approval timelines for new repair materials as inflection indicators for overhaul shop throughput constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | Production repair certification for nickel superalloy blade restoration shortens lead times at German overhaul shops. |
| Predictive Platform Deployment | Sensor network installations convert emergency repair spend into scheduled preventive maintenance engagements. |
| Hydrogen Combustor Retrofit | Fuel-flexibility modifications capture upgrade revenue under METI and EU hydrogen strategy pilots. |
| Modular Service Unbundling | Event-based contracts separate inspection scope from repair execution for IPP procurement autonomy. |
| SMR Maintenance Framework | First-mover service contracts with Canadian and UK nuclear utilities establish emerging reactor MRO capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA generation statistics, FERC maintenance expenditure filings, and IEA power plant databases. Interviews with utility planning officers, independent power producer asset managers, EPC contractors, and aftermarket service heads informed demand-side validation. OEM procurement teams and overhaul shop operations directors supplied supply-side perspectives. Bottom-up equipment-level maintenance spend estimates triangulated against top-down market aggregation.
Segmentation dimensions modeled include equipment type, maintenance philosophy, service delivery mode, and ownership structure across the projection horizon. Fuel source, generation capacity tier, and regional regulatory framework further stratified demand analysis. CAGRs derived from historical maintenance intensity ratios applied to forward capacity and age profiles. Forecast inputs incorporated EPA compliance timelines, EU Green Deal phase-out schedules, and hydrogen turbine pilot program announcements.
Underlying assumptions cover emissions regulation enforcement continuity and superalloy supply availability, with deviation risk concentrated in accelerated renewable substitution and extended material certification timelines. Recalibration cycles align with material shifts in regulatory compliance deadlines and OEM service contract restructuring announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Global Power Supply Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Germany Power EPC Market
Power Equipment
Japan Power EPC Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Romania Power EPC Market
Power Equipment
United States Power Rental Market