
 Europe Regenerative Medicines Market | 2026-2036
Europe Regenerative Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Regenerative Medicines Market Foresight
Hospital procurement is pivoting from fragmented general wards toward centralized specialist centers with cell therapy accreditation. Novartis AG leverages its CAR-T manufacturing footprint to anchor supply relationships with these consolidated buyers. AstraZeneca sustains competitive positioning through gene therapy alliances that extend its reach beyond oncology into rare disease networks. Bristol-Myers Squibb Co differentiates via dual-platform investments in both autologous and allogeneic cell sources.
Regenerative medicines comprise living cells, tissues, or genetic constructs engineered to repair, replace, or regenerate damaged human tissue, typically requiring cryopreservation below minus 150 degrees Celsius and aseptic bioprocessing to maintain viability. Their primary purpose centers on treating previously incurable conditions by restoring native biological function rather than merely managing symptoms. Cell therapy occupies the largest current revenue pool given established CAR-T approvals, while gene therapy represents the fastest-expanding segment as viral vector manufacturing scales across European contract development organizations. Tissue engineering commands premium pricing in orthopedic applications where scaffold-based grafts integrate with native bone, though stem cell products face margin compression from emerging allogeneic alternatives.
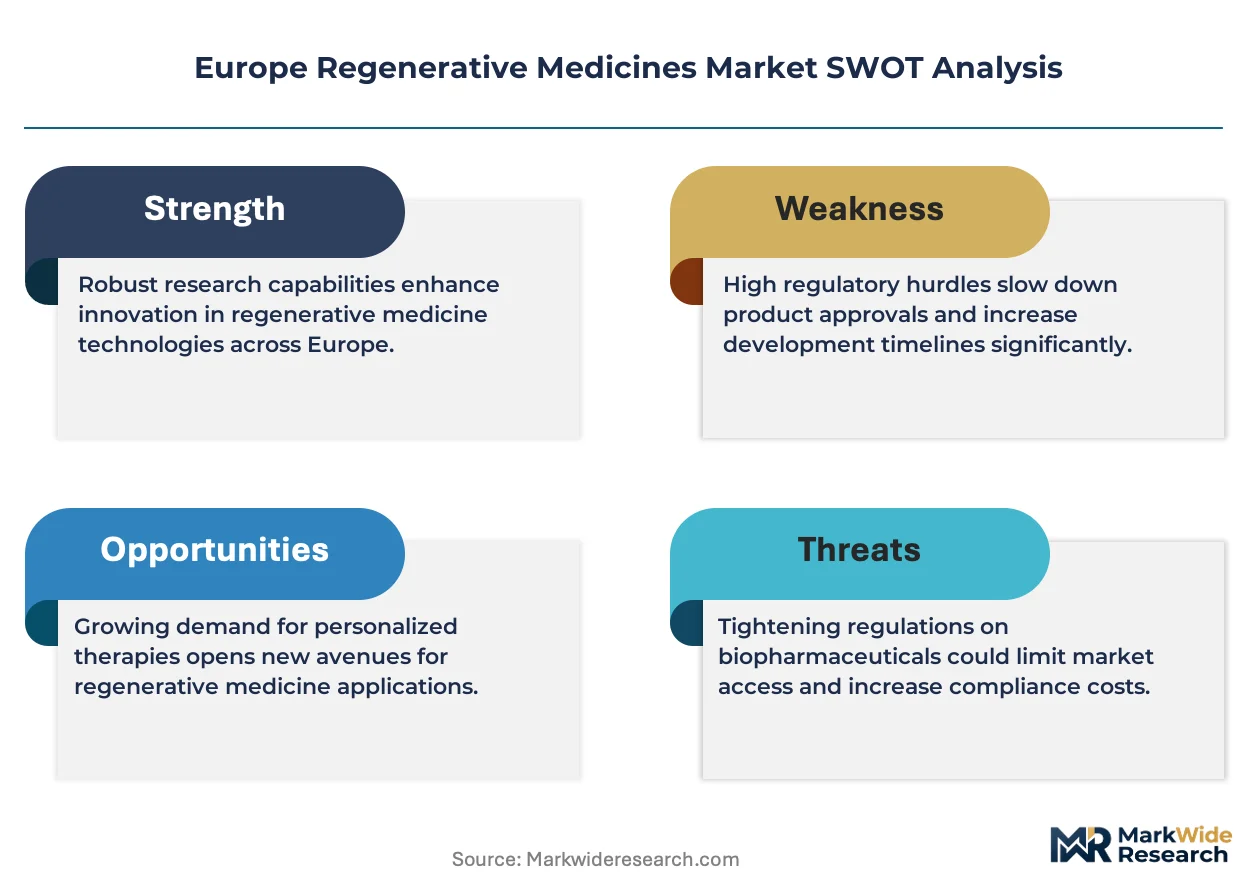
EMA's ATMP classification system shapes market access timelines, with centralized procedures mandatory for all gene and cell therapies seeking European approval. The EU Green Deal's pharmaceutical manufacturing sustainability mandates are forcing adaptations in single-use bioreactor supply chains and cold-chain logistics. France's ANSM and Germany's BfArM maintain divergent national reimbursement assessment criteria that create fragmented pricing outcomes even after EMA approval. Stakeholders must monitor how the EU AI Act's algorithmic transparency requirements will reshape computational tools used in patient-specific therapy matching.
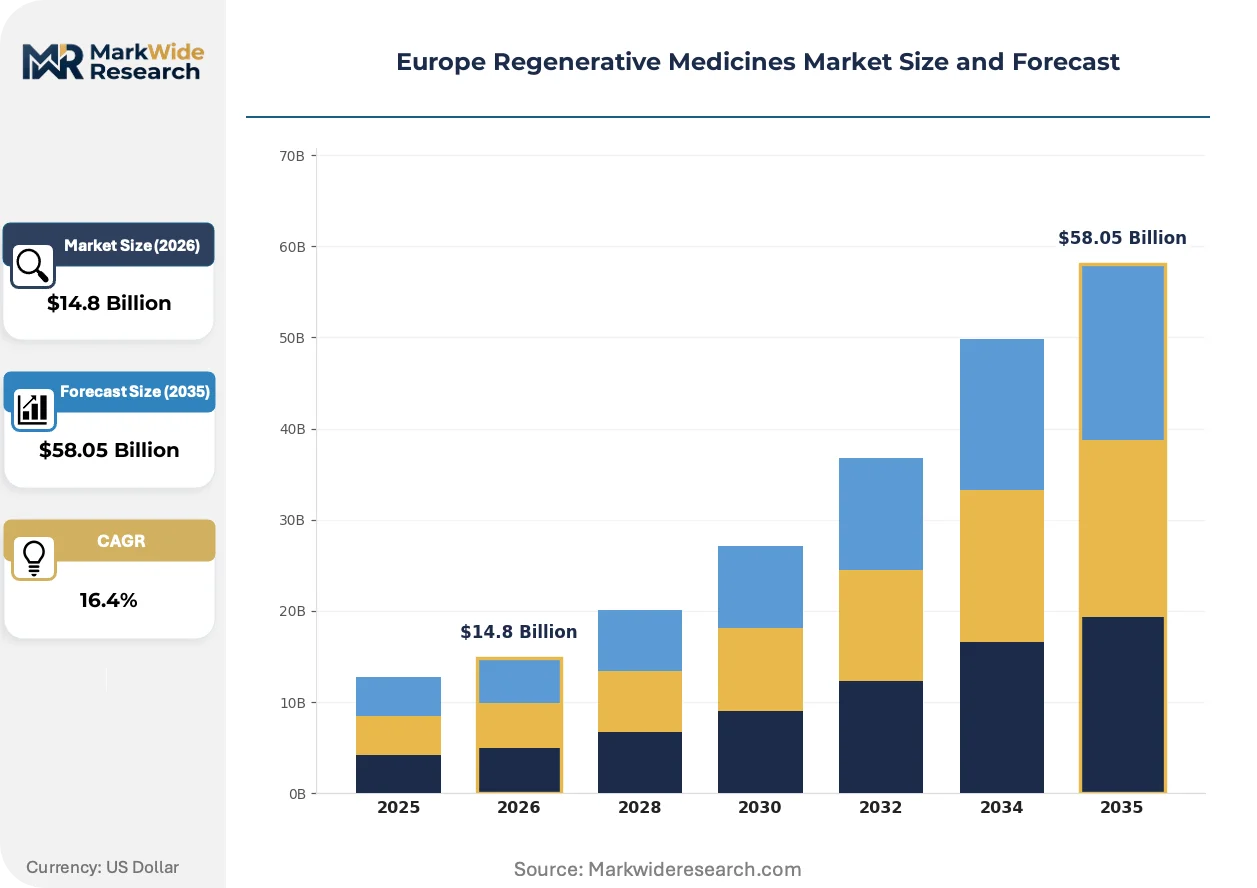
Market Dynamics
Centralized hospital accreditation for cell therapies is consolidating procurement authority across Europe's academic medical centers, compressing vendor access points and elevating manufacturing scale requirements for suppliers.
Growth Catalysts
- EMA's ATMP framework:Streamlined centralized approval pathways accelerate commercial timelines for gene and cell therapies, reducing redundant national assessments.
- Germany's academic hospital networks:Integrated research-to-bedside pipelines anchor regional adoption leadership and generate sustained demand for advanced biologics.
- Viral vector manufacturing scale-up:European contract development organizations are expanding production capacity to serve accelerating gene therapy pipelines.
Market Restraints
- Cryopreservation infrastructure costs:Maintenance below minus 150 degrees Celsius requires specialized equipment and continuous liquid nitrogen supply, constraining site expansion.
- Single-use bioreactor supply concentration:EU Green Deal sustainability mandates are disrupting established supply chains for critical manufacturing consumables.
- France-Germany reimbursement divergence:ANSM and BfArM maintain divergent national assessment criteria that fragment pricing outcomes even after EMA approval.
Strategic Opportunities
- Allogeneic cell source expansion:Off-the-shelf therapies promise manufacturing scale advantages over autologous approaches, opening margin recovery pathways.
- Orthopedic tissue engineering:Scaffold-based bone graft applications command premium pricing and remain underpenetrated relative to oncology's saturation.
- EU AI Act transparency requirements:Algorithmic disclosure mandates will reshape computational tools for patient-specific therapy matching, creating first-mover advantages.
Industry Challenges
- Aseptic bioprocessing talent scarcity:Qualified personnel for cell therapy manufacturing remain concentrated in limited geographic clusters, constraining workforce expansion.
- Cold-chain logistics reconfiguration:Existing distribution networks require fundamental adaptation to maintain viability across temperature-sensitive product handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Regenerative Medicines Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Gene Therapy, Tissue Engineering, Stem Cell Products Application: Orthopedic, Cardiovascular, Neurological, Wound Healing End User: Hospitals, Research Institutions, Pharmaceutical Companies, Biotech Firms Technology: CRISPR, Bioprinting, Viral Vector, Nanotechnology |
| Companies Covered | Novartis AG, AstraZeneca, Integra LifeSciences Corporation, Amgen Inc., Medtronic plc, Bristol-Myers Squibb Co, Johnson & Johnson, Roche Holding AG, Smith & Nephew plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Regenerative Medicines Market Shifts & Advancements
Manufacturing automation and regulatory digitization are converging to reshape how regenerative therapies move from development to patient administration across European healthcare systems.
Closed-system automated bioreactors are integrating aseptic processing steps previously requiring manual intervention. German and French cell therapy centers are adopting these platforms to reduce contamination risk and batch variability. The technology is integrating formerly discrete manufacturing stages into continuous workflows that compress production timelines and reduce facility footprint requirements.
The EU AI Act's algorithmic transparency mandates are imposing documentation burdens on machine-learning tools used for patient stratification and therapy matching. Developers must now maintain explainability logs for clinical decision-support systems deployed in treatment selection. Gene therapy sponsors with computational patient identification platforms face the steepest compliance adaptation requirements.
Hospital buyers are consolidating cell therapy purchasing through centralized specialist accreditation programs. France's university hospital networks and England's NHS specialized commissioning frameworks now require vendor qualification at the system level rather than individual site level. This concentration is most visible in CAR-T procurement, where three-to-five year supply agreements with integrated manufacturing partners are displacing transactional purchasing models.
Europe Regenerative Medicines Market Segmentation
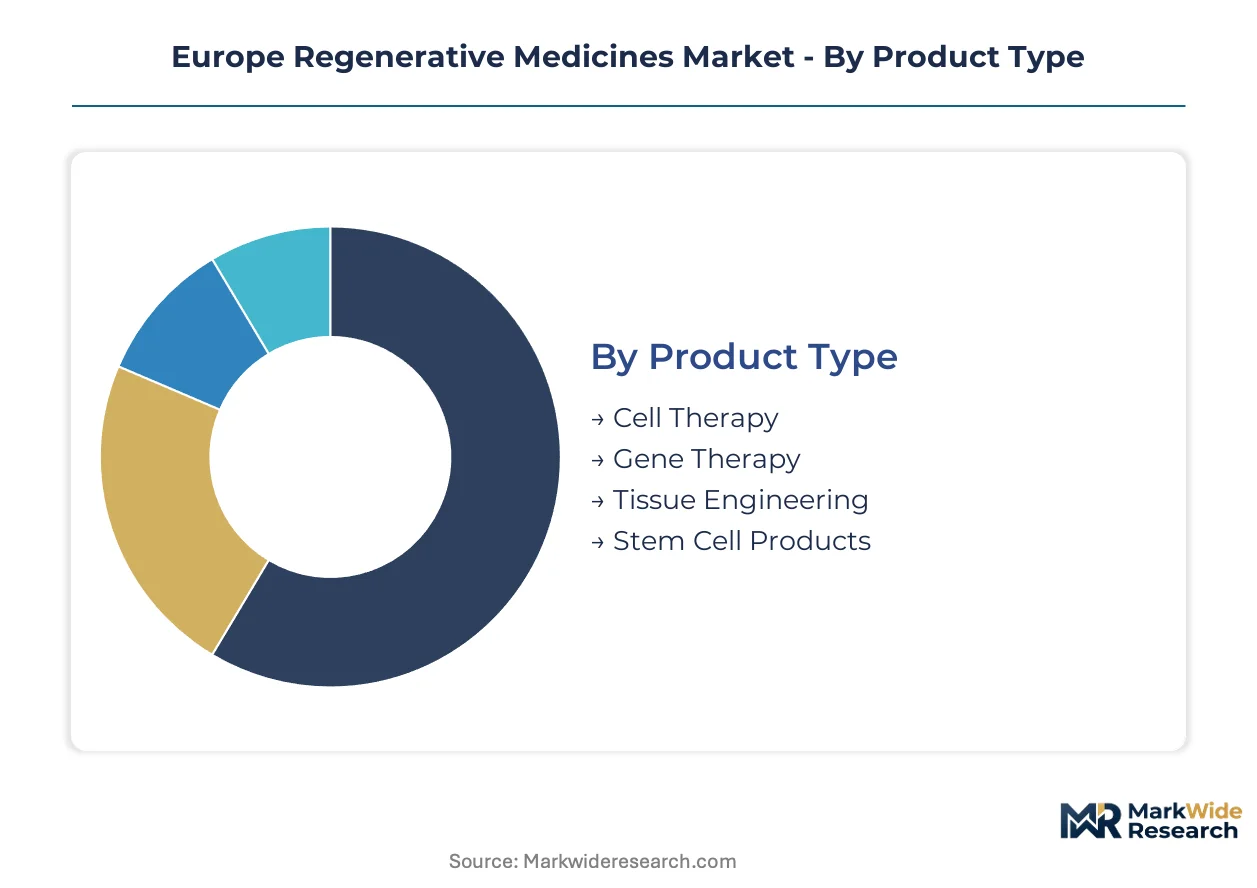
Segmentation in Europe's regenerative medicines market reveals how EMA's ATMP classification system differentially burdens each product category with approval complexity. Hospital procurement teams use these divisions to align purchasing authority with clinical specialization and cold-chain infrastructure capabilities.
Product Type:
EMA's centralized procedure mandates apply uniformly across all four product categories, though certification timelines diverge based on manufacturing complexity and prior precedent volume.
- Cell Therapy:Living cells engineered ex vivo for therapeutic effect, with CAR-T platforms dominating current revenue. German academic hospital networks anchor demand concentration as integrated research-to-bedside pipelines generate sustained procurement volume from consolidated specialist centers.
- Gene Therapy:Viral vector-delivered genetic constructs correcting disease-causing mutations. European contract development organizations are scaling manufacturing capacity to serve accelerating pipelines, with France's university hospital networks driving adoption leadership for inherited retinal and hematologic indications.
- Tissue Engineering:Scaffold-based grafts integrating with native tissue architecture, commanding premium pricing in orthopedic reconstruction where autologous harvesting limitations create addressable need.
- Stem Cell Products:Pluripotent or adult stem cell-derived therapeutics facing margin compression from emerging allogeneic alternatives that promise manufacturing scale advantages.
Leading the category by volume: Cell Therapy. Expanding most quickly: Gene Therapy.
Application:
Reimbursement pathways fragment across France's ANSM and Germany's BfArM assessment criteria, creating divergent pricing outcomes even after unified EMA approval.
- Orthopedic:Scaffold-based bone grafts and cartilage repair systems integrating with native tissue. United Kingdom NHS specialized commissioning frameworks concentrate procurement through designated musculoskeletal centers with cryopreservation infrastructure below minus 150 degrees Celsius.
- Cardiovascular:Regenerative approaches to myocardial repair and vascular reconstruction. Italian and Spanish hospital networks show emerging demand concentration as cardiac cell therapy trials advance through Phase III endpoints.
- Neurological:Gene therapies targeting neurodegenerative and neuromuscular conditions with limited disease-modifying alternatives. Patient identification complexity constrains addressable population sizing.
- Wound Healing:Cell-based and tissue-engineered skin substitutes for chronic and burn indications. Procurement localizes to specialized burn centers and diabetic foot clinics with established advanced therapy administration capabilities.
Dominating current revenue: Orthopedic. Steepest expansion trajectory: Cardiovascular.
End User:
Centralized accreditation programs are compressing vendor access points and elevating manufacturing partnership requirements for suppliers seeking consistent demand.
- Hospitals:Academic medical centers with cell therapy accreditation consolidating procurement authority across France, Germany, and England. Three-to-five year supply agreements with integrated manufacturing partners displace transactional purchasing models.
- Research Institutions:University-affiliated translational centers bridging preclinical development and first-in-human studies. EU Green Deal sustainability mandates force adaptations in single-use bioreactor supply chains.
- Pharmaceutical Companies:Established sponsors leveraging gene therapy alliances to extend reach beyond oncology into rare disease networks.
- Biotech Firms:Development-stage entities dependent on European contract development organizations for viral vector manufacturing scale-up.
Commanding procurement volume: Hospitals. Gaining share fastest: Biotech Firms.
Technology:
The EU AI Act's algorithmic transparency requirements reshape computational tools used in patient-specific therapy matching across technology platforms.
- CRISPR:Precision gene editing enabling ex vivo cell modification and in vivo genetic correction. German and French regulatory science networks anchor European competence center development.
- Bioprinting:Additive manufacturing of living tissue constructs with vascular architecture. Scaffold integration capabilities command premium positioning in orthopedic applications.
- Viral Vector:Adeno-associated and lentiviral delivery systems dominating gene therapy manufacturing. Production capacity constraints at European contract development organizations limit pipeline advancement.
- Nanotechnology:Lipid nanoparticle and synthetic vector approaches reducing immunogenicity profiles. Manufacturing scalability advantages position for cost-competitive positioning against viral alternatives.
Highest current deployment: Viral Vector. Climbing the fastest: Nanotechnology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for regenerative medicines concentrates in Germany's academic hospital networks, where integrated research-to-bedside pipelines anchor regional adoption leadership. France's university hospital systems and England's NHS specialized commissioning frameworks follow as consolidated procurement centers. Italy and Spain are emerging as growth corridors as cardiac cell therapy trials advance.
Germany
Academic hospital networks in Berlin, Heidelberg, and Munich generate sustained procurement volume for CAR-T and gene therapies. BfArM maintains divergent national reimbursement assessment criteria that fragment pricing outcomes even after EMA approval. The Rhine-Main and Upper Bavaria clusters host concentrated viral vector manufacturing capacity at European contract development organizations.
France
University hospital networks in Paris and Lyon drive adoption leadership for inherited retinal and hematologic gene therapy indications. ANSM's national reimbursement assessment operates independently of EMA approval timelines, creating regulatory friction. The Île-de-France region anchors cryopreservation infrastructure development with specialized centers maintaining temperatures below minus 150 degrees Celsius.
United Kingdom
NHS specialized commissioning frameworks concentrate cell therapy purchasing through designated treatment centers in London, Manchester, and Birmingham. The Medicines and Healthcare products Regulatory Agency aligns with EMA's ATMP classification system while maintaining independent market access pathways. Greater London hosts the highest density of accredited cell therapy administration sites.
Italy
Cardiac cell therapy trials advancing through Phase III endpoints are generating emerging demand concentration in Milan and Rome hospital networks. The Italian Medicines Agency participates in EMA's centralized procedures while maintaining national pricing negotiations. The Lombardy region is developing cold-chain logistics capabilities to support temperature-sensitive product distribution.
Spain
Hospital networks in Barcelona and Madrid are building cell therapy accreditation programs to capture centralized procurement flows. The Spanish Agency for Medicines and Health Products is streamlining national reimbursement timelines for ATMP-classified products. Catalonia's biomedical research cluster is scaling aseptic bioprocessing workforce development programs.
Europe Regenerative Medicines Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue allogeneic cell source platforms and automated manufacturing technologies. The market structure reflects consolidation around pharmaceutical sponsors with integrated manufacturing footprints alongside fragmentation among specialized biotech developers. Three archetypes dominate: large-cap diversified pharmaceutical companies with gene therapy alliances, mid-cap cell therapy specialists with CAR-T manufacturing assets, and emerging platform developers focused on off-the-shelf approaches. Competitive moves center on strategic partnerships with European contract development organizations and backward integration into viral vector production.
Among Swiss-based pharmaceutical sponsors, Novartis AG and Roche Holding AG exemplify the large-cap diversified archetype with established European manufacturing footprints. Bristol-Myers Squibb Co represents the mid-cap cell therapy specialist position with dual-platform investments spanning autologous and allogeneic sources. These three anchors sit within a competitive set where supply relationships with centralized hospital accreditation programs determine commercial access.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca |
| Integra LifeSciences Corporation |
| Amgen Inc. |
| Medtronic plc |
| Bristol-Myers Squibb Co |
| Johnson & Johnson |
| Roche Holding AG |
| Smith & Nephew plc |
| Others |
Supply & Pricing Matrix
Liquid nitrogen consumption for cryopreservation below minus 150 degrees Celsius anchors cost structures through German and French academic hospital networks, flowing from specialized gas suppliers through centralized procurement tiers to consolidated specialist centers with cell therapy accreditation.
Pricing Analysis
Volume concentration in CAR-T procurement splits margin capture between autologous platforms at premium tiers and emerging allogeneic alternatives compressing mid-market positioning. Price differentiation hinges on EMA ATMP certification status and cryopreservation infrastructure tier, with centralized specialist centers commanding preferential contract terms over fragmented general wards. Cost compression in standard-tier cell therapies intensifies as European contract development organizations scale viral vector manufacturing capacity. Biotech development-stage entities exhibit highest price sensitivity, while integrated pharmaceutical sponsors with captive manufacturing absorb input volatility.
Supply Chain Analysis
Aseptic bioprocessing talent scarcity in the Rhine-Main and Upper Bavaria clusters constrains workforce expansion for German cell therapy manufacturing sites. Raw material dependencies center on single-use bioreactor consumables, viral vector production media, and cryopreservation-grade liquid nitrogen, drawing from specialized chemical suppliers and industrial gas distributors. Single-source vulnerability in automated closed-system bioreactor platforms elevates supply chain risk as EU Green Deal sustainability mandates disrupt established manufacturing consumables. Distribution runs through cold-chain logistics networks reconfigured for temperature-sensitive product handling between European contract development organizations and centralized hospital accreditation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's regenerative medicines market constitutes a consolidation play as centralized hospital accreditation programs compress vendor access points and elevate manufacturing scale requirements beyond the reach of fragmented biotech developers.
For Market Incumbents: Cement supply relationships with France's university hospital networks and England's NHS specialized commissioning frameworks through three-to-five year integrated manufacturing partnerships. Prioritize backward integration into viral vector production capacity at Rhine-Main and Île-de-France manufacturing clusters to defend margin position against emerging allogeneic platform entrants. Lock in cryopreservation infrastructure exclusivity at designated treatment centers to create switching costs.
For New Entrants and Emerging Players: CRISPR-enabled allogeneic cell source platforms offer a technology-first wedge into orthopedic tissue engineering applications where scaffold-based bone grafts remain underpenetrated relative to oncology saturation. Target Italy's emerging cardiac cell therapy corridor as reimbursement frameworks mature for Phase III trial endpoints. Pursue strategic partnerships with European contract development organizations for viral vector manufacturing access rather than greenfield capacity investment.
For Investors and Strategic Acquirers: EMA approval timelines shortening for novel ATMP classifications is the leading indicator that platform economics will shift toward scaled manufacturing footprints over discovery-stage assets. Frame long-term viability around five-to-ten year windows for automated bioprocessing technology adoption. Target acquisition profiles featuring dual-platform investments spanning autologous and allogeneic cell sources with established centralized hospital procurement relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Hospital Accreditation Partnership | Three-to-five year supply agreements with France's university hospital networks lock in commercial access. |
| Viral Vector Manufacturing Scale-Up | Capacity expansion at European contract development organizations reduces pipeline advancement constraints. |
| Automated Closed-System Bioreactor Adoption | German and French cell therapy centers deploy platforms reducing contamination risk and batch variability. |
| Allogeneic Cell Source Platform Development | Off-the-shelf therapies promise manufacturing scale advantages over patient-specific autologous approaches. |
| EU AI Act Compliance Infrastructure | Algorithmic transparency documentation for patient stratification tools creates first-mover positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with cell therapy manufacturing executives, hospital procurement managers at German academic medical centers, EMA regulatory affairs leads, and formulary directors within France's ANSM assessment framework. Secondary sources included EMA ATMP approval databases, ClinicalTrials.gov pipeline tracking, BfArM reimbursement decision records, and EU Green Deal pharmaceutical manufacturing compliance disclosures. Bottom-up patient-flow modeling and top-down market sizing triangulated volume and value estimates.
Granularity-level modeling deployed treatment line stratification, regional regulatory cluster differentiation, and cryopreservation infrastructure tier classification across the projection horizon. Segmentation dimensions encompassed product type, application, end user, and technology platform with patient population sizing for addressable market calculation. CAGRs derived from growth driver elasticity analysis against baseline adoption curves, incorporating viral vector manufacturing capacity expansion timelines and centralized hospital accreditation rollout schedules as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen EMA regulatory science guidance revisions, abrupt shifts in France-Germany reimbursement divergence, and breakthrough manufacturing automation disruptions. Forecasts reflect assumptions regarding sustained ATMP framework stability and cold-chain logistics network adaptation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market