
 Next Generation Immunotherapies Market | 2026-2036
Next Generation Immunotherapies Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Immunotherapies Market Foresight
Oncology hospital networks are bifurcating into CAR T-capable referral centers and community sites dependent on outsourced infusion. Bristol-Myers Squibb leverages its integrated cell therapy manufacturing footprint to control supply of autologous products. Roche anchors European demand through its distributed hospital pharmacy network. Merck & Co. competes on PD-1 combination protocols across solid tumor indications.
Next generation immunotherapies comprise engineered biological modalities—CAR T-cells, bispecific antibodies, and cytokine constructs—manufactured through viral vector transduction or recombinant protein expression, designed to redirect or amplify immune recognition of disease targets. Monoclonal antibodies occupy the largest revenue pool due to established reimbursement and manufacturing scale, while CAR T-cell therapy represents the fastest-expanding segment driven by lymphoma and multiple myeloma approvals. Immune checkpoint inhibitors concentrate margin capture in melanoma and lung cancer, though autoimmune toxicities limit expansion into earlier treatment lines.
The FDA accelerates market entry through breakthrough therapy and regenerative medicine advanced therapy designations, while EMA's PRIME scheme shapes European development priorities. ISO 14644 cleanroom standards govern cell therapy manufacturing, directly constraining production capacity and geographic distribution of treatment sites. Stakeholders must monitor whether payer willingness to fund inpatient CAR T administration keeps pace with outpatient subcutaneous delivery innovations reshaping site-of-care economics.
Market Dynamics
The FDA's breakthrough therapy designation compresses clinical timelines for engineered cell products while ISO 14644 cleanroom standards constrain manufacturing capacity expansion. This regulatory acceleration collides with physical production bottlenecks, reshaping competitive positioning across autologous therapy supply chains.
Growth Catalysts
- Regulatory Acceleration:The FDA's regenerative medicine advanced therapy designation compresses review timelines for CAR T-cell products. EMA's PRIME scheme mirrors this pathway in Europe.
- Site-of-Care Expansion:Academic medical centers in the United States are expanding dedicated immuno-oncology infusion units. These facilities anchor referral networks for complex cell therapies.
- Vector Manufacturing Scale-Up:Viral vector production capacity is concentrating in specialized CDMO clusters. This concentration enables larger-batch lentiviral and retroviriral supply for transduction processes.
Market Restraints
- Input Cost Volatility:Plasmid DNA and fetal bovine serum prices fluctuate with biopharma demand cycles. These inputs represent fixed-cost anchors in viral vector production.
- Supply Concentration Risk:Lentiviral vector manufacturing concentrates in fewer than ten GMP-certified facilities globally. Any contamination event cascades through multiple sponsor pipelines.
- Technical Limitation:Autologous T-cell fitness varies with patient lymphodepletion status. Poor expansion yields force batch failures and treatment delays.
Strategic Opportunities
- Allogeneic Platform Shift:Off-the-shelf CAR T-cells from healthy donors promise inventory-based distribution. This technology convergence of genome editing and cell banking restructures site-of-care economics.
- Subcutaneous Delivery:Bispecific antibodies enable outpatient administration without cytokine release syndrome monitoring. Community oncology practices capture volume previously requiring inpatient admission.
- Japan's Regenerative Medicine Framework:PMDA's conditional approval pathway accelerates commercial entry for novel modalities. Sponsors target this geography for early revenue generation.
Industry Challenges
- Vector Manufacturing Talent Scarcity:GMP-grade viral production requires rare combinations of cell culture and analytical expertise. Training pipelines lag facility construction timelines.
- Batch Release Complexity:Potency assays for living cell products lack standardized reference materials. Lot-to-lot variability forces extended quality hold times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Immunotherapies Market |
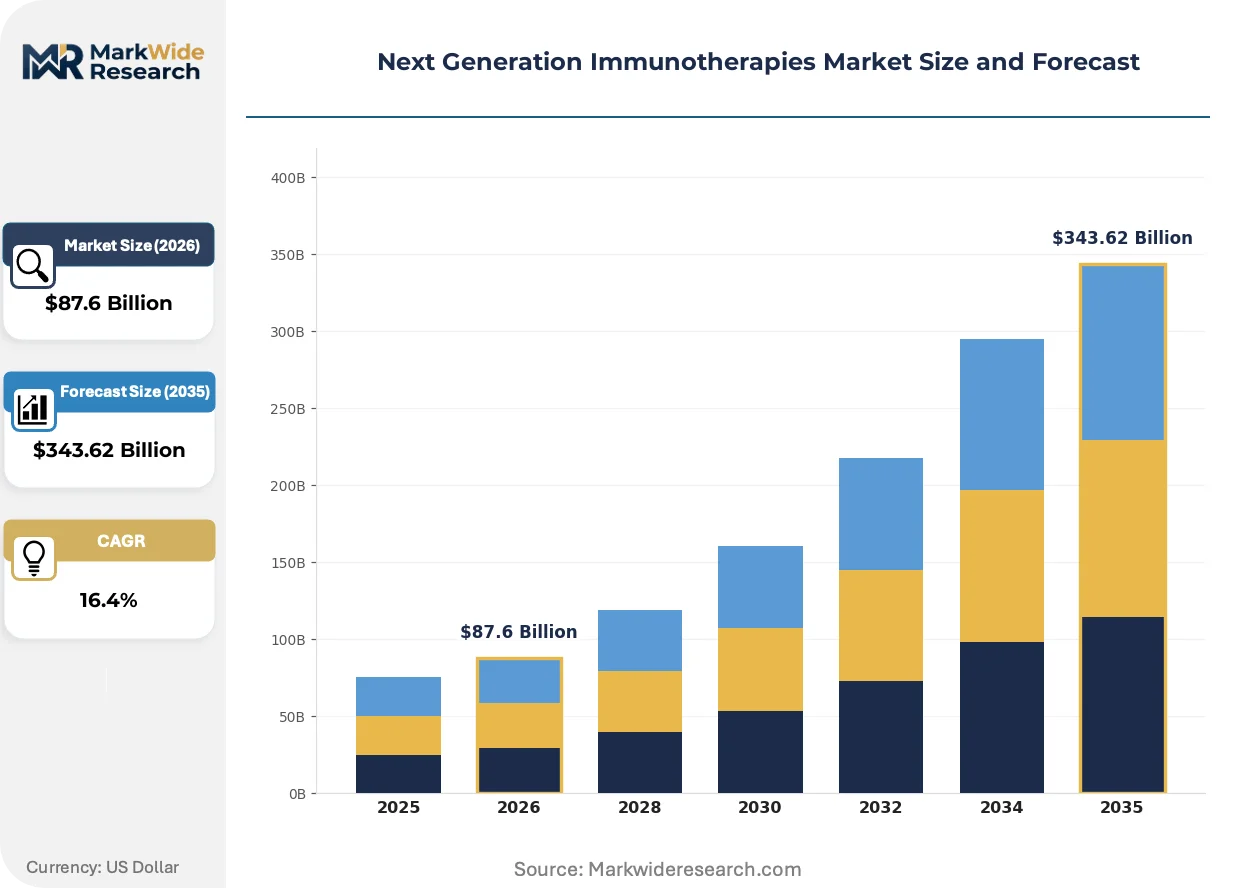
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, CAR T-Cell Therapy, Immune Checkpoint Inhibitors, Cytokine Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Local Injection Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Allergies End User: Hospitals, Research Institutions, Specialty Clinics, Homecare |
| Companies Covered | Bristol-Myers Squibb, Novartis, Roche, Merck & Co., AstraZeneca, Amgen, Regeneron Pharmaceuticals, GlaxoSmithKline, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Immunotherapies Market Shifts & Advancements
Engineered modalities are fragmenting established treatment hierarchies across hematologic and solid tumor indications. Manufacturing automation, regulatory science advances, and site-of-care redistribution collectively compress the gap between clinical proof and commercial reach.
CRISPR-edited allogeneic CAR T-cells are fragmenting the autologous manufacturing paradigm. Biotech developers and large pharma partners are advancing healthy-donor-derived inventories toward pivotal trials. This shift promises to displace patient-specific logistics with centralized batch production and cold-chain distribution to standard infusion centers.
EMA's updated good manufacturing practice Annex 1 requirements for sterile products are forcing cell therapy facilities toward closed-system automation. Manufacturers must validate isolator-based processing to reduce contamination risk. European production sites are responding with capital deployment into robotics and single-use technologies ahead of 2025 inspection cycles.
Hospital procurement for CAR T-cell therapy is consolidating through specialty pharmacy networks and manufacturer direct contracts. Community oncology sites without apheresis capability are losing access to autologous products. This pattern concentrates treatment volume in designated referral centers across the United States, Germany, and Japan.
Next Generation Immunotherapies Market Segmentation
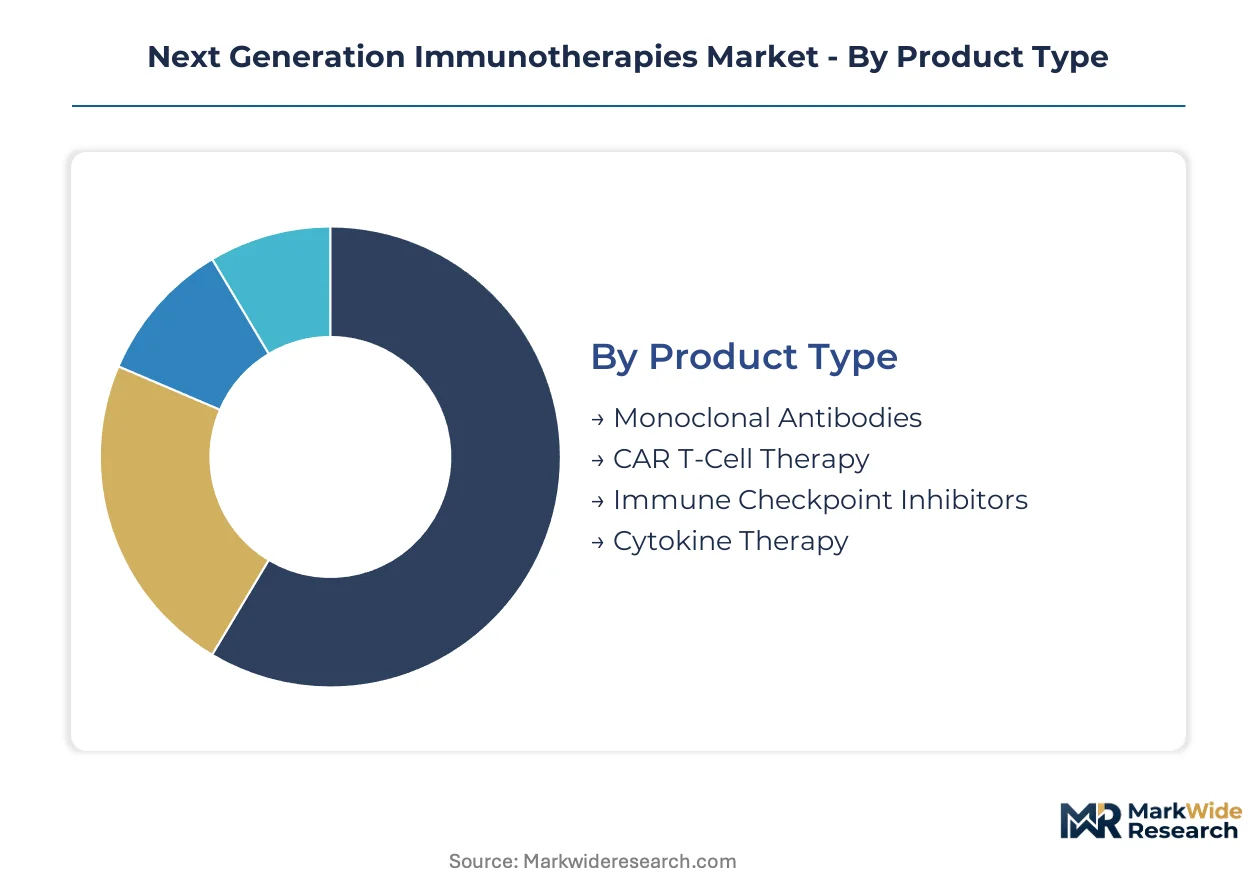
Engineered biological modalities fragment across distinct technical platforms, each carrying unique manufacturing constraints, regulatory pathways, and site-of-care requirements. Segmentation reveals where margin pools concentrate versus where adoption curves remain steep.
Product Type:
FDA breakthrough therapy designation and EMA PRIME scheme create divergent approval timelines across these modalities, compressing development for cell therapies while maintaining established review cadences for protein biologics.
- Monoclonal Antibodies:Recombinant protein constructs manufactured through mammalian cell culture in stainless steel or single-use bioreactors. Demand concentrates in United States hospital networks where established reimbursement codes and outpatient infusion protocols dominate oncology practice. Manufacturing scale and biosimilar competition now pressure originator pricing power.
- CAR T-Cell Therapy:Patient-derived T-cells engineered via lentiviral vector transduction to express chimeric antigen receptors. Academic medical centers in the United States anchor demand through dedicated apheresis and lymphodepletion units; autologous logistics constrain expansion into community settings. Supply bottlenecks in viral vector production limit patient access.
- Immune Checkpoint Inhibitors:PD-1 and CTLA-4 targeting antibodies with validated potency assays and cold-chain distribution networks. United States oncology practices drive volume through combination protocol adoption in melanoma and lung cancer indications.
- Cytokine Therapy:Engineered interleukin constructs and interferon variants requiring precise dosing to manage systemic inflammatory responses. Research institutions in Germany and Japan pilot novel constructs through early-phase investigator-initiated trials.
Established volume favors monoclonal antibodies; emerging adoption favors CAR T-cell therapy.
Delivery Mode:
Site-of-care economics and patient throughput requirements reshape competitive positioning across administration routes, with outpatient-capable modalities gaining share against inpatient-dependent alternatives.
- Intravenous:Infusion-based delivery requiring certified oncology nursing staff and emergency response capability for cytokine release syndrome. United States academic medical centers concentrate this volume through dedicated immuno-oncology units with extended monitoring capacity.
- Subcutaneous:Self-administered or clinic-based injection enabling community oncology practice participation without hospital admission. Bispecific antibody formats are climbing the fastest as manufacturers engineer reduced immunogenicity and simplified cold-chain requirements.
- Oral:Small-molecule immunomodulators with distinct pharmacokinetic profiles from biologic therapies. Specialty pharmacy networks in the United States manage distribution through restricted dispensing programs.
- Local Injection:Intratumoral or lymph node-targeted administration requiring interventional radiology or surgical coordination. Research institutions pilot these approaches for solid tumor indications with limited systemic exposure.
Hospital infrastructure investment favors intravenous capacity; margin expansion favors subcutaneous migration.
Therapy Area:
Clinical validation density and payer coverage determination vary sharply across disease categories, concentrating commercial resource deployment where proof-of-concept is mature.
- Oncology:Hematologic malignancies and solid tumors with established biomarker stratification. The United States National Cancer Institute funds the majority of early-stage trials, anchoring global development priorities.
- Autoimmune Disorders:Rheumatoid arthritis, multiple sclerosis, and inflammatory bowel disease with chronic administration requirements. European rheumatology networks drive adoption where EMA guidance on immunogenicity assessment is established.
- Infectious Diseases:Emerging applications in chronic viral persistence and resistant bacterial infections. Japanese regenerative medicine frameworks accelerate evaluation for novel host-directed therapies.
- Allergies:Desensitization and tolerance induction through engineered immune modulation. Specialty clinics in Germany concentrate pilot programs for severe atopic conditions.
Revenue concentration favors oncology; pipeline diversification favors autoimmune expansion.
End User:
Capability requirements for apheresis, vector handling, and patient monitoring fragment the customer base into distinct procurement and service models.
- Hospitals:Integrated delivery networks with CAR T-capable infrastructure including apheresis units, cleanroom pharmacy, and ICU step-down capacity. United States health systems consolidate referrals to designated centers of excellence.
- Research Institutions:Academic medical centers with investigator-initiated trial infrastructure and GMP-adjacent manufacturing partnerships. National funding agencies in the United States, Germany, and Japan anchor this demand.
- Specialty Clinics:Community oncology practices capturing subcutaneous bispecific antibody volume without hospital admission requirements. United States group purchasing organizations reshape procurement leverage for this segment.
- Homecare:Emerging channel for subcutaneous self-administration with remote monitoring support. Reimbursement frameworks in the United States and Germany are gaining the fastest traction for qualified patient populations.
Complex therapy dependence favors hospital concentration; convenience and cost pressure favor homecare expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy manufacturing equipment and viral vectors flow predominantly from German and Swiss precision engineering clusters into United States academic medical centers, while Japanese bioreactor technology exports serve expanding APAC cleanroom construction.
United States
The National Cancer Institute funds over sixty percent of early-phase immuno-oncology trials, concentrating investigator-initiated research at academic medical centers. FDA breakthrough therapy and regenerative medicine advanced therapy designations compress review timelines for engineered cell products. Boston and San Francisco anchor CAR T-capable referral networks with integrated apheresis units and ICU step-down capacity.
Germany
EMA's PRIME scheme shapes European development priorities while German university hospitals pilot allogeneic platform trials. Updated Annex 1 GMP requirements for sterile products force cell therapy facilities toward closed-system automation. Heidelberg and Munich clusters concentrate lentiviral vector manufacturing expertise alongside robotics suppliers.
Japan
PMDA's conditional approval pathway accelerates commercial entry for novel modalities, attracting sponsors seeking early revenue generation. METI funding for regenerative medicine manufacturing infrastructure expands Kobe and Osaka biocluster capacity. Tokyo academic medical centers anchor regional referral networks for complex cell therapies.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while offering specialized consultation for advanced therapy medicinal products. Basel anchors contract development and manufacturing organization concentration for viral vector production. Zurich and Geneva university hospitals coordinate multicenter European trials for bispecific antibody constructs.
United Kingdom
The Medicines and Healthcare products Regulatory Agency operates post-Brexit recognition pathways with FDA and EMA, preserving trial continuity. London and Oxford academic networks concentrate early-phase cell therapy manufacturing partnerships. Manchester and Birmingham health systems expand dedicated immuno-oncology infusion units.
Next Generation Immunotherapies Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with cell therapy manufacturing footprints, creating tiered competition between autologous product sponsors and allogeneic platform developers. Structure concentrates around three strategic archetypes: large-cap biopharma with captive viral vector capacity, mid-cap cell therapy specialists dependent on contract manufacturing, and emerging genome editing platforms pursuing healthy-donor inventories. Dominant competitive moves include strategic partnerships for vector manufacturing access and geographic expansion of cleanroom pharmacy networks.
Among United States-based integrated developers, Bristol-Myers Squibb and Novartis exemplify the large-cap archetype with established CAR T-cell approval portfolios and controlled supply chains. Roche anchors European positioning through distributed hospital pharmacy networks, representing the regional infrastructure play. Merck & Co. occupies a position defined by PD-1 combination protocol dominance across solid tumor indications, illustrating the checkpoint inhibitor consolidation strategy.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Novartis |
| Roche |
| Merck & Co. |
| AstraZeneca |
| Amgen |
| Regeneron Pharmaceuticals |
| GlaxoSmithKline |
| Pfizer |
| Others |
Supply & Pricing Matrix
Viral vector manufacturing scale economies in the United States and Germany anchor price floors for autologous CAR T-cell therapies, while ISO 14644 cleanroom capacity utilization rates directly determine per-batch cost structures across academic medical center networks. Pricing power concentrates with sponsors possessing captive lentiviral production, forcing contract-dependent developers to absorb margin compression from plasmid DNA and fetal bovine serum input volatility.
Pricing Analysis
Next-generation allogeneic platform pricing gaps against established autologous products reflect manufacturing automation dividends and inventory-based distribution economics. Three-tier pricing structure across premium in-patient administered cell therapies, standard outpatient bispecific antibodies, and emerging subcutaneous self-administered formats stratifies reimbursement negotiations. Cost compression in autologous manufacturing is intensifying because viral vector CDMO queues extend patient wait times and force batch failure risk absorption. Community oncology practices exhibit highest price sensitivity due to absent apheresis infrastructure, while integrated academic medical centers with captive pharmacy networks demonstrate lowest sensitivity.
Supply Chain Analysis
The United States and Germany anchor lentiviral vector manufacturing through GMP-certified cleanroom clusters in Boston, San Francisco, Heidelberg, and Munich. Plasmid DNA templates, fetal bovine serum, and recombinant cytokines draw from concentrated bioreactor feedstock suppliers across North American and European bioclusters. Single-source vulnerability in lentiviral vector production—fewer than ten GMP facilities globally—cascades contamination risk across multiple sponsor pipelines. Distribution runs through specialty pharmacy networks and manufacturer direct contracts to designated CAR T-capable hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as site-of-care redistribution bifurcates between inpatient academic centers and outpatient community practices, creating distinct procurement and service niches across delivery modalities.
For Market Incumbents: Fortify vector manufacturing capacity through backward integration into plasmid DNA production and captive cleanroom expansion in United States and German bioclusters. Allogeneic platform developers threaten autologous product franchises by promising inventory-based distribution without patient-specific logistics; incumbents must secure genome editing partnerships and healthy-donor cell banking infrastructure to defend positioning. For New Entrants and Emerging Players: Differentiate on subcutaneous bispecific antibody formats that bypass cytokine release syndrome monitoring requirements and enable community oncology practice penetration. White-space targets concentrate in Japan's PMDA conditional approval pathway for early revenue generation and in European autoimmune disorder applications where EMA immunogenicity guidance is established. Go-to-market execution should prioritize group purchasing organization channel partnerships over hospital direct contracting. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors allogeneic platform developers with demonstrated CRISPR editing efficiency and scalable cold-chain distribution capabilities. Long-term viability across the projection horizon hinges on successful displacement of patient-specific manufacturing with centralized batch production. Acquisition target archetype: mid-cap cell therapy specialists with validated healthy-donor CAR T-cell expansion protocols. Signal to watch: FDA regenerative medicine advanced therapy designation grants for off-the-shelf inventory products.| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Development | CRISPR-edited healthy-donor inventories displace patient-specific logistics with centralized manufacturing. |
| Closed-System Automation Investment | EMA Annex 1 GMP compliance forces European facilities toward isolator-based cell processing robotics. |
| Subcutaneous Delivery Engineering | Bispecific antibody formats enable community oncology practice participation without hospital admission. |
| Viral Vector Manufacturing Scale-Up | Lentiviral production capacity concentration in CDMO clusters enables larger-batch transduction supply. |
| Japan Regulatory Pathway Entry | PMDA conditional approval accelerates commercial entry for novel regenerative medicine modalities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA breakthrough therapy designations, EMA PRIME scheme submissions, ClinicalTrials.gov protocols, and hospital formulary databases. Primary interviews engaged cell therapy manufacturing executives, regulatory affairs leads at advanced therapy sponsors, academic medical center pharmacy directors, and payer access specialists across United States, German, and Japanese markets. Secondary validation drew from SEC 10-K disclosures, ISO 14644 facility certification records, and GPO contract documentation. Bottom-up patient-volume modeling triangulates against top-down revenue estimates across product type and delivery mode segments.
Segmentation dimensions modeled include engineered modality platform, administration route, therapy area indication, and end-user facility type across the projection horizon. Treatment line positioning, biomarker stratification requirements, and regional regulatory cluster characteristics inform patient access and pricing assumptions. CAGRs derive from logistic diffusion curves fitted to approval timeline compressions under FDA regenerative medicine advanced therapy and EMA PRIME pathways. Forecast inputs incorporate viral vector manufacturing capacity expansion schedules and site-of-care infrastructure investment patterns at designated referral centers.
Material uncertainties — regulatory approval delays for allogeneic platforms, vector manufacturing contamination events, and payer reimbursement restrictions on inpatient administration — sit outside the modeled envelope. Forecasts reflect assumptions regarding FDA breakthrough therapy designation continuity and EMA Annex 1 GMP inspection timelines. Recalibration cycles align with material shifts in site-of-care economics and viral vector production capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Tooth Regeneration Market