
 North America Satellite Manufacturing Market | 2026-2036
North America Satellite Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Satellite Manufacturing Market Insights
The FCC's streamlined small-satellite licensing is expanding access to orbital slots for non-traditional manufacturers. Maxar Technologies Inc leverages its integrated vertical stack from satellite design to geospatial analytics. Space Exploration Technologies Corp anchors commercial launch capacity, creating captive demand for internally produced spacecraft. Lockheed Martin Corporation sustains long-cycle government programs through classified and civilian agency contracts.
North America satellite manufacturing encompasses the design, fabrication, integration, and testing of spacecraft platforms, payloads, and propulsion systems operating in Low Earth Orbit, Geostationary, Medium Earth Orbit, and Nano Satellite configurations, typically involving aluminum-lithium alloy structures, gallium arsenide solar arrays, and chemical or electric propulsion subsystems engineered to withstand thermal cycling, radiation exposure, and vacuum conditions for missions spanning telecommunications, Earth observation, navigation, and scientific research. Low Earth Orbit platforms dominate current production volume as commercial operators deploy dense constellations for broadband and remote sensing. Electric Propulsion and Additive Manufacturing segments attract disproportionate engineering investment due to their potential to reduce mass-to-orbit and compress production timelines.
The FAA governs commercial launch licensing and spaceport certification, while the FCC regulates spectrum allocation and orbital debris mitigation, with both agencies tightening environmental review and collision-avoidance protocols that shape spacecraft design requirements and operational lifespans. NHTSA and OSHA standards indirectly influence ground handling and integration facility safety protocols. Stakeholders must monitor evolving debris-remediation mandates and spectrum-reallocation proceedings that could redefine permissible orbital architectures and communication bandwidth access.
Market Dynamics
The FCC's accelerated small-satellite licensing timeline is compressing procurement cycles from 18 months to 90 days, forcing manufacturers to reconfigure production lines for batch assembly rather than bespoke spacecraft fabrication.
Growth Catalysts
- Streamlined Orbital Licensing:The FCC's Part 25 licensing reforms eliminated procedural bottlenecks for non-geostationary constellations, enabling rapid deployment of broadband and remote sensing networks.
- LEO Constellation Demand:Commercial Earth Observation operators are placing multi-unit production orders that amortize fixed engineering costs across standardized bus architectures.
- Electric Propulsion Maturation:Hall-effect thrusters and gridded ion engines are replacing chemical systems, reducing propellant mass fractions and extending operational lifespans for station-keeping missions.
Market Restraints
- Gallium Arsenide Supply Concentration:Solar cell substrate production clusters in East Asian foundries, exposing North American assemblers to export control disruptions and long-lead procurement timelines.
- Radiation-Hardened Component Scarcity:Qualified microelectronics for deep-space missions rely on a shrinking domestic vendor base with limited foundry capacity.
- Debris Mitigation Compliance Costs:FCC orbital debris rules mandate post-mission disposal and collision-avoidance systems, adding non-recurring engineering expenses to every platform.
Strategic Opportunities
- Mexican Nearshoring:Baja California and Chihuahua offer lower-cost cleanroom and integration facilities within USMCA trade corridors, reducing logistics exposure for California-based prime contractors.
- Additive Manufacturing Integration:Titanium and aluminum-lithium alloy 3D printing is collapsing lead times for propulsion manifolds and structural brackets, enabling same-day design iterations.
- Defense Dual-Use Contracts:Space Development Agency proliferated-LEO architectures are creating stable demand for commercially derived buses with military-grade encryption payloads.
Industry Challenges
- Workforce Pipeline Gaps:Systems engineering and thermal analysis talent concentrates in legacy aerospace hubs, constraining expansion in emerging manufacturing clusters.
- Environmental Qualification Bottlenecks:Thermal vacuum and vibration test facilities operate at capacity, forcing queue delays that compress delivery schedules.
- Supply Chain Reconfiguration Friction:Transitioning from single-source heritage avionics to commercial-off-the-shelf alternatives requires extensive requalification campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Satellite Manufacturing Market |
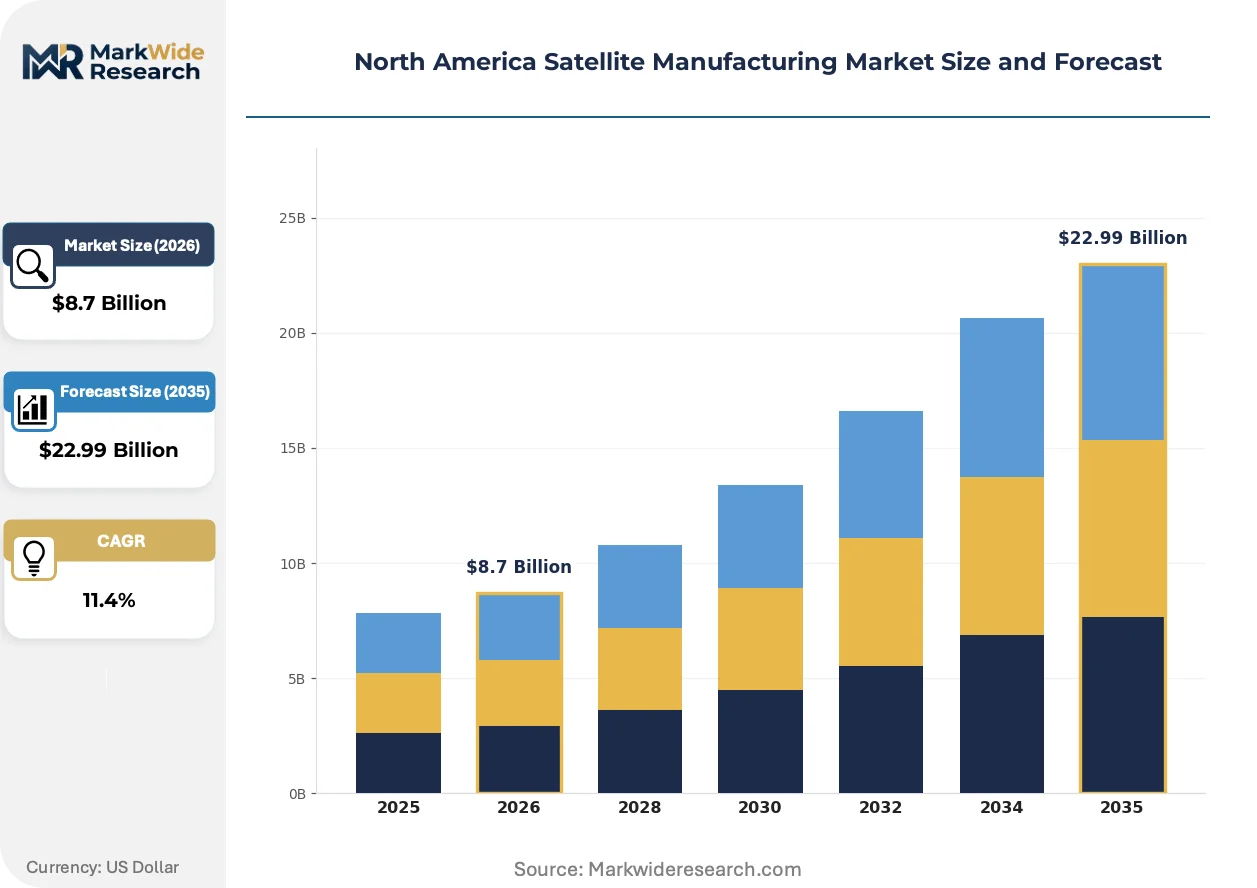
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Earth Orbit, Geostationary, Medium Earth Orbit, Nano Satellites Technology: Solar Power, Chemical Propulsion, Electric Propulsion, Additive Manufacturing End User: Government, Commercial, Educational Institutions, Research Organizations Application: Telecommunications, Earth Observation, Scientific Research, Navigation |
| Companies Covered | Maxar Technologies Inc, Planet Labs Inc, Space Exploration Technologies Corp, Swarm Technologies Inc, Spire Global Inc, Lockheed Martin Corporation, Boeing, Capella Space Corp, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Satellite Manufacturing Market Trends and Innovations
Modular satellite architectures are displacing monolithic platforms across mission profiles, enabling rapid payload swaps and reducing non-recurring engineering for constellation operators seeking orbital refresh cycles.
Software-defined radio payloads are decentralizing communications architecture decisions from hardware fabrication to post-launch configuration. Commercial operators including broadband constellations and IoT aggregators are adopting reprogrammable transponders that shift frequency plans without physical module replacement. This flexibility is compressing the hardware specification freeze point from 24 months pre-launch to 6 months, reducing obsolescence risk.
The FCC's revised orbital debris mitigation rules now mandate collision probability assessments and post-mission disposal reliability demonstrations for all new license applications. Manufacturers must integrate propulsion systems capable of controlled deorbit within 5 years of mission completion or relocate to graveyard orbits. Small-satellite builders with limited propulsion budgets face the steepest redesign requirements, driving partnerships with electric thruster suppliers.
Consolidated procurement by mega-constellation operators is collapsing vendor diversity as prime contractors impose approved supplier lists and volume-commitment contracts. Tier-2 component vendors report 60% revenue concentration from three anchor customers, creating pricing pressure and intellectual property exposure. The Southwest US aerospace corridor from El Segundo to Denver exhibits the most pronounced buyer concentration, with integration facilities clustering around launch ranges to minimize transport risk.
North America Satellite Manufacturing Market Segmentation
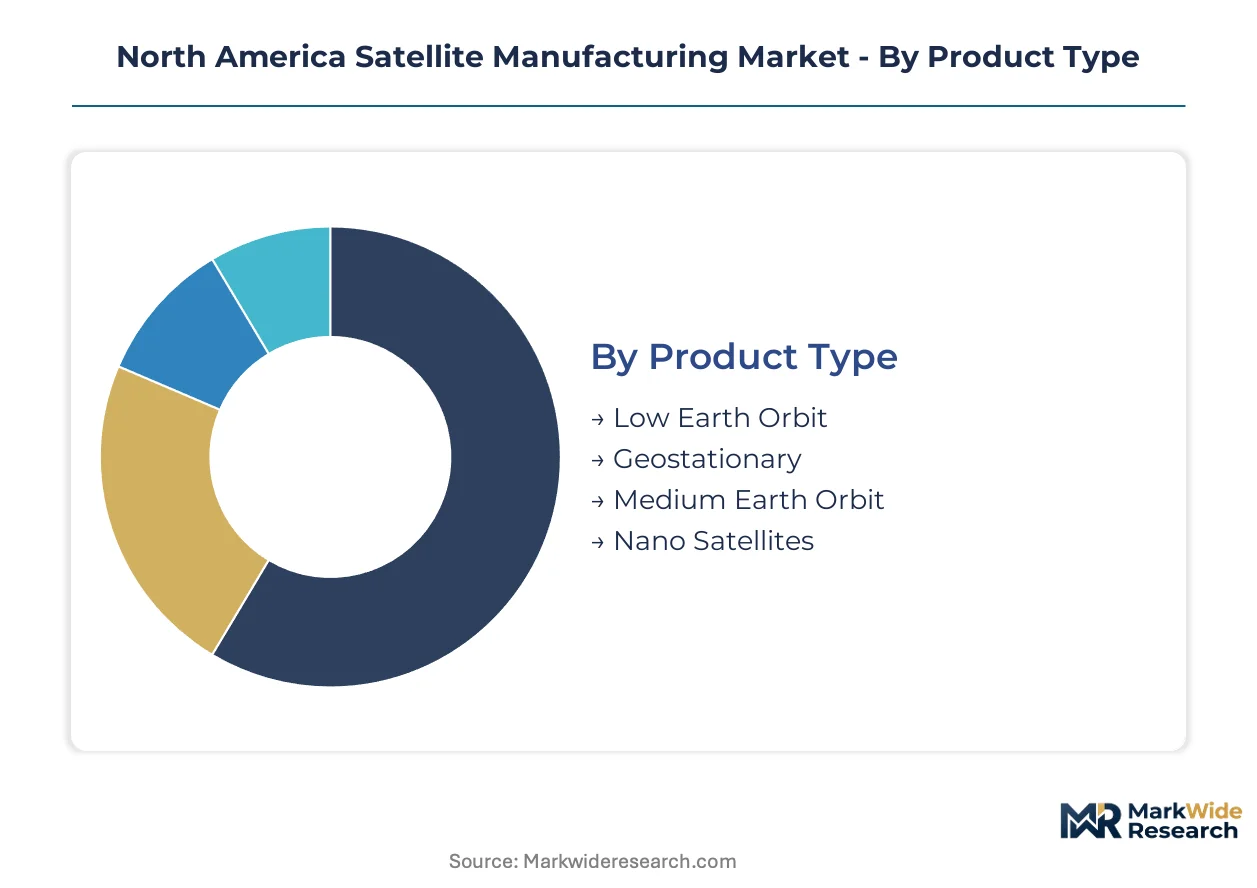
Segmentation in North American satellite manufacturing reveals divergent capital requirements and production rhythms across orbital architectures and propulsion technologies. Manufacturers configure assembly lines differently for high-volume LEO constellations versus bespoke geostationary platforms, with direct implications for facility investment and supplier relationships.
Product Type:
Capital intensity peaks with Geostationary platforms requiring extensive thermal qualification and precision payload integration, while Nano Satellites demand minimal fixed asset deployment.
- Low Earth Orbit:Aluminum-lithium alloy buses with standardized payload interfaces dominate California production facilities. Commercial broadband operators in Los Angeles and Seattle corridors are driving multi-hundred-unit procurement campaigns that amortize engineering across identical platforms.
- Geostationary:These three-axis stabilized platforms incorporate gallium arsenide solar arrays spanning 15-20 kilowatts and chemical propulsion systems for orbital insertion. FCC licensing timelines for geostationary slots extend 24-36 months, locking manufacturers into long-cycle contracts with established prime contractors.
- Medium Earth Orbit:GPS augmentation and navigation constellations occupy this intermediate altitude band with radiation-hardened avionics requirements.
- Nano Satellites:CubeSat form factors under 10 kilograms enable university and commercial experimentation with minimal launch cost exposure.
Most installed capacity flows through Low Earth Orbit. Expansion is steepest in Nano Satellites.
Technology:
Application requirements dictate technology selection, with telecommunications payloads prioritizing power generation while scientific missions emphasize propulsion efficiency.
- Solar Power:Triple-junction gallium arsenide cells bonded to aluminum honeycomb substrates deliver 30% conversion efficiency. East Asian foundry concentration creates procurement vulnerability for North American assemblers seeking supply chain resiliency.
- Electric Propulsion:Hall-effect thrusters and gridded ion engines reduce propellant mass fractions from 40% to 5% for station-keeping missions. SDA proliferated-LEO architectures in Colorado and Virginia are specifying electric systems for constellation replenishment.
- Chemical Propulsion:Bipropellant and monopropellant systems remain standard for orbital insertion maneuvers requiring high thrust.
- Additive Manufacturing:Titanium and aluminum-lithium 3D printing collapses lead times for propulsion manifolds and structural brackets.
Volume concentrates in Solar Power. Electric Propulsion is gaining share fastest.
End User:
Customer type determines contract structure, with government programs sustaining multi-year development cycles and commercial operators demanding accelerated delivery.
- Government:Classified programs through Space Force and NRO sustain Lockheed Martin and Northrop Grumman facilities in California and Colorado with cost-plus contracting. Congressional appropriation cycles create predictable but lumpy demand.
- Commercial:Earth observation operators and broadband constellation deployers in the El Segundo to San Francisco corridor are compressing procurement cycles to 90 days. FCC streamlined licensing enables rapid fleet expansion.
- Educational Institutions:University CubeSat programs provide workforce pipeline entry points.
- Research Organizations:NASA science missions and NOAA weather platforms require specialized instrumentation integration.
Revenue concentration sits with Government. Commercial is climbing the fastest.
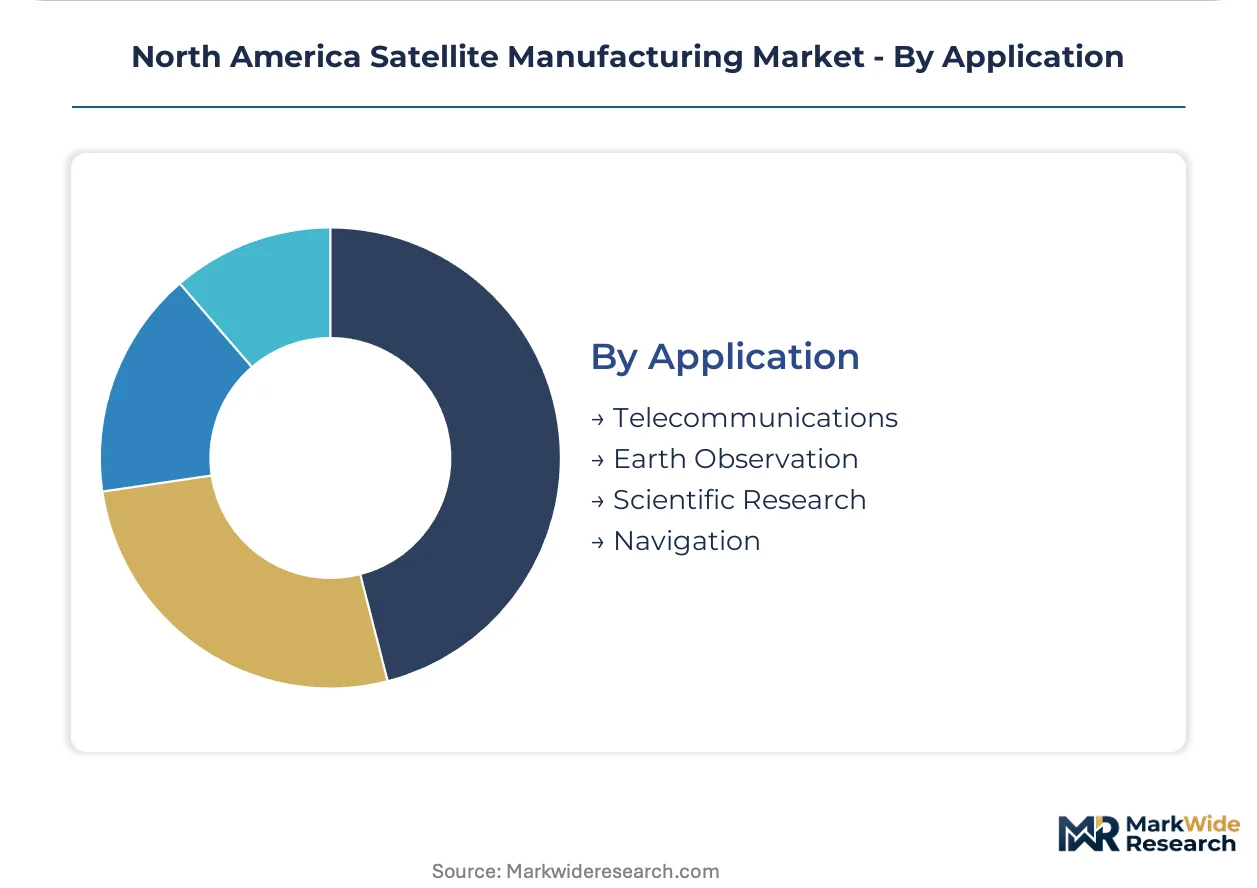
Application:
Mission profiles determine payload specifications, with telecommunications demanding high-power amplifiers and Earth observation requiring precision pointing stability.
- Telecommunications:Ka-band and V-band transponders with software-defined radio architectures enable frequency plan reconfiguration post-launch. Starlink and OneWeb derivative programs in the Southwest aerospace corridor are specifying reprogrammable payloads.
- Earth Observation:Synthetic aperture radar and multispectral imagers require sub-meter pointing accuracy and thermal stability. Maxar and Planet Labs operations in San Francisco and Denver are driving optical payload integration demand.
- Scientific Research:Deep-space probes and heliophysics missions impose radiation-hardening requirements.
- Navigation:GPS III follow-on and augmentation systems demand atomic clock precision.
Deployment volume flows through Telecommunications. Earth Observation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engineering talent concentrates along the California corridor from Los Angeles to San Francisco, anchoring North American satellite manufacturing capacity. This workforce density shapes procurement patterns and supplier clustering across the continent.
United States
Commercial Earth Observation operators in San Francisco and Denver are scaling constellation orders for broadband and remote sensing networks. The FCC's streamlined Part 25 licensing reforms compress time-to-orbit from 18 months to 90 days. California's aerospace corridor from El Segundo to Silicon Valley hosts integration facilities clustering around Vandenberg and Cape Canaveral launch ranges.
Canada
Robotics and space situational awareness capabilities in Ontario and Quebec support satellite servicing and debris tracking missions. The Canadian Space Agency's funding programs for LEO broadband participation create procurement channels for domestic component suppliers. Greater Toronto and Montreal host cleanroom facilities serving US prime contractors under USMCA trade terms.
Mexico
Baja California and Chihuahua offer lower-cost cleanroom and integration facilities within USMCA corridors, reducing logistics exposure for California-based manufacturers. Mexico's federal economic development programs designate aerospace as a priority sector for foreign direct investment. Tijuana and Mexicali house satellite component assembly operations supplying US integration facilities.
North America Satellite Manufacturing Market Competitive Landscape
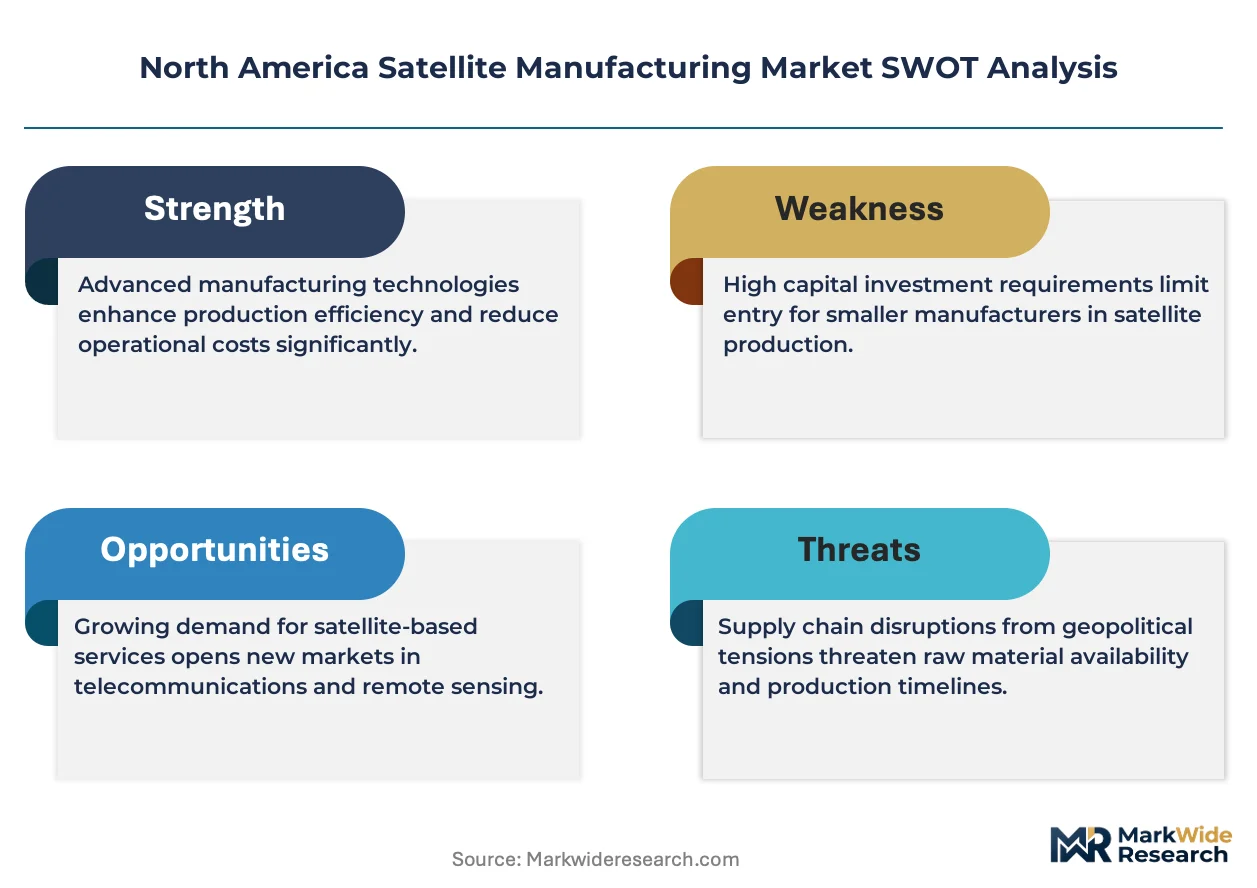
Diversified conglomerates compete with focused pure-play specialists across North American satellite manufacturing. Tier-1 primes with defense heritage sustain long-cycle government contracts through classified programs and civilian agency awards. Emerging commercial operators deploy vertically integrated strategies, combining launch capacity with captive spacecraft production. Consolidation pressure intensifies as mega-constellation procurement concentrates purchasing power among three anchor customers. Strategic moves center on additive manufacturing integration and Mexican nearshoring for cost-sensitive component assembly.
Within the vertically integrated tier, Space Exploration Technologies Corp exemplifies launch-captive manufacturing models, while Maxar Technologies Inc represents integrated design-to-analytics stacks. Lockheed Martin Corporation anchors the defense-contractor archetype sustaining multi-year development cycles through Space Force and NRO programs.
| Leading Market Players |
|---|
| Maxar Technologies Inc |
| Planet Labs Inc |
| Space Exploration Technologies Corp |
| Swarm Technologies Inc |
| Spire Global Inc |
| Lockheed Martin Corporation |
| Boeing |
| Capella Space Corp |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
Performance-grade divergence between radiation-hardened geostationary platforms and commercial-off-the-shelf LEO buses manifests in both procurement economics and supplier network configurations across the North American satellite manufacturing ecosystem. Premium-tier contracts for government missions sustain cost-plus pricing with heritage component suppliers, while commodity-tier constellation production forces prime contractors toward Mexican nearshoring and additive manufacturing to preserve margins under fixed-price pressure.
Pricing Analysis
Bundled turnkey solutions encompassing satellite design, integration, and launch brokering command premium positioning against unbundled component-only transactions. Pricing stratifies across premium, standard, and economy tiers based on radiation-hardening certification levels and volume scale commitments. Cost compression in commercial LEO buses is intensifying because mega-constellation operators consolidate purchasing power among three anchor customers. Educational institutions and research organizations exhibit highest price sensitivity, while classified government programs demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Workforce availability constraints in California's aerospace corridor from El Segundo to Silicon Valley are pushing prime contractors toward Baja California and Chihuahua for cleanroom assembly operations. Supply concentration rests on East Asian foundries for gallium arsenide solar cell substrates, domestic radiation-hardened microelectronics vendors, and Mexican integration facilities. Single-source vulnerability in qualified component supply creates exposure to export control disruptions. Distribution runs through direct prime-contractor relationships with constellation operators and tiered subcontractor networks for government programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's USMCA-advantaged labor cost differential against California manufacturing rates positions the North America satellite manufacturing market as a geographic-arbitrage play for cost-sensitive component assembly and integration operations.
For Market Incumbents: Lock in long-term gallium arsenide supply agreements with East Asian foundries before export control tightening disrupts solar array production. Secure Vandenberg and Cape Canaveral adjacent integration facility capacity to minimize transport risk for constellation operators. Vertical integration into electric propulsion subsystem production defends against emerging pure-play thruster vendors capturing margin from prime contractors. For New Entrants and Emerging Players: University CubeSat programs represent an underserved buyer archetype with minimal incumbent competition and predictable funding cycles through NASA and NSF grants. Target Canadian robotics and space situational awareness capabilities in Ontario and Quebec where domestic content requirements create procurement preference for USMCA-qualified suppliers. Pursue software-defined radio payload partnerships with commercial broadband operators seeking rapid frequency reconfiguration without hardware replacement. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-2 component vendors report revenue concentration exceeding sixty percent from three anchor customers. Five-to-ten year viability favors additive manufacturing specialists with titanium and aluminum-lithium alloy 3D printing capabilities for propulsion manifolds. Watch FCC debris-mitigation rule enforcement stringency as inflection indicator for electric propulsion supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Mexican Nearshoring Expansion | Baja California cleanroom facilities reduce logistics exposure for California prime contractors under USMCA terms. |
| Additive Manufacturing Integration | Titanium 3D printing collapses lead times for propulsion manifolds at Space Development Agency proliferated-LEO suppliers. |
| Electric Propulsion Partnership | Hall-effect thruster sourcing agreements address FCC five-year deorbit mandates for small-satellite builders. |
| Software-Defined Radio Development | Reprogrammable transponder architectures compress hardware specification freeze points for Starlink derivative programs. |
| Defense Dual-Use Certification | Military-grade encryption payload integration unlocks Space Force and NRO cost-plus contracting stability. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with satellite systems engineers, FCC licensing specialists, prime contractor procurement directors, and Mexican economic development officers combined with bottom-up assembly. Secondary sources include FCC Part 25 licensing databases, FAA commercial launch manifests, SEC 10-K filings from aerospace conglomerates, and USMCA trade flow customs records.
Granularity-level modeling addressed orbital architecture, propulsion technology, end-user contract structure, and application mission profile across the projection horizon. Segment-specific CAGRs derived from production volume trajectories, constellation deployment schedules, and government appropriation cycle patterns. Industry-specific forecast inputs incorporated FCC streamlined licensing timeline compression effects and Space Development Agency proliferated-LEO architecture procurement ramps.
Underlying measurement precision varies by segment; Low Earth Orbit commercial constellation forecasts carry tighter precision than classified government program projections due to disclosure constraints. Forecasts reflect documented assumptions regarding regulatory stability, supply chain reshoring momentum, and electric propulsion technology maturation curves. Material deviation in FCC debris-mitigation enforcement, gallium arsenide export control expansion, or Space Force budget appropriation levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Cubesat Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Global Remote Sensing Services Market
Satellite
Nano and Microsatellite Market
Satellite
Commercial LEO Satellite Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Africa Satellite Connectivity Market
Satellite
Global Broadband Satellite Services Market
Satellite
Global Satellite Modem Market
Satellite
Satellite Compass Market
Satellite
M2M Satellite Communication Market
Satellite
LEO Satellite System Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Asia-Pacific Satellite IoT Market