
 North America Residential Construction Market | 2026-2036
North America Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Construction Market Outlook
The EPA Lead Renovation, Repair and Painting Rule is shifting the cost-of-entry calculus for residential contractors across the United States. D.R. Horton leverages national scale to absorb compliance overhead across its 90-plus metro markets. Lennar Corporation anchors its position through in-house mortgage and title services that streamline buyer conversion. Toll Brothers differentiates via luxury product specialization in supply-constrained coastal submarkets.
North America residential construction encompasses the ground-up erection of single-family homes, multi-family units, townhouses, and condominiums using wood framing, steel, concrete, or composite assemblies to create habitable dwelling structures. Wood-framed single-family homes dominate volume but face margin compression from lumber futures volatility and tariff-exposed Canadian softwood supply chains. Multi-family units represent the fastest-growing product type as zoning reforms in Texas, Florida, and North Carolina permit higher-density development near transit corridors. Design-build service arrangements capture expanding share from traditional general contracting as developers seek schedule certainty and consolidated accountability.
The National Association of Home Builders interfaces with the EPA and Department of Energy to shape model energy codes that govern insulation, HVAC efficiency, and envelope performance across member jurisdictions. Canada's National Building Code and provincial variants in Ontario and British Columbia enforce seismic and thermal standards that diverge from U.S. practice, fragmenting cross-border supplier qualification. State-level adoptions of the International Energy Conservation Code vary widely, with California's Title 24 and New York's stretch code imposing the most stringent requirements. Stakeholders must monitor municipal zoning liberalization and utility incentive programs that determine feasible project density and construction cost recovery timelines.
Market Dynamics
Population migration from high-cost coastal metros to Sun Belt states is compressing development timelines and forcing builders to accelerate entitlement processes while local infrastructure struggles to keep pace with permit volumes.
Growth Catalysts
- Texas zoning reforms:Municipalities across Dallas-Fort Worth and Austin are upzoning transit corridors to permit mid-rise multi-family density, unlocking previously restricted infill sites for ground-up construction.
- DOE appliance efficiency standards:Updated federal mandates for HVAC and water heating equipment are pulling forward replacement demand in existing housing stock, creating adjacent renovation revenue streams for residential contractors.
- Cross-laminated timber:Engineered wood products are gaining code approval for mid-rise structures in Washington and Oregon, expanding material options beyond steel and concrete for multi-family developers.
Market Restraints
- Canadian softwood lumber tariffs:Trade duty exposure on imported framing lumber creates margin volatility for U.S. builders dependent on cross-border supply chains.
- EPA Lead Renovation, Repair and Painting Rule:Certification requirements for disturbance of pre-1978 housing impose fixed compliance costs that disproportionately burden smaller renovation contractors.
- Limited skilled electrician availability:Journeyman licensing bottlenecks in California and New York are extending rough-in schedules and compressing subcontractor capacity during peak construction seasons.
Strategic Opportunities
- Utility demand-response incentives:Pacific Gas & Electric and Southern California Edison are offering construction-stage rebates for smart panel and battery-ready wiring, creating specification pull-through for builders.
- Accessory dwelling unit liberalization:California and Oregon state laws are preempting local single-family zoning to permit backyard cottages, opening incremental unit economics on existing lots.
- Panelized wall systems:Off-site fabrication of exterior envelopes is converging with just-in-time logistics to compress weather-dependent schedule risk in northern climate zones.
Industry Challenges
- OSHA silica exposure compliance:Respirable crystalline silica rules for concrete cutting and masonry work require capital investment in wet-cutting equipment and respiratory protection programs.
- Title 24 energy modeling:California's performance-based compliance pathway demands specialized software expertise and third-party verification that many mid-size builders lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Construction Market |
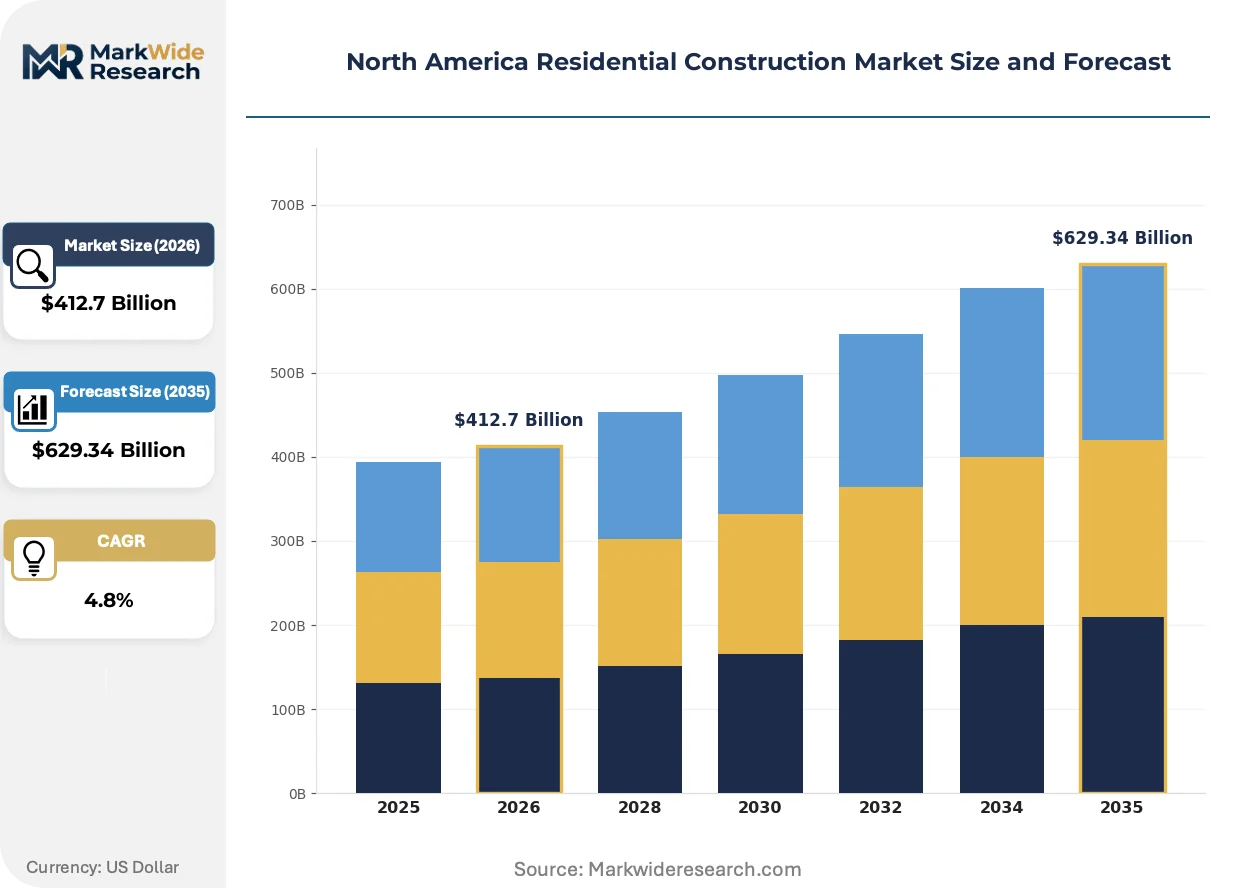
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Townhouses, Condominiums End User: First-Time Buyers, Real Estate Investors, Home Builders, Land Developers Construction Material: Wood, Steel, Concrete, Composite Materials Service Type: General Contracting, Subcontracting, Design-Build, Renovation Services |
| Companies Covered | NVR, Taylor Morrison, D.R. Horton, Meritage Homes Corp., KB Home, Lennar Corporation, Toll Brothers, Clayton Properties Group, PulteGroup, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Construction Market Strategic Shifts
Residential construction is experiencing a structural shift toward industrialized building methods and code-driven performance standards that reward scale and technical capability over traditional craft-based assembly.
Prefabricated bathroom pods are modularizing wet-area construction by consolidating plumbing rough-in, waterproofing, and finish installation into factory-controlled environments. Multi-family developers in Florida and Georgia are specifying these units to eliminate trade stacking conflicts and accelerate certificate-of-occupancy timelines. This approach is modularizing the critical path for high-rise projects where traditional sequential trades create schedule vulnerability.
California's Title 24 Building Energy Efficiency Standards are mandating solar-ready roof zones and electric vehicle circuit capacity in all new single-family construction. The regulation forces design-phase electrical load calculations and panel sizing that previously occurred only in custom builds. Builders in the Central Valley and Inland Empire are responding by standardizing 200-amp service and pre-wiring garage locations to avoid costly retrofit penalties.
Homebuyers are increasingly selecting properties through digital platforms that aggregate mortgage pre-qualification, virtual tours, and builder incentives into single-session transactions. This channel compression is disintermediating traditional broker relationships and concentrating buyer acquisition spend on Zillow, Redfin, and builder-direct digital marketing. The shift is most pronounced in Phoenix, Las Vegas, and Austin where inventory velocity and remote relocation patterns favor frictionless purchase pathways.
North America Residential Construction Market Segmentation
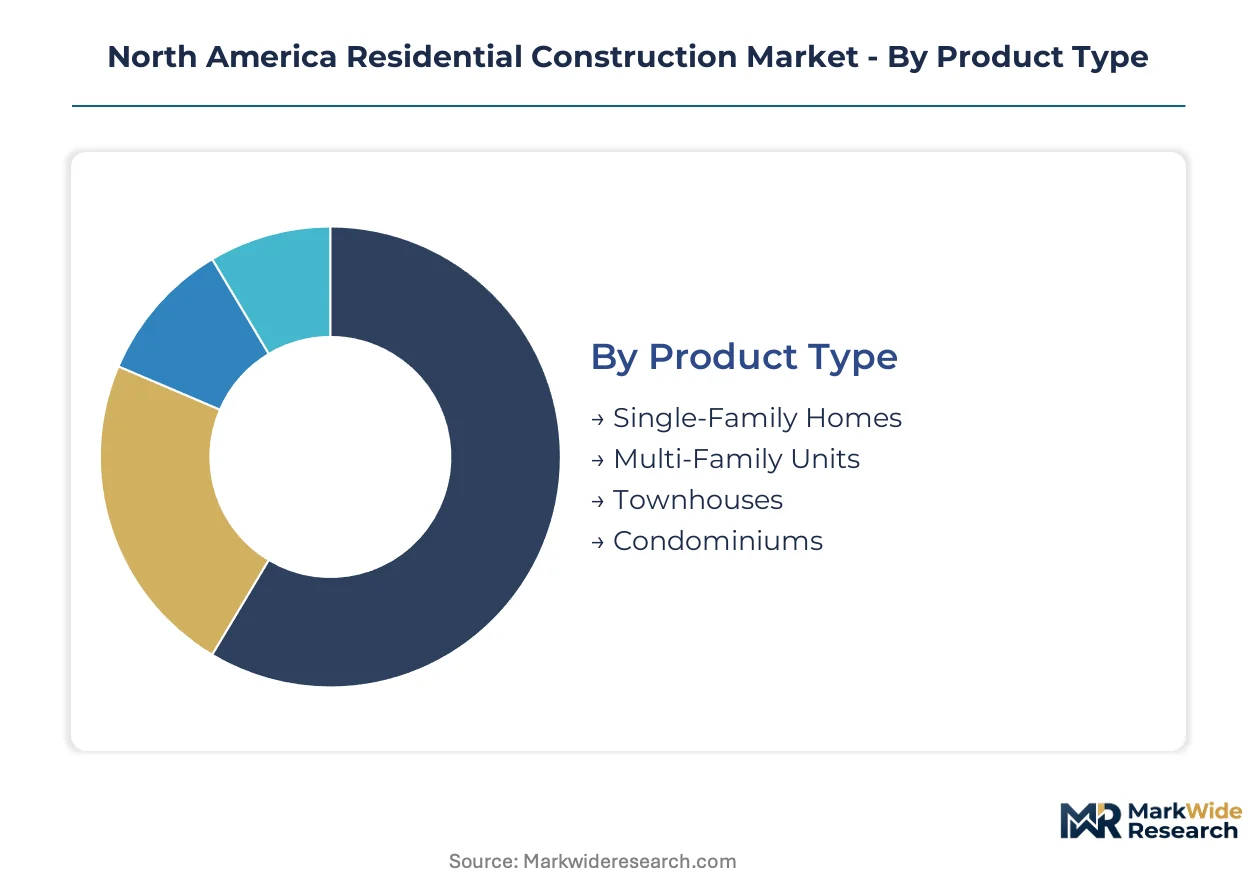
Segmentation reveals how capital deployment, regulatory exposure, and buyer economics fragment opportunity across the North America residential construction landscape. Builders and investors use these cuts to align project scale with financing structures and local entitlement timelines.
Product Type:
Capital intensity varies sharply across housing typologies, with land assembly and horizontal infrastructure demanding the heaviest upfront commitment.
- Single-Family Homes:Wood-framed detached structures on individually platted lots dominate ground-up starts across the United States and Canada. Sun Belt migration compresses development timelines in Dallas-Fort Worth and Phoenix, forcing accelerated entitlement processes.
- Multi-Family Units:Mid-rise and high-rise rental or condominium structures concentrate in transit-adjacent submarkets where Texas and Florida zoning reforms permit higher density. Cross-laminated timber is gaining code approval in Washington and Oregon, expanding material options beyond steel and concrete.
- Townhouses:Attached single-family units on fee-simple or common-interest lots balance density with ownership structures in supply-constrained coastal metros.
- Condominiums:Multi-unit buildings with divided ownership interests face extended certificate-of-occupancy timelines in jurisdictions with stringent warranty and reserve-funding statutes.
Single-Family Homes absorb the bulk of installed capacity; Multi-Family Units are expanding most quickly.
End User:
Financing sophistication and holding-period expectations shape how each buyer category engages with construction risk and regulatory compliance.
- First-Time Buyers:Entry-level purchasers depend on FHA and VA loan programs that impose property-condition standards, steering demand toward new construction that bypasses renovation-triggered EPA lead-safe rules.
- Real Estate Investors:Institutional and private capital deploys into build-to-rent single-family and multi-family assets, prioritizing markets with job growth and landlord-favorable eviction frameworks.
- Home Builders:Production and custom builders carry land-development risk and absorb compliance overhead from evolving energy codes and OSHA silica exposure mandates.
- Land Developers:Entitlement specialists secure zoning and infrastructure approvals before monetizing through vertical construction sales or joint ventures.
Home Builders command the deepest capital reserves; Real Estate Investors are scaling fastest through build-to-rent platforms.
Construction Material:
Material selection trades off structural performance, supply-chain exposure, and labor-skill availability across climate zones.
- Wood:Dimension lumber and engineered wood products frame the vast majority of single-family and low-rise multi-family construction. Canadian softwood lumber tariffs create margin volatility for U.S. builders dependent on cross-border supply chains.
- Steel:Cold-formed steel studs and structural steel framing serve mid-rise multi-family and wind-load-rated coastal construction where dimensional stability matters.
- Concrete:Cast-in-place and precast systems dominate high-rise structures and regions with seismic or hurricane design requirements, though OSHA silica rules elevate cutting and grinding compliance costs.
- Composite Materials:Fiber-cement siding, engineered decking, and insulated concrete forms address durability and thermal performance specifications in stringent code jurisdictions.
Wood commands the highest volume throughput; Composite Materials are climbing the fastest as code stringency hardens envelope requirements.
Service Type:
Contracting structure determines how risk, schedule certainty, and design accountability are allocated between project stakeholders.
- General Contracting:Traditional hard-bid arrangements separate design and construction responsibility, exposing owners to trade-stacking delays and change-order disputes.
- Subcontracting:Specialized electrical, plumbing, and HVAC trades operate under prime contractor direction, with journeyman licensing bottlenecks in California and New York compressing rough-in capacity.
- Design-Build:Single-source accountability consolidates architectural and construction services, accelerating schedules and reducing litigation exposure for developers seeking certificate-of-occupancy certainty.
- Renovation Services:Disturbance of pre-1978 housing triggers EPA Lead Renovation, Repair and Painting Rule certification requirements that disproportionately burden smaller contractors.
General Contracting still handles the largest project flow; Design-Build is gaining share fastest as developers prioritize schedule control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones across the United States are concentrating residential development capital in designated census tracts, accelerating ground-up construction in economically distressed areas with deferred capital-gains incentives.
United States
Sun Belt migration from California and New York is driving housing starts in Dallas-Fort Worth, Phoenix, and Austin. The EPA's Lead Renovation, Repair and Painting Rule imposes certification costs on pre-1978 renovation work, steering first-time buyers toward new construction. Houston's Energy Corridor submarket exemplifies this shift, with production builders absorbing compliance overhead through national scale.
Canada
Cross-border softwood lumber supply chains serve U.S. framing demand despite tariff exposure. British Columbia's National Building Code variant enforces seismic and thermal standards diverging from U.S. practice. Vancouver's constrained coastal submarket sees townhouse and condominium density rising as single-family land assembly costs escalate.
Mexico
Maquiladora corridor expansion near the U.S. border generates workforce housing demand in Tijuana and Ciudad Juárez. Mexico's federal mortgage agency INFONAVIT channels formal-sector payroll deductions into residential construction finance. Monterrey's industrial cluster anchors northern Mexico's highest per-capita housing starts as manufacturing investment concentrates.
North America Residential Construction Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. National production builders with land-banking capabilities and in-house mortgage operations hold scale advantages in Sun Belt volume markets. Three archetypes dominate: vertically integrated national operators, luxury-focused coastal specialists, and regional mid-market consolidators. Competitive moves center on design-build service expansion and utility incentive program capture to accelerate certificate-of-occupancy timelines.
Among publicly traded homebuilders, D.R. Horton exemplifies scale-driven national coverage across ninety-plus metro markets. Lennar Corporation anchors the integrated-services archetype through captive mortgage and title operations. Toll Brothers occupies the premium-tier position in supply-constrained coastal submarkets where entitlement complexity rewards specialized expertise.
| Leading Market Players |
|---|
| NVR |
| Taylor Morrison |
| D.R. Horton |
| Meritage Homes Corp. |
| KB Home |
| Lennar Corporation |
| Toll Brothers |
| Clayton Properties Group |
| PulteGroup |
| Others |
Value Chain & Pricing Dynamics
First-time buyer migration toward new construction to sidestep EPA lead-safe certification costs is compressing pricing power among renovation specialists and redirecting margin toward production builders with national scale. This demand shift forces supply chain reconfiguration around volume lumber procurement and just-in-time panelized delivery systems that penalize smaller contractors.
Pricing Analysis
Short-lead-time premiums dominate project economics as Sun Belt permit backlogs extend horizontal infrastructure timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy-code stringency and warranty bundling. Pricing pressure stems from Canadian softwood tariff exposure that feeds into framing lumber spot markets. First-time buyers exhibit highest price sensitivity, while luxury coastal purchasers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Journeyman electrician shortages in California and New York are extending rough-in schedules and compressing subcontractor capacity during peak construction seasons. Canadian sawmills, U.S. Pacific Northwest timberlands, and Southern yellow pine belt states anchor dimensional lumber supply. Cross-laminated timber feedstock, concrete admixtures, and copper wiring draw from specialized regional producers. Single-source vulnerability concentrates in Canadian softwood dependence for U.S. framing demand. Distribution runs through national production builders with captive logistics networks and regional lumberyard consolidators serving custom builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into mortgage origination and title services is becoming the decisive competitive lever as buyer acquisition costs concentrate on digital platforms. Players capturing downstream financial services margin offset construction-phase compression.
For Market Incumbents: Hedge against lumber futures volatility through long-term offtake agreements with British Columbia suppliers and backward integration into panelized wall fabrication. Cross-laminated timber certification investment defends position against steel and concrete substitution in mid-rise multi-family. Channel control through in-house mortgage operations locks buyer conversion before broker disintermediation accelerates. For New Entrants and Emerging Players: Modular bathroom pod specification technology offers a wedge into Florida and Georgia multi-family markets where trade stacking creates schedule vulnerability. Target accessory dwelling unit liberalization in California and Oregon where state preemption of local zoning opens incremental unit economics on existing lots. Go-to-market positioning centers on design-build single-source accountability that accelerates certificate-of-occupancy timelines. For Investors and Strategic Acquirers: The window for entry favors regional mid-market consolidators with land-banking capabilities in Dallas-Fort Worth and Phoenix entitlement pipelines. Long-term viability rests on capturing utility demand-response incentive programs that pull through smart panel and battery-ready wiring specifications. Monitor municipal zoning liberalization velocity as the inflection signal for deployable project density.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Service Expansion | Consolidated architectural and construction accountability reduces litigation exposure and accelerates Sun Belt entitlement timelines. |
| Cross-Laminated Timber Certification | Code approval for mid-rise structures in Washington and Oregon expands material options beyond steel and concrete. |
| Utility Incentive Program Capture | Pacific Gas & Electric and Southern California Edison rebates for smart panel wiring create specification pull-through. |
| Accessory Dwelling Unit Development | California and Oregon state law preemption of single-family zoning opens backyard cottage unit economics. |
| Panelized Wall System Integration | Off-site exterior envelope fabrication converges with just-in-time logistics to compress weather-dependent schedule risk. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with production builder land-acquisition executives, municipal planning officers, lumberyard procurement directors, and HVAC subcontractor trade associations combined with National Association of Home Builders energy code adoption tracking, EPA certification database records, and U.S. Census Bureau housing starts data. Bottom-up project pipeline enumeration and top-down macroeconomic indicator triangulation validated segment-level outputs.
Granularity-level modeling deployed product-type splits at the state level, construction-material sourcing at the provincial level for Canadian supply chains, and service-type differentiation at the metropolitan statistical area level. End-user segmentation captured financing-vehicle distinctions across FHA, VA, and conventional mortgage channels. CAGRs derived from housing start trajectory analysis cross-referenced with employment migration patterns and entitlement approval velocity. Cross-laminated timber code adoption timelines and utility incentive program expansion schedules fed industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including federal tariff rate renegotiation, seismic code amendments in British Columbia, and municipal infrastructure bond issuance capacity. Forecasts reflect assumptions around continued Sun Belt population migration and sustained lumber trade duty levels. Material deviation in interest rate policy, Canadian softwood supply disruption, or Title 24 energy code stringency escalation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
UK Residential Construction Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
US Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Saudi Arabia Manufactured Homes Market