
 Electric Submersible Pump Market | 2026-2036
Electric Submersible Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Submersible Pump Market Analysis
Buyer concentration among upstream oilfield service purchasers is rebalancing toward integrated procurement frameworks that bundle artificial lift with drilling and completion services. Schlumberger Ltd anchors its position through captive manufacturing of high-temperature motor systems for deep-well deployment. Baker Hughes differentiates via permanent magnet motor technology that extends run-life in corrosive reservoir conditions. Borets International Ltd competes aggressively on cost-optimized designs for Russian and Middle Eastern brownfield markets.
An electric submersible pump is a centrifugal pump assembly coupled to a hermetically sealed electric motor, designed to operate fully submerged in the pumped fluid at depths exceeding 3,000 meters with power ratings from 15 to 5,000 horsepower. The system converts electrical energy to hydraulic energy to lift reservoir fluids to surface facilities in oil production, mine dewatering, and municipal water applications. Multi-stage configurations dominate high-volume oil well pumping where staged impellers generate the pressure head required for deep reservoirs, while single-stage units occupy the shallow groundwater and drainage segments where simplicity and serviceability outweigh efficiency optimization. Variable Frequency Drive technology is displacing conventional fixed-speed controls across the oil and gas end user category, enabling operators to modulate pump curves in real time against declining reservoir pressure.
The US EPA regulates discharge limits from oilfield produced water that directly shape ESP specifications for wastewater treatment integration, while API 11S standard governs motor and seal chamber design for downhole reliability. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in cooling systems for surface variable speed drives, pushing manufacturers toward air-cooled alternatives. Saudi Arabia's national oil company mandates SAMS certification for all downhole electrical equipment entering its supply chain. Stakeholders must monitor how regional decarbonization timelines reshape power source requirements for remote wellpad installations.
Market Dynamics
Upstream operators are consolidating artificial lift procurement under integrated service contracts that bundle ESP systems with drilling and completion packages, compressing vendor margins while elevating qualification barriers for standalone pump manufacturers.
Growth Catalysts
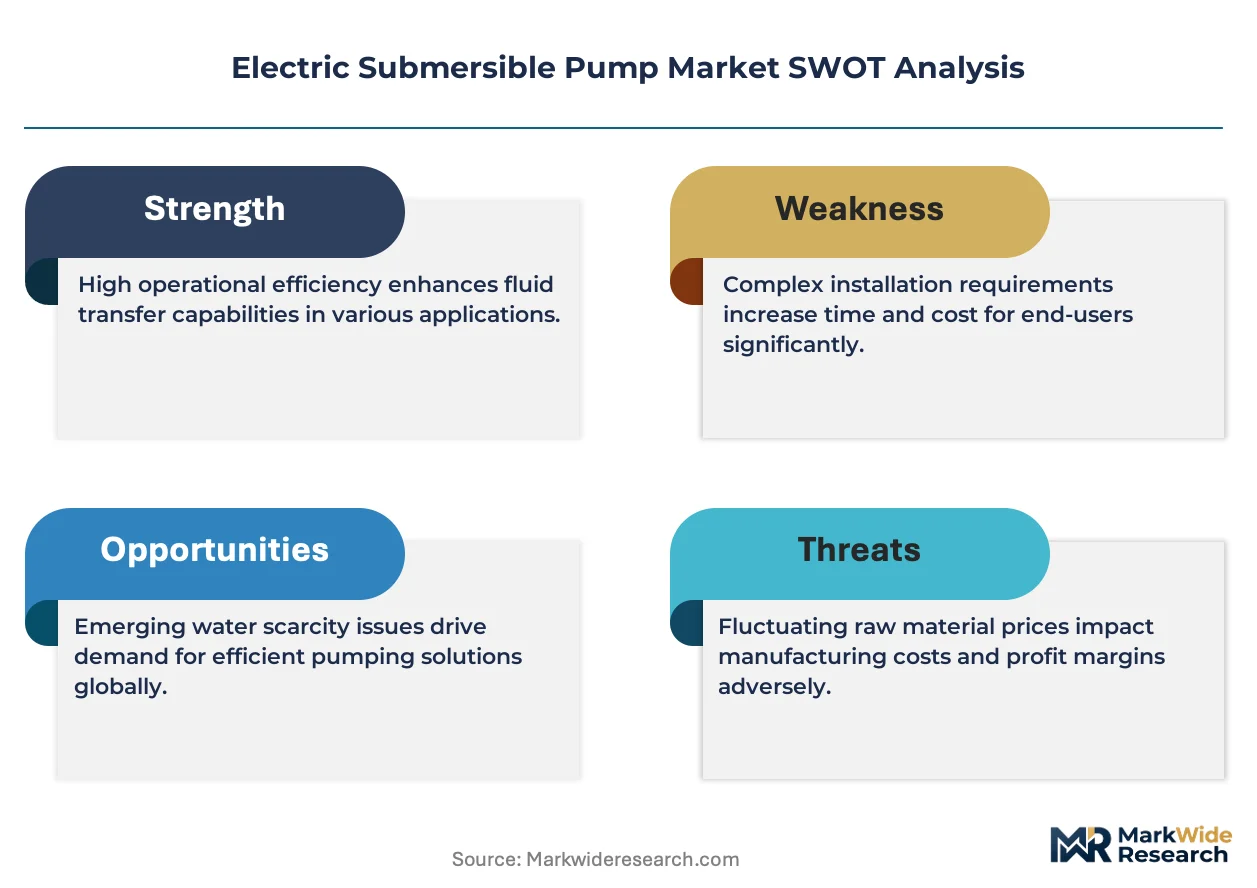
- Permian Basin unconventional development:Multi-stage ESP demand accelerates in Texas and New Mexico as producers target deeper laterals with higher drawdown requirements.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in surface variable speed drive cooling systems push adoption of air-cooled alternatives with lower leakage risk.
- SAMS certification mandate:Saudi Arabia's national oil company requires this downhole electrical equipment standard for all supply chain entrants, creating certified vendor scarcity that rewards early compliance investment.
Market Restraints
- Permanent magnet material cost volatility:Neodymium and dysprosium price swings squeeze motor manufacturers dependent on rare earth supply concentrated in Chinese processing facilities.
- Deep-well technical ceiling:Temperature degradation of elastomer seals above 200°C limits ESP deployment in ultra-deep geothermal and high-pressure reservoir applications.
- Vendor consolidation friction:Oilfield service majors integrating captive pump manufacturing are freezing out independent suppliers from integrated contract bidding pools.
Strategic Opportunities
- Geothermal energy expansion:Binary cycle power plants in Turkey and Kenya require high-temperature submersible pumps for brine extraction, opening non-oilfield demand channels.
- Carbon capture utilization and storage:CO2 injection wells for enhanced oil recovery and sequestration need corrosion-resistant ESP metallurgy that commands premium positioning.
- Digital twin integration:Real-time pump performance modeling combined with edge computing enables predictive maintenance contracts that extend beyond hardware margins.
Industry Challenges
- Downhole electronics reliability engineering:Shortage of specialists capable of designing hermetic motor lead extensions and potting compounds for high-pressure gas environments extends product development cycles.
- Legacy wellpad power infrastructure retrofit:Variable frequency drive installation requires grid stability upgrades and harmonic filtering that complicate deployment timelines in remote field locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Submersible Pump Market |
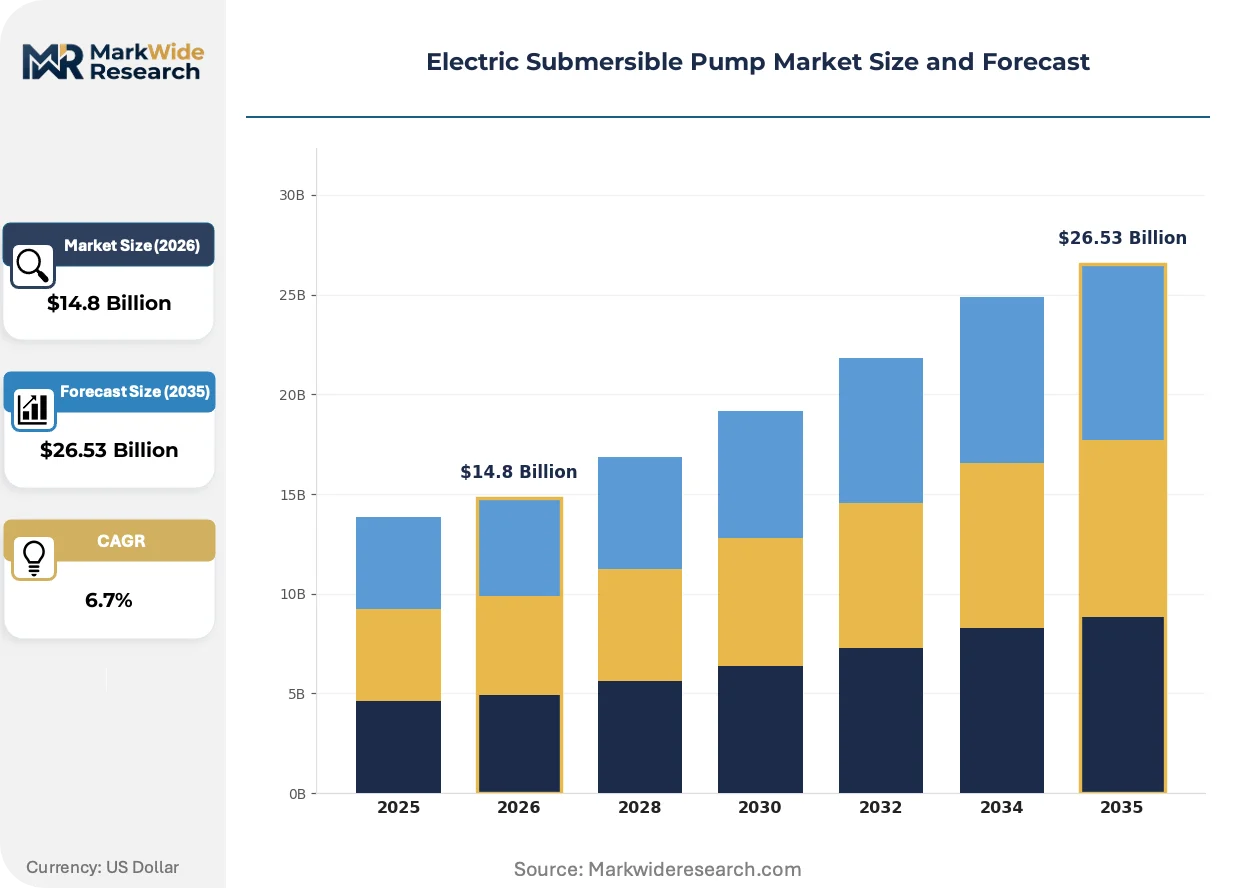
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Stage, Single-Stage, Borehole, Slurry End User: Oil & Gas, Agriculture, Wastewater Treatment, Industrial Technology: Submersible, Electrical, Hydraulic, Variable Frequency Drive Application: De-watering, Well Pumping, Drainage, Flood Control |
| Companies Covered | Schlumberger Ltd, Baker Hughes, Halliburton, Borets International Ltd, Novomet, Atlas Copco AB, Sulzer Ltd, Xylem Inc., Grundfos Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Submersible Pump Market Emerging Trajectories
Permanent magnet motor technology is absorbing capital allocation from conventional induction designs as operators prioritize run-life extension in corrosive reservoir conditions over upfront equipment cost minimization.
Permanent magnet synchronous motor technology is absorbing market share from traditional induction systems by eliminating rotor slip losses and enabling higher power density in slim-hole completions. Permian Basin operators deploying these systems in high-sand-cut environments report extended mean time between failures compared to conventional wound-rotor alternatives. The technology is absorbing service contract value toward integrated motor-protector-seal packages that reduce vendor count at the wellsite.
The EU F-Gas Regulation is tightening discharge quotas for hydrofluorocarbon refrigerants used in liquid-cooled variable speed drives, forcing manufacturers toward air-cooled or dielectric fluid alternatives. This transition elevates capital cost for surface electrical infrastructure but eliminates ongoing refrigerant compliance liability. Oil and gas operators in the North Sea and North African developments face accelerated retrofit timelines as 2024-2027 phase-down milestones approach.
Integrated procurement contracts are compressing the standalone ESP vendor population as oilfield service majors bundle artificial lift with drilling and completions packages. Independent pump manufacturers are responding by specializing in aftermarket refurbishment and rapid-deployment rental fleets for workover applications. This pattern concentrates most visible in the US onshore market where operator procurement desks have consolidated vendor panels under master service agreements.
Electric Submersible Pump Market Segmentation
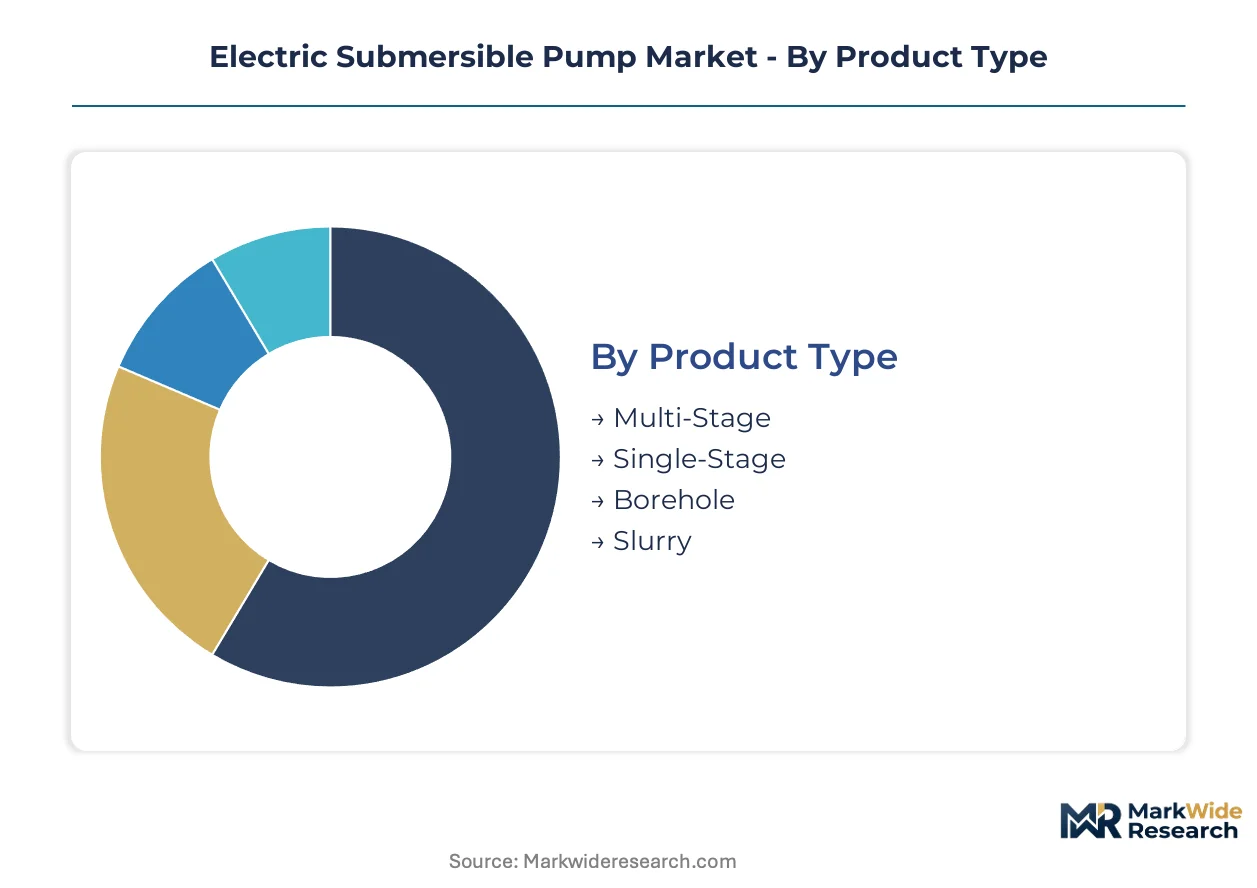
ESP procurement decisions split sharply between certified high-reliability systems for oilfield deployment and cost-optimized units for municipal and agricultural use. Certification requirements from Saudi Aramco's SAMS standard and API 11S specifications create tiered vendor eligibility that shapes competitive dynamics across each segment boundary.
Product Type:
SAMS certification mandates and API 11S motor specifications apply differentially across product architectures, with deep-well configurations facing the most stringent qualification burdens.
- Multi-Stage:Stacked impeller assemblies generate pressure heads exceeding 3,000 meters for deep reservoir extraction. Permian Basin operators in Texas and New Mexico deploy these systems in unconventional laterals where high drawdown requirements dominate procurement specifications.
- Single-Stage:Simplified centrifugal designs prioritize serviceability over peak efficiency in shallow groundwater and drainage applications. Agricultural users in India's Gujarat and Maharashtra states favor these units for borewell irrigation where capital constraints outweigh energy optimization.
- Borehole:Slim-diameter configurations fit narrow well casings for municipal water supply and monitoring applications.
- Slurry:Abrasion-resistant metallurgy handles solids-laden fluids in mining dewatering and tailings management.
Multi-Stage sits at the top of the volume ranking, with Borehole climbing the fastest.
End User:
Cost tiers separate oilfield purchasers willing to pay premium positioning for run-life guarantees from municipal buyers optimizing total cost of ownership over 15-year depreciation cycles.
- Oil & Gas:Upstream operators bundle artificial lift procurement with drilling and completion contracts, compressing standalone vendor margins. Saudi Arabia's national oil company enforces SAMS certification that freezes out uncertified suppliers from its supply chain.
- Wastewater Treatment:US EPA discharge limits for produced water and industrial effluent shape ESP specifications for solids handling and chemical resistance. Municipal utilities in Germany's Ruhr region prioritize energy efficiency certifications under EU procurement directives.
- Agriculture:Groundwater extraction for irrigation in India's Punjab and Haryana states drives demand for cost-optimized single-stage units.
- Industrial:Mine dewatering operations in Australia's Bowen Basin and Chile's Atacama require corrosion-resistant metallurgy for acidic drainage.
Oil & Gas commands the dominant revenue share, while Wastewater Treatment gains share fastest on regulatory tightening.
Technology:
Application maturity varies sharply, with Variable Frequency Drive penetration accelerating in oilfield settings while hydraulic systems retain share in hazardous environment deployments.
- Variable Frequency Drive:Real-time pump curve modulation against declining reservoir pressure eliminates throttling losses. Permian operators report 15-20% energy savings versus fixed-speed alternatives, though harmonic filtering requirements complicate remote wellpad retrofits.
- Submersible:Hermetically sealed motor-pump integration dominates deep-well oil production where surface drive accessibility is impractical.
- Electrical:Surface-mounted motor configurations persist in shallow dewatering and drainage where maintenance access outweighs efficiency gains.
- Hydraulic:Explosion-proof operation without electrical ignition risk maintains position in coal mine methane drainage and refinery sump applications.
Variable Frequency Drive leads technology investment, with Submersible maintaining the broadest installed base.
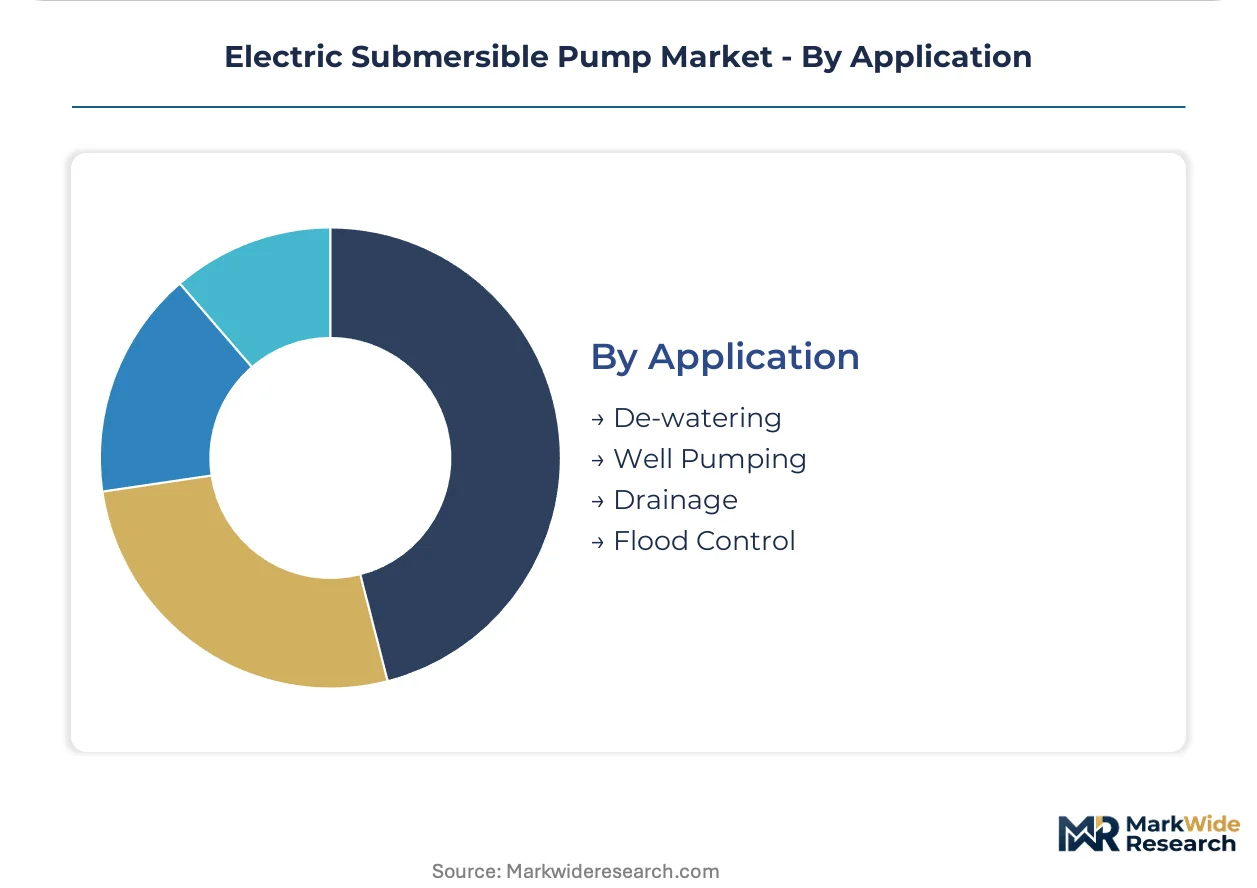
Application:
Volume concentration tracks geography, with well pumping anchored in petroleum provinces and dewatering fragmented across mining and construction sites globally.
- Well Pumping:Artificial lift for oil production and municipal water supply represents the core revenue pool. Multi-stage ESPs in Saudi Arabia's Ghawar field and US Permian Basin account for the highest unit value per installation.
- De-watering:Open-pit mining operations in Brazil's Carajás and Australia's Pilbara require high-volume, abrasion-resistant slurry handling. Seasonal construction activity in Southeast Asia drives rental fleet demand for temporary drainage.
- Drainage:Urban infrastructure and tunneling projects in Turkey's Anatolian region specify compact submersible units for continuous groundwater control.
- Flood Control:Emergency deployment specifications in the Netherlands' polder systems and Bangladesh's delta regions prioritize rapid mobilization over efficiency optimization.
Well Pumping dominates absolute volume, with De-watering expanding most quickly on mining capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin producers in Texas and New Mexico drive multi-stage ESP demand for unconventional wells, while Saudi Arabia's SAMS certification requirements reshape vendor eligibility across Middle Eastern supply chains.
United States
Permian Basin operators in Texas and New Mexico deploy multi-stage ESP systems in high-drawdown unconventional laterals. The EPA regulates discharge limits from oilfield produced water, forcing wastewater treatment integration into pump specifications. Houston anchors the largest concentration of artificial lift engineering and service contracting in North America.
Saudi Arabia
Saudi Aramco mandates SAMS certification for all downhole electrical equipment entering its supply chain, creating certified vendor scarcity. The national oil company's procurement consolidation rewards early compliance investment with exclusive contract access. The Eastern Province hosts the Ghawar field, where multi-stage ESPs command the highest unit value per installation globally.
Germany
Municipal utilities in the Ruhr region prioritize energy efficiency certifications under EU procurement directives for groundwater and drainage applications. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in cooling systems for surface variable speed drives. Industrial pump manufacturing clusters in North Rhine-Westphalia supply cost-optimized units for European brownfield markets.
China
Rare earth processing concentration in Chinese facilities shapes permanent magnet material cost volatility for motor manufacturers worldwide. The country's national standards body governs equipment certification for domestic oilfield deployment. Manufacturing capacity in the Yangtze River Delta produces cost-competitive pump assemblies for agricultural and industrial dewatering segments.
Brazil
Open-pit mining operations in the Carajás region require high-volume, abrasion-resistant slurry handling systems for dewatering applications. The national mining regulator enforces environmental compliance standards that shape pump metallurgy specifications. São Paulo state anchors the largest concentration of industrial pump distribution and aftermarket service infrastructure in Latin America.
Electric Submersible Pump Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Oilfield service majors integrating captive pump manufacturing are freezing out independent suppliers from integrated contract bidding pools. Three archetypes dominate: vertically integrated energy service conglomerates, specialized artificial lift pure-plays, and diversified industrial pump manufacturers. Consolidation through integrated service contracts and technology licensing partnerships represent the dominant competitive moves reshaping vendor access.
Within the energy service conglomerate tier, Schlumberger Ltd and Baker Hughes exemplify the vertically integrated model, while Borets International Ltd occupies a position among specialized pure-play competitors. Schlumberger anchors its market presence through captive manufacturing capabilities, Baker Hughes represents the technology-differentiated archetype, and Borets exemplifies cost-optimized positioning for regional brownfield markets. These three companies illustrate the strategic divergence between integrated service bundling and standalone equipment specialization.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Baker Hughes |
| Halliburton |
| Borets International Ltd |
| Novomet |
| Atlas Copco AB |
| Sulzer Ltd |
| Xylem Inc. |
| Grundfos Holding A/S |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between SAMS-compliant deep-well systems and uncertified shallow-water units manifests simultaneously in three-tier pricing stratification and geographically clustered supply configurations. Oilfield operators in Saudi Arabia pay premium positioning for certified motor-protector-seal packages while agricultural buyers in India source cost-optimized single-stage assemblies from Yangtze River Delta manufacturing clusters.
Pricing Analysis
Capacity additions in China's permanent magnet processing facilities are reshaping price floors for high-efficiency motor systems while squeezing margins on conventional induction designs. Three-tier pricing structure across premium SAMS-certified, standard API-compliant, and economy non-certified levels separates oilfield procurement from municipal and agricultural segments. Price differentiation hinges on metallurgy grade for corrosive reservoir conditions and after-sales service bundling for remote wellpad deployment. Cost compression in the economy tier intensifies because Chinese manufacturers are flooding agricultural segments with standardized borehole units. Municipal utilities in Germany's Ruhr region exhibit lowest price sensitivity due to EU procurement directive compliance requirements, while Indian groundwater extractors in Gujarat and Maharashtra face acute capital constraints.
Supply Chain Analysis
Regional distribution centers in Houston, Dammam, and Singapore anchor hub-and-spoke patterns for artificial lift equipment deployment to wellsite locations. Geographic supply concentration centers on China for rare earth magnet processing, Germany for precision metallurgy components, and the United States for high-temperature motor engineering. Raw material dependencies draw from neodymium and dysprosium feedstocks, specialty elastomer compounds for seal chambers, and corrosion-resistant superalloys for impeller casting. Single-source vulnerability in Chinese rare earth refining creates exposure to export restriction shocks. Distribution runs through integrated service contract channels that bundle ESP systems with drilling and completion packages, compressing standalone vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Submersible Pump Market functions as a regulatory compounder where EU F-Gas Regulation phase-down milestones and Saudi SAMS certification mandates are restructuring procurement specifications and vendor eligibility simultaneously.
For Market Incumbents: Anchor market position through captive manufacturing of high-temperature motor systems for deep-well deployment while accelerating air-cooled variable speed drive development ahead of refrigerant phase-down deadlines. Defensive consolidation moves require absorbing specialized seal engineering capabilities to eliminate vendor count at the wellsite and preempting independent suppliers from integrated contract bidding pools threatened by oilfield service majors. For New Entrants and Emerging Players: Municipal wastewater treatment operators in Germany's Ruhr region represent an underserved buyer archetype seeking energy efficiency certifications under EU procurement directives rather than oilfield reliability premiums. White-space targets include rapid-deployment rental fleets for Southeast Asian construction drainage and aftermarket refurbishment services for legacy Permian Basin installations. Go-to-market positioning should emphasize predictive maintenance contracts enabled by digital twin integration rather than hardware-only sales. For Investors and Strategic Acquirers: Consolidation pressure builds where integrated service contracts are freezing independent pump manufacturers from bidding pools and concentrating procurement under fewer vendor relationships. Long-term viability favors specialized artificial lift pure-plays with SAMS certification access and permanent magnet motor technology portfolios over diversified industrial pump manufacturers lacking oilfield service integration. Acquisition target archetypes include hermetic motor lead extension specialists and edge computing providers for pump performance modeling. Signal to monitor is Saudi Aramco procurement panel consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| SAMS Certification Investment | Unlocks exclusive contract access to Saudi Aramco's Ghawar field procurement. |
| Permanent Magnet Motor Scale-Up | Eliminates rotor slip losses for Permian Basin high-sand-cut environments. |
| Air-Cooled VSD Transition | Eliminates EU F-Gas Regulation refrigerant compliance liability for North Sea operators. |
| Digital Twin Platform Development | Enables predictive maintenance contracts extending beyond hardware margins. |
| Geothermal Brine Pump Specialization | Captures binary cycle power plant demand in Turkey and Kenya. |
Methodological Framework
Multiple input streams — primary interviews with artificial lift engineering directors and procurement managers at national oil companies, secondary validation through API standards documentation and EPA discharge limit filings, and customs data on permanent magnet material trade flows — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged maintenance directors at Permian Basin operators, aftermarket service heads at independent pump distributors, and plant engineers at variable speed drive manufacturing facilities. Secondary sources included SEC 10-K filings from energy service conglomerates, Saudi Aramco supplier qualification databases, and EU F-Gas Regulation implementation tracking. Bottom-up well count and artificial lift deployment rates were triangulated against top-down energy service revenue attribution.
Historical deployment patterns were cross-referenced against panel input from oilfield service procurement executives to establish baseline penetration assumptions across the projection horizon. Segmentation dimensions modeled include product architecture (multi-stage versus single-stage), end-user category (oil and gas versus wastewater treatment versus agriculture), and technology type (variable frequency drive versus fixed-speed). CAGRs were derived from regression analysis against crude oil price scenarios and unconventional well completion intensity. Industry-specific forecast inputs incorporated Permian Basin lateral length extension trends and EU refrigerant phase-down compliance timelines.
Inputs from Saudi Aramco procurement disclosures and EPA enforcement actions were available through the study window; gaps in real-time rare earth pricing transparency and independent vendor market share data introduce uncertainty bands around permanent magnet motor adoption trajectories. Forecasts reflect assumptions regarding certification mandate enforcement consistency and integrated contract bundling velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market