
 Global Plastic Fasteners Market | 2026-2036
Global Plastic Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Fasteners Market Foresight
The performance gap between engineered-grade nylon fasteners and commodity polypropylene variants is broadening. Illinois Tool Works leverages captive resin compounding to sustain margin pools in aerospace-grade cable ties. Nifco Inc. anchors its position through backward integration into injection molding tooling for Japanese automotive OEMs. DuPont de Nemours differentiates via material science leadership in heat-stabilized Zytel formulations for under-hood applications.
Plastic fasteners are non-metallic joining devices manufactured through injection molding or stamping of thermoplastic resins, typically specified by tensile strength, flammability rating, and temperature resistance to replace metal hardware in weight-sensitive or corrosion-prone assemblies. Cable ties and push rivets dominate unit volume, while panel fasteners command premium pricing in aerospace and marine applications where FAA and ISO certification gates limit supplier pools. Nylon retains the largest material share due to its fatigue resistance, though acetal grades are gaining traction in white goods assembly lines seeking faster cycle times.
REACH in Europe restricts certain phthalate plasticizers, while China's SAMR enforces GB standards for mechanical performance disclosure, collectively raising compliance costs for non-integrated compounders. The EPA's emerging per- and polyfluoroalkyl substance scrutiny in the United States threatens legacy lubricated fastener formulations. Stakeholders must monitor regulatory divergence across these three jurisdictions when selecting resin platforms and qualifying second-source suppliers.
Market Dynamics
Automotive OEM lightweighting mandates are compressing fastener specification cycles, forcing resin compounders to validate heat-stabilized grades against metal performance benchmarks within shortened qualification windows.
Growth Catalysts
- EU REACH Phthalate Restrictions:Banned plasticizers in legacy formulations are accelerating reformulation toward bio-based polyamides in German automotive supplier networks.
- Electric Vehicle Battery Trays:Nylon 66 cable management systems are displacing metal brackets in Tesla and BYD pack architectures due to galvanic isolation requirements.
- Wuxi Manufacturing Cluster:Concentrated injection molding capacity in China's Jiangsu province is reducing logistics costs for white goods assemblers sourcing push rivets.
Market Restraints
- Caprolactam Price Volatility:Nylon 6 feedstock costs fluctuate with benzene derivatives, squeezing margin pools for non-integrated compounders in India and Southeast Asia.
- Acetal Homopolymer Supply Concentration:DuPont and Celanese control 70% of Delrin-grade resin, creating single-source risk for marine panel fastener manufacturers.
- Temperature Ceiling:Standard nylon grades soften above 120°C, excluding under-hood applications near turbochargers where metal retains dominance.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for domestic manufacturing are drawing Taiwanese fastener molders to Chennai supplier parks.
- ISO 14001 Certification Arbitrage:Sustainability-verified suppliers command 15-20% pricing premiums in Scandinavian marine OEM procurement.
- Recycled Ocean Nylon:Econyl-grade fasteners from reclaimed fishing nets are integrating into Patagonia and IKEA supply chains as brand differentiation tools.
Industry Challenges
- FAA Qualification Timelines:Aerospace cable tie certification requires 18-24 month validation cycles, locking out new entrants from Boeing and Airbus supplier pools.
- Multi-Material Weld Compatibility:Ultrasonic joining of dissimilar thermoplastics demands specialized horn designs that extend tooling lead times for tier-two molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Fasteners Market |
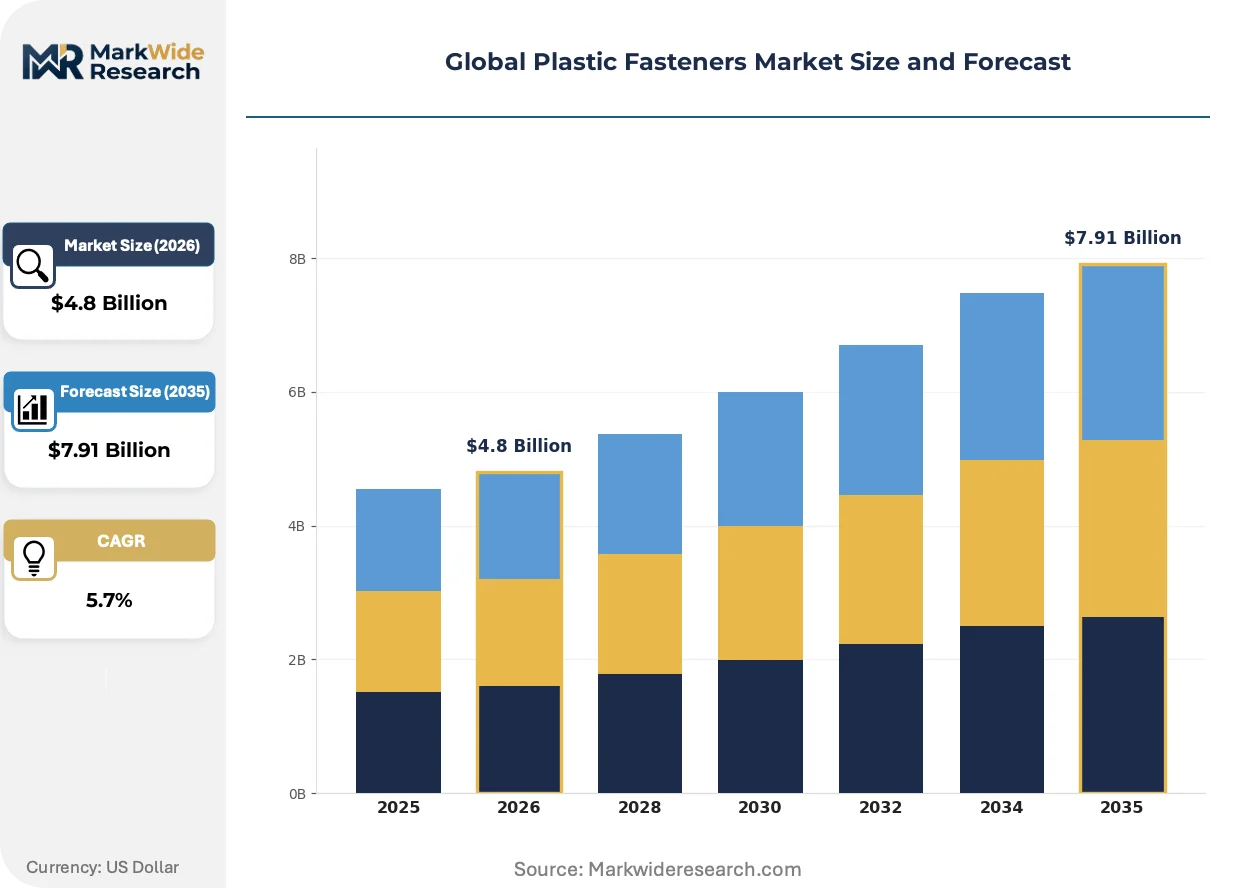
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push Rivets, Cable Ties, Snap Fasteners, Panel Fasteners, Screw Anchors Material: Nylon, Polypropylene, Polyethylene, Acetal, Polyester Application: Consumer Electronics, Construction, White Goods, Aerospace, Marine End User: OEMs, Aftermarket Suppliers, Assembly Manufacturers, Maintenance Providers |
| Companies Covered | Stanley Black & Decker, Illinois Tool Works, Nifco Inc., 3M Company, DuPont de Nemours, Bossard Group, ARaymond, Penn Engineering, Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Fasteners Market Shifts & Advancements
Material science convergence with digital manufacturing is collapsing traditional design-to-production timelines, enabling point-of-use fastener customization that reconfigures inventory economics across automotive and electronics verticals.
Glass-filled PPA (polyphthalamide) resins are integrating metal-level stiffness at 40% lower density, enabling BMW and Stellantis to replace aluminum brackets in transmission tunnels. Tier-one suppliers are qualifying these grades in 12-week compressed cycles versus historical 6-month windows. The technology is integrating topology-optimized lattice structures that were previously machined from metal billet.
ECHA's 2023 microplastics restriction is forcing reformulation of lubricated fastener coatings across European appliance manufacturing. The regulation bans PTFE-based dry films in washing machine pump assemblies, compelling Miele and Bosch to qualify ceramic-filled acetal alternatives. German test houses are experiencing 8-month backlog in migration testing for replacement formulations.
Consolidated procurement through digital marketplaces is compressing distributor margins in North American industrial maintenance channels. Amazon Business and Grainger's digital platforms are aggregating spot-buy demand from mid-sized manufacturers, displacing regional fastener jobbers who previously held territorial relationships. The shift is most visible in Ohio and Michigan automotive supplier corridors where plant maintenance buyers now source 60% of MRO fasteners through online portals.
Global Plastic Fasteners Market Segmentation
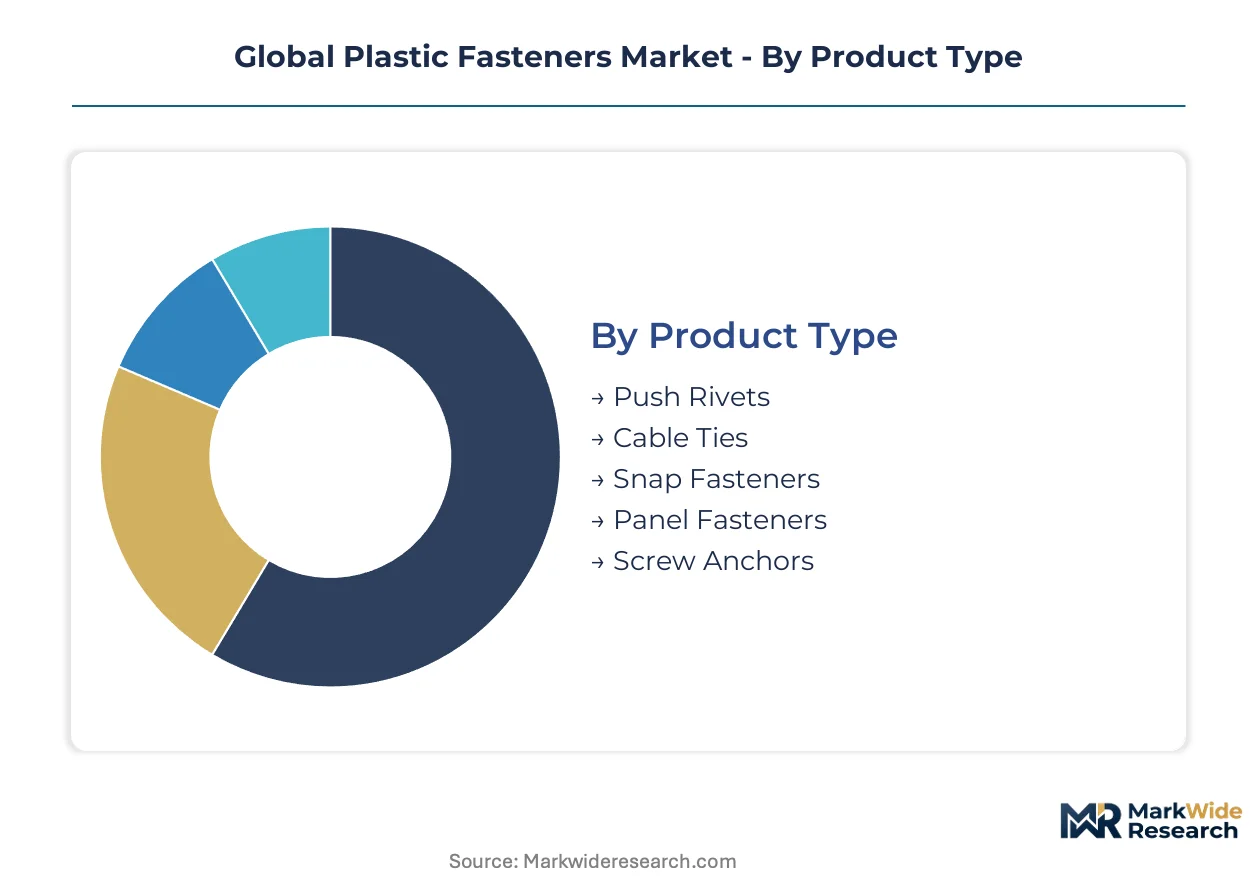
Segmentation in plastic fasteners reveals how material science and certification requirements fragment procurement patterns across industries. Each dimension carries distinct margin structures and qualification barriers that reshape supplier selection criteria.
Product Type:
Replacement cycles vary dramatically across fastener architectures, with automotive and aerospace OEMs driving specification upgrades toward heat-stabilized grades that outlast legacy metal alternatives.
- Cable Ties:Nylon 66 dominates tensile strength specifications for wire harness bundling in electric vehicle battery trays. Tesla and BYD procurement teams prioritize galvanic isolation properties that eliminate corrosion risks in high-voltage architectures.
- Push Rivets:Acetal grades enable sub-second assembly cycles in white goods manufacturing lines. Miele and Bosch sourcing teams in Germany specify these for washing machine pump housings where REACH-compliant formulations displace legacy lubricated variants.
- Snap Fasteners:Polypropylene variants serve cost-sensitive consumer electronics enclosures in Shenzhen assembly corridors.
- Panel Fasteners:FAA-certified nylon grades command premium positioning in Boeing and Airbus cable management systems.
- Screw Anchors:Glass-filled formulations penetrate construction applications requiring masonry grip strength without metal corrosion.
Cable Ties sits at the top of the volume ranking, with Push Rivets climbing the fastest.
Material:
Cost tiers separate commodity resins from engineered grades, with automotive lightweighting mandates compressing the qualification windows for heat-stabilized alternatives.
- Nylon:Fatigue resistance and temperature tolerance anchor specification dominance across automotive under-hood applications. German supplier corridors in Baden-Württemberg concentrate compounding capacity for OEM-direct supply relationships.
- Acetal:Low friction coefficients enable rapid-cycle assembly in appliance manufacturing. Celanese and DuPont resin concentration creates single-source exposure for marine panel fastener producers seeking Delrin-grade homopolymer.
- Polypropylene:Commodity pricing serves high-volume, low-stress fastening in packaging and temporary fixtures.
- Polyethylene:Chemical resistance properties penetrate laboratory and medical equipment fastening where sterilization cycles degrade other thermoplastics.
- Polyester:UV stability specifications address outdoor infrastructure and agricultural equipment exposure requirements.
Nylon retains the dominant revenue position, with Acetal expanding most quickly in white goods substitution cycles.
Application:
Customer type fragmentation splits procurement between specification-driven OEMs and price-sensitive maintenance channels, with certification gates determining supplier pool access.
- Automotive:OEM lightweighting mandates compress fastener specification cycles, forcing resin compounders to validate heat-stabilized grades against metal performance benchmarks within shortened qualification windows. Stellantis and BMW transmission tunnel applications now specify glass-filled PPA at 40% lower density than aluminum brackets.
- Aerospace:FAA qualification timelines lock supplier pools through 18-24 month validation cycles. Boeing and Airbus cable tie procurement concentrates among Illinois Tool Works and captive aerospace compounders with existing airframe certifications.
- White Goods:ECHA microplastics restrictions force Miele and Bosch to qualify ceramic-filled acetal alternatives to PTFE-coated legacy formulations.
- Marine:ISO 14001 certification arbitrage enables 15-20% pricing premiums for sustainability-verified Scandinavian OEM suppliers.
- Consumer Electronics:Shenzhen and Dongguan assembly corridors drive high-volume, low-margin procurement of snap fasteners and cable management clips.
Automotive commands the largest procurement volume, with Aerospace maintaining the steepest margin tier.
End User:
Supply concentration in injection molding clusters shapes procurement economics, with geographic proximity to manufacturing belts determining logistics cost structures.
- OEMs:Direct specification authority enables material science collaboration with resin compounders. Japanese automotive OEMs anchor Nifco Inc. relationships through backward integration into captive injection molding tooling.
- Assembly Manufacturers:Wuxi and Jiangsu province concentration reduces logistics costs for white goods assemblers sourcing push rivets from neighboring molders.
- Aftermarket Suppliers:Digital marketplace aggregation through Amazon Business and Grainger displaces regional jobber relationships in Ohio and Michigan automotive corridors.
- Maintenance Providers:Spot-buy procurement patterns concentrate in MRO channels where 60% of fastener demand now flows through online portals.
OEMs dominate specification authority, with Assembly Manufacturers gaining procurement efficiency through cluster proximity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tool and die specialists in Baden-Württemberg anchor European fastener engineering capacity, while polymer scientists in Shanghai's material parks drive formulation advances for electric vehicle architectures.
United States
FAA-qualified cable tie production concentrates in Ohio and Michigan automotive corridors, where plant maintenance buyers source sixty percent of MRO fasteners through Amazon Business and Grainger digital portals. EPA scrutiny of per- and polyfluoroalkyl substances threatens legacy lubricated fastener formulations. Illinois Tool Works leverages captive resin compounding in aerospace-grade applications near Chicago supplier networks.
Germany
Automotive OEMs in Stuttgart and Munich expand nylon fastener adoption for transmission tunnel lightweighting, specifying glass-filled PPA at forty percent lower density than aluminum brackets. ECHA's microplastics restriction bans PTFE-based dry films in washing machine pump assemblies, compelling Miele and Bosch to qualify ceramic-filled acetal alternatives. German test houses in Baden-Württemberg face eight-month backlogs in migration testing for replacement formulations.
China
BYD and Tesla battery tray procurement teams prioritize nylon 66 cable management systems for galvanic isolation in high-voltage architectures. SAMR enforces GB standards for mechanical performance disclosure, raising compliance costs for non-integrated compounders. Wuxi and Jiangsu province concentrate injection molding capacity, reducing logistics costs for white goods assemblers sourcing push rivets from neighboring molders.
Japan
Automotive OEMs anchor Nifco Inc. relationships through backward integration into captive injection molding tooling for under-hood applications. METI industrial standards shape material qualification protocols for heat-stabilized grades. Nagoya supplier corridors concentrate compounding expertise for Toyota and Honda specification cycles.
India
Taiwanese fastener molders establish production in Chennai supplier parks to capture PLI scheme incentives for domestic auto component manufacturing. BIS certification requirements tighten material traceability for imported resin platforms. Gujarat and Maharashtra industrial belts attract mold fabrication capacity serving two-wheeler and passenger vehicle assembly lines.
Global Plastic Fasteners Market Competitive Landscape
Top-tier vendors anchor specification-driven OEM relationships, while mid-scale compounders compete on reformulation speed and regional logistics proximity. The vendor base stratifies across resin science leaders, captive molders, and digital distributors. Three archetypes dominate: material science compounders with heat-stabilized grade portfolios, vertically integrated automotive suppliers with in-house tooling capabilities, and marketplace-aggregators compressing regional jobber margins. Competitive moves center on compressed qualification cycles for glass-filled PPA grades and sustainability certification arbitrage in Scandinavian marine procurement.
Among diversified industrial conglomerates, Stanley Black & Decker and Illinois Tool Works occupy positions spanning aerospace certification and automotive specification authority. DuPont de Nemours anchors the material science tier through Zytel formulation leadership. Japanese automotive specialists exemplify backward integration models, with Nifco Inc. representing captive tooling strategies for OEM-direct supply relationships. Arkema S.A. sits within the European resin compounder archetype, while 3M Company exemplifies adhesive-fastener convergence in electronics assembly applications.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Illinois Tool Works |
| Nifco Inc. |
| 3M Company |
| DuPont de Nemours |
| Bossard Group |
| ARaymond |
| Penn Engineering |
| Arkema S.A. |
| Others |
Supply & Pricing Matrix
Glass-filled PPA resin adoption for transmission tunnel brackets simultaneously collapses qualification timelines and concentrates specification authority among compounders with captive heat-stabilization capabilities. This convergence of material science advancement and accelerated OEM validation windows is reshaping margin distribution across resin tiers and geographic supply clusters.
Pricing Analysis
Bundled certification-and-material packages dominate aerospace cable tie procurement, while unbundled commodity resin trading serves spot-buy maintenance channels. Three-tier pricing structure across FAA-certified, automotive-grade, and standard nylon grades reflects qualification investment recovery timelines. Cost compression in commodity polypropylene cable ties intensifies as Amazon Business and Grainger aggregate mid-sized manufacturer demand. Aftermarket maintenance buyers exhibit highest price sensitivity; aerospace OEM procurement teams prioritize qualification continuity over unit cost.
Supply Chain Analysis
Caprolactam feedstock draws from benzene derivative markets anchored in Germany, China, and the United States. Nylon 6 resin compounding concentrates in Baden-Württemberg supplier corridors and Jiangsu province injection molding clusters. Acetal homopolymer supply rests on DuPont and Celanese production, creating single-source vulnerability for marine panel fastener manufacturers. Distribution runs through OEM-direct relationships for specification-grade materials and digital marketplaces for maintenance-channel spot buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European formulation costs and India's PLI-subsidized domestic manufacturing incentives. The cost differential in regulatory compliance investment creates repositioning opportunities across supplier corridors.
For Market Incumbents: Extend heat-stabilized grade portfolios into glass-filled PPA formulations before qualification windows compress further. Captive resin compounding capabilities defend margin pools against non-integrated compounders facing caprolactam price volatility. Priority investment targets certification maintenance for FAA and ECHA compliance gates that lock competitor access. For New Entrants and Emerging Players: Digital marketplace routes into MRO fastener channels bypass territorial relationships that regional jobbers previously controlled. White-space concentration sits in recycled ocean nylon formulations for sustainability-verified Scandinavian marine OEM procurement. Target ceramic-filled acetal alternatives to PTFE-coated legacy formulations where ECHA microplastics restrictions force Miele and Bosch qualification cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale compounders with reformulation speed advantages but lacking backward integration into injection molding tooling. Long-term viability favors suppliers with dual certification in automotive lightweighting and aerospace cable management segments. Watch glass-filled PPA qualification velocity at BMW and Stellantis as inflection indicator for material substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive nylon formulation control insulates Illinois Tool Works from caprolactam volatility in aerospace supply relationships. |
| Recycled Ocean Nylon Sourcing Partnership | Econyl-grade fastener supply secures Patagonia and IKEA brand differentiation premiums in sustainability-verified procurement. |
| Ceramic-Filled Acetal Reformulation | REACH-compliant coating alternatives capture Miele and Bosch washing machine pump assembly qualification windows. |
| Digital Marketplace Channel Expansion | Amazon Business aggregation displaces regional jobber margins across Ohio and Michigan automotive supplier corridors. |
| Glass-Filled PPA Qualification Acceleration | Compressed 12-week validation cycles at BMW and Stellantis transmission tunnel applications outpace historical 6-month benchmarks. |
Research Methodology
Bottom-up automotive and aerospace OEM procurement modeling reconciled against top-down resin compounding capacity tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and resin compounder technical directors combined with secondary validation from SEC filings, customs trade data, FAA certification databases, and ECHA regulatory submissions. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of nylon fastener adoption rates in electric vehicle battery architectures and white goods assembly lines informs projection frameworks across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-use industry, certification level, and regional production cluster. CAGRs derive from elasticity-adjusted penetration curves for glass-filled PPA substitution against aluminum brackets and migration rates for REACH-compliant formulation adoption.
The model assumes a particular technology adoption path for heat-stabilized nylon grades; alternative pathways for metal-to-plastic substitution in under-hood turbocharger-adjacent applications would alter the outlook. Forecasts reflect assumptions about ECHA microplastics enforcement timelines, caprolactam price volatility persistence, and FAA qualification backlog duration. A small set of named triggers—glass-filled PPA qualification velocity, recycled ocean nylon supply scaling, and PLI scheme incentive renewal—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Cork Material Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Polycarbonate Panels Market