
 Middle East Wireline Logging Services Market | 2026-2036
Middle East Wireline Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Wireline Logging Services Market Foresight
Advanced composite cable materials are consolidating around high-strength synthetic fibers that replace traditional steel-armored wireline in corrosive high-pressure wells. Schlumberger Limited leverages proprietary cable manufacturing to sustain tool reliability across Saudi Arabia's Ghawar field operations. Baker Hughes Company anchors its regional position through specialized high-temperature logging technology designed for Kuwait's deep Burgan reservoirs. Halliburton Company differentiates via integrated wellsite chemistry and wireline service bundling across UAE offshore concessions.
Middle East wireline logging services encompass the deployment of instrumented cables and downhole tools to acquire geophysical, geochemical, and mechanical data from boreholes, typically operating at depths exceeding 6,000 meters with temperature ratings above 175°C to characterize subsurface formations. These services enable real-time reservoir evaluation, completion design optimization, and production monitoring across carbonate and sandstone plays. Open hole logging retains the dominant share of service revenue as operators prioritize pre-completion formation evaluation in Saudi Arabia's mature super-giant fields. Cased hole services represent the fastest-expanding category, driven by Saudi Aramco's aggressive workover and infill drilling programs targeting bypassed pay zones. Electrical logging technology leads technology deployment, though nuclear logging maintains critical importance for porosity assessment in heterogeneous carbonate reservoirs where acoustic methods face interpretation challenges.
The Saudi Standards, Metrology and Quality Organization and the UAE's national oil regulatory frameworks mandate rigorous well integrity documentation and tool calibration protocols that elevate compliance costs for service providers. The SFDA in Saudi Arabia and MOHAP in the UAE enforce occupational safety standards that directly shape logging crew deployment requirements and equipment certification cycles across the region. Stakeholders must monitor how Saudi Arabia's localization mandates and the UAE's in-country value requirements reshape procurement criteria for wireline contracts.
Market Dynamics
Saudi Aramco's aggressive sour gas and unconventional development programs are concentrating demand for high-temperature wireline tools above 200°C ratings, forcing service providers to accelerate digital platform upgrades across mature carbonate basins.
Growth Catalysts
- SFDA Well Integrity Mandates:Saudi Arabia's occupational safety frameworks mandate enhanced tool calibration cycles, elevating recurring service revenue for compliant wireline operators.
- Kuwait Burgan Deep Reservoirs:Kuwait Oil Company's push into formations below 5,000 meters concentrates demand for specialized high-pressure logging strings.
- Composite Cable Substitution:Synthetic fiber armored wireline is displacing steel in corrosive high-CO2 wells, extending operational lifespan across UAE sour gas fields.
Market Restraints
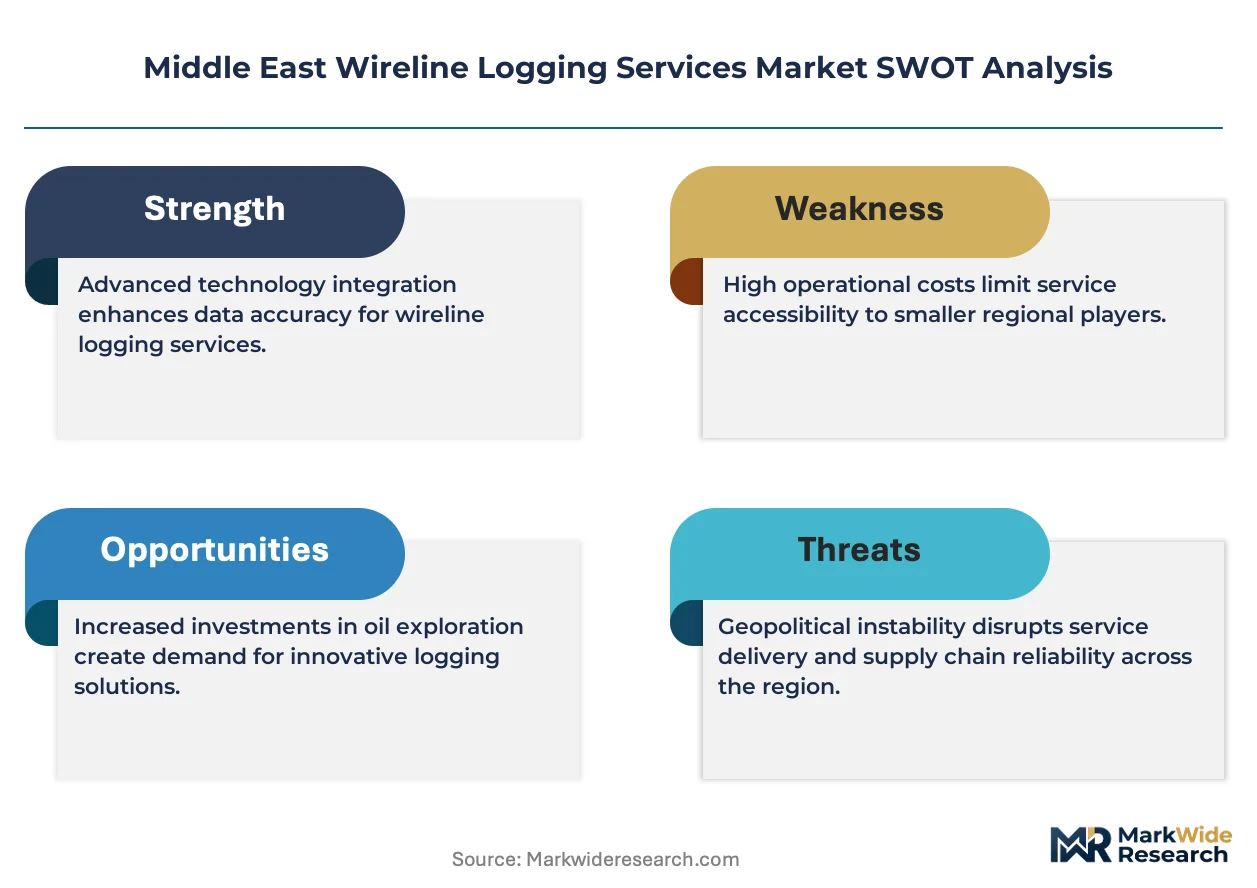
- Steel Alloy Supply Concentration:Specialty high-tensile cable manufacturing concentrates among three Asian metallurgical suppliers, creating input vulnerability for regional tool fabricators.
- Tool Certification Friction:MOHAP calibration protocols in the UAE impose 90-day recertification cycles that compress equipment utilization rates.
- Acoustic Logging Limitations:Heterogeneous carbonate porosity in Saudi Arabia's Ghawar field forces reliance on nuclear logging methods with higher operational complexity and regulatory scrutiny.
Strategic Opportunities
- Oman Underexplored Basins:Petroleum Development Oman's tight gas concessions remain underpenetrated for modern formation evaluation, creating first-mover positioning for integrated logging-chemistry service bundles.
- Real-Time Data Convergence:Integration of wireline telemetry with AI-driven formation interpretation is compressing decision cycles from days to hours during drilling operations.
- Abu Dhabi ICV Procurement:ADNOC's in-country value requirements are reshaping contract award criteria toward localized joint ventures and technology transfer commitments.
Industry Challenges
- High-Temperature Electronics Talent Gap:Specialized downhole instrumentation engineering expertise remains scarce across Middle Eastern technical universities, forcing reliance on expatriate specialists.
- Digital Platform Integration Complexity:Legacy mechanical logging units require capital-intensive retrofitting to interface with cloud-based data acquisition systems demanded by national oil company digitalization roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Wireline Logging Services Market |
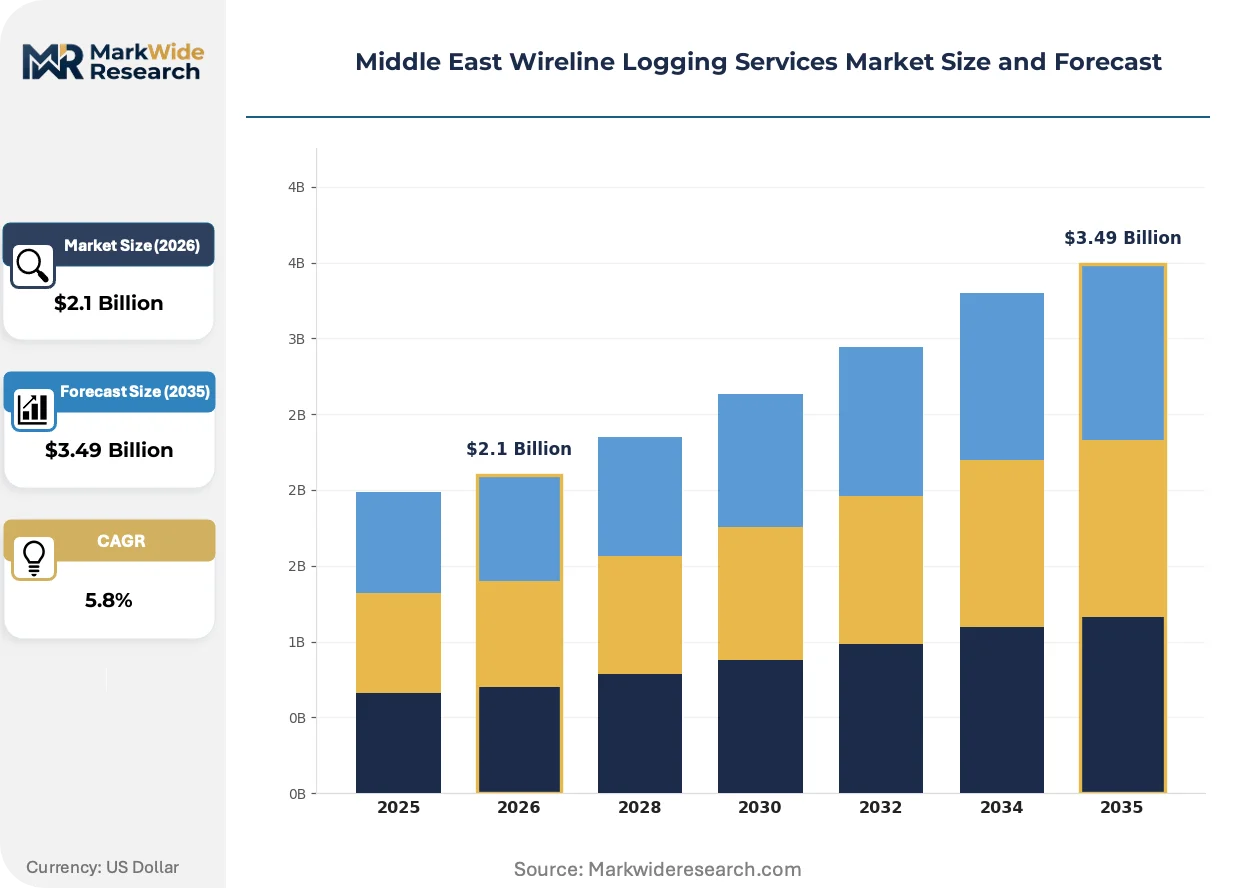
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Open Hole, Cased Hole, Formation Evaluation, Wireline Coring Technology: Electrical Logging, Nuclear Logging, Acoustic Logging, Microseismic Application: Oil Production, Gas Exploration, Water Well Monitoring, Environmental Assessment End User: Oil & Gas Companies, Mining Firms, Environmental Agencies, Research Institutions |
| Companies Covered | Weatherford International plc, Superior Energy Services, Schlumberger Limited, Petrofac Limited, Nabors Industries Ltd, Halliburton Company, Expro International Group Ltd, National Energy Services Reunited Corp, Baker Hughes Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Wireline Logging Services Market Shifts & Advancements
Wireline logging across the Middle East is undergoing fundamental instrumentation evolution as national oil companies demand reservoir characterization precision that matches their enhanced oil recovery ambitions.
Advanced distributed fiber optic sensing is unifying acoustic, temperature, and strain measurement into single-cable deployments. Saudi Aramco's unconventional gas pilots are adopting these systems at accelerated procurement cycles. The technology is unifying previously separate logging runs, compressing rig time and reducing mechanical failure points in extended-reach laterals.
MOHAP and SFDA are tightening occupational exposure limits for radioactive logging sources, forcing nuclear porosity tool operators to adopt shielding innovations and alternative chemical tracers. Service providers are responding with tungsten-collimated detector housings and reduced-source-strength configurations that maintain measurement precision while satisfying regulatory dose-rate thresholds.
Integrated service contracting is displacing discrete tool rentals across UAE offshore concessions. ADNOC's bundled procurement models combine wireline logging with wellsite chemistry and completion fluids under single-vendor accountability. This concentration is most visible in Upper Zakum development, where integrated contracts now dominate awards above 50 million dollars.
Middle East Wireline Logging Services Market Segmentation
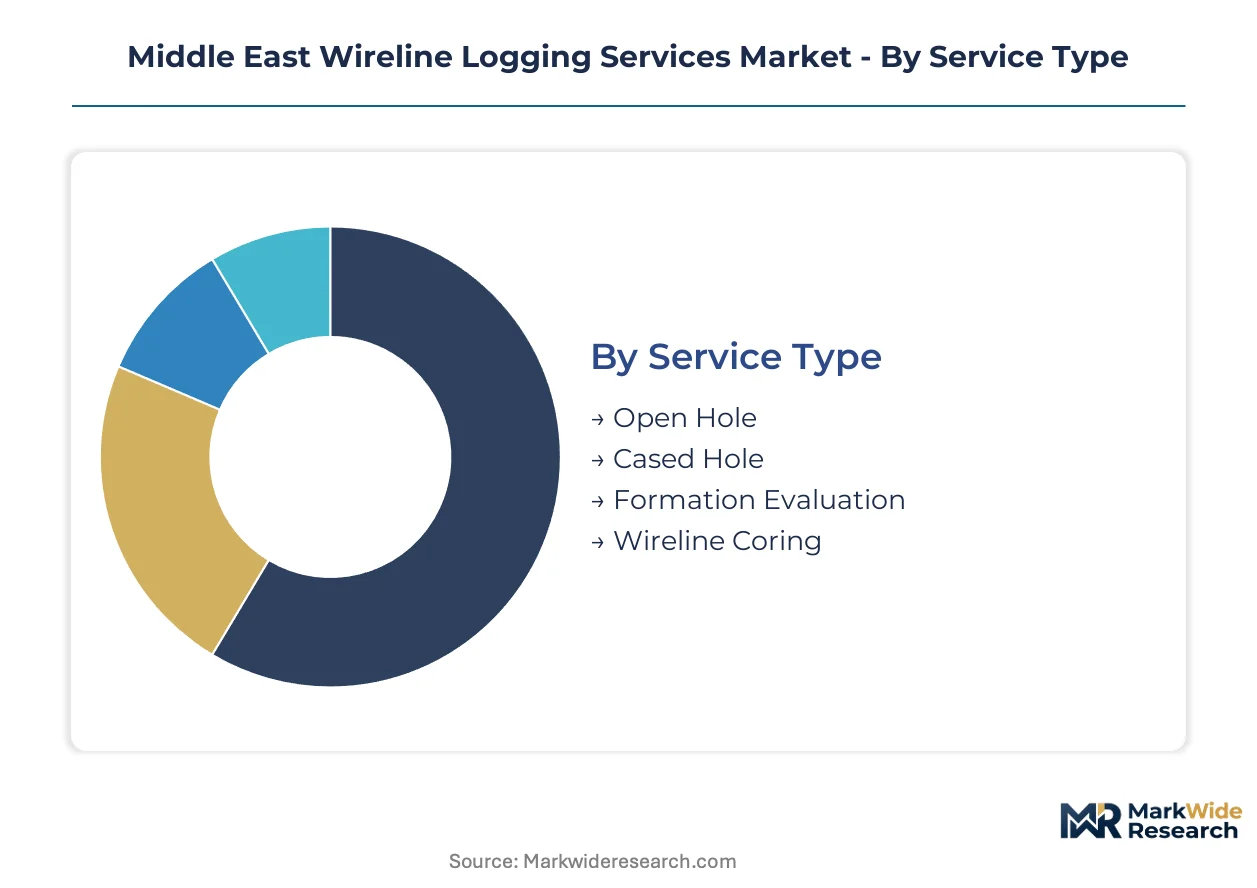
Wireline logging procurement across the Middle East fragments across four distinct dimensions that shape equipment specification, crew certification requirements, and contract tenure. Understanding how national oil companies prioritize service categories illuminates where technology investments concentrate and where margin compression risks emerge.
Service Type:
Upgrade cycles for digital wireline platforms are accelerating as Saudi Aramco and ADNOC mandate real-time data transmission capabilities across all service categories.
- Open Hole:Pre-completion formation evaluation services deploy instrumented cables to acquire resistivity, porosity, and lithology data in uncased boreholes. Demand concentrates in Saudi Arabia's Ghawar and Safaniya fields where infill drilling programs require precise reservoir characterization before casing installation.
- Cased Hole:Post-completion logging through production casing enables saturation monitoring, cement evaluation, and corrosion assessment. This category is expanding most quickly across Kuwait's Burgan field workover campaigns and UAE sour gas well integrity programs where mechanical failures in mature wells drive recurring intervention demand.
- Formation Evaluation:Integrated petrophysical analysis combining multiple logging measurements into unified reservoir models. ADNOC's Upper Zakum development awards favor bundled formation evaluation contracts above 50 million dollars.
- Wireline Coring:Retrieval of physical rock samples from specific depths for laboratory analysis. Petroleum Development Oman deploys coring services selectively in tight gas appraisal wells where core-calibrated permeability data reduces uncertainty.
Volume placements concentrate in Open Hole services; the faster expansion belongs to Cased Hole as workover intensity rises across mature carbonate basins.
Technology:
Technology selection hinges on temperature tolerance and regulatory compliance rather than pure measurement precision, with high-CO2 wells forcing material substitutions.
- Electrical Logging:Resistivity and spontaneous potential measurements using electrode arrays conveyed on conductive wireline. This technology dominates Saudi Aramco's unconventional gas pilots where deep resistivity mapping guides fracture staging decisions.
- Nuclear Logging:Gamma-ray and neutron porosity measurements employing sealed radioactive sources. SFDA and MOHAP dose-rate regulations are tightening operational protocols, extending rig time and elevating shielding costs across UAE sour gas fields.
- Acoustic Logging:Sonic velocity and cement bond evaluation using piezoelectric transmitters and receivers. Heterogeneous carbonate porosity in Ghawar limits acoustic porosity accuracy, forcing operator reliance on nuclear alternatives.
- Microseismic:Downhole monitoring of induced seismicity during hydraulic fracturing operations. Kuwait Oil Company pilots microseismic arrays in deep Burgan tight gas formations to optimize fracture geometry.
Electrical Logging commands the largest deployment base; Microseismic is gaining share fastest as unconventional development expands beyond Saudi Arabia into Oman and Kuwait.
Application:
Application mix reflects the Middle East's hydrocarbon endowment, with gas exploration commanding premium tool specifications and water well monitoring requiring simplified economics.
- Oil Production:Reservoir monitoring and saturation tracking in mature oilfields. Saudi Aramco's maximum recovery programs sustain continuous open hole and cased hole demand across Ghawar, Khurais, and Shaybah.
- Gas Exploration:Formation evaluation in high-temperature, high-pressure gas-bearing intervals. Abu Dhabi's sour gas expansion and Saudi Arabia's unconventional Jafurah development concentrate demand for 200°C-rated logging strings.
- Water Well Monitoring:Aquifer characterization and salinity profiling for groundwater management. UAE municipal water authorities deploy simplified logging suites in shallow coastal aquifers.
- Environmental Assessment:Borehole logging for contaminated site characterization and carbon storage verification. Emerging demand centers on ADNOC's carbon capture project sites requiring cement integrity confirmation.
Oil Production absorbs the highest service volume; Gas Exploration is climbing the fastest as national oil companies diversify toward sour and unconventional gas resources.
End User:
End user procurement behavior diverges sharply, with national oil companies driving technology roadmaps and environmental agencies imposing distinct compliance frameworks.
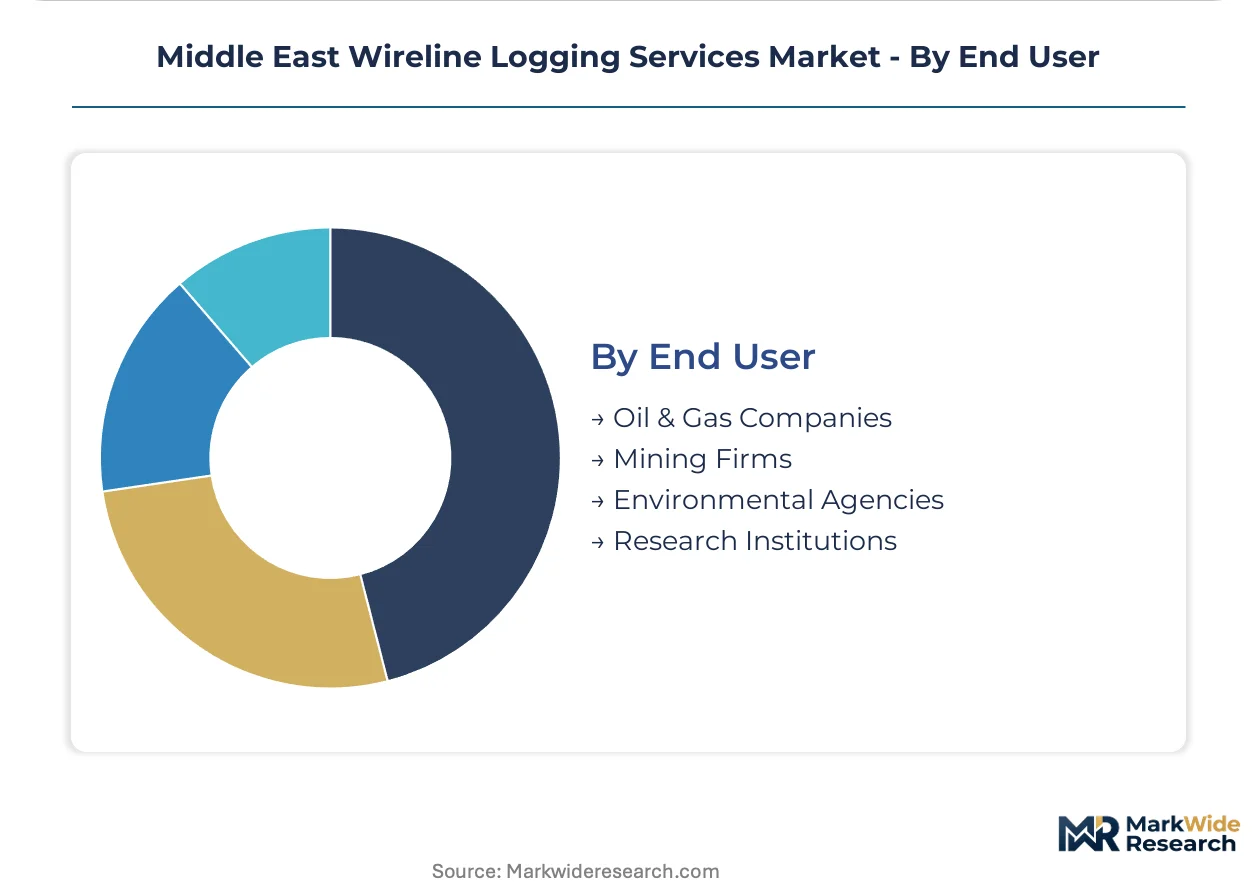
- Oil & Gas Companies:Integrated operators and national oil companies commanding multi-year service contracts. Saudi Aramco, ADNOC, and Kuwait Oil Company collectively shape regional logging technology standards through bundled procurement.
- Mining Firms:Mineral exploration operators requiring slim-hole logging in hard-rock environments. Limited penetration in the Middle East outside Saudi Arabia's bauxite and phosphate exploration programs.
- Environmental Agencies:Regulatory bodies mandating logging for groundwater protection and contamination assessment. UAE's Environment Agency Abu Dhabi specifies logging protocols for coastal aquifer monitoring.
- Research Institutions:Universities and geological surveys acquiring logging data for academic publication and basin modeling. King Abdullah University of Science and Technology maintains proprietary logging databases for carbonate reservoir research.
Contract value concentrates with Oil & Gas Companies; Research Institutions are expanding procurement most rapidly as national oil companies fund collaborative digital reservoir initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireline logging demand concentrates in the Gulf Cooperation Council states, where national oil companies drive technology roadmaps through bundled procurement and localization mandates. Saudi Arabia, Kuwait, and the UAE collectively shape regional service specifications, while Oman and Qatar emerge as secondary growth vectors for tight gas and offshore exploration.
Saudi Arabia
Saudi Aramco's unconventional gas development at Jafurah and sour gas expansion programs concentrate demand for 200°C-rated logging tools. SFDA well integrity mandates enforce 90-day recertification cycles that elevate compliance costs for service providers. The Eastern Province hosts the Ghawar and Safaniya super-giant fields where infill drilling sustains continuous open hole logging demand.
United Arab Emirates
ADNOC's sour gas expansion at Shah and Bab fields drives procurement of high-temperature composite cable systems. MOHAP calibration protocols impose stringent radioactive source handling requirements that extend rig time for nuclear porosity operations. Abu Dhabi's Upper Zakum offshore development favors integrated logging-chemistry contracts above fifty million dollars.
Kuwait
Kuwait Oil Company's deep Burgan reservoir workovers concentrate demand for specialized high-pressure logging strings rated beyond 5,000 meters. The country's national oil regulatory framework mandates enhanced tool calibration documentation for mature field interventions. Burgan field operations anchor regional cased hole service expansion as workover intensity rises.
Oman
Petroleum Development Oman's tight gas concessions in underexplored basins create first-mover positioning for modern formation evaluation bundles. The sultanate's localization policies require joint venture structures for service contracts above defined thresholds. Central Oman tight gas pilots adopt microseismic logging arrays to optimize fracture geometry in deep carbonate formations.
Qatar
QatarEnergy's North Field expansion sustains demand for high-specification logging tools in high-pressure offshore environments. The country's regulatory framework emphasizes well integrity documentation for sour gas production systems. Ras Laffan industrial city clusters service provider technical support facilities for offshore concession logistics.
Middle East Wireline Logging Services Market Competitive Landscape
Integrated service bundling dominates the current landscape as national oil companies consolidate procurement accountability under single-vendor frameworks. The market structures around three tiers: international oilfield service conglomerates with full technology portfolios, regional specialists with niche high-temperature capabilities, and emerging local joint ventures satisfying in-country value requirements. Strategic archetypes include technology licensors leveraging proprietary cable manufacturing, chemistry-integrated service providers, and digital platform specialists. Portfolio diversification and localization partnerships represent the dominant competitive vectors as ADNOC and Saudi Aramco rewrite contract award criteria.
Within the integrated conglomerate tier, Schlumberger Limited, Baker Hughes Company, and Halliburton Company exemplify divergent regional positioning strategies. Schlumberger occupies a position anchored by proprietary cable manufacturing capabilities sustaining reliability across Saudi Arabia's Ghawar field operations. Baker Hughes exemplifies the high-temperature specialization archetype through focused technology deployment in Kuwait's deep Burgan reservoirs. Halliburton represents the bundled service model combining wireline logging with wellsite chemistry across UAE offshore concessions. These three entities collectively shape national oil company technology roadmaps through multi-year framework agreements.
| Leading Market Players |
|---|
| Weatherford International plc |
| Superior Energy Services |
| Schlumberger Limited |
| Petrofac Limited |
| Nabors Industries Ltd |
| Halliburton Company |
| Expro International Group Ltd |
| National Energy Services Reunited Corp |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
National oil company bundled procurement across Saudi Arabia, Kuwait, and the UAE anchors contract structures around long-term framework agreements with embedded service tiers. This buyer concentration compresses spot-market pricing leverage while elevating compliance premiums for vendors meeting SFDA and MOHAP certification requirements.
Pricing Analysis
Volume placements in open hole logging generate thinner margins than cased hole and formation evaluation bundles where technical complexity commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates ADNOC's integrated contracts above fifty million dollars from discrete tool rentals in shallow water well monitoring. Pricing pressure stems from Kuwait Oil Company's aggressive localization mandates forcing joint venture cost absorption. International oilfield service conglomerates exhibit lowest price sensitivity due to proprietary cable manufacturing; emerging local joint ventures face acute margin compression during qualification phases.
Supply Chain Analysis
SFDA tool calibration protocols and MOHAP radioactive source handling certifications gate supplier eligibility before commercial engagement, creating eighteen-month qualification timelines for new entrants. High-tensile cable manufacturing concentrates in Japan, South Korea, and Germany, drawing from specialty steel alloy and synthetic fiber feedstocks. Single-source vulnerability runs through Asian metallurgical suppliers for armored wireline components. Distribution runs through national oil company framework agreements with Schlumberger, Baker Hughes, and Halliburton rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SFDA's ninety-day recertification cycles and MOHAP's dose-rate regulations erect barrier-to-entry moats favoring incumbents with established calibration infrastructure and shielding technology investments.
For Market Incumbents: Deepen proprietary cable manufacturing capabilities to defend against composite fiber substitution threats from Asian suppliers. Expand high-temperature electronics talent pipelines through King Abdullah University of Science and Technology partnerships to offset expatriate specialist scarcity. Prioritize ADNOC in-country value joint venture structures to secure Upper Zakum integrated contract renewals. For New Entrants and Emerging Players: Distributed fiber optic sensing unifying acoustic, temperature, and strain measurement offers technology-first positioning against legacy mechanical logging units. Petroleum Development Oman's tight gas concessions present the most penetrable white space given underexplored basin status and microseismic logging array demand. Pursue Oman localization joint venture thresholds to bypass direct competition with established framework holders. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with niche high-temperature capabilities and existing MOHAP certification infrastructure in Abu Dhabi. Long-term viability centers on vendors capable of bridging legacy mechanical units to cloud-based data acquisition systems demanded by national oil company digitalization roadmaps. Watch for ADNOC procurement criterion shifts toward technology transfer commitments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Cable Manufacturing Scale-Up | Synthetic fiber armored wireline displaces steel in UAE sour gas corrosive environments. |
| High-Temperature Electronics Talent Pipeline | King Abdullah University of Science and Technology partnerships address expatriate specialist scarcity. |
| ADNOC In-Country Value Joint Venture | Localized structures satisfy procurement criteria reshaping Upper Zakum contract awards. |
| Digital Platform Retrofit Program | Legacy mechanical unit upgrades interface with cloud-based data acquisition roadmaps. |
| Shielding Technology Certification Investment | Tungsten-collimated detector housings satisfy MOHAP dose-rate thresholds for nuclear logging. |
Research Methodology
Trade publications, national oil company procurement disclosures, and regulatory filings from SFDA and MOHAP formed the secondary backbone for market sizing and technology trend identification. Primary interviews with wireline logging operations managers, petroleum engineering directors at Saudi Aramco and ADNOC, and technical procurement leads at Kuwait Oil Company validated secondary assumptions. Bottom-up segment sizing across service type, technology, application, and end user combined with top-down national oil company capital expenditure triangulation.
Historical trendline analysis of wireline logging contract awards and equipment deployment rates established baseline growth patterns across the analysis window. The forecast framework modeled service type segmentation, technology temperature rating tiers, and national oil company localization policy intensity. CAGRs derived from weighted average of operator drilling program announcements and regulatory mandate implementation timelines. Industry-specific inputs included Saudi Aramco's Jafurah unconventional gas pilot acceleration and ADNOC's Shah sour gas expansion procurement cycles.
Several conditions sit outside the modeled scope, including sudden commodity price collapses triggering drilling program suspensions, geopolitical disruptions to specialty steel alloy supply chains, and unanticipated regulatory harmonization across Gulf Cooperation Council states. Forecasts reflect assumptions regarding sustained national oil company capital commitment to mature field recovery and unconventional gas development. A model refresh is warranted upon material change in SFDA or MOHAP calibration protocol stringency or ADNOC in-country value procurement weighting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
CO2 EOR Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Well Cementing Market
Oil & Gas
Injection Well Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Oman Directional Drilling Market