
 Perforating Gun Market | 2026-2036
Perforating Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Perforating Gun Market Intelligence
The skilled explosives technician labor pool is collapsing across North American oilfield service basins, constraining deployment capacity for complex multi-stage perforating operations. Hunting PLC leverages its vertically integrated shaped charge manufacturing to sustain supply chain reliability amid workforce shortages. Baker Hughes Company anchors its position through proprietary wireless firing systems that reduce crew size requirements on location. DynaEnergetics differentiates via precision-engineered charges optimized for extended-reach laterals.
A perforating gun is a specialized downhole tool housing explosive shaped charges arranged to create controlled perforations in steel casing, cement sheath, and surrounding formation rock, typically rated for pressures exceeding 15,000 psi and temperatures above 400°F. Its primary purpose is to establish conductive flow paths between hydrocarbon-bearing formations and the wellbore during completion operations. Shaped charge guns command the dominant product position due to their established reliability in deep unconventional wells, while wireless technology represents the fastest-growing segment as operators eliminate wireline dependencies for live-well interventions. Oil well completion applications generate the largest revenue pool, though reservoir enhancement work is gaining traction as mature field rejuvenation intensifies.
API RP 19B governs charge performance testing protocols in the United States, while OSHA's Process Safety Management standard regulates explosives handling across the domestic supply chain. The EPA's emissions disclosure requirements for hydraulic fracturing operations indirectly shape perforating gun demand by influencing completion design intensity. Stakeholders must monitor evolving Bureau of Alcohol, Tobacco, Firearms and Explosives storage regulations, as distributed inventory models face tightening compliance thresholds that could reshape logistics networks.
Market Dynamics
The perforating gun market is being restructured by the collapse of skilled explosives technician availability across North American oilfield service basins, forcing operators to redesign deployment protocols and accelerate wireless firing adoption to sustain completion intensity.
Growth Catalysts
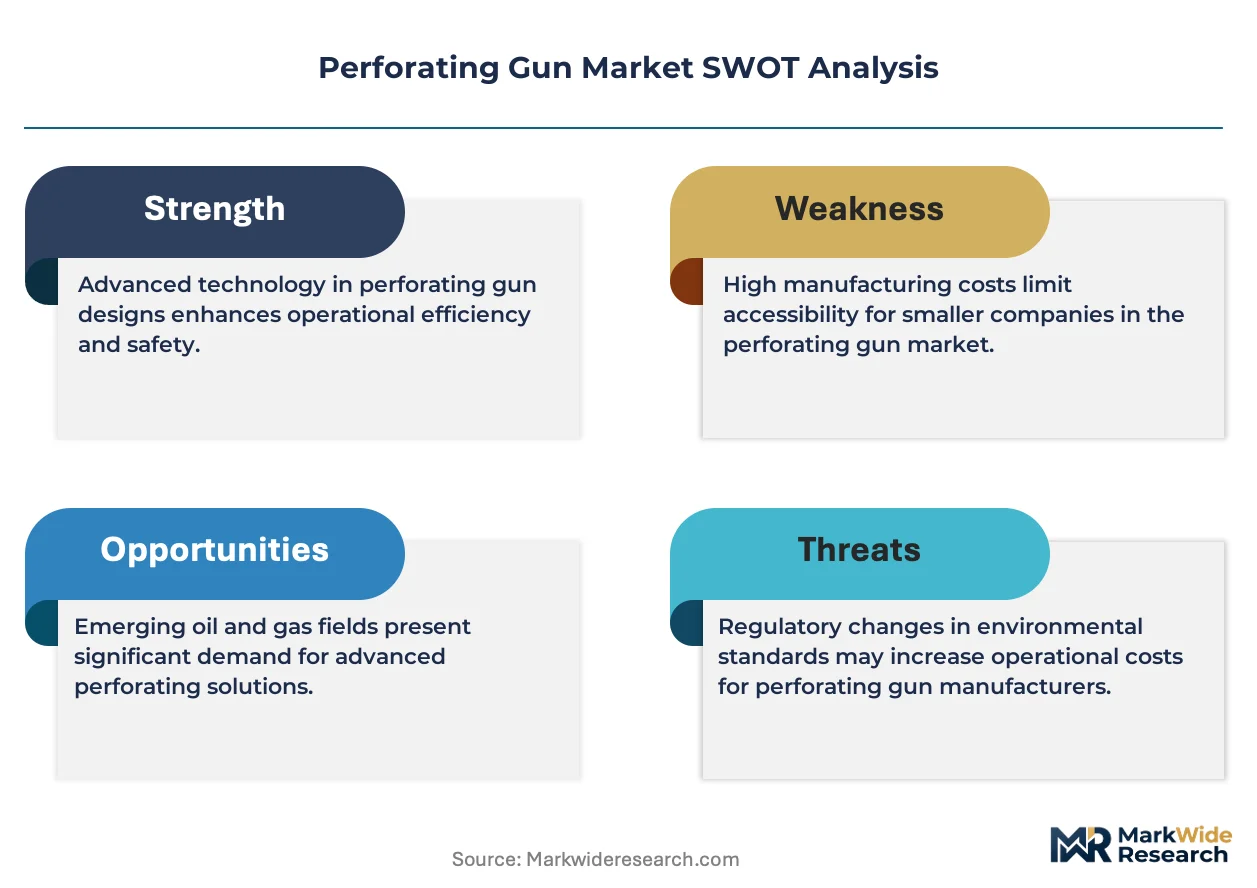
- API RP 19B tightening:Stricter shaped charge performance verification standards in the United States are mandating higher-specification gun systems that command premium positioning and extend replacement cycles.
- Horizontal well dominance:Extended-reach laterals in unconventional basins require more perforating stages per wellbore, directly expanding gun consumption per completion.
- Wireless firing maturation:Live-well intervention capability without wireline dependency is unlocking efficiency gains in high-pressure, high-temperature reservoirs previously inaccessible to conventional systems.
Market Restraints
- RDX and HMX cost volatility:Primary explosive raw materials face price instability tied to defense sector demand fluctuations and limited domestic manufacturing capacity.
- Permian supply concentration:Overreliance on West Texas infrastructure and service provider density creates regional vulnerability to weather disruptions and logistics bottlenecks.
- OSHA Process Safety Management:Explosives handling compliance costs are escalating as distributed inventory models face tightening storage threshold regulations.
Strategic Opportunities
- Mature field rejuvenation:Reservoir enhancement work in declining North Sea and Gulf of Mexico assets is opening secondary revenue pools beyond greenfield completions.
- Integrated perforating-frac systems:Convergence of gun deployment with hydraulic fracturing units is enabling single-trip completion designs that compress rig time.
- Canada oil sands thermal:Steam-assisted gravity drainage operations in Alberta represent an underpenetrated application requiring specialized high-temperature gun configurations.
Industry Challenges
- Explosives technician shortage:The skilled labor pipeline for handling shaped charges has collapsed, constraining multi-stage operation deployment capacity and forcing crew size optimization.
- ATF storage compliance:Bureau of Alcohol, Tobacco, Firearms and Explosives distributed inventory regulations are reshaping logistics networks and requiring capital-intensive facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perforating Gun Market |
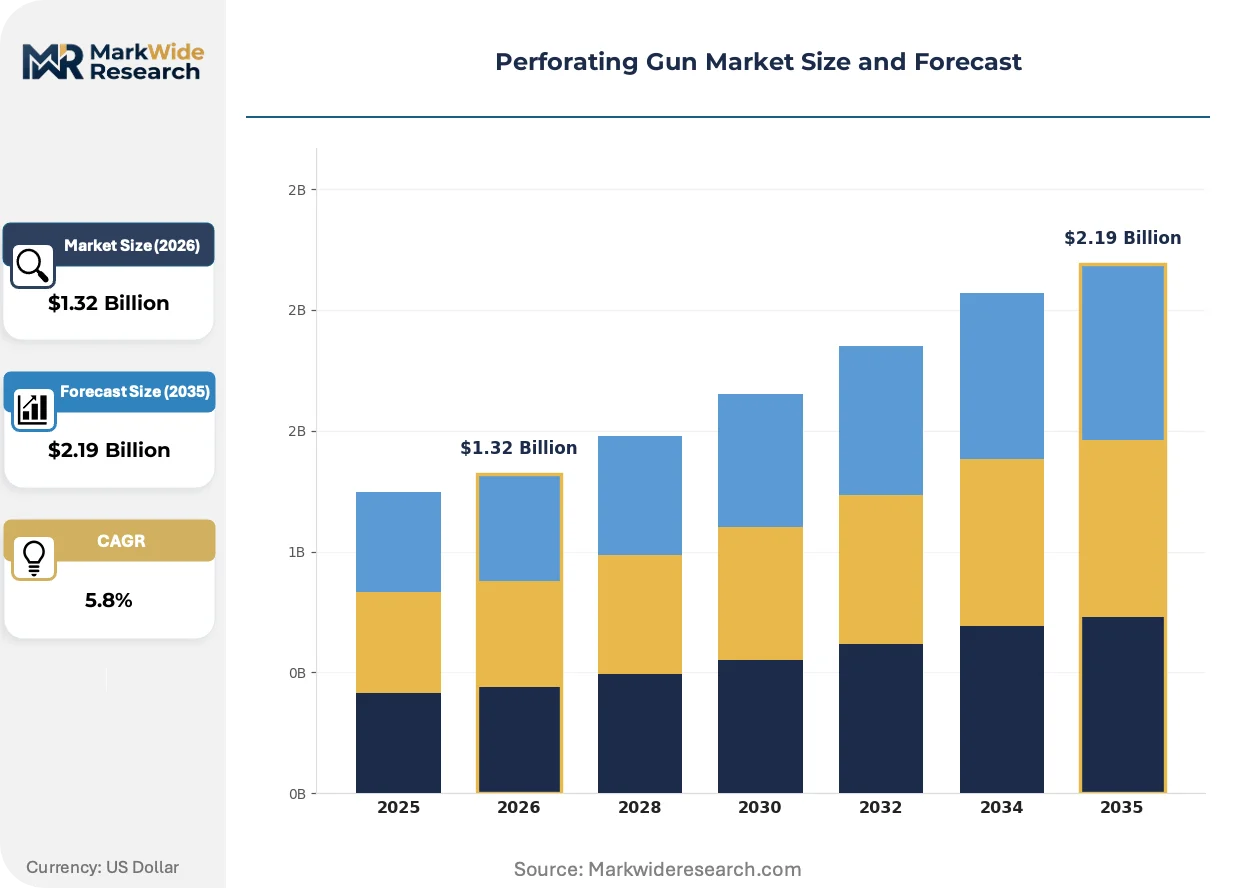
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Guns, Shaped Charge Guns, Multi-Diameter Guns, Jet Perforating Guns, Preloaded Guns Technology: Electric, Hydraulic, Fiber Optic, Pressure Activated, Wireless Application: Oil Well Completion, Gas Well Completion, Well Stimulation, Reservoir Enhancement End User: Drilling Contractors, Exploration Companies, Well Service Providers, Reservoir Management Firms |
| Companies Covered | Weatherford International plc, Hunting PLC, Baker Hughes Company, DMC Global Inc., DynaEnergetics, SLB, NOV Inc., Core Laboratories, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perforating Gun Market Strategic Shifts & Innovations
Digital firing architecture and automated charge verification systems are actively displacing manual intervention protocols across unconventional completion programs, compressing operational risk profiles while extending technical performance boundaries.
Addressable switch technology is decomposing traditional multi-wire gun string architectures into individually controllable perforation clusters. Unconventional shale operators in the Permian and Bakken formations are deploying these systems at accelerating rates to enable variable shot density without physical redress. The shift is decomposing legacy inventory models built around fixed-shot configurations and creating demand for software-defined perforating programs.
OSHA's evolving enforcement posture on explosives handling is mandating real-time personnel proximity monitoring and automated exclusion zone management at wellsite locations. The regulatory pressure is forcing capital allocation toward integrated safety systems rather than standalone gun hardware. Smaller independent operators lacking integrated service capabilities face disproportionate compliance burden concentration.
Buying patterns among supermajors and large independents are consolidating procurement around integrated service packages that bundle gun supply, firing control, and real-time diagnostics. Traditional equipment-only vendors are being displaced by full-service providers capable of outcome-based completion performance guarantees. This restructuring is most visible in the United States, where operator consolidation has concentrated purchasing power among a shrinking buyer base demanding single-accountability contracts.
Perforating Gun Market Segmentation
Perforating gun procurement patterns diverge sharply across deployment contexts, with unconventional shale operators prioritizing stage density and wireless reliability while mature basin work emphasizes cost-efficient conventional systems. Segment boundaries are blurring as integrated service packages bundle hardware, firing control, and diagnostics into single-accountability contracts.
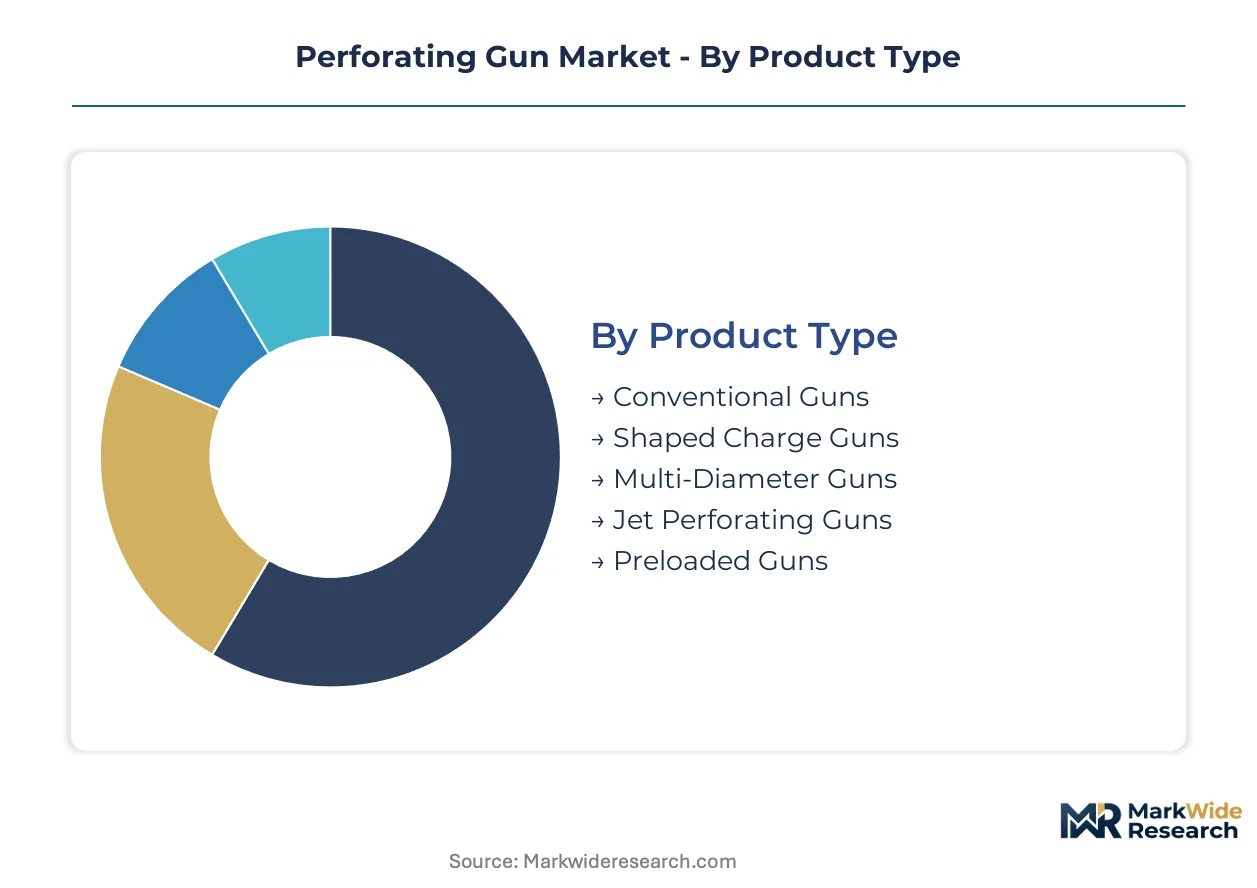
Product Type:
Domestic demand concentrates on systems engineered for Permian Basin pressure regimes, while export markets favor modular configurations adaptable to varying casing programs.
- Shaped Charge Guns:Steel-bodied carriers house precision-machined explosive charges rated for 15,000+ psi and 400°F operating envelopes. Operators in the Delaware and Midland sub-basins deploy these systems for 50+ stage laterals where charge reliability under thermal cycling determines completion economics.
- Multi-Diameter Guns:Adjustable outer diameter configurations accommodate variable casing programs without inventory duplication. Gulf of Mexico shelf operators favor these systems for batch-drilling campaigns across mixed wellbore architectures.
- Conventional Guns:Standard steel carriers with fixed charge arrangements serve mature onshore work where cost minimization outweighs stage complexity.
- Jet Perforating Guns:High-velocity fluid jet systems penetrate casing without explosives, finding niche application in sensitive subsea completions.
- Preloaded Guns:Factory-assembled charge strings reduce wellsite handling time and OSHA exposure hours for high-frequency programs.
Shaped charge systems command the established base. The steepest expansion runs through preloaded configurations as labor constraints intensify.
Technology:
Technology selection tracks operator scale, with supermajors absorbing wireless premiums and independents defaulting to proven electric architectures.
- Wireless:Radio-frequency firing eliminates wireline dependency for live-well interventions in high-pressure reservoirs. Permian operators are deploying these systems at accelerating rates to compress stage timing and reduce crew exposure.
- Electric:Conventional multi-wire architectures dominate legacy fleet operations where capital replacement cycles extend across multiple years.
- Hydraulic:Pressure-pulse activation serves subsea and deepwater contexts where electrical integrity at depth remains problematic.
- Fiber Optic:Immune to electromagnetic interference, these systems penetrate high-noise environments near production facilities.
- Pressure Activated:Simple mechanical firing mechanisms persist in low-complexity international markets with limited technical infrastructure.
Electric systems retain volume leadership across installed base. Wireless platforms are climbing the fastest as completion intensity pressures operational efficiency.
Application:
Application mix shifts with basin maturity, with greenfield unconventional work driving completion volumes and brownfield assets generating reservoir enhancement retrofit demand.
- Oil Well Completion:Horizontal shale programs in the Permian, Bakken, and Eagle Ford generate concentrated demand for multi-stage perforating systems optimized for tight-oil reservoir architecture.
- Well Stimulation:Perforating-frac integration enables single-trip completion designs that compress rig time and reduce fluid exposure.
- Gas Well Completion:Haynesville and Marcellus dry gas development favors higher-pressure gun ratings and corrosion-resistant metallurgy.
- Reservoir Enhancement:Recompletion work in declining North Sea and Gulf of Mexico assets opens secondary revenue pools beyond primary drilling.
Oil well completion anchors revenue concentration. Reservoir enhancement work is gaining share fastest as mature field rejuvenation intensifies.
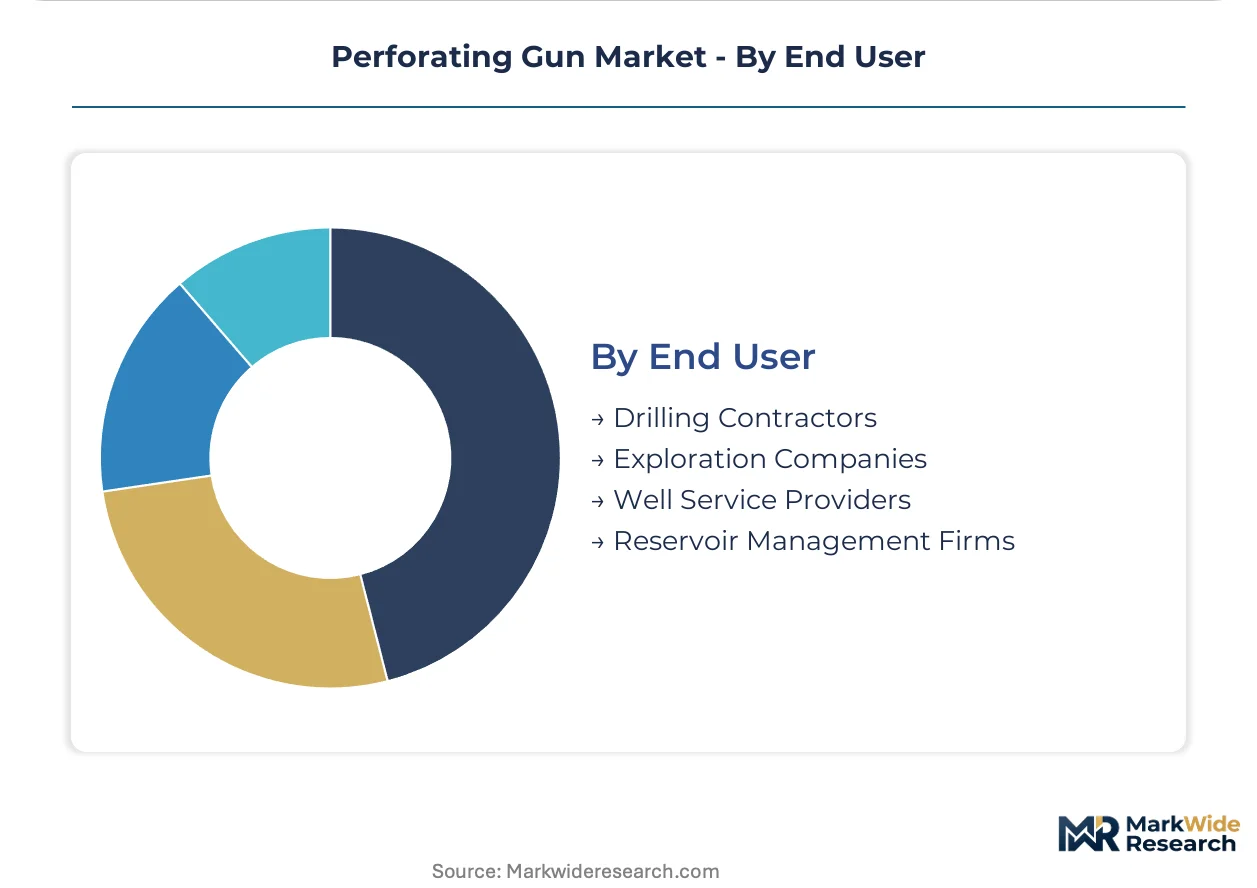
End User:
End-user procurement authority is consolidating, with drilling contractors ceding specification control to integrated well service providers.
- Well Service Providers:Schlumberger, Halliburton, and Baker Hughes bundle gun supply with pumping services, capturing specification authority through integrated performance guarantees.
- Drilling Contractors:Nabors and Helmerich & Payne retain influence where rifle-shot perforating precedes their rig-based completion activities.
- Exploration Companies:EOG Resources and Pioneer Natural Resources (now ExxonMobil) dictate technical requirements through long-term supply agreements.
- Reservoir Management Firms:Specialized enhanced oil recovery contractors specify perforating programs for CO2 flood and steam injection patterns.
Well service providers control the dominant procurement channel. Reservoir management firms are expanding their specification influence fastest as tertiary recovery projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where unconventional shale intensity commands premium gun configurations, while Canadian operators absorb cost pressures through standardized bulk procurement. This asymmetry shapes regional deployment strategies and technology adoption curves.
United States
Permian Basin operators drive demand for 50+ stage horizontal completions requiring high-pressure gun ratings. OSHA's Process Safety Management standard governs explosives handling protocols across Texas and New Mexico well sites. Midland-Odessa service clusters face acute technician shortages that accelerate wireless firing adoption.
Canada
Alberta oil sands thermal operations require specialized high-temperature gun configurations for steam-assisted gravity drainage. Health Canada regulates explosives storage and transport through the Explosives Act and associated permits. Calgary-based service providers coordinate supply chains reaching Fort McMurray thermal projects.
Saudi Arabia
Aramco's gas development programs in the Jafurah Basin generate demand for corrosion-resistant perforating systems. The Saudi Food and Drug Authority oversees industrial chemical imports including explosive precursors. Eastern Province drilling clusters around Dhahran integrate perforating with high-volume hydraulic fracturing campaigns.
China
Sinopec and PetroChina expand shale gas development in Sichuan Basin formations requiring extended-reach lateral perforating. The Ministry of Emergency Management regulates explosives manufacturing and storage under GB standards. Chongqing service hubs coordinate domestic gun assembly for southwestern tight-gas programs.
Norway
Equinor's mature North Sea assets drive recompletion work demanding modular gun systems for subsea interventions. The Petroleum Safety Authority Norway governs well intervention equipment certification. Stavanger service clusters specialize in reservoir enhancement perforating for declining Johan Sverdrup and Snøhvit fields.
Perforating Gun Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around integrated oilfield service providers bundling gun supply with pumping and diagnostics, while specialized manufacturers retain positions in shaped charge engineering and wireless firing systems. Two strategic archetypes dominate: vertically integrated energy service conglomerates and precision explosives specialists. Competitive moves concentrate on wireless technology licensing partnerships and backward integration into shaped charge manufacturing.
Among integrated service providers, SLB and Halliburton Company occupy positions exemplifying full-service bundling strategies, while Hunting PLC represents the explosives specialist archetype with captive manufacturing capabilities. These three anchors illustrate the structural divide between scale-driven service integration and component-level technical focus.
| Leading Market Players |
|---|
| Weatherford International plc |
| Hunting PLC |
| Baker Hughes Company |
| DMC Global Inc. |
| DynaEnergetics |
| SLB |
| NOV Inc. |
| Core Laboratories |
| Halliburton Company |
| Others |
Cost & Logistics Intelligence
API RP 19B certification gates both supplier qualification and price differentiation in perforating gun procurement, as operators demand documented charge performance verification that only premium manufacturers can deliver. This regulatory threshold stratifies the supply base into certified premium suppliers and non-compliant economy alternatives, compressing margins for undifferentiated competitors while protecting pricing power for verified performers.
Pricing Analysis
United States pricing commands a significant premium over Canadian and Middle Eastern markets due to higher-specification requirements for Permian Basin HPHT conditions. Three-tier pricing structure across premium, standard, and economy levels tracks API RP 19B certification status, with wireless-enabled systems capturing the top tier. Pricing pressure stems from operator consolidation concentrating purchasing power among supermajors demanding outcome-based performance guarantees. Independent operators show highest price sensitivity, defaulting to conventional electric architectures, while integrated service providers absorb wireless premiums for operational efficiency gains.
Supply Chain Analysis
Inventory lead times for shaped charges have extended due to ATF storage compliance upgrades forcing facility consolidation across Texas and New Mexico. Manufacturing concentrates in the United States, Germany, and China, with domestic capacity dominating North American demand. Raw material supply draws from defense-sector RDX and HMX producers, steel forging operations, and specialty electronics for firing systems. Single-source vulnerability runs through limited domestic explosive precursor manufacturers. Distribution runs through Midland-Odessa service clusters coordinating just-in-time delivery to multi-well pads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perforating gun market is entering cyclical recovery as unconventional drilling intensity rebounds from trough levels, with horizontal completion counts serving as the primary demand oscillator. Operators are restocking depleted gun inventories while accelerating wireless technology adoption to offset persistent labor constraints.
For Market Incumbents: Secure backward integration into shaped charge manufacturing to protect margin erosion from raw material volatility and defense-sector demand competition. Lock in long-term supply agreements with RDX and HMX producers before capacity constraints tighten. Defend position against emerging wireless specialists by accelerating addressable switch technology roadmaps and bundling real-time diagnostics with hardware deployment.
For New Entrants and Emerging Players: Lead with preloaded gun configurations targeting independent operators burdened by OSHA compliance costs and technician shortages. Alberta oil sands thermal applications represent the most penetrable white-space segment, requiring specialized high-temperature metallurgy that incumbent portfolios underserve. Establish go-to-market partnerships with Calgary-based service providers coordinating Fort McMurray logistics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wireless firing system development as software-defined perforating programs replace fixed-shot hardware inventory models. Long-term viability favors integrated service providers with captive manufacturing and diagnostics capabilities over pure-play equipment vendors. Target acquisition archetype: mid-cap explosives specialists with ATF-licensed facilities and proven shaped charge engineering. Watch for inflection signals in Permian stage-count recovery and supermajor integrated service contract awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Firing System Development | Eliminates wireline dependency for live-well interventions in HPHT reservoirs. |
| Preloaded Gun Configuration Expansion | Reduces OSHA exposure hours and accelerates deployment for labor-constrained operators. |
| Addressable Switch Technology Integration | Enables variable shot density control without physical redress across extended-reach laterals. |
| Shaped Charge Manufacturing Backward Integration | Secures supply chain reliability amid defense-sector explosive precursor competition. |
| Integrated Service Package Bundling | Captures specification authority through outcome-based completion performance guarantees. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with completion engineers, explosives technicians, well service procurement managers, and regulatory compliance officers across North American basins. Secondary validation drew from API RP 19B test documentation, OSHA enforcement records, ATF licensing databases, and operator capital expenditure disclosures. Bottom-up gun deployment counts by basin were triangulated against top-down oilfield service revenue segmentation.
Across the analysis window, forecasts model product type, technology platform, application context, and end-user procurement channel dimensions. CAGRs were derived from stage-count intensity projections tied to horizontal well completion forecasts. Industry-specific inputs include Permian Basin drilling permit trajectories, wireless firing system adoption curves, and explosives technician labor pool estimates.
Forecasts assume regulatory continuity in OSHA Process Safety Management and ATF storage regimes; material policy shifts would require re-modeling deployment capacity and logistics network economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Underreamers Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Well Completion Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market