
 Dissolvable Frac Plug Market | 2026-2036
Dissolvable Frac Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolvable Frac Plug Market Analysis
Modular plug-and-perf bundling with dissolvable frac balls and seats is expanding buyer choice toward integrated completion packages that reduce rig time. Halliburton Company leverages its integrated service model to bundle dissolvable plugs with pumping and wireline services across Permian and Eagle Ford operations. Baker Hughes Company anchors its position through proprietary metal alloy formulations that control dissolution rates in varying downhole chemistries. Schlumberger NV competes by extending its portfolio into fully dissolvable bridge plugs that eliminate mechanical intervention in extended-reach laterals.
Dissolvable frac plugs are downhole isolation devices fabricated from engineered metallic alloys, ceramic composites, or high-performance polymers that degrade predictably in wellbore fluids after hydraulic fracturing operations, typically dissolving within hours to days based on temperature, salinity, and pH conditions to restore full wellbore diameter without milling. Water-soluble technology leads current deployment volumes due to proven reliability in freshwater and low-salinity formations, while acid-soluble variants represent the fastest-growing category as operators push into high-temperature, high-salinity basins where controlled dissolution demands precise chemical triggering. Composite product types occupy the premium tier with superior mechanical strength during high-pressure stimulation, whereas polymer-based plugs capture cost-sensitive applications in shallower, lower-pressure zones.
The EPA regulates downhole material disposal and wellbore integrity under the Safe Drinking Water Act Underground Injection Control program, while OSHA mandates worker exposure limits during plug deployment and dissolution byproduct handling. API standards for frac plug testing and validation shape product qualification requirements that determine market access for new entrants. Stakeholders must monitor evolving state-level restrictions on dissolved metal concentrations in produced water streams and assess how biodegradable certification standards from ISO could reshape material selection criteria across supplier portfolios.
Market Dynamics
The shift toward extended-reach laterals and multi-well pad development in North American shale basins is compressing completion timelines and eliminating mechanical intervention steps. Operators now demand isolation technologies that dissolve predictably without mill-out operations, fundamentally restructuring supplier value propositions around chemistry control and dissolution precision.
Growth Catalysts
- EPA methane emissions standards:The EPA's updated performance standards for new, modified, and reconstructed oil and gas facilities mandate reduced venting and fugitive emissions during completion operations. Single-trip dissolvable systems eliminate venting associated with plug drill-out and reduce overall wellsite emissions intensity.
- Permian Basin lateral extension:West Texas and southeastern New Mexico operators are pushing lateral lengths beyond 15,000 feet, where mechanical intervention becomes prohibitively expensive and time-consuming. Dissolvable plugs enable continuous pumping operations without coil tubing or workover rigs.
- High-temperature alloy chemistry:Advanced magnesium and aluminum alloy formulations now withstand bottom-hole temperatures exceeding 350°F while maintaining controlled dissolution rates. This material breakthrough opens high-thermal-gradient basins previously inaccessible to dissolvable technologies.
Market Restraints
- Raw material concentration:Specialty magnesium alloys and rare-earth-doped aluminum grades concentrate among a limited set of metallurgical suppliers, primarily in China and Russia. This upstream concentration exposes frac plug manufacturers to supply disruption and price volatility.
- Dissolution rate variability:Downhole fluid chemistry heterogeneity—salinity fluctuations, pH shifts, and temperature gradients—creates unpredictable dissolution timing. Operators in formations with highly variable produced water chemistry face reliability risks that constrain adoption.
- Coil tubing substitute competition:In shorter laterals and lower-well-count pads, conventional composite plugs with economic coil tubing mill-out retain cost advantages. This substitute technology limits dissolvable plug penetration in shallower, less capital-intensive development scenarios.
Strategic Opportunities
- Argentina Vaca Muerta shale:Neuquén Basin operators are replicating North American pad drilling models but lack established mill-out service infrastructure. Dissolvable plug deployment eliminates capital-intensive coil tubing fleet requirements and accelerates development timelines for international operators.
- API 19G qualification expansion:The API's emerging standards for dissolvable downhole equipment create first-mover certification advantages. Suppliers achieving early qualification under this framework gain preferential positioning with supermajors and national oil companies.
- Real-time dissolution monitoring:Integration of distributed fiber optic sensing with dissolvable plug systems enables downhole confirmation of complete dissolution before flowback initiation. This technology convergence reduces operational uncertainty and insurance costs.
Industry Challenges
- Materials engineering talent scarcity:The intersection of corrosion science, mechanical engineering, and oilfield application expertise is concentrated among a small cohort of specialists. Recruitment competition from battery and aerospace sectors constrains supplier R&D velocity.
- ISO 13628-4 compliance timelines:Subsea and high-pressure wellhead equipment certification protocols are being adapted for dissolvable plug validation. Extended testing cycles for dissolution predictability and debris generation slow product commercialization.
- Legacy wellbore compatibility:Older casing designs and worn wellbore geometries in mature basins present sealing surface irregularities that challenge dissolvable plug elastomer and metal-to-metal seal integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolvable Frac Plug Market |
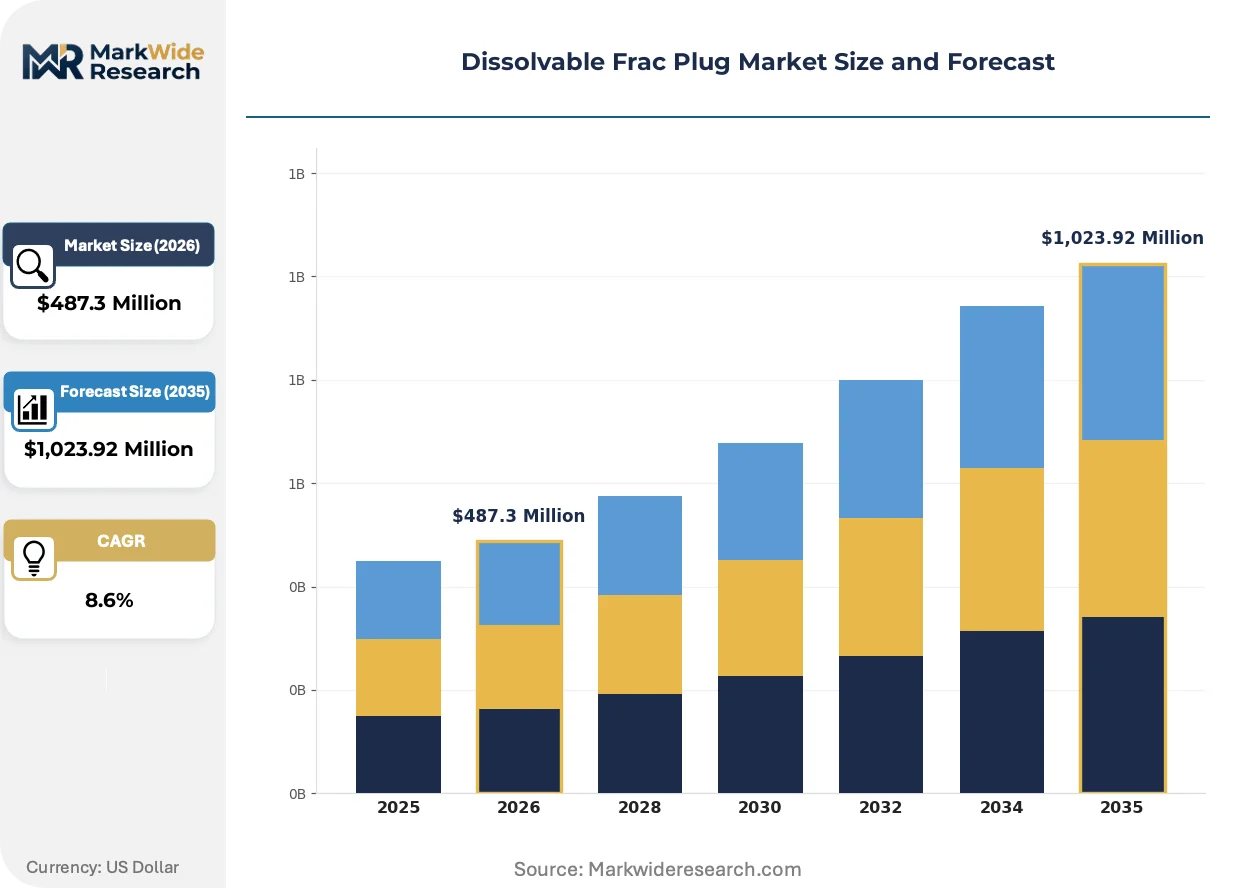
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Ceramic, Polymers, Others Technology: Water-soluble, Acid-soluble, Biodegradable, Others End User: Oil & Gas, Water Resources, Geothermal, Offshore Application: Pressure Testing, Stimulation, Well Completion, Reservoir Management |
| Companies Covered | Halliburton Company, Schlumberger NV, Baker Hughes Company, Nine Energy Services Inc., NCS Multistage, NexTier Oilfield Solutions, Weatherford International plc, Innovex Downhole Solutions, Inc., KLX Energy Services Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolvable Frac Plug Market Emerging Trajectories
Material science advances and downhole sensing integration are compressing the uncertainty window around dissolvable plug performance. Suppliers now compete on dissolution predictability rather than mechanical strength alone, shifting R&D investment toward real-time monitoring and adaptive chemistry.
Smart alloy systems incorporating microelectromechanical sensors are automating dissolution verification in extended-reach laterals. Baker Hughes and Halliburton field crews in the Permian Basin now deploy these instrumented plugs to confirm complete material degradation before initiating flowback. This automation eliminates the conservative waiting periods that previously extended completion timelines by 12-24 hours.
The EPA's finalized methane emissions standards under the Clean Air Act New Source Performance Standards are mandating reduced completion-related venting. Operators in the Denver-Julesburg and Powder River basins are responding by specifying dissolvable plug systems that eliminate venting associated with conventional plug drill-out operations. This regulatory pressure is accelerating specification changes in operator procurement standards.
Integrated service contracting is displacing discrete equipment purchasing across major shale basins. Exploration and production companies in the Eagle Ford and Bakken formations now bundle dissolvable plugs with pumping, wireline, and flowback services under single-provider arrangements. This procurement consolidation favors suppliers with full-service capabilities and compresses margins for standalone equipment manufacturers.
Dissolvable Frac Plug Market Segmentation
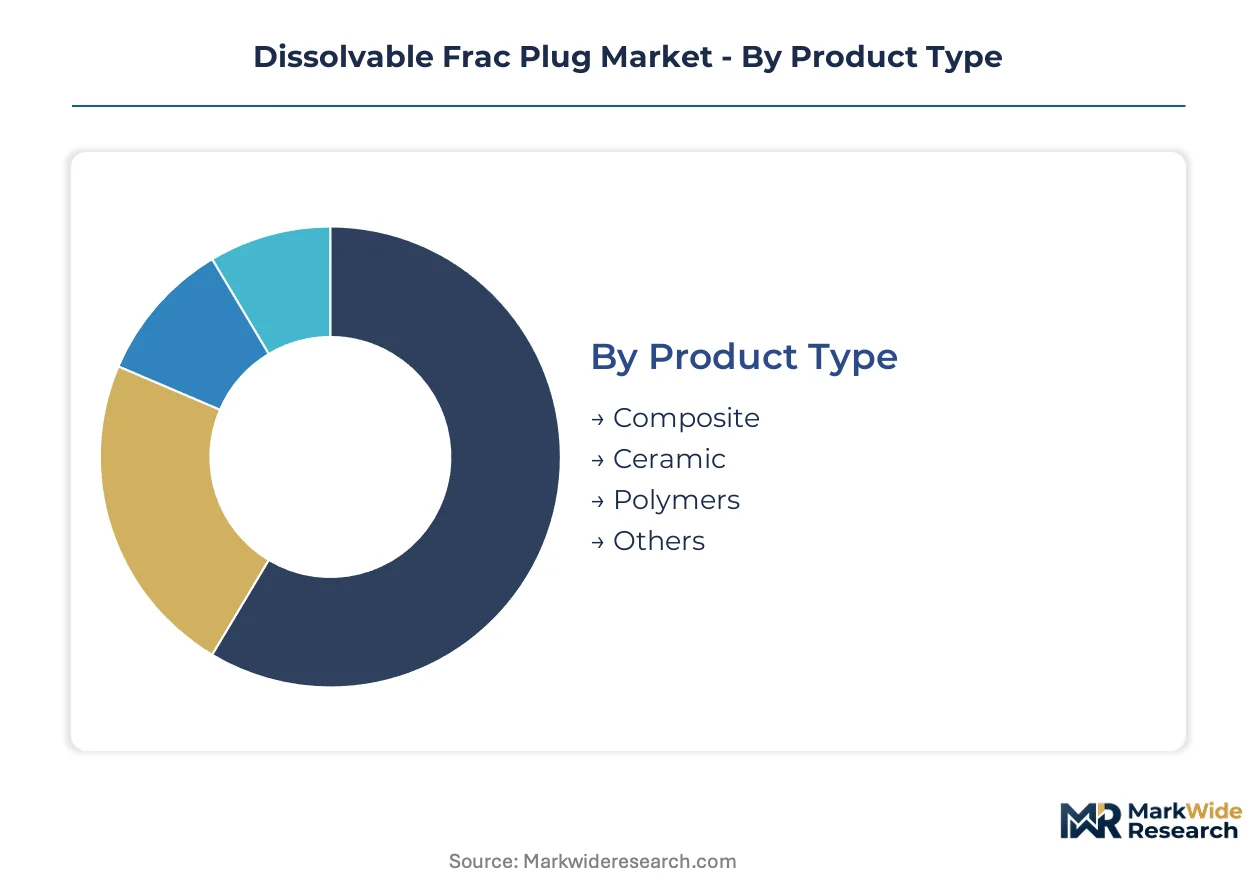
Dissolvable frac plug procurement varies sharply by wellbore chemistry, thermal gradient, and completion strategy. Buyers select material systems and dissolution mechanisms to match specific downhole conditions rather than defaulting to standardized specifications.
Product Type:
Cost tier separates premium mechanical performance from economy-grade deployment in shallower zones.
- Composite:Engineered fiber-reinforced polymer matrices deliver superior tensile strength and pressure containment during high-rate stimulation stages. Operators in the Permian Basin specify composite plugs for extended-reach laterals exceeding 12,000 feet where mechanical integrity failures carry catastrophic cost consequences.
- Ceramic:Aluminum oxide and silicon carbide formulations withstand bottom-hole temperatures above 350°F while maintaining predictable fracture patterns during dissolution. Appalachian Basin operators confronting high-thermal-gradient Marcellus and Utica formations drive ceramic specification for thermal stability assurance.
- Polymers:Cost-optimized polyglycolic acid and polylactic acid constructions serve shallow, low-pressure zones in the Powder River Basin where dissolution speed outweighs mechanical premium.
- Others:Hybrid metal-polymer laminates and experimental bio-composites address niche wellbore geometries in legacy California fields.
Volume sits with composite systems; growth tilts toward ceramic formulations as thermal demands intensify.
Technology:
Application environment—salinity, pH, and temperature—determines dissolution chemistry selection rather than plug geometry.
- Water-soluble:Magnesium and aluminum alloys degrade predictably in aqueous wellbore fluids through controlled oxidation reactions. Freshwater and low-salinity formations in the Eagle Ford and Denver-Julesburg basins anchor current deployment volumes due to established reliability profiles.
- Acid-soluble:Calcium carbonate and acid-reactive metal composites trigger dissolution through pH reduction, enabling precise timing control in high-salinity brines. Bakken operators managing highly variable produced water chemistry specify acid-soluble systems to eliminate premature degradation risks.
- Biodegradable:Enzyme-triggered and microbially-active materials align with emerging EPA produced water discharge standards. Oklahoma regulatory pressure on dissolved metal concentrations accelerates biodegradable specification in SCOOP-STACK development.
- Others:Electrochemical and thermally-activated dissolution mechanisms remain experimental for ultra-deep Gulf Coast wells.
Deployment dominance belongs to water-soluble chemistry; specification momentum shifts fastest toward acid-soluble variants.
End User:
Customer type dictates performance requirements, with hydrocarbon extraction demanding the most stringent mechanical specifications.
- Oil & Gas:Exploration and production operators in unconventional shale basins require isolation devices rated for 10,000+ psi differential pressure and 300°F bottom-hole temperatures.
- Water Resources:Aquifer storage and recovery wells in California and Texas specify lower-pressure dissolvable plugs for temporary zonal isolation during injection testing.
- Geothermal:Enhanced geothermal system developers in Nevada and Utah test high-temperature alloy formulations exceeding 400°F operational limits.
- Offshore:Gulf of Mexico subsea completions demand corrosion-resistant formulations compatible with high-pressure, high-temperature wellhead environments.
Revenue concentration rests with oil and gas applications; geothermal represents the steepest expansion trajectory as renewable baseload capacity scales.
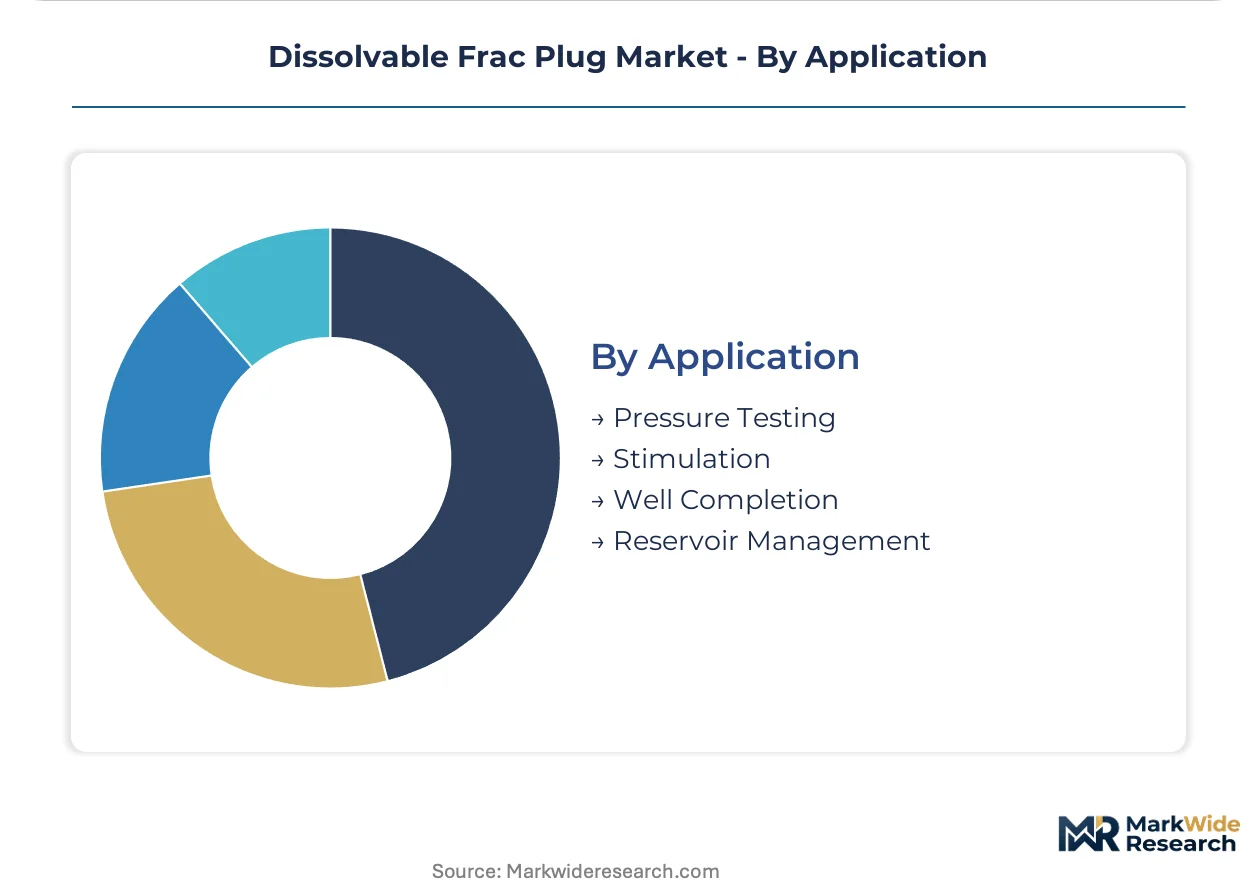
Application:
Operational phase within the well lifecycle determines plug specification, with stimulation-stage devices facing the most extreme mechanical demands.
- Pressure Testing:Temporary isolation for casing integrity verification requires rapid dissolution without milling but lower pressure ratings than stimulation plugs.
- Stimulation:Multi-stage hydraulic fracturing demands plugs that withstand repeated pressure cycling and abrasive proppant flow before complete dissolution.
- Well Completion:Final zonal isolation before production startup favors slower-dissolving formulations that maintain integrity through initial flowback.
- Reservoir Management:Workover and recompletion applications in mature Texas fields use dissolvable plugs to avoid mechanical intervention in corroded casing.
Stimulation-stage volume dominates procurement; reservoir management applications are climbing fastest as shale basins mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin Development Zone spanning West Texas and southeastern New Mexico concentrates dissolvable frac plug deployment through tax-advantaged drilling incentives and streamlined permitting corridors. This concentration pattern replicates across four additional national markets where unconventional development economics favor elimination of mechanical intervention.
United States
The EPA's methane emissions standards under the Clean Air Act New Source Performance Standards mandate reduced venting during completion operations. Appalachian Basin operators in Pennsylvania and West Virginia specify dissolvable systems for Marcellus and Utica shale stages. The Denver-Julesburg Basin in Colorado and Wyoming is accelerating specification changes as state regulators tighten venting restrictions.
Argentina
Neuquén Basin operators replicate North American pad drilling models without established coil tubing infrastructure. The national petroleum regulator enforces well integrity standards that favor single-trip completion technologies. Vaca Muerta shale development clusters around Loma Campana and Bajada de Añelo where international operators deploy dissolvable plugs to eliminate capital-intensive mill-out fleets.
Canada
Montney and Duvernay formation operators in Alberta and British Columbia adopt dissolvable technologies to compress completion timelines during abbreviated drilling seasons. Environment and Climate Change Canada methane regulations align with US EPA standards. The Grande Prairie region anchors Western Canadian adoption as LNG export projects drive pad development intensity.
Saudi Arabia
Unconventional gas development in the Jafurah Basin creates demand for high-temperature dissolvable systems. The national hydrocarbon regulator mandates well integrity standards compatible with dissolvable isolation technologies. Eastern Province drilling clusters around Haradh and Ghawar field extensions where extended-reach laterals favor chemistry-controlled dissolution over mechanical retrieval.
China
Sichuan Basin shale gas operators in the Fuling and Weiyuan blocks test dissolvable plug deployment for multi-well pad efficiency. The Ministry of Ecology and Environment enforces produced water discharge standards that favor biodegradable dissolution byproducts. Chongqing municipality anchors Southwestern Chinese adoption through state-backed unconventional development programs.
Dissolvable Frac Plug Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around integrated service capabilities. The vendor base stratifies into three tiers: full-service oilfield service conglomerates controlling chemistry and pumping assets, specialized downhole equipment fabricators with alloy formulation expertise, and regional service companies bundling third-party plugs with local deployment capacity. Dominant competitive moves include backward integration into specialty magnesium alloy supply and strategic partnerships with distributed fiber optic sensing providers.
Among Houston-based integrated service conglomerates, Halliburton Company and Baker Hughes Company exemplify the full-service archetype through bundled dissolvable plug deployment with pumping and wireline operations. Schlumberger NV occupies a distinct position extending portfolio coverage into fully dissolvable bridge plug categories. These three entities anchor competitive dynamics around dissolution predictability and real-time monitoring integration rather than mechanical strength differentiation alone.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger NV |
| Baker Hughes Company |
| Nine Energy Services Inc. |
| NCS Multistage |
| NexTier Oilfield Solutions |
| Weatherford International plc |
| Innovex Downhole Solutions, Inc. |
| KLX Energy Services Holdings |
| Others |
Supply Flow & Price Mechanics
Magnesium alloy spot indices on the London Metal Exchange cascade through dissolvable frac plug manufacturing into three-tier pricing stratification across premium composite, standard ceramic, and economy polymer grades. Specialty rare-earth-doped aluminum ingot costs concentrate pricing power among integrated service conglomerates with captive metallurgical supply, while standalone equipment fabricators absorb margin compression from volatile Chinese and Russian raw material markets.
Pricing Analysis
Margin tightening in economy-grade polymer plugs reflects volume consolidation around bundled service contracts from Halliburton and Baker Hughes. Three-tier pricing structure across premium, standard, and economy levels separates composite systems rated for 15,000-foot laterals from ceramic thermal-stable formulations and shallow-zone polymer alternatives. Price differentiation hinges on API 19G qualification status and dissolution predictability guarantees, with supermajor procurement teams least sensitive and independent Permian operators most price-responsive.
Supply Chain Analysis
Dual-sourcing mandates from ExxonMobil and Chevron require frac plug manufacturers to qualify magnesium alloy suppliers across China, Russia, and domestic US metallurgical producers. Specialty rare-earth doping agents and high-purity aluminum billets draw from concentrated upstream refining capacity, creating tariff exposure from Section 232 steel and aluminum duties. Distribution runs through Halliburton and Baker Hughes regional service yards in Midland, Denver-Julesburg, and Appalachia, with last-mile deployment executed by wireline crews under integrated service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty magnesium alloy smelting capacity constraints prop dissolvable frac plug pricing power, as metallurgical suppliers struggle to expand rare-earth doping throughput for high-temperature formulations.
For Market Incumbents: Hedge raw material exposure through backward integration into specialty alloy supply or long-term offtake agreements with Chinese and Russian smelters. Defend against coil tubing substitute competition by accelerating real-time dissolution monitoring integration, which locks in supermajor specification preferences. Prioritize API 19G certification investment to maintain procurement gatekeeper status with national oil companies in Saudi Arabia and Argentina. For New Entrants and Emerging Players: Real-time fiber optic sensing integration offers the most penetrable wedge for standalone technology specialists lacking pumping assets. Target Vaca Muerta shale operators in Argentina's Neuquén Basin, where absent coil tubing infrastructure eliminates integrated service bundling advantages. Pursue geothermal energy developers in Nevada and Utah as a white-space vertical, where 400°F operational requirements exceed incumbent polymer formulation capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor alloy formulation specialists with ISO 13628-4 compliance progress in the US Gulf Coast corridor. Five-to-ten-year viability rests on material science talent retention as battery and aerospace sectors compete for corrosion engineers. Watch EPA produced water discharge standard tightening as the signal for biodegradable specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Halliburton and Baker Hughes captive magnesium sourcing insulates margin from Chinese export volatility. |
| API 19G Qualification Achievement | First-mover certification under emerging dissolvable equipment standards secures supermajor procurement preference. |
| Real-Time Dissolution Monitoring Integration | Fiber optic sensing partnerships with Baker Hughes and Schlumberger eliminate conservative 12-24 hour waiting periods. |
| Geographic Expansion into Argentina Vaca Muerta | Neuquén Basin pad drilling without coil tubing infrastructure accelerates dissolvable plug specification. |
| High-Temperature Alloy R&D Investment | 400°F magnesium formulations unlock enhanced geothermal system deployment in Nevada and Utah. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this dissolvable frac plug market assessment. Primary interviews with completion engineers at Permian and Eagle Ford operators, wireline service managers, metallurgical procurement leads, and EPA regulatory affairs specialists combined with API standards documentation, SEC 10-K equipment disclosures, and USGS mineral commodity summaries. Bottom-up well count and stage intensity models triangulated against top-down service revenue aggregation.
Granularity-level modeling distinguished composite, ceramic, and polymer product types across water-soluble, acid-soluble, and biodegradable technology categories. End-user segmentation captured oil and gas, geothermal, water resources, and offshore applications with stimulation-stage versus reservoir management deployment phases. CAGRs derived from stage-count growth curves and dissolvable plug penetration rate assumptions, incorporating EPA methane regulation compliance timelines and Permian lateral extension trajectories.
Several conditions sit outside the modeled scope, including abrupt rare-earth export restrictions from China, breakthrough electrochemical dissolution technologies, and coil tubing cost reductions that reverse substitution economics. Forecasts reflect documented assumptions about alloy dissolution predictability and high-temperature performance validation. Deviation in EPA produced water metal concentration limits or API 19G certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Oil Hose Market
Oil & Gas
Nigeria Oil and Gas Market