
 Signal Jammer Market | 2026-2036
Signal Jammer Market Size, Share, and Industry Trends Forecast 2026-2036
Signal Jammer Market Intelligence
Defense agency procurement is expanding as the fastest-growing end-use vertical, overtaking traditional law enforcement channels in annual contract volume. L3Harris Technologies leverages its software-defined electronic warfare portfolio to dominate military frequency-hopping jammer contracts. BAE Systems anchors European defense programs through its specialized counter-IED and convoy protection systems. Northrop Grumman Corporation competes on integrated platform solutions that embed jamming modules into broader electronic attack architectures.
A signal jammer is a radio-frequency transmitting device designed to disrupt, block, or interfere with wireless communications by emitting noise or deceptive signals across targeted frequency bands, typically operating from 20 MHz to 6 GHz with power outputs ranging from milliwatts for handheld units to kilowatts for fixed installations. Its primary commercial and industrial purpose is to neutralize unauthorized or hostile wireless transmissions in security-sensitive environments. Vehicle-mounted systems represent the fastest-growing product category, driven by mobile force protection requirements, while handheld units occupy the largest installed base due to lower procurement thresholds across corporate security and private user segments. Digital technology leads in new program awards as military operators demand programmable, multi-band coverage, whereas analog architectures persist in cost-constrained personal privacy applications where single-frequency blocking suffices.
The Federal Communications Commission prohibits civilian marketing and operation of signal jammers in the United States, creating a bifurcated market where legal demand channels through federal and state agencies exclusively. The European Union's Radio Equipment Directive and national spectrum regulators such as France's ANFR enforce type-approval requirements that limit commercial availability while permitting licensed security and defense applications. Stakeholders must monitor evolving drone mitigation regulations, as counter-UAS jamming authorizations represent the most significant demand expansion mechanism outside traditional military procurement.
Market Dynamics
Defense procurement officers are consolidating vendor relationships around software-defined radio architectures that enable rapid frequency reprogramming, compressing qualification timelines and squeezing analog hardware suppliers from military contract pools.
Growth Catalysts
- Counter-UAS Authorization Expansion:FAA and FCC are granting selective experimental licenses for drone mitigation jammers at critical infrastructure sites, opening civilian-adjacent demand channels previously sealed under blanket prohibitions.
- NATO Convoy Protection Mandates:Vehicle-mounted electronic warfare systems are receiving accelerated funding through collective defense procurement frameworks, with member states harmonizing technical specifications to enable cross-border interoperability.
- Software-Defined Radio Maturation:Field-programmable gate arrays and open-source waveform libraries are slashing development costs for multi-band jamming platforms, enabling mid-tier defense contractors to challenge established radio frequency specialists.
Market Restraints
- Gallium Nitride Supply Concentration:High-electron-mobility transistors essential for efficient power amplification depend on Chinese substrate manufacturing, exposing defense contractors to export control volatility and supply disruption.
- FCC Marketing Prohibition:The Communications Act of 1934 and subsequent enforcement orders criminalize civilian sales, forcing manufacturers to maintain entirely separate production lines and compliance documentation for authorized government channels.
- Spectral Efficiency Trade-offs:Wideband jamming generates harmful interference outside target bands, triggering international spectrum coordination disputes that delay host-nation agreements for deployed military systems.
Strategic Opportunities
- Prison System Modernization:Federal Bureau of Prisons and state correctional authorities are replacing legacy cellular jammers with managed access systems that permit authorized calls while blocking contraband phones, creating upgrade cycles across 122 federal facilities.
- Integrated Electronic Attack Architectures:Jamming modules are converging with cyber and signals intelligence payloads on common airborne and maritime platforms, enabling prime contractors to capture larger program shares through subsystem bundling.
- EU Drone Mitigation Harmonization:The European Union Aviation Safety Agency is developing standardized counter-UAS authorization pathways that would replace fragmented national permits with bloc-wide operating certificates.
Industry Challenges
- RF Engineering Talent Scarcity:Microwave circuit design and electromagnetic compatibility testing require specialized expertise that universities are producing insufficiently to match defense sector hiring targets.
- Legacy Platform Integration Complexity:New digital jamming systems must interface with analog-era command-and-control networks through protocol translation layers that introduce latency and reliability risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Signal Jammer Market |
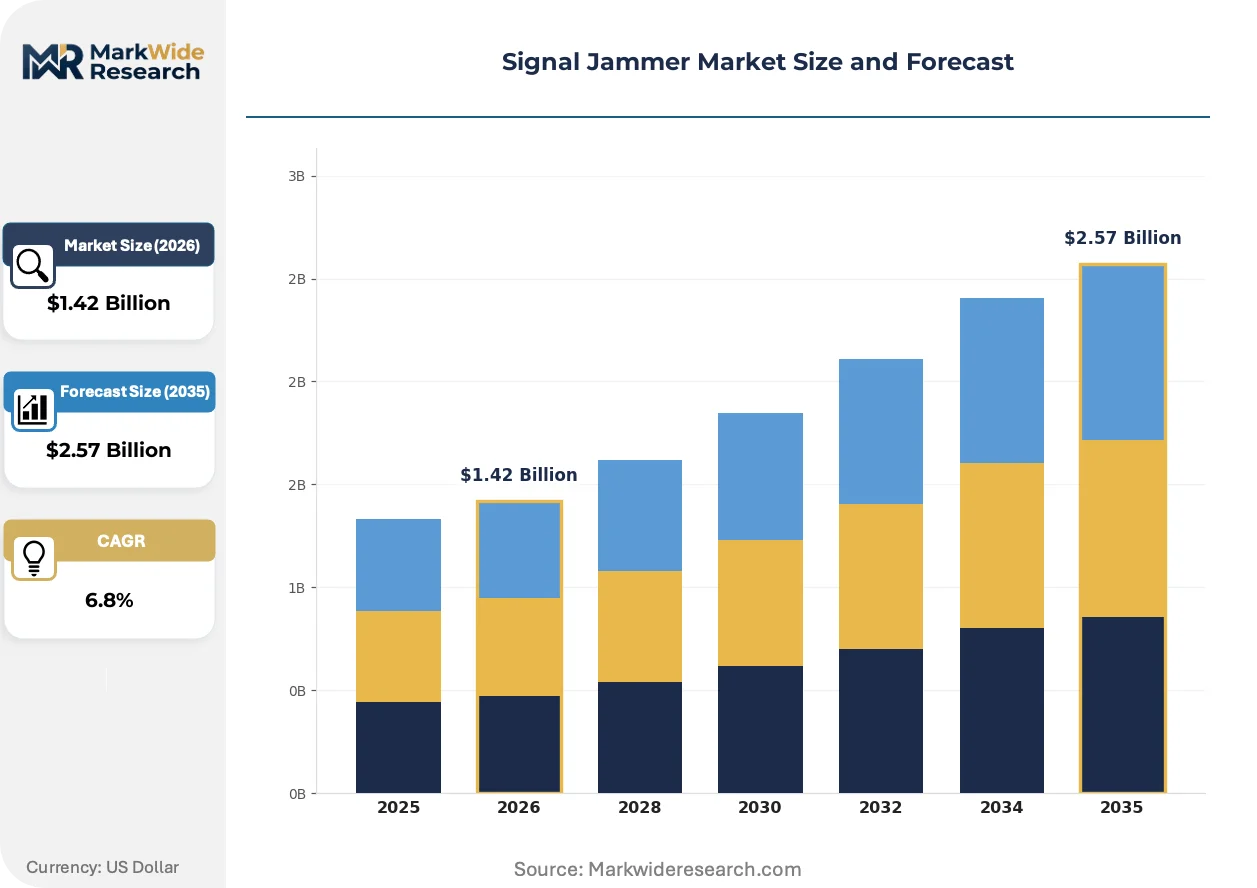
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Vehicle-Mounted, Fixed Installation Technology: Analog, Digital, Frequency Hopping, Broadband Application: Military Operations, Personal Privacy, Security Enforcement, Counter-Surveillance End User: Law Enforcement, Defense Agencies, Corporate Security, Private Users |
| Companies Covered | L3Harris Technologies, Thales Group, Raytheon Technologies Corporation, MCTECH Technology, HSS Development, Lockheed Martin, BAE Systems, SESP Group, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Signal Jammer Market Strategic Shifts & Innovations
Active electronically scanned arrays and cognitive jamming algorithms are redefining performance benchmarks, while regulatory frameworks struggle to keep pace with dual-use technology diffusion.
Artificial intelligence-enabled threat detection is converging with real-time waveform generation to create adaptive jamming systems that identify and counter frequency-hopping protocols without operator intervention. Military electronic warfare units are field-testing these cognitive architectures in contested electromagnetic environments. The technology is converging with existing platform electronics to reduce standalone payload weight and power draw.
The European Union's Radio Equipment Directive is tightening electromagnetic compatibility certification requirements for security-sensitive radio equipment, extending type-approval timelines by six to twelve months for non-EU manufacturers. National regulators including France's ANFR are conducting enhanced post-market surveillance on jamming equipment sold to licensed security services. Counter-UAS system vendors are establishing EU-based testing laboratories to maintain market access.
Defense procurement officers are consolidating annual contract volumes into multi-year framework agreements that bundle hardware, software licenses, and sustainment services under single vendor relationships. Small specialty jamming houses are losing direct bidding access to prime platforms, instead licensing subsystems to tier-one integrators. This channel compression is most visible in United States Department of Defense programs, where L3Harris and Northrop Grumman are absorbing subsystem suppliers into their supply chains.
Signal Jammer Market Segmentation
Signal jammer procurement patterns diverge sharply across deployment contexts, with military buyers prioritizing software-defined flexibility while civilian-adjacent channels remain legally constrained. Understanding these segment boundaries reveals where technology investments concentrate versus where legacy hardware persists.
Product Type:
Mobility requirements separate tactical operators from facility-based security managers, driving fundamentally different power, weight, and cooling specifications.
- Handheld:Compact battery-powered units operating below 5 watts dominate corporate security and private user channels where concealment matters. FCC prohibitions channel United States demand exclusively through federal prison systems and military special operations units requiring clandestine deployment.
- Vehicle-Mounted:NATO convoy protection mandates are accelerating procurement of 500-watt to 2-kilowatt systems with active electronically scanned arrays. Member states are harmonizing technical specifications to enable cross-border interoperability for collective defense frameworks.
- Portable:Transit-case designs bridge tactical and fixed applications, serving rapid deployment scenarios at temporary checkpoints or emergency response sites.
- Fixed Installation:Permanent kilowatt-scale installations protect critical infrastructure and correctional facilities with continuous spectrum monitoring and remote management capabilities.
Handheld units lead volumes today; vehicle-mounted systems are gaining share fastest.
Technology:
Defense procurement officers now treat programmability as a threshold requirement, compressing analog suppliers into cost-constrained personal privacy niches.
- Digital:Field-programmable gate array architectures enable real-time waveform adaptation across 20 MHz to 6 GHz coverage. Military electronic warfare units are consolidating vendor relationships around these software-defined platforms.
- Frequency Hopping:Cognitive algorithms identify and counter agile protocols without operator intervention. L3Harris Technologies dominates United States Department of Defense contracts through integrated electronic attack portfolios embedding this capability.
- Analog:Discrete component designs persist where single-frequency blocking suffices and procurement budgets are constrained.
- Broadband:Wideband noise generation covers multiple threat bands simultaneously, though spectral efficiency trade-offs trigger international coordination disputes.
Digital platforms anchor new program awards; frequency hopping is expanding most quickly in contested electromagnetic environments.
Application:
Threat sophistication determines whether buyers need full-spectrum dominance or targeted neutralization of specific transmission protocols.
- Military Operations:Integrated electronic attack architectures combine jamming with cyber and signals intelligence payloads on common platforms. Prime contractors capture larger program shares through subsystem bundling.
- Security Enforcement:Managed access systems are replacing legacy cellular jammers across 122 United States federal prison facilities, permitting authorized calls while blocking contraband phones.
- Counter-Surveillance:Corporate and diplomatic buyers deploy RF detection and localized jamming against unauthorized audio and video transmission.
- Personal Privacy:Consumer-grade devices operate in regulatory gray zones outside United States and European Union jurisdictions.
Military operations concentrate the highest contract values; security enforcement is climbing the fastest as prison modernization cycles accelerate.
End User:
Budget scale and legal authorization separate institutional buyers from restricted commercial channels.
- Defense Agencies:Multi-year framework agreements bundle hardware, software licenses, and sustainment services under single vendor relationships. Small specialty houses are losing direct bidding access to prime platforms.
- Law Enforcement:State and local agencies navigate fragmented counter-UAS authorization pathways, with FAA experimental licenses opening limited civilian-adjacent demand at critical infrastructure sites.
- Corporate Security:Financial institutions and critical infrastructure operators represent the addressable market should drone mitigation regulations expand beyond government channels.
- Private Users:Regulatory prohibitions in major markets relegate this segment to jurisdictions with weak spectrum enforcement.
Defense agencies dominate procurement value; law enforcement shows the steepest expansion trajectory as counter-UAS licenses proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Washington DC-Arlington-Alexandria corridor anchors signal jammer procurement through concentrated defense agency headquarters and federal prison system contracting offices. National security budgets flow through this cluster, directing technology requirements that cascade to manufacturing bases across multiple states.
United States
The Federal Bureau of Prisons maintains 122 facilities requiring managed access system upgrades, while the Department of Defense consolidates electronic warfare procurement under multi-year framework agreements. FCC marketing prohibitions under the Communications Act of 1934 criminalize civilian sales, channeling all legal demand through federal and state agencies exclusively.
United Kingdom
Ministry of Defence electronic warfare programs prioritize counter-IED and convoy protection systems for NATO collective defense frameworks. BAE Systems anchors domestic production through specialized military contracts, while national spectrum regulators enforce type-approval requirements under EU-derived radio equipment standards.
Germany
The Bundeswehr accelerates vehicle-mounted jammer procurement through NATO harmonization initiatives, with technical specifications designed for cross-border interoperability. KBA and federal network agency regulations constrain commercial availability while permitting licensed security and defense applications.
France
ANFR conducts enhanced post-market surveillance on jamming equipment sold to licensed security services, extending certification timelines for non-EU manufacturers. Thales Group leverages domestic defense relationships to capture prime platform integration contracts, with Paris-Saclay cluster hosting specialized RF engineering capabilities.
Israel
Contested electromagnetic environments drive cognitive jamming algorithm development, with defense procurement officers field-testing adaptive systems against frequency-hopping protocols. National security priorities concentrate RF engineering talent in Tel Aviv-Yafo and Haifa technology corridors, supporting specialized electronic attack subsystem exports.
Signal Jammer Market Key Industry Players
Channel compression dominates the current landscape as defense procurement officers consolidate annual contract volumes into multi-year framework agreements. Prime contractors capture larger program shares through subsystem bundling, squeezing small specialty houses from direct bidding access. Three archetypes define competitive positioning: integrated platform primes, software-defined radio specialists, and legacy analog component suppliers. M&A absorption and technology licensing represent the dominant competitive moves, with tier-one integrators acquiring subsystem capabilities rather than developing organically.
Among United States-based defense primes, L3Harris Technologies, Northrop Grumman Corporation, and Lockheed Martin exemplify the integrated platform archetype, occupying positions that bundle jamming modules with broader electronic attack architectures. These entities represent the consolidation endpoint where military procurement frameworks favor single-vendor relationships spanning hardware, software licenses, and sustainment services. European counterparts including Thales Group and BAE Systems occupy parallel positions within their respective national defense ecosystems, anchoring regional procurement through specialized counter-IED and convoy protection system relationships.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Thales Group |
| Raytheon Technologies Corporation |
| MCTECH Technology |
| HSS Development |
| Lockheed Martin |
| BAE Systems |
| SESP Group |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
Defense-prime-dominated vendor consolidation has compressed channel margins while concentrating pricing power among tier-one integrators bundling hardware, software licenses, and sustainment services under multi-year framework agreements. Sovereign-backed procurement officers leverage volume commitments to extract performance-tier discounts, forcing mid-tier contractors into subsystem licensing arrangements that erode direct margin capture.
Pricing Analysis
Distributor margins in authorized government channels run thin at 8-12 percent, with direct-to-agency contracts commanding 15-25 percent price premiums over foreign military sale equivalents. Three-tier pricing structure across military-grade, security-grade, and commercial-grade certification levels separates NATO-interoperable systems from national-only deployments. Cost compression in analog hardware tiers is intensifying because software-defined platforms are displacing legacy architectures from new program awards. Federal prison systems exhibit highest price sensitivity due to fixed appropriations cycles, while defense electronic warfare units prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese substrate manufacturers supplying gallium nitride wafers for high-electron-mobility transistor fabrication. Defense-qualified foundries in the United States, Germany, and Israel anchor final assembly, drawing from Japanese precision components and South Korean memory modules. Tariff exposure on rare-earth magnet feeds threatens power amplifier cost stability. Distribution runs through prime contractor logistics networks with security-cleared handling requirements, bypassing conventional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory authorization expansion, with FAA experimental licenses for drone mitigation jammers at critical infrastructure sites representing the most significant demand catalyst outside traditional military procurement.
For Market Incumbents: Deploy software-defined radio architecture roadmaps to capture NATO harmonization mandates for cross-border interoperability. Consolidate subsystem suppliers through selective technology licensing that absorbs FPGA design capabilities without organic R&D duplication. Counter emerging mid-tier defense contractors challenging established radio frequency specialists by embedding jamming modules into integrated electronic attack platforms that prime contractors alone can bid. For New Entrants and Emerging Players: Cognitive jamming algorithms trained on frequency-hopping protocol libraries offer the most penetrable wedge against established frequency specialists. Target state correctional authority managed access system upgrades where 122 federal facilities are replacing legacy cellular jammers, creating procurement windows for qualified new vendors. Pursue FAA experimental license partnerships with critical infrastructure operators as a go-to-market angle that bypasses direct defense prime competition. For Investors and Strategic Acquirers: Defense primes with electronic warfare portfolios are the most active acquirers in this space, absorbing FPGA specialists and cognitive algorithm developers into subsystem supply chains. Long-term viability hinges on sustained counter-UAS regulatory expansion and NATO collective defense procurement frameworks. Watch for EU-wide drone mitigation authorization harmonization by EASA as the inflection indicator signaling addressable market expansion beyond government-exclusive channels.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Enables real-time waveform adaptation across NATO-interoperable frequency bands. |
| Counter-UAS Regulatory Licensing | FAA experimental permits open civilian-adjacent demand at critical infrastructure sites. |
| Gallium Nitride Supply Diversification | Reduces exposure to Chinese substrate export controls through qualified alternative foundries. |
| Managed Access System Integration | Captures Federal Bureau of Prisons modernization cycles across 122 facilities. |
| Cognitive Jamming Algorithm Deployment | Automates frequency-hopping protocol countermeasures without operator intervention. |
Research Approach
Direct dialogue with defense procurement officers, prison system technology directors, RF engineering specialists, and spectrum regulatory officials grounded qualitative findings in operational constraints. Secondary validation drew from FCC enforcement orders, NATO standardization agreements, FAA experimental license databases, and EU Radio Equipment Directive technical documentation. Bottom-up facility counts and top-down defense budget allocations were triangulated to reconcile volume estimates.
Segment-level projections across product type, technology architecture, application context, and end-user category were generated through the analytical framework. CAGRs were derived from fitted growth curves calibrated to historical procurement cycles and authorization expansion trajectories. Software-defined radio adoption rates and counter-UAS regulatory milestone timing served as primary forecast sensitivity inputs across the projection horizon.
The model holds under sustained defense budget prioritization and incremental regulatory liberalization; deviation in Gallium Nitride supply disruption severity or NATO collective defense framework suspension would shift trajectory materially. Forecasts reflect documented assumptions about procurement consolidation patterns and technology substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Private Security Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Security Operations Center Market