
 Explosive Detection Technology Market | 2026-2036
Explosive Detection Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Detection Technology Market Insights
Semiconductor-based sensor materials are rebalancing cost-performance economics across trace detection platforms. Smiths Detection Group Ltd. leverages integrated manufacturing to sustain supply chain control over spectrometer components. Nuctech Company Limited anchors its position through dominant installed base across Asia-Pacific customs checkpoints. L3Harris Technologies Inc. differentiates via classified military channel access and hardened field architectures.
Explosive detection technology encompasses physicochemical systems engineered to identify threat compounds at parts-per-billion sensitivity thresholds, employing ion mobility drift cells, quadrupole mass filters, or Raman-shifted laser excitation to trigger alarm protocols. The primary purpose spans prevention of unauthorized explosive transport across aviation, border, and critical venue perimeters. Ion mobility spectrometry occupies the largest installed base due to decades of TSA certification and sub-ten-second alarm generation, while mass spectrometry captures expanding share in cargo inspection where molecular specificity reduces false positive rates. Handheld detectors represent the fastest-growing product category as battery-weight improvements and miniaturized pumps enable point-of-use screening by patrol officers.
The Transportation Security Administration mandates drive US procurement specifications for aviation checkpoint systems, while EASA implements parallel certification pathways across EU member states. India's Bureau of Indian Standards and CDSCO are developing indigenous testing protocols to reduce import dependency for defense and homeland security applications. Stakeholders must monitor convergence between AI-enabled threat libraries and evolving data governance frameworks that could restrict cross-border algorithm training datasets.
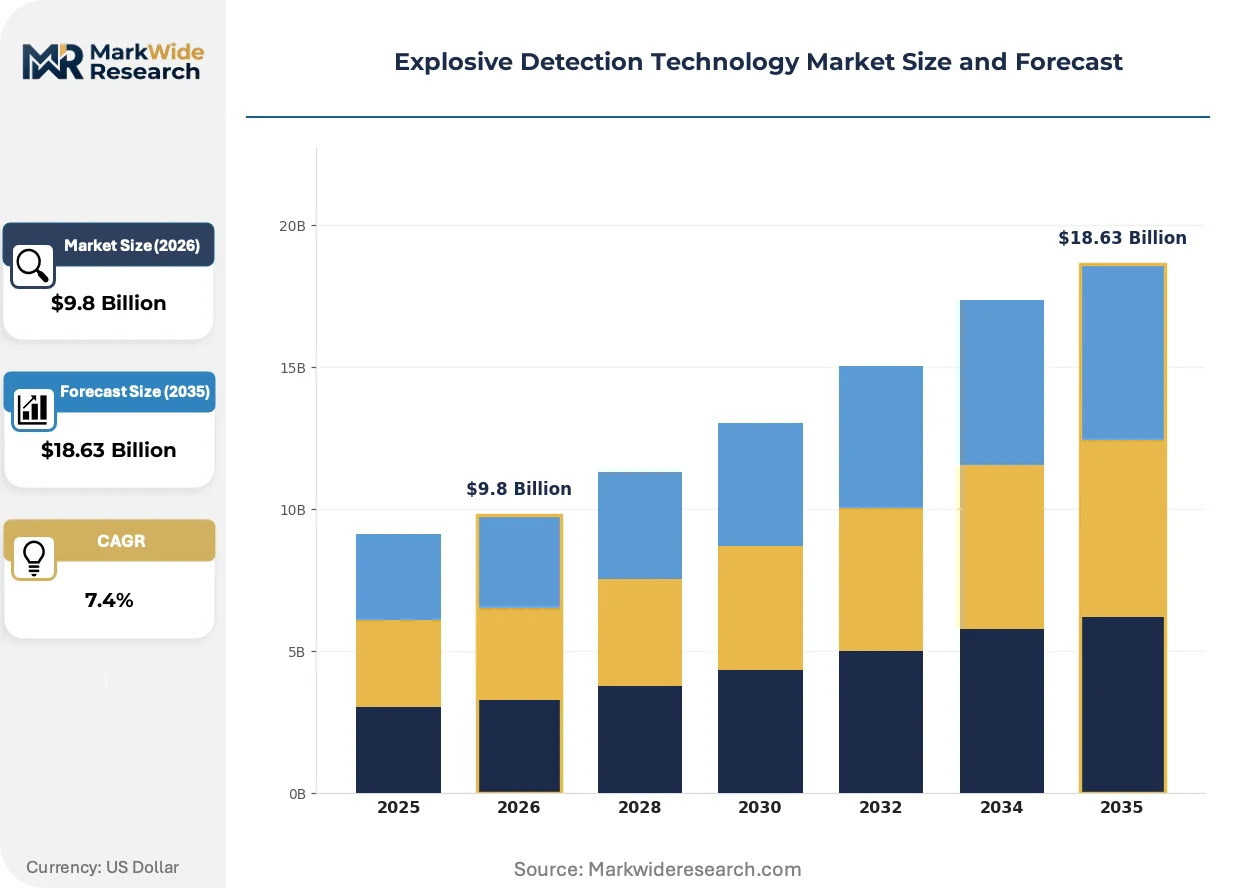
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing explosive detection system manufacturers to rearchitect threat recognition engines, stripping out opaque machine-learning layers that cannot explain alarm triggers to airport security auditors.
Growth Catalysts
- Aviation checkpoint mandates:The Transportation Security Administration's next-generation credentialing protocols require sub-five-second passenger throughput, compressing procurement cycles for dual-mode millimeter-wave and chemical trace portals.
- Critical infrastructure hardening:India's Bureau of Indian Standards is fast-tracking indigenous testing protocols for mass spectrometry cargo scanners, reducing import dependency for customs modernization at Mumbai and Chennai ports.
- Handheld battery chemistry advances:Solid-state lithium-sulfur cells are extending patrol officer screening duration from four to twelve hours without recharging, expanding point-of-use deployment across municipal police forces.
Market Restraints
- Helium-3 supply concentration:Neutron-based detection systems depend on radioactive isotope sourcing from aging US and Russian stockpiles, with no commercial reprocessing capacity coming online before 2030.
- Quadrupole mass filter fabrication:Precision-machined hyperbolic electrodes require Swiss and German specialty metalworking suppliers, creating single-source vulnerability for high-resolution cargo inspection systems.
- Ion mobility spectrometry specificity ceiling:Drift-cell platforms cannot resolve structural isomers of nitrogen-rich compounds, generating false positives that consume security personnel bandwidth at high-volume checkpoints.
Strategic Opportunities
- Autonomous drone-mounted screening:Raman-shifted laser systems paired with unmanned aerial platforms enable perimeter sweeps of stadium and pipeline infrastructure without ground crew exposure.
- EU Green Deal procurement incentives:Member state customs authorities receive carbon-accounting preference points for detectors with recyclable sensor substrates and reduced rare-earth magnet content.
- Cross-modal threat libraries:Convergence of explosive, narcotic, and radiological signature databases into unified detection algorithms creates upsell pathways for installed-base upgrades.
Industry Challenges
- Spectroscopy technician scarcity:Mass spectrometry maintenance requires vacuum-system and RF electronics expertise that vocational programs in India and Southeast Asia have not scaled to match deployment rates.
- Legacy IMS certification lock-in:Airport operators face sunk-cost resistance when migrating from TSA-certified ion mobility platforms to molecular-specific alternatives, even where false-positive economics favor replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Detection Technology Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.63 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mass Spectrometry, Ion Mobility Spectrometry, Raman Spectroscopy, X-ray Diffraction, Infrared Spectroscopy, Nuclear Quadruple Resonance Application: Airport Security, Border Protection, Event Security, Cargo Inspection, Military Screening, Venue Access Control Product Type: Handheld Detectors, Portable Analyzers, Fixed Systems, Vehicle-Mounted Detectors, Conveyor Belt Scanners, Drone-Mounted Sensors End User: Law Enforcement Agencies, Homeland Security, Customs Authorities, Military Forces, Private Security Firms, Transportation Operators |
| Companies Covered | Bruker Corporation, Teledyne Technologies Incorporated, Smiths Detection Group Ltd., Nuctech Company Limited, Rapiscan Systems Inc., L3Harris Technologies Inc., OSI Systems Inc., Chemring Group PLC, Leidos Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Detection Technology Market Trends and Innovations
Sensor fusion architectures are collapsing the distinction between trace chemical detection and bulk imaging, enabling single-passenger screening that previously required sequential queueing through separate machines.
Semiconductor-based metal-oxide chemiresistor arrays are decentralizing explosive trace detection from centralized laboratory-grade mass spectrometers to battery-powered field units. Customs patrol divisions in Germany and India are deploying these platforms for container-yard spot checks. The shift is compressing the addressable market for benchtop analysis systems while expanding serviceable detection points by an order of magnitude.
The EU AI Act's explainability requirements are mandating algorithmic audit trails for threat classification decisions. Airport operators in France and Germany must now demonstrate that detection neural networks can output human-interpretable feature maps for each alarm. Manufacturers are responding by hybridizing deep learning with rule-based spectral matching that preserves traceable decision paths.
Security procurement officers are unbundling hardware acquisition from maintenance and calibration contracts, treating detection systems as consumable infrastructure rather than capital assets. This preference is displacing traditional ten-year service agreements in favor of per-passenger or per-alarm pricing models. The pattern is most pronounced in US municipal transit authority budgets, where operating-expense flexibility outweighs capital-commitment capacity.
Explosive Detection Technology Market Segmentation
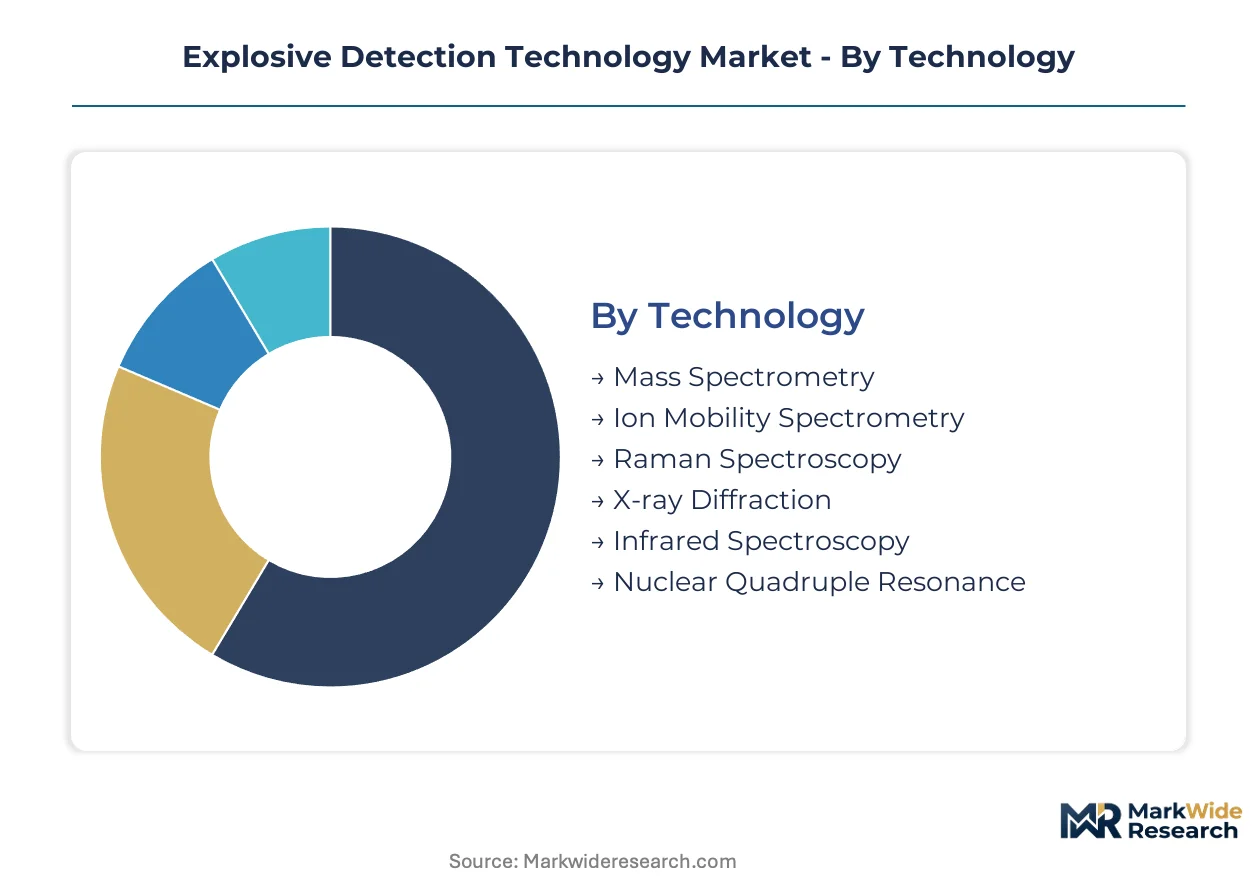
Technology selection in explosive detection hinges on the trade-off between molecular specificity and operational throughput. Procurement patterns diver sharply between aviation checkpoints demanding sub-ten-second alarm generation and cargo terminals prioritizing false-positive reduction over speed.
Technology:
Ion mobility spectrometry commands the volume tier through decades of TSA certification, while mass spectrometry captures the premium tier where molecular resolution justifies higher capital outlay.
- Mass Spectrometry:Quadrupole and time-of-flight configurations resolve nitrogen-rich isomers at parts-per-billion thresholds. Demand concentrates in German and Indian customs modernization programs where false-positive economics favor replacement of drift-cell platforms despite higher unit costs.
- Ion Mobility Spectrometry:Drift-cell architectures dominate installed base through sub-ten-second alarm generation and battery-powered portability. US aviation checkpoint mandates sustain procurement volume despite specificity limitations that generate personnel bandwidth costs at high-throughput terminals.
- Raman Spectroscopy:Shifted-laser excitation enables non-contact identification through sealed containers. German customs patrol divisions deploy handheld units for container-yard spot checks.
- X-ray Diffraction:Crystallographic analysis distinguishes explosive fillers from benign organics with similar elemental signatures. Military screening applications in India leverage this capability for bulk cargo assessment.
- Infrared Spectroscopy:Fourier-transform platforms provide fingerprint region identification at reduced capital cost compared to mass spectrometry. Fixed installations at US critical infrastructure perimeters favor this technology.
- Nuclear Quadruple Resonance:Radio-frequency excitation detects nitrogen-14 signatures without radiation sources. Helium-3 supply constraints limit neutron-based alternatives, expanding addressable market for this modality.
Mature deployment sits with Ion Mobility Spectrometry. Newer deployment is concentrated in Mass Spectrometry.
Application:
Aviation checkpoints generate the highest procurement velocity through regulatory mandate density, while cargo inspection commands longer sales cycles with larger contract values per installation.
- Airport Security:TSA next-generation credentialing protocols compress procurement cycles for dual-mode millimeter-wave and chemical trace portals. US terminal operators face sunk-cost resistance when migrating from certified ion mobility platforms.
- Border Protection:India's Bureau of Indian Standards fast-tracks indigenous testing protocols for mass spectrometry cargo scanners at Mumbai and Chennai ports, reducing import dependency.
- Event Security:Temporary perimeter deployments favor battery-weight improvements in handheld detectors. Municipal police forces extend patrol duration through solid-state lithium-sulfur chemistry.
- Cargo Inspection:Molecular specificity requirements drive quadrupole mass filter adoption where structural isomer resolution reduces false-positive rates.
- Military Screening:Hardened field architectures and classified channel access differentiate procurement specifications from civilian counterparts.
- Venue Access Control:Point-of-use screening by private security firms expands addressable detection points through semiconductor-based chemiresistor arrays.
Procurement volume clusters in Airport Security. Steepest expansion trajectory appears in Cargo Inspection as molecular specificity economics improve.
Product Type:
Fixed systems anchor revenue concentration through decade-long service agreements, while handheld form factors are climbing the fastest as battery chemistry and miniaturized pumps enable decentralized deployment.
- Handheld Detectors:Solid-state lithium-sulfur cells extend patrol officer screening duration from four to twelve hours without recharging. German and Indian customs divisions deploy these for container-yard spot checks.
- Fixed Systems:Centralized checkpoint architectures sustain installed-base revenue through calibration and maintenance contracts. US aviation terminals represent the densest concentration.
- Portable Analyzers:Benchtop mass spectrometry units serve laboratory-grade confirmation roles at customs facilities requiring vacuum-system expertise.
- Vehicle-Mounted Detectors:Mobile screening platforms enable perimeter sweeps of pipeline and stadium infrastructure without fixed infrastructure investment.
- Conveyor Belt Scanners:Integration into baggage handling systems demands sub-five-second passenger throughput compliance with TSA protocols.
- Drone-Mounted Sensors:Raman-shifted laser systems paired with unmanned aerial platforms enable ground-crew-risk reduction in hazardous zone assessment.
Revenue concentration remains with Fixed Systems. Gaining share fastest are Handheld Detectors through point-of-use expansion.
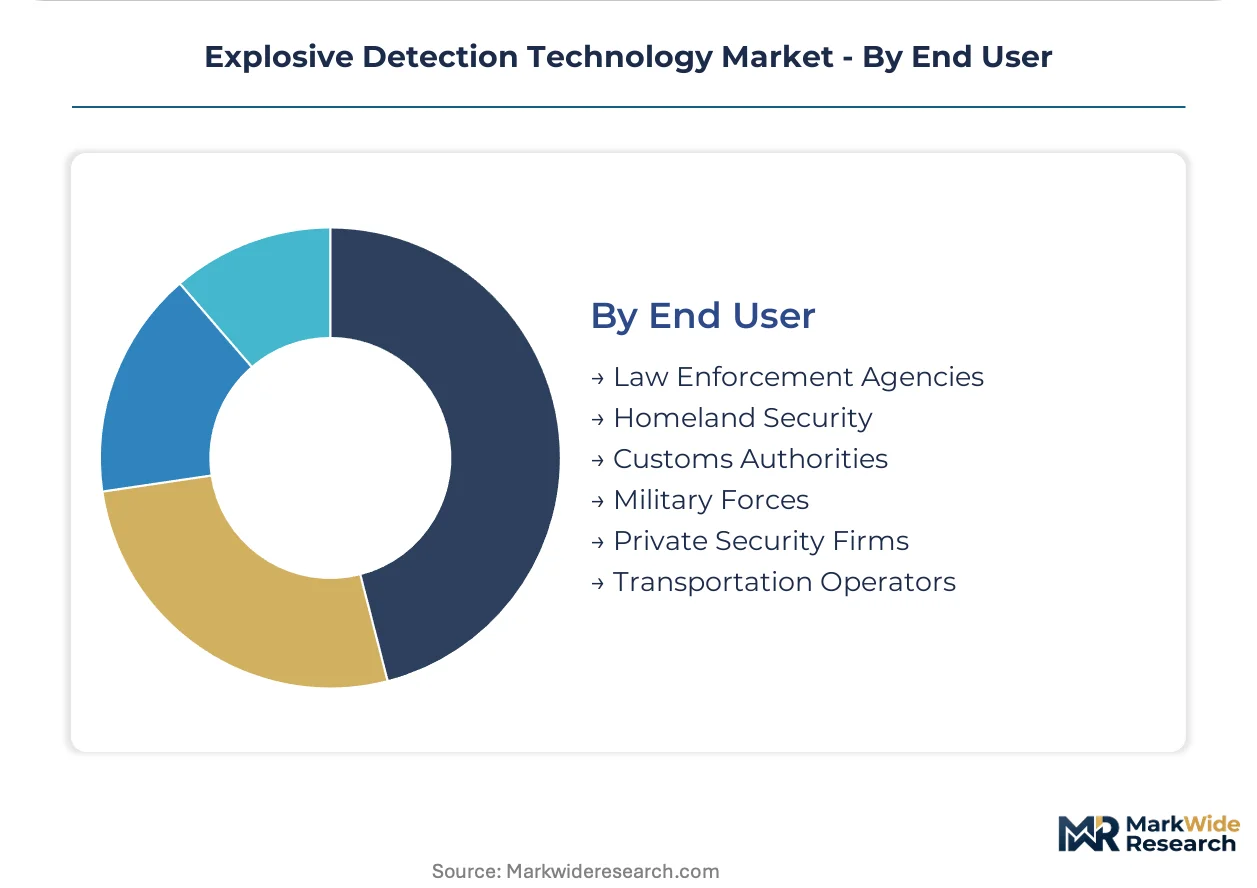
End User:
Homeland security agencies command the premium tier through classified procurement channels, while private security firms represent the volume growth tier as detection systems become consumable infrastructure.
- Homeland Security:Classified military channel access and hardened field architectures differentiate procurement specifications. US and Indian agencies drive indigenous testing protocol development.
- Private Security Firms:Unbundling of hardware acquisition from maintenance contracts enables per-passenger or per-alarm pricing models. US municipal transit authorities favor operating-expense flexibility.
- Law Enforcement Agencies:Patrol officer deployment of handheld units expands through battery-weight improvements and solid-state chemistry advances.
- Customs Authorities:EU Green Deal procurement incentives reward carbon-accounting preference points for detectors with recyclable sensor substrates.
- Military Forces:Field-hardened architectures and autonomous drone-mounted screening requirements diverge from civilian specifications.
- Transportation Operators:Aviation and rail terminals face TSA mandate compliance for sub-five-second passenger throughput.
Contract value concentration sits with Homeland Security. Procurement velocity is expanding most quickly in Private Security Firms through consumption-based pricing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and India as these nations modernize critical infrastructure protection. Aviation checkpoint mandates and customs modernization programs drive procurement velocity across distinct regulatory environments. Each geography presents unique certification pathways and supply chain configurations.
United States
The Transportation Security Administration mandates next-generation credentialing protocols requiring sub-five-second passenger throughput. TSA certification pathways sustain ion mobility spectrometry procurement despite specificity limitations. Terminal operators at Atlanta Hartsfield-Jackson and Dallas-Fort Worth face sunk-cost resistance when migrating to molecular-specific alternatives.
Germany
EU AI Act algorithmic transparency requirements force manufacturers to rearchitect threat recognition engines for airport security auditors. German customs patrol divisions deploy handheld Raman units for container-yard spot checks at Hamburg and Bremerhaven ports. EASA certification parallels create procurement specification overlap with member state authorities.
India
The Bureau of Indian Standards fast-tracks indigenous testing protocols for mass spectrometry cargo scanners at Mumbai and Chennai ports. CDSCO regulatory development aims to reduce import dependency for defense and homeland security applications. Domestic manufacturing incentives accelerate local production of semiconductor-based chemiresistor arrays.
United Kingdom
Aviation security operators at Heathrow and Gatwick implement dual-mode millimeter-wave and chemical trace portals under CAA oversight. Post-Brexit regulatory divergence creates parallel certification maintenance costs for equipment suppliers. British military screening requirements sustain demand for hardened field architectures distinct from civilian specifications.
Japan
METI industrial security guidelines shape procurement specifications for critical venue protection ahead of international event hosting. Japanese customs authorities prioritize false-positive reduction in cargo terminals over checkpoint speed metrics. Osaka and Tokyo aviation hubs represent concentrated installed-base upgrade opportunities.
Explosive Detection Technology Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system architects commanding premium positioning in aviation checkpoints while component suppliers capture volume in handheld deployment. The vendor base clusters around three strategic archetypes: diversified defense conglomerates with classified channel access, detection-focused specialists with TSA certification heritage, and emerging Asian fabricators leveraging cost-position in customs modernization markets. Consolidation pressure operates through technology licensing arrangements rather than outright acquisition, as regulatory certification portfolios prove more defensible than manufacturing scale.
Within the diversified defense tier, L3Harris Technologies Inc. and Leidos Holdings Inc. occupy positions shaped by military procurement relationships and hardened field architecture requirements. Smiths Detection Group Ltd. and Nuctech Company Limited exemplify the detection-specialist archetype, with the former representing European certification heritage and the latter anchoring Asia-Pacific customs installed base expansion. Bruker Corporation sits within the analytical instrumentation tier, translating laboratory-grade mass spectrometry expertise into security applications.
| Leading Market Players |
|---|
| Bruker Corporation |
| Teledyne Technologies Incorporated |
| Smiths Detection Group Ltd. |
| Nuctech Company Limited |
| Rapiscan Systems Inc. |
| L3Harris Technologies Inc. |
| OSI Systems Inc. |
| Chemring Group PLC |
| Leidos Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Helium-3 isotope sourcing from aging US and Russian stockpiles feeds directly into neutron-based detection system pricing tiers, with procurement officers facing tiered cost structures that separate premium military-grade platforms from civilian checkpoint alternatives.
Pricing Analysis
Volume procurement of ion mobility spectrometry platforms sustains thin margins at aviation checkpoints, while mass spectrometry cargo scanners command premium positioning through molecular specificity certification. Three-tier pricing structure across premium, standard, and economy levels separates TSA-certified legacy systems from next-generation dual-mode portals and handheld field units. Pricing pressure stems from unbundling of hardware acquisition from maintenance contracts, with US municipal transit authorities favoring per-passenger consumption models over capital commitments. Private security firms exhibit highest price sensitivity, while homeland security agencies absorb premium tiers through classified procurement channels.
Supply Chain Analysis
Refurbishment flows for precision-machined quadrupole mass filter electrodes create secondary supply channels that extend component lifecycles beyond original equipment specifications. Swiss and German specialty metalworking suppliers anchor upstream fabrication for hyperbolic electrodes, while semiconductor-based sensor materials draw from Taiwan and South Korea fabrication facilities. Solid-state lithium-sulfur cell chemistry for handheld units rests on South Korean battery manufacturing capacity. Single-source vulnerability concentrates in Swiss electrode machining, with no qualified alternative suppliers for high-resolution cargo inspection systems. Distribution runs through certified integrators who maintain TSA and EASA compliance documentation for airport operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory certification portfolios are forcing consolidation as smaller fabricators lack capital to sustain parallel TSA, EASA, and BIS compliance pathways, eliminating marginal players from aviation and customs procurement cycles.
For Market Incumbents: Lock in certification heritage advantages by accelerating indigenous testing protocol partnerships with India's BIS and CDSCO, while backward integration into spectrometer component manufacturing neutralizes Swiss electrode supply vulnerability. Threat of emerging Asian fabricators in customs modernization markets demands channel control through localized service networks. For New Entrants and Emerging Players: EU AI Act algorithmic transparency mandates in Germany and France open a window for explainable AI-native detection platforms that bypass legacy neural network rearchitecture costs. White-space targets concentrate in autonomous drone-mounted screening for pipeline perimeter applications and semiconductor-based chemiresistor arrays for municipal police deployment. Go-to-market through per-alarm pricing partnerships with US private security firms bypasses incumbent service contract lock-in. For Investors and Strategic Acquirers: TSA next-generation credentialing protocol procurement acceleration is the leading indicator that dual-mode portal demand will concentrate share among integrated system architects. Five-to-ten year viability favors acquisition of detection-focused specialists with certification heritage rather than diversified defense conglomerates where security applications compete for capital allocation. Signal to monitor: BIS indigenous testing protocol approvals for mass spectrometry cargo scanners at Mumbai and Chennai ports.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Parallel TSA, EASA, and BIS pathway investment secures aviation and customs procurement access. |
| Backward Integration into Spectrometer Components | In-house electrode machining reduces Swiss supplier dependency for high-resolution cargo systems. |
| AI-Native Platform Development | Explainable algorithm architectures preempt EU AI Act compliance costs for airport operators. |
| Per-Alarm Pricing Model Deployment | Consumption-based contracts unlock US municipal transit authority budgets beyond capital commitment capacity. |
| Indigenous Testing Protocol Partnership | BIS and CDSCO collaboration positions suppliers for India's customs modernization program awards. |
Research Methodology
Independent corroboration across airport security procurement officers, customs technology directors, and semiconductor sensor manufacturers underwrites the qualitative findings, validated against TSA procurement databases, EASA certification registries, BIS technical standards filings, and customs modernization program announcements. Bottom-up triangulation of installed-base counts with top-down market sizing from defense and homeland security budget disclosures anchors volume estimates.
Rate-of-change decomposition across technology modality, application segment, product form factor, and end-user archetype structures the analytical framework over the projection horizon. CAGRs derive from segment-level demand elasticity modeling against regulatory mandate timelines and procurement cycle compression patterns. Forecast inputs incorporate solid-state battery chemistry advancement curves and AI algorithm training dataset governance evolution.
Caveats apply where helium-3 supply disruption, EU AI Act enforcement variance, or indigenous testing protocol delays could materially shift the outlook. Practitioners should monitor BIS mass spectrometry scanner approvals, lithium-sulfur cell manufacturing scale-up, and EASA algorithmic audit trail specifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Security Services Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Seaport Security Management Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Europe Security Testing Market