
 Virtual Reality (VR) in Healthcare Market | 2026-2036
Virtual Reality (VR) in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality (VR) in Healthcare Market Intelligence
EU MDR is pivoting the cost-of-entry calculus for VR surgical platforms by demanding clinical evidence thresholds that smaller developers struggle to fund. AppliedVR sustains its lead in prescription digital therapeutics through FDA De Novo clearances for chronic pain. Osso VR dominates orthopedic surgical simulation with proprietary haptic-enabled training modules. XRHealth navigates European reimbursement complexity by partnering with statutory health insurers in Germany and Israel.
Virtual Reality in Healthcare encompasses fully immersive computer-generated environments delivered through head-mounted displays with sub-20ms motion-to-photon latency, designed to simulate anatomical structures, therapeutic scenarios, or surgical procedures for clinical training, patient treatment, and rehabilitation. Hardware captures the dominant revenue share as institutional procurement of enterprise-grade headsets with integrated eye tracking and hand controllers outpaces software licensing in absolute dollar terms. Surgical training applications generate the fastest expansion as residency programs replace cadaveric labs with repeatable virtual procedures, while pain management retains mature reimbursement codes that stabilize near-term revenue.
FDA, EU MDR, and ISO 13485 collectively govern product safety, clinical validation, and quality management for VR healthcare devices, with FDA's 510(k) and De Novo pathways determining US market access timelines and EU MDR's post-market surveillance requirements extending compliance costs. Health Canada and Japan's PMDA add parallel clearance layers for North American and Asian commercialization. Stakeholders must monitor evolving digital therapeutics reimbursement decisions by CMS and Germany's BfArM, as these determinations will separate reimbursable prescription platforms from discretionary wellness applications.
Market Dynamics
FDA De Novo clearance pathways for prescription digital therapeutics are compressing development timelines while EU MDR clinical evidence demands simultaneously raise capital barriers, creating divergent market access conditions across Atlantic markets.
Growth Catalysts
- VA Hospital Procurement Mandates:United States veterans affairs facilities anchor institutional demand through centralized purchasing of surgical simulation platforms for risk-free procedural rehearsal.
- ISO 13485 Quality Management:Standardized quality frameworks reduce regulatory friction for hardware-software integrated devices entering multi-jurisdictional markets.
- Haptic Feedback Integration:Tactile-enabled training modules replicate tissue resistance and instrument feedback, accelerating adoption in orthopedic and neurosurgical residency programs.
Market Restraints
- Enterprise Headset Cost Concentration:Eye-tracking and hand-controller integration in institutional-grade hardware inflates per-unit procurement costs beyond community hospital budgets.
- EU MDR Post-Market Surveillance:Extended clinical follow-up obligations and notified body capacity constraints delay European commercialization for smaller developers.
- Motion Sickness Physiological Limits:Sub-20ms motion-to-photon latency requirements remain technically demanding, excluding certain patient populations from therapeutic applications.
Strategic Opportunities
- German Statutory Reimbursement Partnerships:BfArM digital therapeutics decisions create precedent for prescription VR coverage across European statutory health insurance networks.
- AI-Generated Anatomical Modeling:Machine learning synthesis of patient-specific imaging into procedural simulations converges with cloud-rendered streaming delivery.
- Remote Rehabilitation Channels:Home-based therapeutic deployment through telehealth-integrated headsets bypasses facility capacity constraints in rural and post-acute settings.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Cross-functional expertise spanning clinical workflow design, sensor hardware, and software validation remains concentrated in academic medical centers.
- Multi-Jurisdictional Clearance Sequencing:FDA 510(k) and De Novo pathway timing misalignment with Health Canada and Japan PMDA parallel reviews extends commercialization cadence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality (VR) in Healthcare Market |
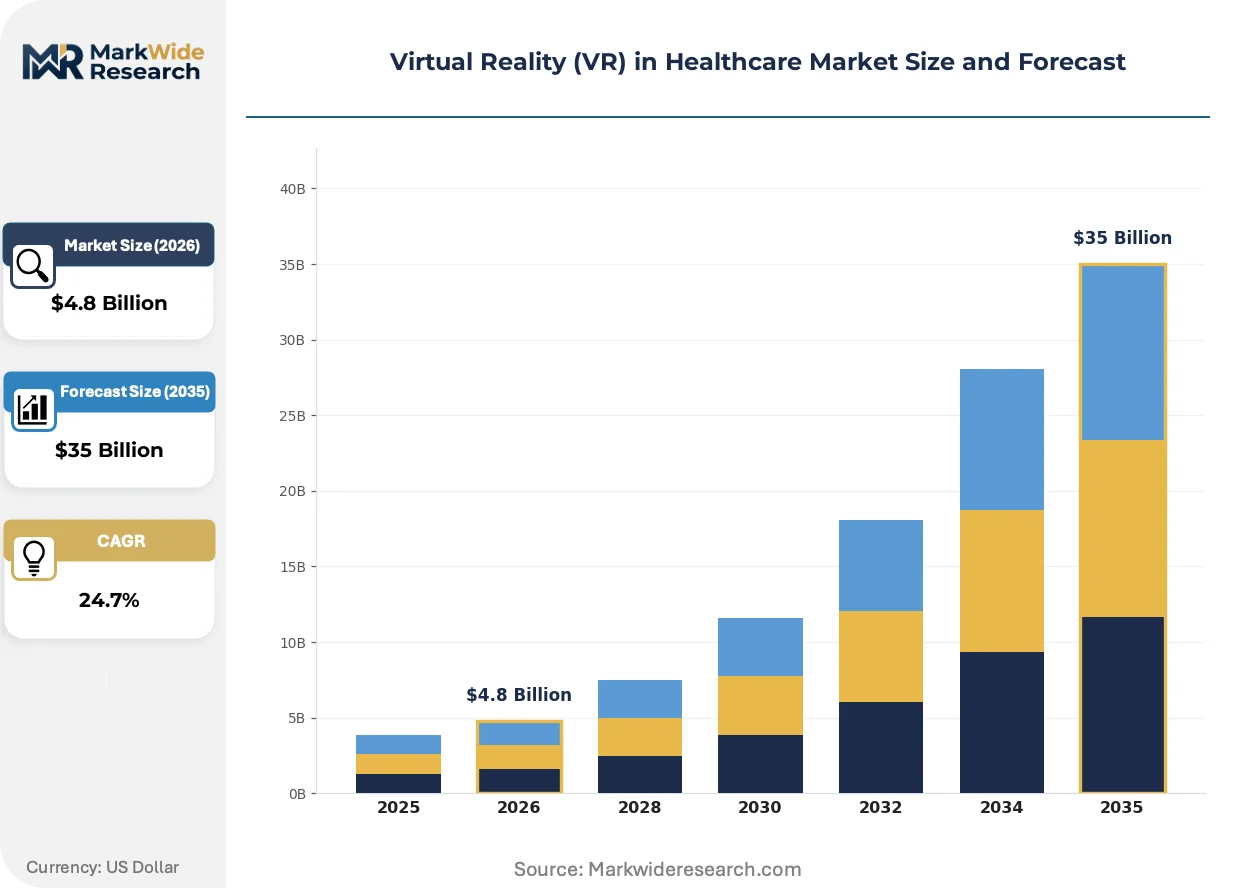
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Services End User: Hospitals, Rehabilitation Centers, Clinics, Medical Schools Application: Surgical Training, Pain Management, Phobia Treatment, Fitness Technology: Motion Tracking, 360-Degree Video, Haptic Feedback, Augmented Reality |
| Companies Covered | SimX, Virti, AppliedVR, Vicarious Surgical, ORamaVR, XRHealth, MyndVR, Proximie, Osso VR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality (VR) in Healthcare Market Strategic Shifts & Innovations
Cloud-rendered procedural streaming is compressing hardware requirements while regulatory divergence between FDA digital health guidance and EU MDR evidence thresholds is fragmenting development strategies across developer tiers.
Standalone wireless headsets with integrated eye tracking is overtaking tethered PC-dependent systems in surgical training environments. Residency programs at academic medical centers adopt these platforms for repeatable virtual procedures without dedicated simulation labs. This technology is overtaking cadaveric specimen procurement as the primary rehearsal modality, reducing per-procedure training costs and enabling unlimited repetition cycles.
EU MDR's post-market clinical follow-up requirements are extending compliance timelines for immersive therapeutic devices. Smaller developers face capital constraints funding multi-year surveillance studies demanded by notified bodies. Surgical simulation platforms with established ISO 13485 quality systems are responding through strategic partnerships with contract research organizations to distribute evidence generation costs.
Subscription-based software licensing is displacing perpetual hardware-software bundled sales in institutional procurement. Medical schools and hospital networks negotiate enterprise access to content libraries rather than single-module purchases. This shift is most visible in United States academic medical centers, where procurement committees prioritize scalable curriculum integration over capital equipment depreciation schedules.
Virtual Reality (VR) in Healthcare Market Segmentation
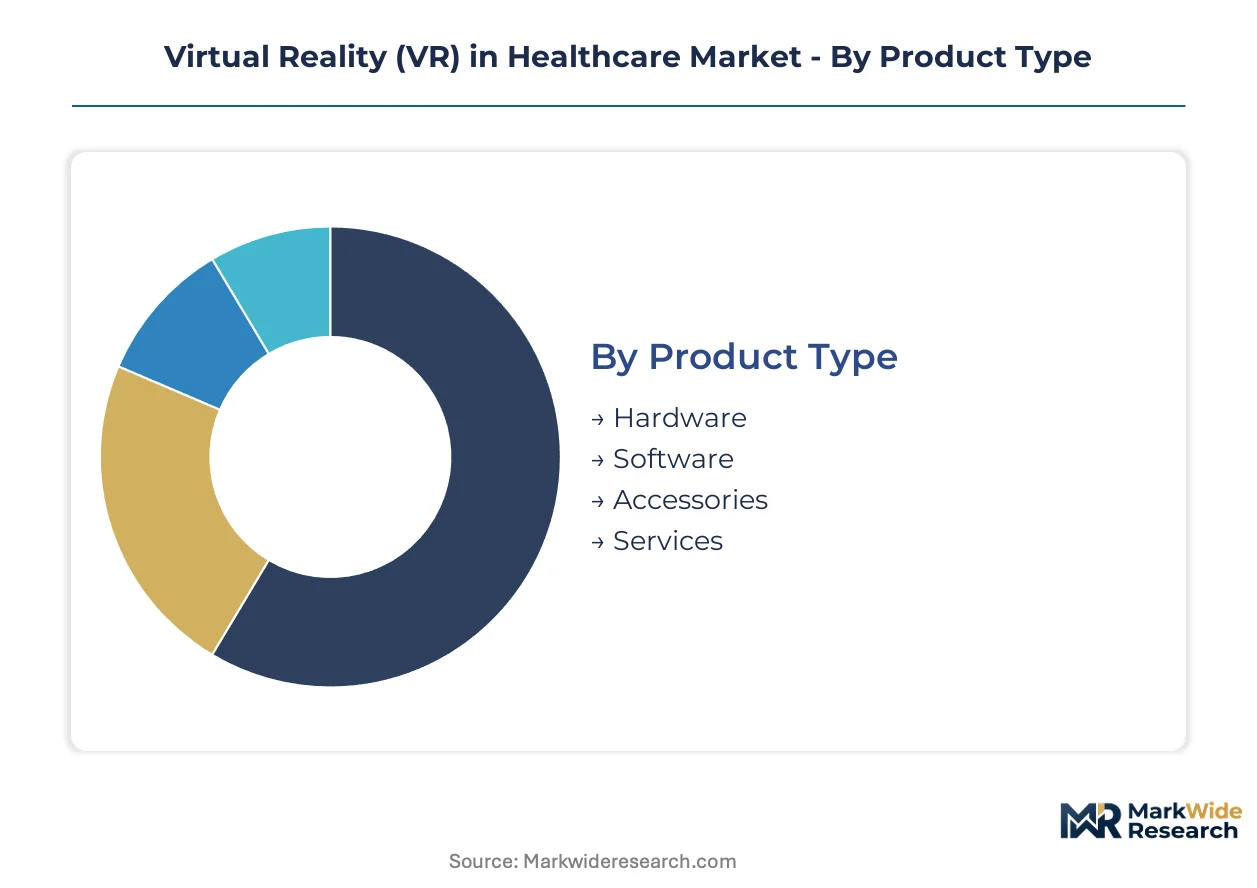
Segmentation in VR healthcare reveals distinct procurement patterns between standalone hardware deployments and integrated system architectures. Understanding where each segment sits on this integration spectrum clarifies why surgical training commands premium hardware budgets while pain management scales through software subscriptions.
Product Type:
Hardware dominates institutional procurement through enterprise-grade headsets with embedded eye tracking and hand controllers, while software layers increasingly detach from hardware bundles through cloud-rendered delivery models.
- Hardware:Enterprise headsets with sub-20ms motion-to-photon latency and integrated biometric sensors anchor capital budgets at academic medical centers and VA hospitals. United States procurement concentrates here as facilities replace cadaveric labs with repeatable virtual environments.
- Software:Cloud-native procedural platforms and AI-generated anatomical modeling tools are displacing perpetual licenses with subscription access. German statutory health insurers now reimburse prescription digital therapeutic software, validating this segment's clinical legitimacy.
- Accessories:Haptic gloves and force-feedback instruments extend hardware utility in orthopedic simulation.
- Services:Implementation consulting and curriculum integration support medical school adoption timelines.
Volume placements concentrate in Hardware; the faster expansion belongs to Software.
End User:
Customer type determines integration depth—hospitals demand full-stack systems while medical schools prioritize scalable content libraries over capital equipment ownership.
- Hospitals:Surgical departments at United States academic medical centers procure tethered and wireless systems for resident rehearsal, with procurement committees favoring ISO 13485-certified platforms that satisfy FDA quality system requirements.
- Medical Schools:Curriculum-integrated simulation programs across United States residency networks are replacing cadaveric specimen procurement with unlimited virtual repetition cycles.
- Rehabilitation Centers:Post-acute facilities deploy home-based therapeutic headsets through telehealth-integrated channels.
- Clinics:Outpatient pain management practices access prescription VR through CMS-reimbursed digital therapeutic pathways.
Procurement volume clusters at Hospitals; Medical Schools are climbing the fastest.
Application:
Clinical use case dictates hardware specification intensity—surgical rehearsal demands haptic precision while phobia treatment runs on consumer-grade mobility.
- Surgical Training:Orthopedic and neurosurgical residency programs at United States academic medical centers adopt haptic-enabled modules that replicate tissue resistance and instrument feedback, displacing cadaveric labs as the primary rehearsal modality.
- Pain Management:FDA De Novo-cleared prescription digital therapeutics for chronic pain retain mature reimbursement codes that stabilize near-term revenue, with AppliedVR sustaining category leadership through regulatory clearance.
- Phobia Treatment:Exposure therapy protocols leverage 360-degree environments for anxiety disorder intervention.
- Fitness:Rehabilitation-focused movement applications serve post-acute and home-based recovery settings.
Revenue concentration sits with Surgical Training; Pain Management holds the steepest expansion trajectory.
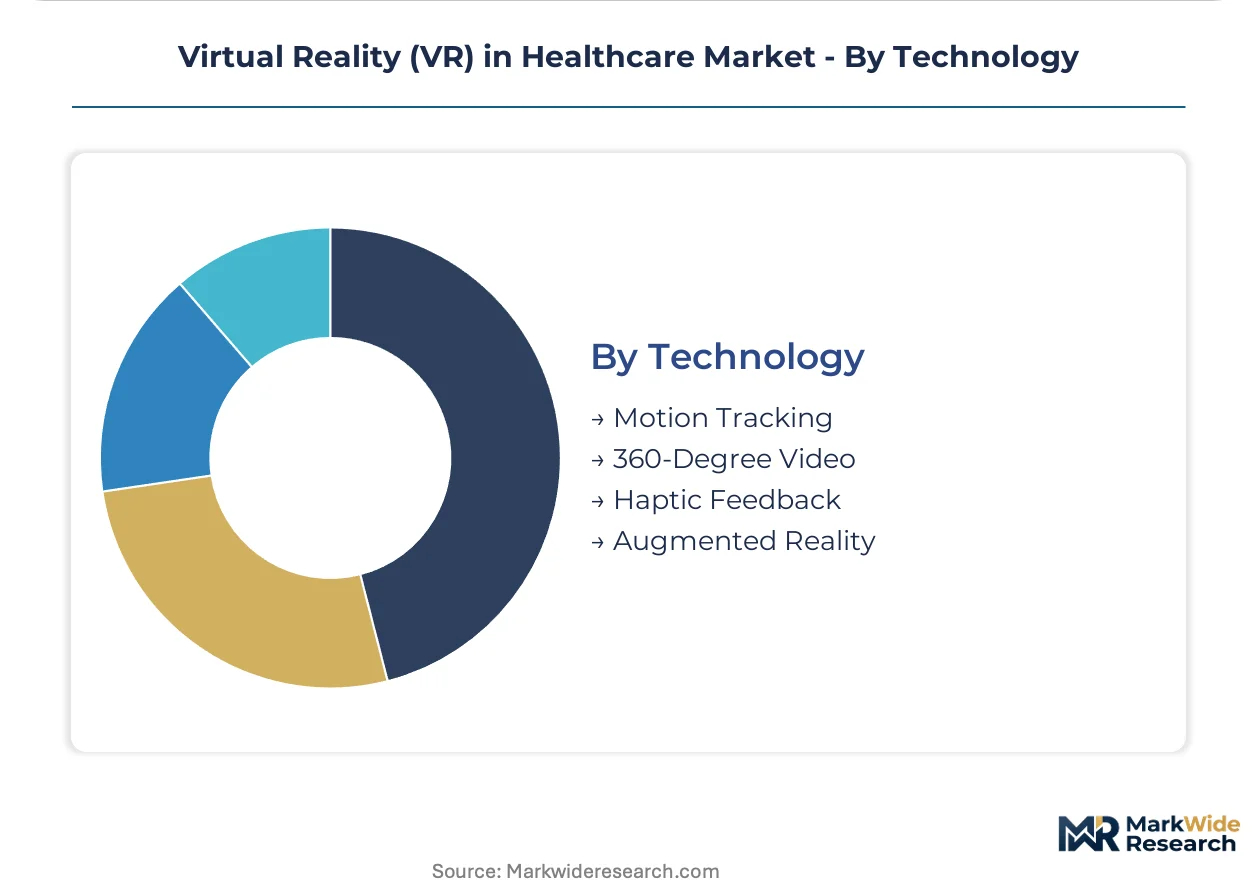
Technology:
Technical architecture separates embedded systems requiring facility infrastructure from portable modalities enabling remote deployment.
- Haptic Feedback:Force-resistance systems replicate surgical instrument interaction with anatomical structures, commanding premium integration costs at orthopedic training programs. United States residency adoption concentrates here as programs prioritize tactile fidelity over visual immersion alone.
- Motion Tracking:Sub-20ms latency hand and eye tracking enables precise procedural metrics for skill assessment. FDA-cleared platforms at VA hospitals leverage this capability for standardized competency evaluation.
- 360-Degree Video:Cinematic capture supports exposure therapy and environmental familiarization at lower hardware cost tiers.
- Augmented Reality:Overlay systems blend physical and virtual elements for intraoperative guidance applications.
Adoption depth peaks with Haptic Feedback; Motion Tracking is gaining share fastest through regulatory validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in the United States concentrate VR healthcare investment through capital gains tax deferrals, while Germany's MedTech clusters leverage BfArM digital therapeutics pathways to anchor European expansion.
United States
VA hospitals anchor procurement volumes through centralized purchasing mandates for surgical simulation platforms. FDA De Novo clearance pathways for prescription digital therapeutics compress development timelines for developers targeting chronic pain applications. Academic medical centers in Boston and the San Francisco Bay Area replace cadaveric labs with haptic-enabled training modules.
Germany
Bavarian medical device clusters drive hardware manufacturing for enterprise-grade headsets with integrated eye tracking. BfArM reimbursement decisions for prescription digital therapeutics validate software-based therapeutic platforms for statutory health insurance coverage. Berlin-based developers partner with statutory insurers to navigate European reimbursement complexity.
United Kingdom
NHS England innovation accelerators channel procurement toward ISO 13485-certified surgical training platforms. MHRA convergence with FDA digital health guidance streamlines parallel clearance for immersive therapeutic devices. London and Oxford medical school networks adopt subscription-based software licensing over perpetual hardware purchases.
Japan
PMDA medical device review pathways govern market access for VR surgical platforms with haptic feedback integration. METI funding programs support telehealth-integrated rehabilitation headsets for rural post-acute deployment. Osaka-based residency programs pilot wireless standalone systems for orthopedic procedural rehearsal.
Israel
Sheba Medical Center and Hadassah University Hospital anchor clinical validation studies for FDA-bound digital therapeutics. Ministry of Health reimbursement pilot programs cover prescription VR for chronic pain and phobia treatment. Tel Aviv's digital health cluster concentrates venture funding for AI-generated anatomical modeling tools.
Virtual Reality (VR) in Healthcare Market Key Industry Players
United States developers anchor the prescription digital therapeutics tier; European specialists hold regulatory navigation capabilities for multi-jurisdictional clearance. Market structure concentrates around three strategic archetypes: FDA De Novo pathway specialists, ISO 13485-certified surgical simulation providers, and telehealth-integrated rehabilitation platform operators. Dominant competitive moves include strategic partnerships with academic medical centers for clinical evidence generation and cloud-rendered delivery model adoption to reduce hardware dependency.
Among United States-based developers, AppliedVR and Osso VR occupy distinct archetype positions—AppliedVR exemplifies the prescription digital therapeutics pathway through FDA De Novo clearances, while Osso VR anchors the surgical simulation tier with haptic-enabled training module specialization. XRHealth represents the European regulatory navigation archetype through BfArM partnership structures in Germany and Israel.
| Leading Market Players |
|---|
| SimX |
| Virti |
| AppliedVR |
| Vicarious Surgical |
| ORamaVR |
| XRHealth |
| MyndVR |
| Proximie |
| Osso VR |
| Others |
Cost & Logistics Intelligence
Eye-tracking sensor arrays and haptic feedback actuators feed through three distinct pricing tiers as institutional procurement committees weigh latency specifications against curriculum integration budgets. Component costs for sub-20ms motion-to-photon hardware concentrate procurement power at United States academic medical centers and VA hospital networks.
Pricing Analysis
Lead-time compression commands premium positioning as German statutory health insurers demand ISO 13485-certified platforms with accelerated deployment timelines. Pricing stratifies across FDA De Novo-cleared prescription tiers, CE-marked surgical simulation bundles, and non-certified wellness applications. Cost compression in hardware-software integrated systems intensifies as cloud-rendered delivery models reduce capital equipment dependency. Medical schools exhibit highest price sensitivity through subscription licensing negotiations, while VA hospitals absorb premium hardware costs through centralized procurement mandates.
Supply Chain Analysis
Refurbishment flows for enterprise-grade headsets create secondary market channels as academic medical centers cycle hardware through residency program rotations. Manufacturing concentrates in China for display panels and sensor assemblies, Taiwan for semiconductor components, and Germany for precision haptic instrumentation. Supply chains draw from rare earth elements for magnet systems, specialized optical polymers for lens arrays, and medical-grade silicones for facial interface materials. Single-source vulnerability in eye-tracking module production threatens hardware delivery timelines. Distribution runs through GPO contracts at United States hospital networks and direct institutional sales at European medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints for EU MDR clinical evidence review prop pricing power for developers with established quality systems. Supply bottlenecks in haptic feedback component sourcing limit hardware scaling.
For Market Incumbents: Hedge against regulatory divergence by maintaining parallel FDA 510(k) and EU MDR technical file capabilities. Secure backward integration into haptic actuator supply through partnerships with Bavarian precision engineering clusters. Defensive positioning requires cloud-rendered delivery infrastructure to reduce hardware dependency as subscription licensing displaces capital sales. For New Entrants and Emerging Players: AI-generated anatomical modeling from patient-specific imaging offers entry into surgical training content without hardware manufacturing overhead. White-space concentration sits with remote rehabilitation platforms for rural post-acute deployment, where telehealth-integrated headsets bypass facility capacity constraints. Go-to-market execution targets German statutory health insurer partnership structures to validate prescription digital therapeutic reimbursement pathways. For Investors and Strategic Acquirers: BfArM reimbursement decisions for prescription VR platforms are the leading indicator that European digital therapeutics infrastructure is reaching institutional maturity. Long-term viability centers on developers with ISO 13485 quality systems and multi-jurisdictional clearance portfolios rather than single-market wellness applications. Acquisition target archetypes include haptic-enabled surgical simulation specialists and AI-driven anatomical modeling platforms. Monitor CMS reimbursement coding decisions for chronic pain digital therapeutics as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Clearance Pathway | Prescription digital therapeutic status unlocks CMS reimbursement at United States pain management clinics. |
| EU MDR Technical File Investment | Notified body certification enables German statutory health insurance coverage decisions. |
| Academic Medical Center Partnership | Clinical evidence generation with Boston and San Francisco Bay Area residency programs validates procedural efficacy. |
| Cloud-Rendered Delivery Platform | Streaming architecture reduces hardware procurement barriers for medical school curriculum integration. |
| Haptic Module Backward Integration | In-house production of force-feedback instruments secures supply for orthopedic simulation scaling. |
Research Approach
FDA 510(k) and De Novo clearance databases, EU MDR notified body technical file registries, and CMS reimbursement coding decisions formed the secondary backbone for market access pathway mapping. Primary interviews with biomedical engineers at academic medical centers, GPO contracts managers at United States hospital networks, and regulatory affairs leads at digital therapeutics developers triangulated procurement pattern validation. Bottom-up segmentation modeling across hardware, software, and services categories converged with top-down market sizing from institutional procurement database analysis.
Bottom-up demand aggregation tracked headset deployment volumes at VA hospitals, medical school simulation lab procurement cycles, and rehabilitation center telehealth integration timelines. Segmentation dimensions spanned product type integration depth, end-user facility scale, application clinical intensity, and technology architecture portability. CAGRs derived from procedure volume elasticity to training modality substitution rates and reimbursement code expansion trajectories. Forecast inputs incorporated haptic feedback adoption curves in orthopedic residency programs and cloud-rendered streaming latency improvement roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints and CMS digital therapeutics coverage determination delays. Projections reflect assumptions of continued FDA digital health guidance evolution and stable statutory health insurance reimbursement frameworks in Germany. Practitioners should monitor BfArM prescription VR coverage expansion and VA hospital centralized procurement mandate renewals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Healthcare Navigation Platform Market