
 Cable Material Market | 2026-2036
Cable Material Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Material Market Outlook
Utility procurement concentration is hardening across major transmission operators in Europe and Asia-Pacific. Prysmian Group leverages its integrated submarine and land cable portfolio to anchor long-term supply agreements with national grid operators. Nexans competes through specialized high-temperature superconductor development, while Sumitomo Electric Industries sustains dominance in optical fiber ribbon cables for dense urban deployments.
Cable materials encompass conductive metals, dielectric insulators, and protective sheathing engineered to transmit electrical power or optical signals across specified voltage ratings, bandwidth thresholds, and environmental exposure limits. Copper and aluminum conductors remain the structural backbone of power transmission infrastructure, though fiber optic materials are displacing copper in data networking backbones due to superior bandwidth-distance performance. Thermoplastic insulation dominates low-voltage construction wiring where cost sensitivity shapes procurement, while thermoset formulations command premium positioning in industrial manufacturing environments requiring thermal and chemical resistance.
FERC grid reliability standards in the United States, EU Green Deal decarbonization mandates under the European Commission, and China's GB standards enforced by SAMR collectively elevate material performance requirements and compliance costs for cable suppliers. REACH substance restrictions and RoHS hazardous material limits further constrain formulation choices for PVC and rubber insulation compounds across European markets. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps as electrification targets tighten material specifications.
Market Dynamics
Cross-linked polyethylene insulation technology is modularizing medium-voltage distribution architectures, compressing installation timelines and displacing thermoplastic formulations across European and Asian grid modernization programs. This material transition is redistributing competitive advantage toward suppliers with integrated compounding capabilities.
Growth Catalysts
- EU Green Deal decarbonization mandates:The European Commission's binding electrification targets are accelerating procurement of high-voltage conductor materials for utility-scale renewable integration across Germany, Spain, and Poland.
- China's GB standards enforcement:SAMR-mandated performance upgrades are displacing legacy PVC formulations in construction wiring, creating demand for halogen-free thermoset compounds.
- Utility-scale solar and offshore wind:Renewable developers in India and Vietnam are intensifying procurement of submarine-rated cable sheathing for inter-array and export connections.
Market Restraints
- Copper price volatility:LME copper fluctuations above historical baselines are compressing margin structures for distributors without long-term smelter offtake agreements.
- REACH substance restrictions:ECHA-mandated phthalate limitations are constraining formulation flexibility for PVC insulation compounds, forcing reformulation investments.
- Optical fiber substitution:Dense wavelength division multiplexing is displacing copper data trunking in metropolitan backbones, eroding legacy conductor demand.
Strategic Opportunities
- India's rural electrification gaps:CEA-mandated last-mile connectivity programs are creating white space for low-smoke zero-halogen materials in distribution networks.
- High-temperature superconductor convergence:Cryogenic cooling integration with fault-current limiters is opening premium positioning for urban underground transmission corridors.
- Direct utility contracting:Bypassing distributor channels through framework agreements with national transmission operators is capturing margin from specification influence.
Industry Challenges
- Compound formulation chemist scarcity:Specialized expertise in thermoset cross-linking chemistry is concentrating among aging technical workforces in Germany and Japan.
- Type-testing certification timelines:IEC 60502 and GB/T 12706 approval cycles extending 18-24 months are delaying product launches for modified insulation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Material Market |
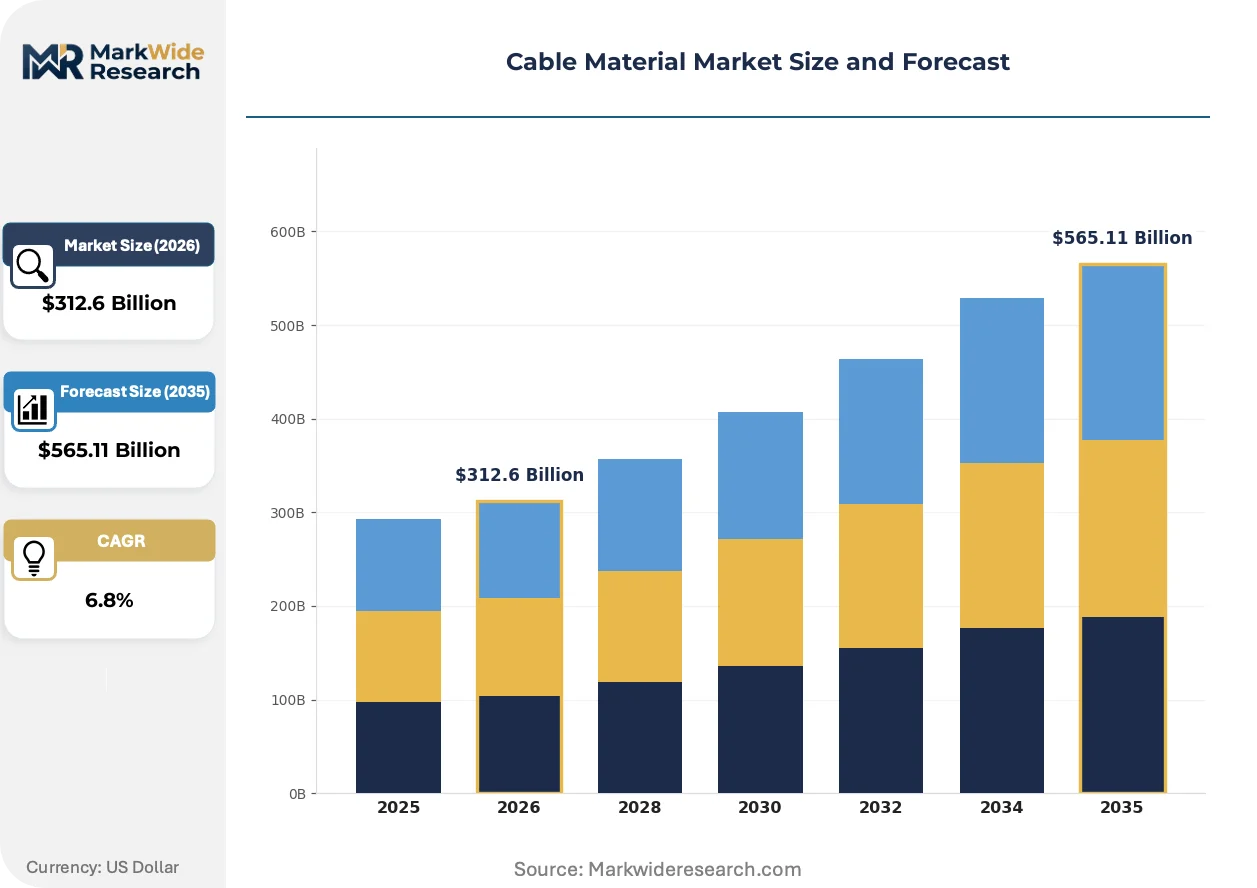
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
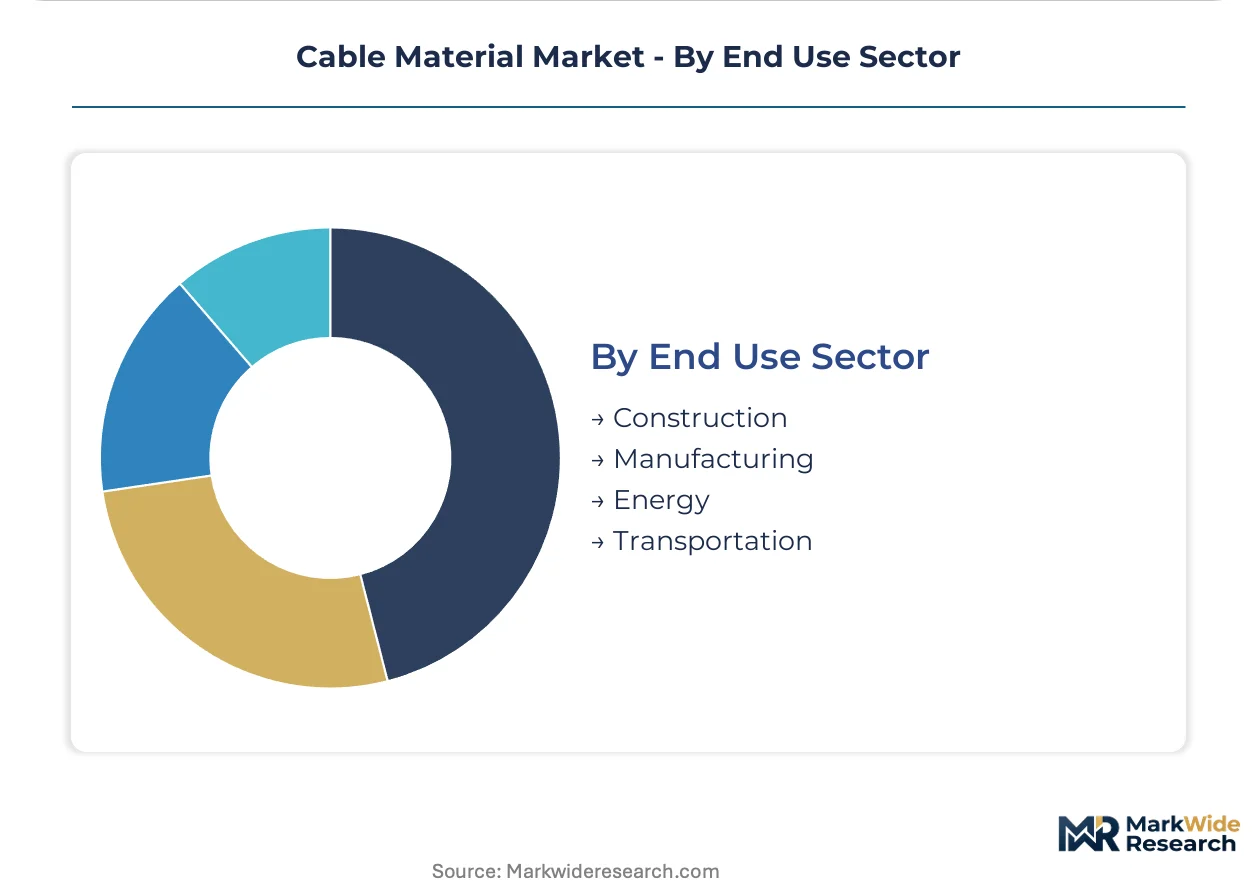
| Segmentation | Material Type: Copper, Aluminum, Fiber Optic, PVC Application: Power Transmission, Telecommunications, Data Networking, Automotive Insulation Type: Thermoplastic, Thermoset, Polyethylene, Rubber End Use Sector: Construction, Manufacturing, Energy, Transportation |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Sumitomo Electric Industries, LS Cable & System, Furukawa Electric Co., Belden Inc., General Cable, Fujikura Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Material Market Strategic Shifts
Material science advances and procurement model compression are reshaping how cable specifications are developed, tested, and commercialized. Three forces are actively restructuring competitive positioning.
Silicone rubber insulation is modularizing flexible medium-voltage connection systems for offshore wind turbine generators. Developers in the North Sea and Taiwan Strait are specifying prefabricated plug-and-play cable assemblies to reduce offshore installation vessel time. This standardization is compressing project engineering cycles and shifting value capture toward system integrators with marine certification capabilities.
REACH substance restrictions are forcing reformulation of flame-retardant additives across European PVC and rubber compounding operations. ECHA's expanding candidate list is eliminating legacy brominated and chlorinated options, redirecting R&D investment toward phosphorus-nitrogen synergists. Medium-voltage industrial cable suppliers serving German automotive manufacturing are absorbing the highest compliance costs and accelerating qualification of alternative chemistries.
Specification influence is migrating from distributor sales forces to utility engineering departments with centralized technical standards. Procurement departments at State Grid, TenneT, and National Grid are unbundling material supply from installation services, compressing distributor margins while rewarding manufacturers with direct testing relationships. This disintermediation is most advanced in China and Germany, where framework agreements now cover multi-year conductor and insulation material volumes.
Cable Material Market Segmentation

Material selection in cable systems determines voltage tolerance, thermal performance, and regulatory compliance across divergent end-use environments. Procurement committees weight copper conductivity against aluminum cost efficiency, while insulation chemistry choices cascade through decades-long asset lifecycles.
Material Type:
Procurement committees prioritize conductivity-to-weight ratios and commodity price hedging when selecting conductive substrates for transmission infrastructure.
- Copper:Oxygen-free high-conductivity copper delivers superior ampacity for high-voltage transmission corridors and precision instrumentation. Demand concentrates in German offshore wind export cables and Indian urban distribution networks where resistive losses carry steep lifecycle penalties.
- Aluminum:Lightweight conductivity at roughly one-third copper density reduces structural loading for long-span overhead lines. China State Grid and US rural cooperatives specify aluminum alloy conductors for cost-sensitive transmission extensions across mountainous terrain.
- Fiber Optic:Silica-based waveguides transmit terabit-scale data through total internal reflection with negligible attenuation.
- PVC:Chlorinated polymer sheathing offers flame retardancy and moisture resistance at construction-grade price points.
Volume sits with aluminum in megawatt-scale transmission; growth tilts toward fiber optic in data center interconnects.
Application:
End-use voltage ratings and signal bandwidth requirements partition material specifications across infrastructure domains.
- Power Transmission:Extruded cross-linked polyethylene insulation rated to 500kV contains electric fields within submarine and underground high-voltage corridors. Procurement from TenneT and National Grid drives demand for low-dielectric-loss formulations in North Sea interconnector projects.
- Telecommunications:Single-mode optical fiber with germanium-doped cores enables coherent transmission across transoceanic distances. Dense wavelength division multiplexing deployments in Tokyo and Singapore metro rings displace legacy copper trunk infrastructure.
- Data Networking:Twinax copper and active optical cables bridge rack-scale distances within hyperscale facilities.
- Automotive:Flexible silicone-insulated conductors withstand engine compartment thermal cycling and chemical exposure.
Power transmission commands the heaviest conductor tonnage; telecommunications exhibits the steepest expansion trajectory.
Insulation Type:
Thermal endurance requirements and installation environment exposure dictate polymer chemistry selection for dielectric containment.
- Thermoplastic:PVC and polyethylene compounds soften reversibly under thermal load, enabling extrusion at high line speeds. Low-voltage building wire manufacturers in Vietnam and Indonesia favor thermoplastic jacketing for cost-optimized residential electrification programs.
- Thermoset:Cross-linked polyethylene and ethylene propylene rubber form irreversible molecular networks that retain mechanical integrity above crystalline melting points. German industrial cable specifications mandate thermoset insulation for continuous operation at 90°C in automotive paint shop environments.
- Polyethylene:Unfilled linear low-density grades provide moisture barriers in direct-buried distribution cables.
- Rubber:Ethylene propylene diene monomer compounds deliver flexibility for mining and portable power applications.
Thermoplastic dominates construction wiring volumes; thermoset gains share fastest in renewable energy integration.
End Use Sector:
Asset lifecycle duration and regulatory exposure shape material grade selection across vertical markets.
- Construction:Halogen-free flame-retardant compounds satisfy EU CPR classification requirements for high-rise building vertical risers. French and Polish electrical contractors specify low-smoke zero-halogen sheathing for public infrastructure fire safety compliance.
- Manufacturing:Oil-resistant thermoset jackets protect conductors in steel mill and chemical processing environments where mechanical abuse and thermal cycling converge.
- Energy:Submarine-rated lead sheathing and polyethylene armor withstand hydrostatic pressure and seabed abrasion for offshore wind array cables.
- Transportation:Thin-wall irradiated cross-linked insulation reduces weight in aerospace and rolling stock applications.
Construction absorbs the highest conductor tonnage; energy sector procurement climbs the fastest on renewable buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration for high-voltage conductor materials clusters in China, Germany, and India where grid modernization programs and renewable energy buildouts are reshaping material specifications. Utility engineering departments at State Grid, TenneT, and Power Grid Corporation of India now dictate insulation chemistry requirements through multi-year framework agreements.
China
State Grid Corporation's ultra-high-voltage transmission expansion drives demand for cross-linked polyethylene insulation rated above 500kV. SAMR-enforced GB standards are displacing legacy PVC formulations in construction wiring across megacity clusters. Yangtze River Delta manufacturers in Jiangsu and Zhejiang provinces are scaling halogen-free thermoset compound production for export-qualified cable systems.
Germany
TenneT and 50Hertz procurement for North Sea offshore wind interconnectors sustains premium demand for low-dielectric-loss submarine cable insulation. EU Green Deal mandates under the European Commission accelerate copper conductor procurement for renewable energy integration. Industrial cable fabricators in North Rhine-Westphalia are absorbing REACH reformulation costs for automotive manufacturing supply chains.
India
CEA-mandated rural electrification programs create white space for low-smoke zero-halogen materials in last-mile distribution networks. Power Grid Corporation's green energy corridors intensify aluminum alloy conductor procurement for cost-sensitive transmission extensions. Manufacturing clusters in Gujarat and Maharashtra are expanding thermoplastic jacketing capacity for residential electrification programs.
United States
FERC grid reliability standards elevate material performance requirements for interstate transmission infrastructure. Rural electric cooperatives specify aluminum conductors for long-span overhead lines across mountainous western terrain. Southeast manufacturing corridors in Georgia and the Carolinas are scaling construction-grade PVC sheathing production for residential building wire.
Japan
METI carbon neutrality roadmaps accelerate procurement of high-temperature superconductor materials for urban underground transmission. Dense wavelength division multiplexing deployments in Tokyo metro rings displace copper trunk infrastructure with single-mode optical fiber. Kansai region compounders specialize in ethylene propylene rubber formulations for industrial manufacturing environments.
Cable Material Market Competitive Environment
European producers anchor one tier; East Asian specialists hold differentiated positions in optical fiber and superconductor development. The vendor base concentrates among integrated manufacturers with in-house compounding capabilities and marine certification portfolios. Three archetypes dominate: full-line transmission suppliers, fiber optic specialists, and regional construction wire fabricators. Competitive moves center on direct utility framework agreements and backward integration into conductor smelting operations.
Within the integrated transmission tier, Prysmian Group and Nexans occupy positions shaped by submarine cable certification and European grid operator relationships. Sumitomo Electric Industries exemplifies the fiber-dominant archetype through its concentration in dense urban optical deployments. Southwire Company anchors the North American construction wire segment with scale-driven positioning in aluminum alloy conductor supply.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Sumitomo Electric Industries |
| LS Cable & System |
| Furukawa Electric Co. |
| Belden Inc. |
| General Cable |
| Fujikura Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers and family-owned mid-caps anchor conductor supply across Jiangsu and North Rhine-Westphalia, compressing pricing discipline through captive smelter relationships and multi-year utility offtake agreements. Their ownership structures insulate against spot commodity volatility while concentrating specification influence with national grid operators.
Pricing Analysis
Volume concentrates in construction-grade aluminum alloy conductors where margin compression runs deepest, while premium positioning persists in submarine-rated cross-linked polyethylene systems certified for North Sea interconnectors. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60502-certified thermoset insulation from GB/T 12706 construction wiring and unbranded PVC jacketing. Pricing pressure stems from LME copper volatility above historical baselines, squeezing distributor margins without long-term smelter contracts. Price-sensitive rural electric cooperatives in mountainous US terrain prioritize aluminum cost efficiency, while least-sensitive TenneT procurement teams absorb premium for low-dielectric-loss submarine formulations.
Supply Chain Analysis
Scrap copper recovery and insulation compound reformulation flows are gaining traction as REACH-mandated phthalate restrictions force reclamation of halogen-free thermoset materials. Primary supply concentrates in China, Germany, and India where State Grid, TenneT, and Power Grid Corporation of India dictate multi-year framework volumes. Raw material sourcing draws from Chilean copper concentrate, Qatari liquefied natural gas for ethylene feedstock, and German chemical specialist compounding. Single-source vulnerability concentrates in high-temperature superconductor cryogenic cooling integration, where Japanese and German technical workforces anchor specialized expertise. Distribution runs through direct utility contracting channels that disintermediate traditional distributor networks in China and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into conductor smelting and in-house thermoset compounding capabilities determine long-term margin capture. Players are pursuing captive copper and aluminum supply to insulate against LME volatility and secure utility framework agreements.
For Market Incumbents: Hedge against optical fiber substitution in data networking backbones by accelerating submarine cable certification for offshore wind arrays. Prysmian-type integrated portfolios should consolidate thermoset compounding expertise in Germany and Japan before aging technical workforces retire. Defend specification influence through direct testing relationships with State Grid and National Grid engineering departments. For New Entrants and Emerging Players: Capture white space in India's rural electrification gaps where CEA-mandated last-mile connectivity programs lack low-smoke zero-halogen material suppliers. Gujarat and Maharashtra manufacturing clusters offer accessible thermoplastic jacketing capacity for residential electrification. Prioritize halogen-free compound qualification ahead of SAMR-enforced GB standard upgrades. For Investors and Strategic Acquirers: Framework agreement announcements from TenneT or 50Hertz for North Sea offshore wind interconnectors are the leading indicator that premium submarine cable insulation demand is inflecting upward. Five-to-ten-year viability favors integrated manufacturers with marine certification portfolios and in-house cross-linking chemistry capabilities. Monitor ECHA candidate list expansions for phosphorus-nitrogen synergist qualification timelines that signal reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductor Smelting | Captive copper supply insulates Prysmian-type integrated suppliers against LME volatility and secures multi-year State Grid volumes. |
| Submarine Cable Marine Certification | DNV-GL and Bureau Veritas approval unlocks TenneT and 50Hertz procurement for North Sea offshore wind interconnectors. |
| Halogen-Free Thermoset Compound Qualification | ECHA REACH compliance enables continued access to German automotive manufacturing and French public infrastructure fire safety markets. |
| Direct Utility Framework Agreements | Bypassing distributor channels captures margin from specification influence at State Grid, National Grid, and Power Grid Corporation of India. |
| High-Temperature Superconductor Cryogenic Integration | METI-funded urban underground transmission corridors in Tokyo open premium positioning for fault-current limiter convergence. |
Study Parameters
Trade flow databases, IEC standard certification registries, and utility procurement disclosure filings formed the secondary backbone for conductor and insulation material demand estimation. Primary interviews with cable engineering directors at transmission operators, thermoset compound formulators in German industrial clusters, and procurement leads at national grid corporations validated secondary estimates. Bottom-up and top-down triangulation cross-referenced country-level electrification program targets against manufacturer capacity disclosures.
Bottom-up modeling built from individual project pipelines for offshore wind interconnectors and rural electrification programs, while top-down analysis scaled from macro grid investment forecasts across the projection horizon. Segmentation dimensions included material type, voltage rating tier, insulation chemistry, and end-use sector regulatory exposure. CAGRs derived from weighted average of utility capital expenditure trajectories and commodity price scenario modeling. Forecast inputs incorporated SAMR GB standard enforcement timelines and EU Green Deal binding electrification targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, REACH substance restriction expansions, and cryogenic cooling technology maturation for superconductor deployment. Forecasts reflect documented assumptions about grid modernization program execution rates and renewable energy buildout pacing. Practitioners should monitor ECHA candidate list announcements, TenneT framework agreement awards, and METI carbon neutrality roadmap revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
EDM Wires Market
Cables
Cable Tags Market
Cables
Cable Market
Cables
Patch Cable Market
Cables
Radio Frequency Cables Market
Cables
Coaxial Cable Market
Cables
South Africa Wire and Cable Market
Cables
Magnetic Charging Cable Market
Cables
Aluminium Battery Cable Market
Cables
Cable Testing Market
Cables
North America Patch Cable Market
Cables
Middle East Cable Market
Cables
LASER Light Cables Market
Cables
Global Cable Tie Market
Cables
Premise Cable Market
Cables
Fiber Optic Cable Materials Market