
 Fluorophore Market | 2026-2036
Fluorophore Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorophore Market Foresight
Aftermarket service revenue for instrument calibration and dye requalification is narrowing as manufacturers bundle subscription-based fluorophore replenishment with hardware leases. Thermo Fisher Scientific leverages its diagnostics distribution network to lock in multi-year reagent supply contracts with hospital systems. ATTO-TEC GmbH anchors its position through proprietary rhodamine derivatives optimized for super-resolution microscopy. Bio-Rad Laboratories competes by sustaining deep backward integration into reactive dye intermediates.
A fluorophore is a chemical compound that absorbs light at a specific excitation wavelength and emits fluorescence at a longer emission wavelength, with quantum yields typically ranging from 0.1 to 1.0 and Stokes shifts between 20 and 100 nanometers; these photophysical properties enable detection sensitivity down to single-molecule levels in analytical and imaging systems. Organic fluorophores dominate current revenue owing to established synthetic routes and broad spectral tunability through heterocyclic modification, though nanocrystal fluorophores capture the fastest expansion as cadmium-free formulations resolve prior toxicity barriers. Fluorescence Lifetime Imaging technology concentrates margin pools in oncology and neuroscience research, where temporal resolution separates bound from unbound probe states.
FDA oversight of in vitro diagnostic devices and EPA registration requirements for chemical substances shape fluorophore commercialization pathways in the United States, while REACH compliance in Europe mandates extensive substance dossiers for novel dye chemistries. ISO 13485 certification pressures diagnostic-grade suppliers to maintain batch-to-batch optical consistency within two percent coefficient of variation. Stakeholders must monitor how EMA guidance on companion diagnostic co-development redefines fluorophore performance specifications for clinical translation.
Market Dynamics
Pharmaceutical developers are consolidating fluorescence-guided assay procurement around multi-year reagent supply contracts bundled with hardware leases, compressing standalone aftermarket service margins and reshaping vendor economics across the value chain.
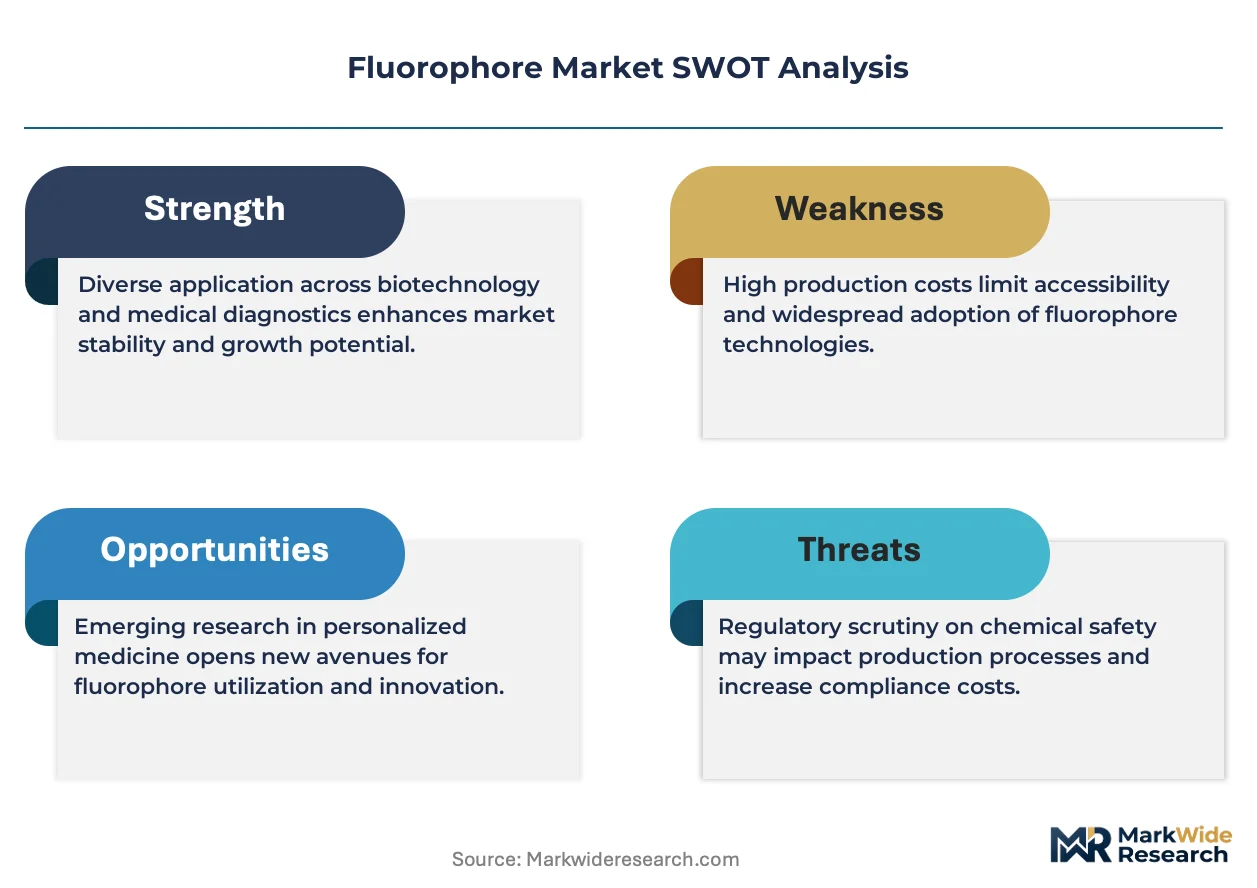
Growth Catalysts
- High-throughput screening expansion:Contract research organizations in Germany's Rhine-Main biotech cluster are scaling fluorescence-based compound libraries, anchoring organic fluorophore procurement volumes for drug discovery pipelines.
- REACH compliance thresholds:ECHA-mandated purity standards for heavy-metal-containing quantum dots are accelerating cadmium-free nanocrystal formulations, opening substitution pathways in analytical instrumentation.
- Super-resolution microscopy adoption:Research institutes are deploying rhodamine derivatives with enhanced photostability, driving demand for proprietary heterocyclic modifications in neuroscience and oncology imaging.
Market Restraints
- Rare earth element volatility:Europium and terbium supply concentration in Chinese processing facilities creates input cost instability for lanthanide-based fluorophores used in time-resolved assays.
- Batch-to-batch optical variance:ISO 13485 certification requirements for diagnostic-grade suppliers enforce coefficient of variation below two percent, raising quality control overhead for small-scale dye manufacturers.
- Photobleaching limitations:Organic fluorophores exhibit degradation under continuous excitation, constraining longitudinal live-cell imaging applications where quantum dot alternatives face RoHS toxicity barriers.
Strategic Opportunities
- Companion diagnostic co-development:EMA guidance on synchronized therapeutic and diagnostic approval pathways creates specification windows for clinical-grade fluorophores in precision oncology.
- Fluorescence Lifetime Imaging expansion:Temporal resolution capabilities separating bound from unbound probe states are penetrating neuroscience research, opening margin pools in academic and pharmaceutical R&D budgets.
- Subscription-based replenishment models:Instrument manufacturers are bundling dye requalification services with hardware leases, creating recurring revenue streams that displace transactional reagent sales.
Industry Challenges
- Reactive dye intermediate sourcing:Deep backward integration requirements for azo and anthraquinone precursors demand capital-intensive in-house production capabilities that mid-tier suppliers struggle to finance.
- Cross-jurisdiction registration complexity:EPA chemical substance registration for novel fluorophore chemistries runs parallel to FDA in vitro diagnostic device oversight, extending commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorophore Market |
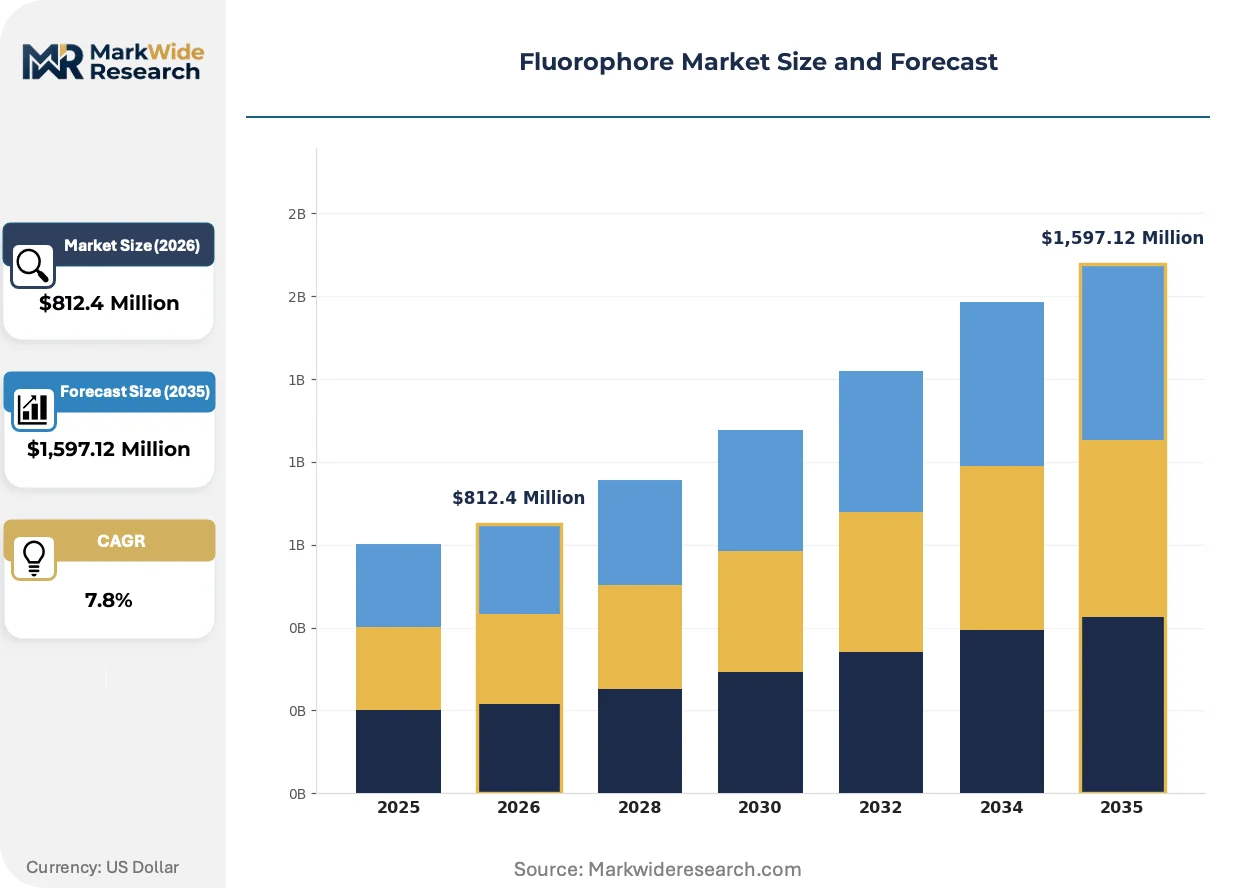
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,597.12 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fluorophores, Inorganic Fluorophores, Polymer-based Fluorophores, Nanocrystal Fluorophores Application: Bioimaging, Flow Cytometry, Fluorescence Microscopy, Molecular Probing, DNA Sequencing Technology: Fluorescence Resonance Energy Transfer, Two-Photon Excitation, Time-Resolved Fluorescence, Fluorescence Lifetime Imaging End User: Biotechnology Firms, Academic Research Centers, Pharmaceutical Developers, Diagnostic Laboratories |
| Companies Covered | PerkinElmer, ATTO-TEC GmbH, Thermo Fisher Scientific, Becton Dickinson, Sigma-Aldrich, Merck KGaA, AAT Bioquest, Agilent Technologies, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorophore Market Shifts & Advancements
Fluorophore technology trajectories center on spectral engineering advances, regulatory-driven material substitutions, and procurement model restructuring that favors integrated supply agreements over spot purchasing.
Nanocrystal fluorophores engineered with indium phosphide cores are migrating from research-grade microscopy toward clinical diagnostic platforms. In vitro diagnostic manufacturers are qualifying these cadmium-free formulations for flow cytometry and immunoassay applications. This migration is compressing the addressable market for traditional organic dyes in high-sensitivity detection workflows.
REACH authorization requirements for substances of very high concern are tightening disclosure obligations for novel dye chemistries entering the European Economic Area. ECHA substance dossier preparation now consumes 12-18 months for heterocyclic modifications with uncharacterized toxicological profiles. Contract research organizations in Germany and the Netherlands are prioritizing fluorophore suppliers with pre-registered substance portfolios to accelerate project initiation.
Hospital systems and academic core facilities are consolidating reagent procurement through multi-year supply contracts tied to instrument placement agreements. Thermo Fisher Scientific's diagnostics distribution network captures this concentration by locking in exclusive fluorophore replenishment rights. This bundling dynamic is most visible in United States hospital consolidation markets where integrated delivery networks command volume-based pricing leverage.
Fluorophore Market Segmentation
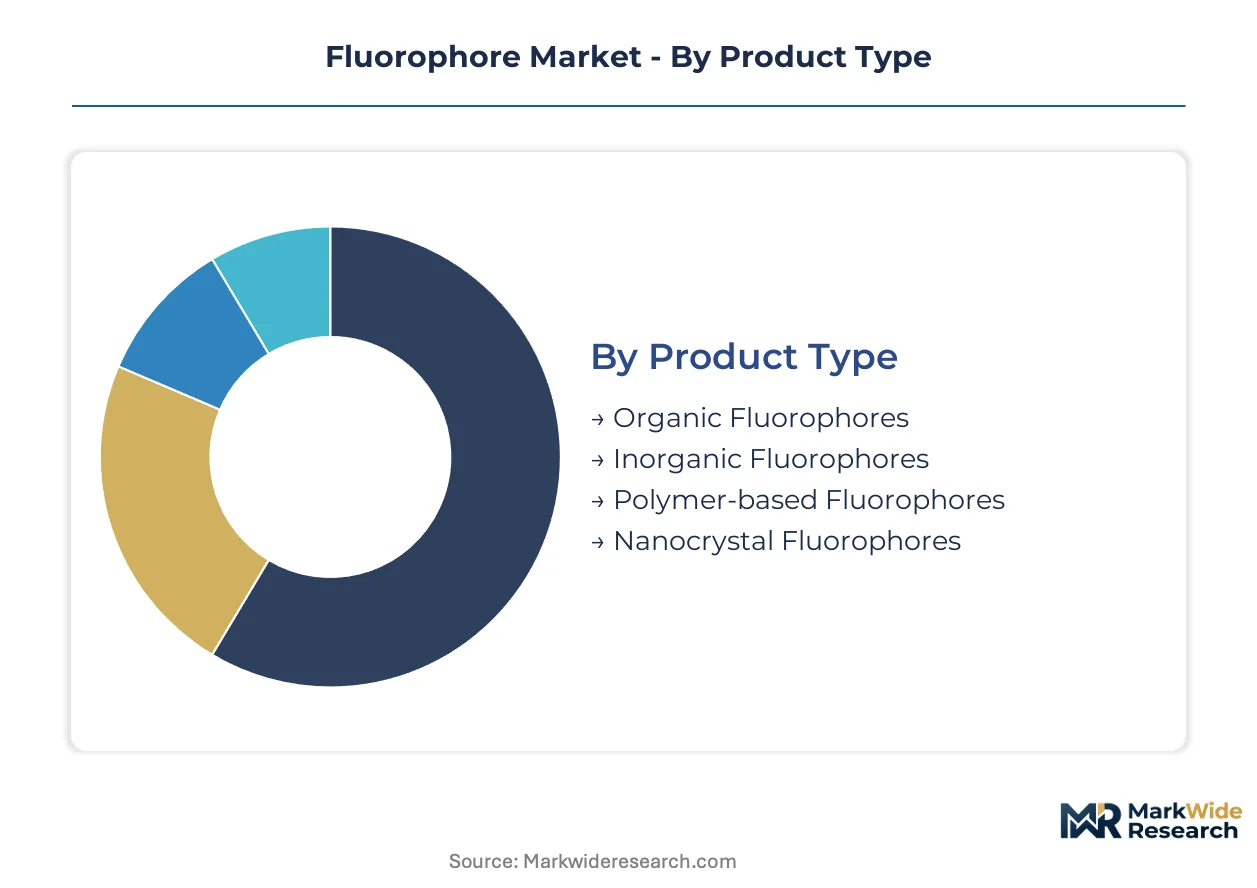
Fluorophore procurement patterns diverge sharply across product chemistries and detection platforms. Each segmentation dimension reveals distinct margin structures, regulatory exposure, and vendor consolidation dynamics that reshape competitive positioning.
Product Type:
Cost tiers separate commodity dye intermediates from precision-engineered nanocrystals with proprietary surface chemistries.
- Organic Fluorophores:Heterocyclic compounds including fluorescein, rhodamine, and cyanine derivatives dominate current procurement volumes through established synthetic routes and spectral tunability. Rhine-Main biotech clusters in Germany anchor demand for high-purity batches in drug discovery screening workflows.
- Inorganic Fluorophores:Lanthanide chelates incorporating europium and terbium enable time-resolved detection with microsecond emission lifetimes that eliminate autofluorescence interference. Supply concentration in Chinese rare earth processing facilities creates input cost volatility that constrains pricing flexibility for assay manufacturers.
- Polymer-based Fluorophores:Conjugated polymer systems amplify signal through energy migration along molecular backbones.
- Nanocrystal Fluorophores:Quantum dots with indium phosphide cores resolve prior cadmium toxicity barriers under REACH authorization pathways.
Organic fluorophores command the established base. The steepest expansion runs through nanocrystal formulations.
Application:
End-use requirements dictate photostability thresholds, spectral multiplexing needs, and regulatory classification intensity.
- Bioimaging:Live-cell and tissue imaging applications demand photostable probes with minimal phototoxicity. Super-resolution microscopy adoption in German neuroscience institutes drives specification intensity for rhodamine derivatives with enhanced photostability profiles.
- Flow Cytometry:High-speed cell sorting requires bright, narrow-emission fluorophores compatible with multiple laser lines. In vitro diagnostic manufacturers in the United States are qualifying cadmium-free nanocrystals for clinical-grade instrument platforms.
- Fluorescence Microscopy:Widefield and confocal systems utilize broad spectral libraries for multiplexed detection.
- Molecular Probing:Target-specific conjugates enable protein localization and interaction studies.
- DNA Sequencing:Next-generation sequencing platforms consume fluorophore-labeled nucleotides at industrial scale.
Fluorescence microscopy captures the largest installed base. Bioimaging applications are climbing the fastest as super-resolution techniques penetrate academic and pharmaceutical R&D budgets.
Technology:
Detection modality selection determines capital equipment compatibility and reagent specification windows.
- Fluorescence Resonance Energy Transfer:FRET-based assays exploit distance-dependent energy transfer between donor and acceptor fluorophores for molecular interaction studies. High-throughput screening operations in contract research organizations favor ratiometric FRET biosensors for compound library profiling.
- Two-Photon Excitation:Nonlinear optical excitation with near-infrared lasers enables deep-tissue imaging with reduced photodamage. Neuroscience research institutes in Germany deploy two-photon microscopy for longitudinal in vivo studies requiring extended probe photostability.
- Time-Resolved Fluorescence:Microsecond-lifetime lanthanide emission separates signal from nanosecond autofluorescence backgrounds.
- Fluorescence Lifetime Imaging:Temporal resolution distinguishes bound from unbound probe states in oncology and neuroscience research.
FRET platforms anchor the broadest installed instrument base. Fluorescence Lifetime Imaging is gaining share fastest as temporal resolution capabilities penetrate precision oncology applications.
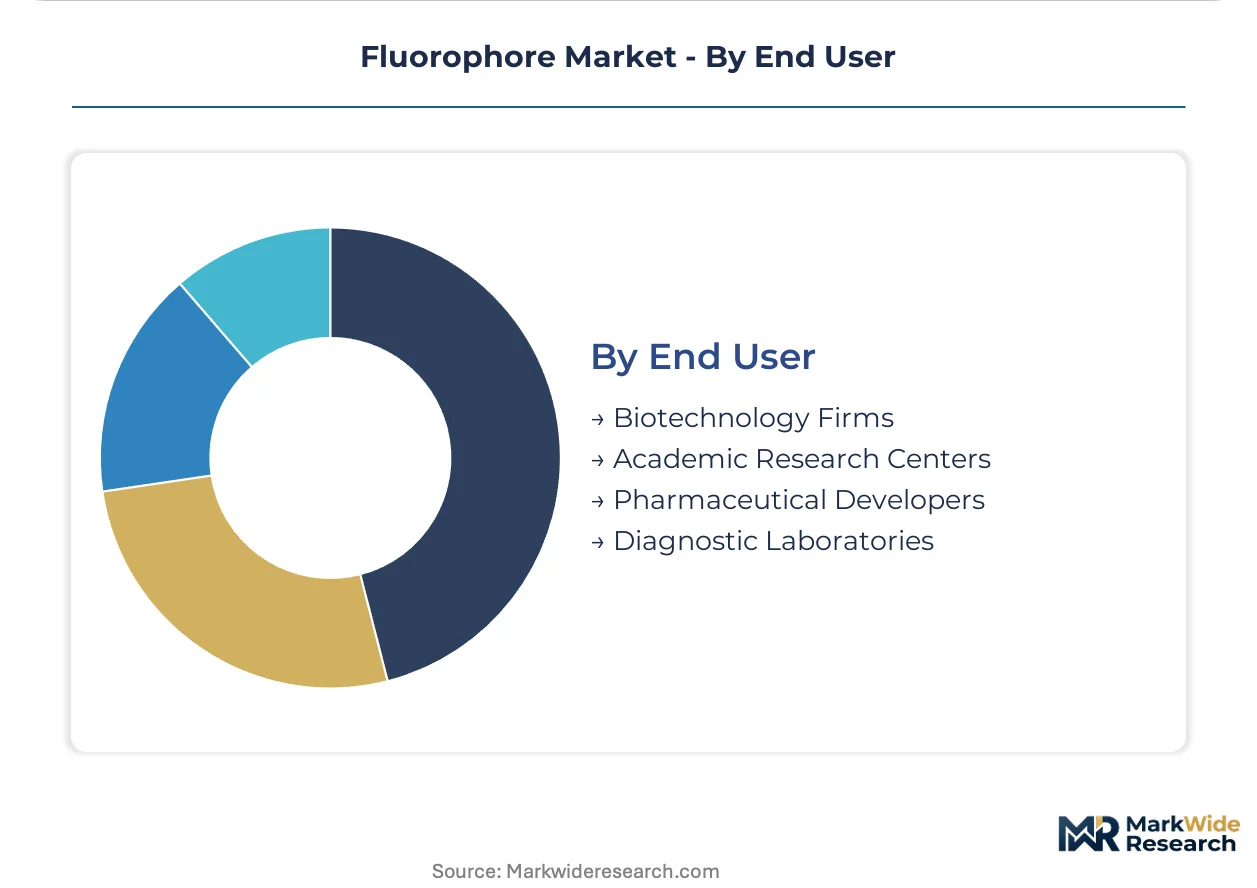
End User:
Customer scale and purchasing integration reshape contract structures and vendor lock-in intensity.
- Biotechnology Firms:Mid-scale research operations balance flexibility against reagent quality consistency. German contract research organizations in the Rhine-Main cluster consolidate procurement through multi-year supply agreements tied to instrument placement.
- Academic Research Centers:Core facility models concentrate purchasing power across institutional user bases. United States university systems negotiate volume-based pricing through integrated delivery network structures.
- Pharmaceutical Developers:High-throughput screening demands drive large-batch organic fluorophore procurement with ISO 13485-compliant quality documentation.
- Diagnostic Laboratories:Clinical-grade reagent requirements enforce batch-to-batch optical consistency within two percent coefficient of variation.
Pharmaceutical developers command the highest reagent consumption volumes. Diagnostic laboratories are expanding procurement fastest as companion diagnostic co-development pathways mature under EMA guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Academic core facilities in the United States absorb premium pricing for ISO-certified diagnostic grades, while contract research organizations in Central Europe negotiate volume-based contracts that compress margins for organic fluorophore suppliers.
United States
Hospital consolidation into integrated delivery networks concentrates procurement leverage for multi-year reagent supply agreements. FDA oversight of in vitro diagnostic devices and EPA chemical substance registration create parallel compliance pathways that extend commercialization timelines. The Greater Boston biotech corridor anchors fluorescence-guided assay development for pharmaceutical screening pipelines.
Germany
Rhine-Main biotech clusters drive organic fluorophore consumption through high-throughput screening operations at contract research organizations. REACH authorization requirements for substances of very high concern tighten disclosure obligations for novel heterocyclic modifications. Munich and Heidelberg research institutes deploy super-resolution microscopy, accelerating demand for photostable rhodamine derivatives.
China
Domestic in vitro diagnostic manufacturers scale flow cytometry platform production, creating import substitution pressure for cadmium-free nanocrystal formulations. NMPA registration pathways for clinical-grade reagents enforce batch-to-batch optical consistency standards. Yangtze River Delta fluorescence probe suppliers expand synthetic capacity for export markets.
Japan
Neuroscience research institutes prioritize two-photon microscopy systems for longitudinal in vivo imaging applications. METI funding programs support domestic development of lanthanide chelates with microsecond emission lifetimes. Osaka-based diagnostic reagent manufacturers qualify time-resolved fluorescence platforms for automated immunoassay systems.
United Kingdom
Academic core facilities consolidate purchasing power across institutional user bases through shared services frameworks. MHRA alignment with EMA guidance on companion diagnostic co-development creates specification windows for clinical-grade fluorophores. The Cambridge-London life sciences corridor anchors demand for DNA sequencing-grade dye-labeled nucleotides.
Fluorophore Market Competitive Landscape
Capability concentration sits with specialized dye chemistry houses; scale advantage sits with diversified life sciences conglomerates. The market structure separates into three tiers: global distributors with diagnostics networks, mid-scale specialists with proprietary heterocyclic portfolios, and commodity dye intermediates suppliers. Strategic archetypes include backward-integrated reactive dye manufacturers, subscription-based reagent bundlers, and nanocrystal formulation pioneers. Competitive moves center on multi-year supply contract capture and cadmium-free quantum dot qualification for clinical platforms.
Among Germany-based specialists, ATTO-TEC GmbH exemplifies the proprietary heterocyclic modification tier. Thermo Fisher Scientific occupies the scale-driven diagnostics distribution position. Bio-Rad Laboratories represents backward integration into reactive dye intermediates. These three anchors illustrate how vendor economics diverge between bundled hardware-lease models and standalone reagent sales.
| Leading Market Players |
|---|
| PerkinElmer |
| ATTO-TEC GmbH |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Sigma-Aldrich |
| Merck KGaA |
| AAT Bioquest |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Undercapacity in European rare earth processing facilities is tightening lanthanide chelate supply and amplifying pricing power for qualified fluorophore manufacturers serving diagnostic-grade contracts.
Pricing Analysis
Aftermarket service revenue from instrument calibration and dye requalification is compressing as manufacturers bundle subscription-based fluorophore replenishment with hardware leases. Three-tier pricing structure across premium diagnostic-grade, standard research-grade, and economy bulk-intermediate levels separates ISO 13485-certified batches from uncertified alternatives. Cost compression in standalone reagent sales is intensifying because hospital consolidation into integrated delivery networks commands volume-based leverage. Contract research organizations in Germany's Rhine-Main cluster exhibit highest price sensitivity, while United States academic core facilities absorb premium pricing for certified diagnostic grades.
Supply Chain Analysis
Extended payment terms from German diagnostic instrument manufacturers are squeezing working capital for mid-tier dye chemistry houses. Supply concentrates in China for europium and terbium processing, Germany for heterocyclic dye synthesis, and the United States for nanocrystal formulation. Reactive dye intermediate sourcing draws from azo and anthraquinone precursor streams. Single-source vulnerability in Chinese rare earth processing creates input cost instability. Distribution runs through diagnostics distribution networks and direct procurement channels to hospital systems and academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EMA companion diagnostic guidance creates specification windows that favor specialized clinical-grade suppliers over commodity producers.
For Market Incumbents: Harden supply security through captive europium and terbium sourcing agreements with Chinese processors, and accelerate ISO 13485 certification investments to defend diagnostic-grade margins against cadmium-free nanocrystal substitutes. Threat from indium phosphide quantum dots penetrating clinical platforms demands preemptive heterocyclic modification R&D in photostable rhodamine derivatives. For New Entrants and Emerging Players: Pursue white-space in lanthanide chelate alternatives with microsecond emission lifetimes for time-resolved fluorescence platforms, and target United States hospital consolidation markets with subscription-based reagent bundling. Companion diagnostic co-development pathways offer the most penetrable entry angle, with go-to-market execution through instrument manufacturer partnership structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostics-distribution-integrated fluorophore suppliers with multi-year hospital system contracts. Long-term viability centers on defensible proprietary heterocyclic portfolios and REACH-registered substance dossiers. Acquisition target archetype: mid-scale specialists with backward integration into reactive dye intermediates. Signal to watch: cadmium-free nanocrystal qualification milestones at in vitro diagnostic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Substance Dossier Registration | ECHA pre-registration accelerates project initiation for German contract research organizations. |
| Cadmium-Free Nanocrystal Qualification | Indium phosphide core formulations unlock clinical diagnostic platform migration pathways. |
| Backward Integration into Reactive Dye Intermediates | In-house azo and anthraquinone production secures margin control for mid-tier suppliers. |
| Multi-Year Supply Contract Capture | Hardware-lease bundling displaces transactional reagent sales with recurring revenue streams. |
| ISO 13485 Certification Investment | Batch-to-batch optical consistency enforcement creates barrier against uncertified competitors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fluorophore procurement managers at German contract research organizations, regulatory affairs leads at in vitro diagnostic manufacturers, hospital purchasing committee members, and academic core facility directors; and secondary validation through ECHA substance dossier databases, FDA in vitro diagnostic device filings, EPA chemical substance registrations, and SEC 10-K disclosures from diversified life sciences conglomerates. Bottom-up volume modeling and top-down market sizing triangulated segment-level estimates.
Forecast inputs considered organic fluorophore procurement volumes from Rhine-Main biotech clusters, nanocrystal formulation adoption curves in flow cytometry applications, and fluorescence lifetime imaging penetration rates in oncology and neuroscience research across the analysis window. Segmentation dimensions modeled include product chemistry tier, detection platform compatibility, end-user scale, and regional regulatory cluster. CAGRs were derived from compound growth trajectory analysis incorporating substitution dynamics between organic dyes and cadmium-free quantum dots.
Sensitivities concentrate around REACH authorization timelines for novel heterocyclic modifications, NMPA registration pathway efficiency for Chinese market access, and rare earth element supply disruption scenarios. Forecasts reflect assumptions regarding sustained pharmaceutical high-throughput screening demand and diagnostic laboratory consolidation trends. Macroeconomic contraction, regulatory timeline extension, or nanocrystal performance breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Europe Scintillator Market
Optical Components
Optical Waveguide Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Prism Coupler Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Passive Optical Component Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Europe Optical Film Market
Optical Components
Spatial Light Modulator Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
North America Tunable Laser Market
Optical Components
Optical Isolator Market
Optical Components
VCSEL for Data Communication Market
Optical Components
100G Optical Transceivers Market