
 Global Electronic Fiberglass Market | 2026-2036
Global Electronic Fiberglass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Fiberglass Market Foresight
The capital-intensity divergence between furnace-scale producers and downstream weavers is redrawing competitive boundaries in electronic fiberglass. China Jushi Co., Ltd. leverages its captive boron-alumina supply chain to control input costs across S-Glass and E-Glass lines. Taishan Fiberglass anchors its position through dedicated tank furnaces optimized for low-alkali formulations serving PCB laminators. Owens Corning competes by extending its North American logistics network to reduce lead times for telecommunications infrastructure projects.
Electronic fiberglass consists of continuous glass filaments drawn from molten silica-alumina-boron melts at temperatures exceeding 1300°C, then sized with silane coupling agents to ensure adhesion in epoxy resin matrices. Its primary commercial purpose is to provide dimensional stability, dielectric insulation, and mechanical reinforcement for multilayer printed circuit boards and high-voltage electrical components. E-Glass formulations dominate volume flows due to their balanced dielectric constant and cost structure, while S-Glass commands premium positioning in aerospace and satellite applications where tensile modulus requirements exceed 85 GPa. Chopped strands are capturing expanding share in automotive component molding as electric vehicle manufacturers seek flame-retardant housing materials.
REACH compliance in Europe and NMPA material certification in China are forcing reformulation of traditional boron-rich glass compositions to meet stricter workplace exposure thresholds. The EU F-Gas Regulation and China's dual carbon goals are simultaneously elevating energy efficiency standards for melting furnace operations, favoring producers with oxy-fuel or electric boosting retrofits. Stakeholders must monitor how substrate miniaturization trends in advanced packaging reshape filament diameter specifications and whether regional carbon border adjustments redirect trade flows for woven roving and continuous filament supplies.
Market Dynamics
Substrate miniaturization in advanced semiconductor packaging is compressing filament diameter specifications and forcing furnace operators to retool for finer denier production. This structural pressure cascades through the value chain, rewarding producers with precision drawing capabilities and penalizing commodity-scale operators.
Growth Catalysts
- 5G Base Station Deployment:Telecommunications infrastructure buildouts in China, South Korea, and Germany are pulling high-frequency laminate substrates that require ultra-low Dk/Df E-Glass formulations.
- REACH Phase-Out Mandates:ECHA restrictions on boron oxide workplace exposure are accelerating certified low-alkali glass adoption among European PCB laminators seeking regulatory clearance.
- Electric Vehicle Battery Housings:Automotive OEMs specify flame-retardant chopped strand composites for thermal runaway protection, opening volume offtake outside traditional electronics.
Market Restraints
- Boron-Alumina Input Volatility:Concentrated supply of boron compounds from Turkish and Argentine deposits exposes margin structures to extraction quota fluctuations.
- Furnace Scale Concentration:Melting capacity clusters in China's Jiangsu province create single-point vulnerability for global continuous filament supply.
- High-Modulus Carbon Fiber Substitution:Aerospace satellite manufacturers increasingly specify T800-grade carbon for antenna substrates where S-Glass once dominated.
Strategic Opportunities
- India PCB Fabrication:PLI scheme subsidies for semiconductor packaging are attracting laminate producers to Gujarat and Tamil Nadu, creating greenfield glass demand.
- Oxy-Fuel Retrofit Incentives:China's dual carbon goals offer tax credits for furnace electrification, rewarding early movers with operating cost advantages.
- AI Accelerator Substrates:Convergence of chiplet architectures and high-layer-count PCBs is opening specification windows for ultra-fine filament weaves.
Industry Challenges
- Fiber-Drawing Technician Scarcity:Specialized skills for 5-7 micron diameter control are concentrated among aging workforces in Japan and Germany.
- NMPA Certification Timelines:China's medical-grade material approval process extends 18-24 months for implantable device substrates.
- Legacy ERP Integration:Furnace operators struggle to mesh IoT sensor networks with decades-old production planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Fiberglass Market |
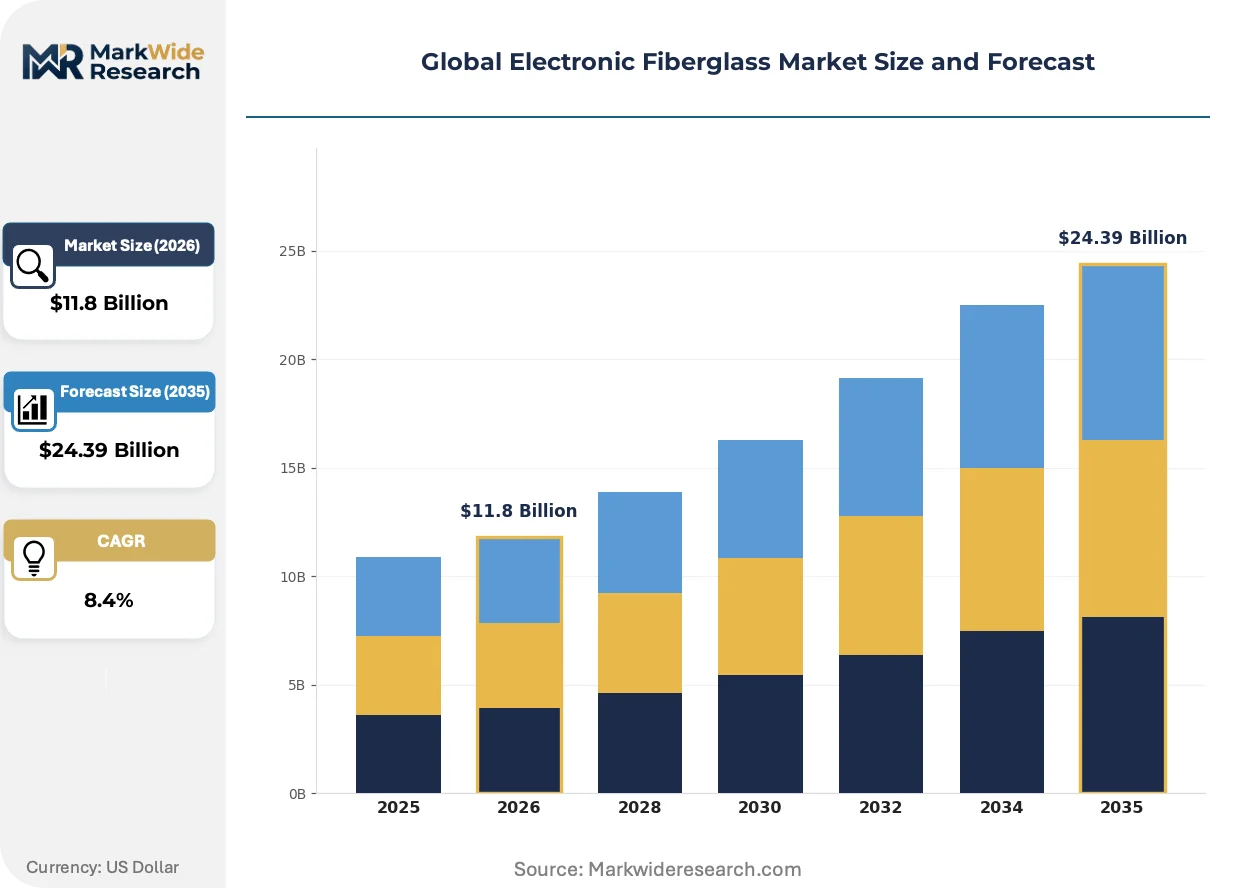
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Roving, Chopped Strands, Continuous Filaments, Mats, Cores Technology: E-Glass, S-Glass, AR-Glass, C-Glass, Quartz Glass Application: Printed Circuit Boards, Electrical Insulation, Packaging, Automotive Components, Marine Equipment End User Industry: Telecommunications, Consumer Electronics, Aerospace, Renewable Energy, Construction |
| Companies Covered | Taishan Fiberglass, China Jushi Co., Ltd., Chongqing Polycomp International Corp., Saint-Gobain Vetrotex, Nittobo, Taiwan Glass Group, Owens Corning, Nippon Electric Glass Co., Ltd., AGY Holding Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Fiberglass Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine glass chemistry and manufacturing processes. Producers must simultaneously manage purity escalation, energy transition, and specification fragmentation.
Ultra-fine E-Glass filaments below 5 microns are displacing conventional 7-9 micron weaves in high-density interconnect applications. Advanced packaging houses in Taiwan and South Korea now specify sub-5 micron glass for 10+ layer stack-ups. This specification compression is displacing standard-weave capacity and forcing loom retrofits among Japanese and Taiwanese weavers.
EU F-Gas Regulation phase-down schedules are tightening emissions standards for melting furnace operations. Operators must convert oxy-fuel combustion systems or face carbon border adjustment exposure. German and Dutch fiberglass producers are accelerating electric boosting retrofits to maintain EU market access.
Consolidated procurement by Asian PCB laminators is compressing supplier bases and extending contract durations. Tier-one laminate manufacturers in China now negotiate 24-36 month offtake agreements with preferred furnace operators. This buyer concentration is most visible in Jiangsu province, where three laminate groups control 60% of regional glass consumption.
Global Electronic Fiberglass Market Segmentation
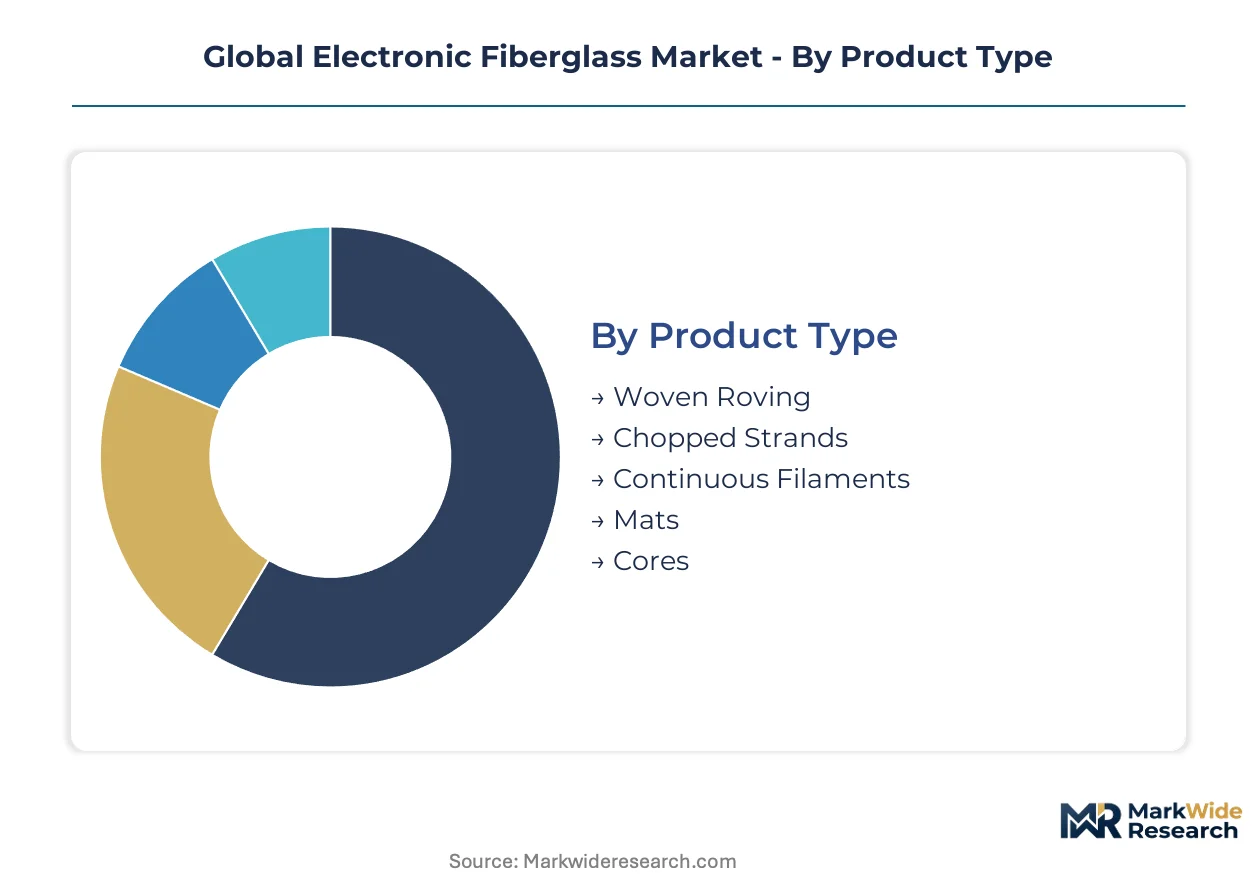
Electronic fiberglass segments flow through distinct channel configurations that shape margin capture and specification requirements. Product form and glass chemistry determine whether material moves through laminate distributors, direct mill relationships, or specialized composite converters serving PCB and automotive OEMs.
Product Type:
Channel configurations diverge sharply between continuous supply agreements for high-volume laminate producers and spot-market purchases for specialized composite molders.
- Woven Roving:Bidirectional fabric constructions from 200 to 800 g/m² provide structural reinforcement for multilayer PCB substrates and electrical insulation panels. Taiwan and South Korean laminate manufacturers pull the majority of high-specification roving through 24-36 month offtake contracts with Jiangsu province furnace operators.
- Chopped Strands:Discontinuous filaments 3-25mm in length, sized for thermoplastic compatibility, feed injection molding and compression molding channels. Automotive OEMs in Germany and Japan specify flame-retardant chopped strands for electric vehicle battery housings, bypassing traditional electronics distributors.
- Continuous Filaments:Unidirectional tows and yarns serve specialized aerospace and satellite antenna applications through qualified supplier programs.
- Mats:Random-oriented chopped strand constructions target lower-cost electrical insulation and building materials channels.
- Cores:Three-dimensional spacer fabrics and honeycomb structures serve marine and wind blade applications requiring sandwich panel construction.
Woven Roving dominates installed base across PCB laminate supply chains. Chopped Strands is where expansion concentrates as automotive thermal protection specifications multiply.
Technology:
Cost tiers separate certified low-alkali formulations from commodity borosilicate grades, with premium chemistry commanding 40-60% price elevation.
- E-Glass:Calcium-alumina-borosilicate composition with dielectric constant near 6.6 and dissipation factor below 0.001 serves high-frequency PCB laminates and general electrical insulation. China's NMPA material certification and EU REACH compliance are forcing reformulation of traditional boron-rich variants to meet stricter workplace exposure thresholds.
- S-Glass:Magnesia-alumina-silicate chemistry delivers tensile modulus exceeding 85 GPa for aerospace and satellite antenna substrates where dimensional stability under thermal cycling is critical. Satellite manufacturers in the US and Europe specify S-Glass for deployable antenna structures, though T800-grade carbon fiber is displacing share in some applications.
- AR-Glass:Zirconia-modified alkali-resistant formulations target cementitious construction composites outside core electronics channels.
- C-Glass:Calcium-borosilicate chemistry with superior acid resistance serves chemical processing equipment and battery separator applications.
- Quartz Glass:Ultra-high-purity silica formulations command extreme premium positioning for semiconductor wafer handling and optical fiber preform markets.
E-Glass dominates installed base across telecommunications and consumer electronics laminates. S-Glass is where expansion concentrates for next-generation satellite constellations and defense platforms.
Application:
Application mix tracks directly to customer scale, with PCB laminators consolidating procurement and automotive molders fragmenting across tiered supply bases.
- Printed Circuit Boards:Multilayer laminate cores and prepreg constructions require ultra-low Dk/Df E-Glass for 5G base station and AI accelerator substrates. Substrate miniaturization in advanced packaging is compressing filament diameter specifications below 5 microns for 10+ layer stack-ups.
- Electrical Insulation:Transformer bushings, motor slot liners, and high-voltage switchgear components utilize mica-glass composites and woven tapes. Grid infrastructure upgrades in Germany and transmission expansion in India are pulling volume through electrical OEM channels.
- Packaging:Specialized electronic component shipping materials and moisture barrier bags represent niche demand outside structural applications.
- Automotive Components:Under-hood electrical housings and battery module enclosures specify flame-retardant glass-reinforced thermoplastics. OEM thermal runaway protection mandates are opening volume offtake outside traditional electronics markets.
- Marine Equipment:Radar domes, antenna housings, and hull structures utilize corrosion-resistant glass composites for recreational and commercial vessels.
Printed Circuit Boards dominates installed base across laminate fabrication capacity. Automotive Components is where expansion concentrates as electrification mandates reshape material specifications.
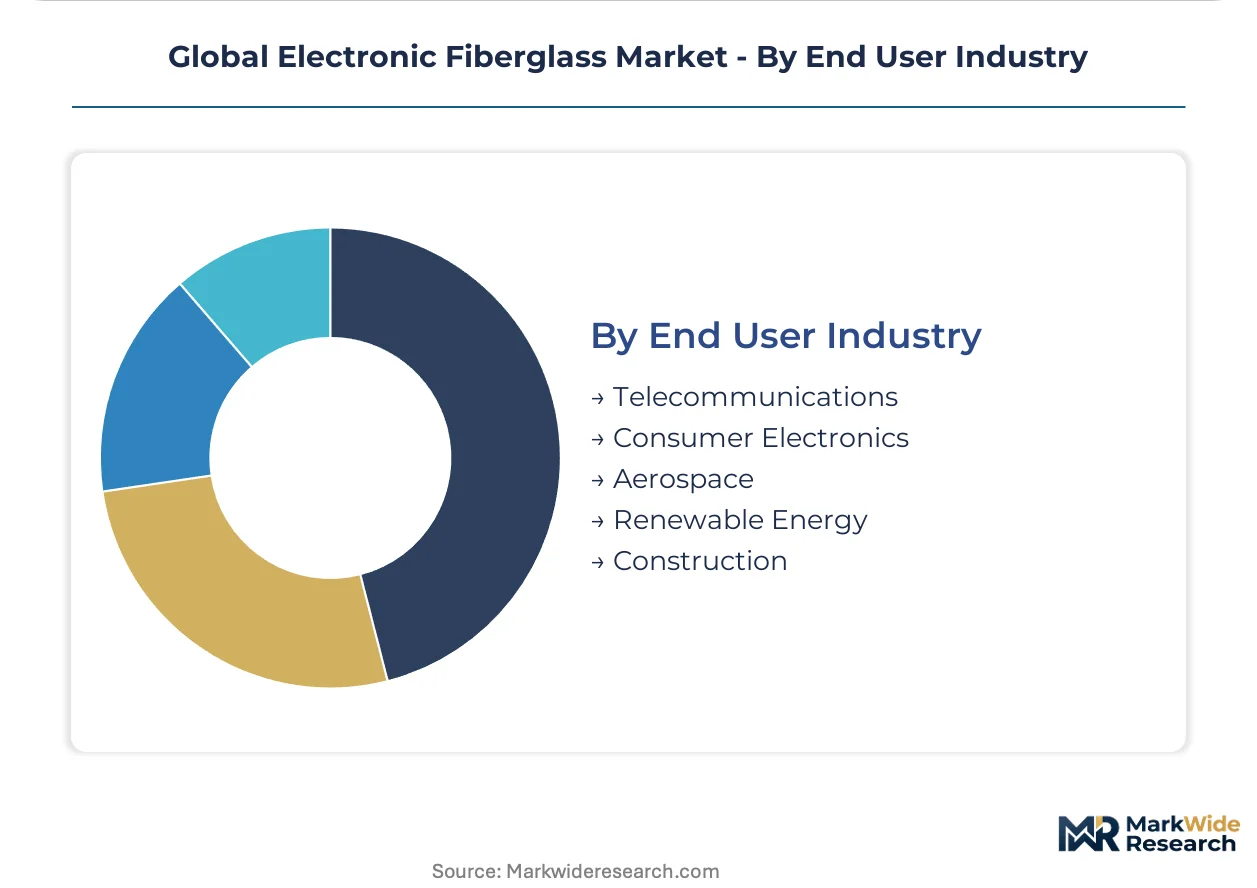
End User Industry:
Customer type determines contract structure, with telecommunications infrastructure builders negotiating multi-year supply agreements and construction buyers operating on project-based procurement.
- Telecommunications:5G base station deployment in China, South Korea, and Germany pulls high-frequency laminate substrates requiring ultra-low Dk/Df E-Glass formulations. Network equipment manufacturers specify certified material lots with full traceability for infrastructure projects.
- Consumer Electronics:Smartphone, tablet, and wearable device PCB laminators concentrate procurement among three to five preferred glass suppliers per manufacturing cluster. Taiwan and South Korean packaging houses drive specification compression toward sub-5 micron filament weaves.
- Aerospace:Satellite antenna substrates and radome structures specify S-Glass for dielectric transparency and thermal stability. Prime contractors maintain approved supplier lists with rigorous qualification protocols.
- Renewable Energy:Wind turbine blade manufacturers utilize glass cores and multiaxial fabrics for structural spar caps and shell constructions.
- Construction:Exterior insulation finish systems and geotechnical reinforcement employ AR-Glass for alkali resistance in cementitious matrices.
Telecommunications dominates installed base across infrastructure buildout cycles. Aerospace is where expansion concentrates for next-generation satellite constellation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese furnace operators command pricing leverage over European converters due to concentrated melting capacity in Jiangsu province, while German and Dutch producers absorb carbon border adjustment costs from EU F-Gas Regulation compliance.
China
5G base station deployment and AI accelerator substrate demand pull ultra-low Dk/Df E-Glass formulations through laminate manufacturers in Jiangsu and Guangdong provinces. NMPA material certification timelines extend 18-24 months for medical-grade substrates, filtering supplier pools. Taishan Fiberglass anchors supply through dedicated tank furnaces optimized for low-alkali formulations serving PCB laminators in the Yangtze River Delta cluster.
Germany
Telecommunications infrastructure buildouts for 5G networks and grid infrastructure upgrades drive high-frequency laminate and electrical insulation demand. ECHA restrictions on boron oxide workplace exposure under REACH accelerate certified low-alkali glass adoption among PCB laminators. Industrial concentration in North Rhine-Westphalia and Bavaria hosts furnace operators accelerating electric boosting retrofits to maintain EU market access.
South Korea
Advanced packaging houses specify sub-5 micron glass filaments for 10+ layer stack-ups in AI accelerator and high-density interconnect applications. MFDS medical device material standards govern implantable substrate certifications. Seoul Capital Area and Busan-Ulsan manufacturing corridors concentrate precision weaving capacity for ultra-fine filament specifications.
United States
Satellite constellation deployment and defense platform specifications sustain S-Glass demand for antenna substrates and radome structures. FAA and DOD qualification protocols maintain rigorous approved supplier lists for aerospace applications. Texas and California industrial corridors host prime contractors specifying dielectric transparency and thermal stability in deployable antenna structures.
India
PLI scheme subsidies for semiconductor packaging attract laminate producers to Gujarat and Tamil Nadu, creating greenfield glass demand for emerging PCB fabrication capacity. BIS standards govern electrical insulation material specifications for grid infrastructure expansion. Maharashtra and Karnataka industrial corridors concentrate procurement activity as telecommunications infrastructure buildouts accelerate.
Global Electronic Fiberglass Market Competitive Landscape
Concentration sits with furnace-scale producers controlling captive boron-alumina supply chains and dedicated tank furnace configurations. The vendor base stratifies across three tiers: integrated chemical-glass conglomerates with upstream mineral control, specialized fiberglass manufacturers with precision drawing capabilities, and regional weavers dependent on spot filament purchases. Dominant competitive moves include oxy-fuel retrofit investments for carbon compliance and 24-36 month offtake contract negotiations with consolidated Asian PCB laminators.
Among Chinese integrated producers, China Jushi Co., Ltd. and Taishan Fiberglass exemplify the furnace-scale archetype with upstream chemical integration, while Owens Corning represents North American logistics-network positioning for telecommunications infrastructure lead time reduction. Taiwan Glass Group and Nippon Electric Glass Co., Ltd. occupy precision-weaving specialist positions serving advanced packaging specification compression in East Asian manufacturing clusters.
| Leading Market Players |
|---|
| Taishan Fiberglass |
| China Jushi Co., Ltd. |
| Chongqing Polycomp International Corp. |
| Saint-Gobain Vetrotex |
| Nittobo |
| Taiwan Glass Group |
| Owens Corning |
| Nippon Electric Glass Co., Ltd. |
| AGY Holding Corp |
| Others |
Supply & Pricing Matrix
Furnace-scale economies in Jiangsu province concentrate melting capacity among operators running 100,000+ ton-per-year tank configurations, compressing unit economics and establishing price floors that commodity-scale weavers cannot match. This scale asymmetry rewards integrated producers with captive boron-alumina supply chains while squeezing margin capture for downstream converters dependent on spot filament purchases.
Pricing Analysis
Configured-to-order E-Glass formulations for medical-grade substrates command 40-60% premiums over standard borosilicate grades due to NMPA certification requirements and extended qualification timelines. Contract-based long-term offtake agreements dominate high-volume channels, with 24-36 month durations locking in laminate manufacturers while spot markets serve specialized composite molders. Price differentiation rests on REACH compliance tier and filament diameter precision, with sub-5 micron specifications attracting premium positioning. Cost compression in standard-weave grades intensifies as Chinese furnace operators expand capacity, while aerospace S-Glass segments maintain pricing resilience against T800 carbon fiber substitution pressure. Automotive OEMs exhibit highest price sensitivity for chopped strand volumes, whereas satellite manufacturers prioritize dielectric performance over unit cost.
Supply Chain Analysis
Inventory buffers for boron compounds rarely exceed 60-90 days given concentrated extraction from Turkish and Argentine deposits, exposing furnace operators to raw material volatility. Melting capacity clusters in China's Jiangsu province, with secondary concentrations in Germany's North Rhine-Westphalia and the US Southeast drawing from these feedstocks. Raw material dependencies center on boron oxide, alumina hydrate, and silane coupling agents for sizing chemistry. Single-source vulnerability concentrates in Jiangsu's tank furnace corridor, where three laminate groups control 60% of regional glass consumption. Distribution runs through direct mill relationships for tier-one PCB laminators and specialized composite converters serving automotive OEMs, with spot channels filling specialized aerospace and medical device requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber substitution in satellite antenna substrates and aerospace radome applications threatens S-Glass premium positioning, forcing incumbents to defend dielectric performance advantages while expanding into thermal protection applications where glass retains cost-thermal runaway trade-offs.
For Market Incumbents: Compound furnace-scale advantages by accelerating oxy-fuel retrofits ahead of EU F-Gas Regulation phase-down schedules, locking in carbon-compliant capacity while competitors absorb border adjustment costs. Backward integration into boron compound sourcing through offtake agreements with Turkish and Argentine extractors reduces input volatility exposure. Prioritize sub-5 micron filament drawing capabilities to capture specification compression in Taiwan and South Korean advanced packaging channels, defending against precision-weaving specialists. For New Entrants and Emerging Players: Anchor in India's Gujarat and Tamil Nadu corridors where PLI scheme subsidies for semiconductor packaging are attracting greenfield laminate capacity without incumbent furnace presence. Target medical-grade substrate certification gaps where NMPA timelines extend 18-24 months, creating qualification moats against commodity-scale competitors. Pursue joint development agreements with electric vehicle battery housing specialists seeking flame-retardant chopped strand alternatives to metal enclosures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among furnace operators with 24-36 month offtake contracts and captive chemical integration, offering visibility through telecommunications infrastructure cycles. Five-to-ten year viability favors producers with demonstrated REACH and NMPA certification pathways and electric boosting retrofit completion. Acquisition targets should demonstrate precision drawing capabilities below 7 micron diameter and established qualified supplier status with aerospace prime contractors. Monitor T800 carbon fiber pricing spreads against S-Glass as the critical inflection signal for satellite antenna substrate specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | EU F-Gas Regulation compliance secures market access against carbon border adjustments. |
| Backward Integration into Boron Sourcing | Turkish and Argentine offtake agreements stabilize input costs against extraction quota fluctuations. |
| Sub-5 Micron Filament Capacity Expansion | Taiwan and South Korean advanced packaging specifications drive premium capture in AI accelerator substrates. |
| NMPA Medical-Grade Certification Investment | Eighteen-to-twenty-four month approval timelines filter competitor pools for implantable device glass. |
| Automotive Thermal Protection Partnership | Electric vehicle battery housing mandates open volume channels outside traditional electronics procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from fiberglass producers, ECHA REACH registration databases, and NMPA medical device material certification records. Plant managers at Jiangsu province furnace operations, procurement leads at Taiwan and South Korean laminate manufacturers, and technical R&D directors at silane coupling agent suppliers provided operational validation. Bottom-up capacity assessments across tank furnace configurations triangulate against top-down demand modeling from PCB layer-count projections and 5G base station deployment pipelines.
Segmentation dimensions modeled include glass chemistry tier, product form, filament diameter specification, end-use application, and regional regulatory cluster across the analysis window. CAGRs derive from elasticity-adjusted demand curves for telecommunications infrastructure, automotive electrification mandates, and satellite constellation deployment schedules. Forecast inputs incorporate furnace utilization rates from Chinese industry association disclosures and boron compound extraction quota announcements from Turkish state mining authorities.
Material uncertainties — boron supply disruption, REACH reformulation timelines, carbon fiber substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding NMPA certification pathway stability and EU F-Gas Regulation enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Renewable Carbon Fibers Market
Fibers
Viscose Market
Fibers
Europe Carbon Fiber Market
Fibers
Thermoformed Fiber Market
Fibers
Fiberglass Resin Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
North America Carbon Fiber Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Global Basalt Fiber Market
Fibers
North America Nanofiber Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Bioglass Fiber Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Viscose Filament Yarn Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market