
 Saudi Arabia Drilling Rigs Market | 2026-2036
Saudi Arabia Drilling Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Drilling Rigs Market Analytics
Multi-source contracting for jack-up and land rig fleets is hardening as NOC procurement teams diversify supplier rosters beyond legacy single-source arrangements. Arabian Drilling Company anchors the onshore segment through its long-standing Aramco partnership. ARO Drilling competes aggressively in offshore shallow-water programs with its expanded jack-up fleet. ADES Holding Company leverages its modular rig platform to capture marginal field contracts that larger incumbents often bypass.
A drilling rig is a mobile or fixed platform housing hoisting, rotating, and circulation systems capable of boring wells from surface to target depth, typically rated by maximum hook load, mast height, and horsepower output; its primary purpose is to create boreholes for hydrocarbon extraction, geothermal access, or subsurface investigation. Onshore rigs dominate the installed base due to the scale of Saudi Arabia's super-giant terrestrial fields, though offshore rigs command premium day rates in the Arabian Gulf. Smart rigs represent the fastest-growing technology tier as automated pipe handling and real-time diagnostics reduce non-productive time. Directional drilling services capture expanding margin pools as lateral complexity increases in mature field redevelopment programs.
SFDA equipment safety mandates and Saudi Aramco's internal drilling standards shape rig specification requirements, while environmental regulators enforce emissions controls on diesel-powered rig packages operating in protected coastal zones. The Saudi Standards, Metrology and Quality Organization (SASO) implements technical regulations for imported drilling equipment that affect market access for non-domestic manufacturers. Stakeholders must monitor how Aramco's localization directives and domestic content requirements reshape supplier qualification criteria across the rig supply chain.
Market Dynamics
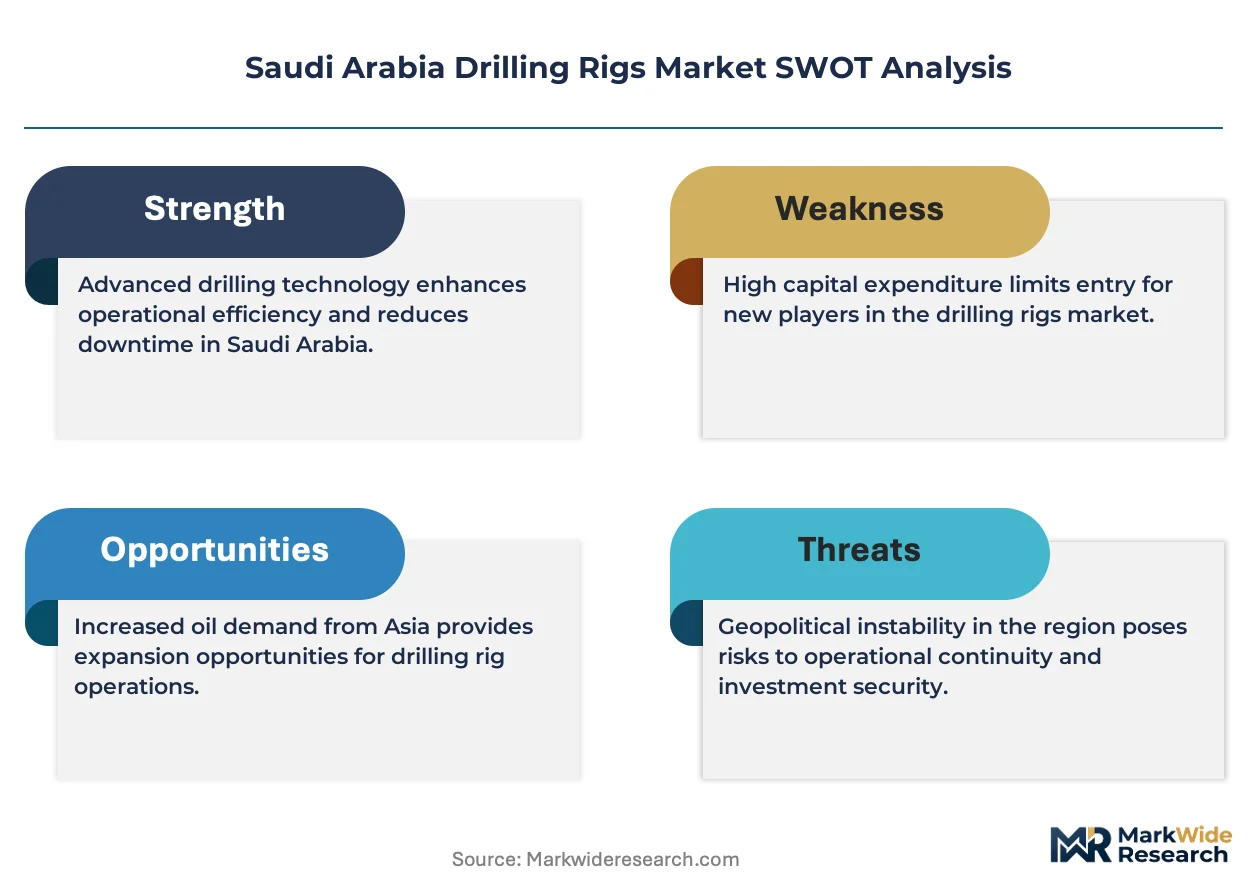
Aramco's upstream capital expansion is compressing rig deployment timelines while tightening localization mandates reshape supplier qualification criteria across the Eastern Province cluster.
Growth Catalysts
- SFDA Equipment Certification Mandates:Tighter safety protocols for hoisting and rotating systems are accelerating replacement cycles for aging rig fleets in coastal and onshore fields.
- Smart Rig Automation:Automated pipe handling and real-time diagnostics are reducing non-productive time, pushing operators toward technology-upgraded contracts.
- Eastern Province Field Concentration:Ghawar and Safaniya redevelopment programs concentrate demand in a single geography, creating procurement scale effects.
Market Restraints
- Steel Alloy Input Volatility:Mast and derrick fabrication depends on high-grade structural steel, exposing rig builders to commodity price swings.
- Offshore Jack-up Supply Concentration:Shallow-water premium rig availability clusters with a limited set of specialized fleet operators, constraining rapid expansion.
- SFDA-SASO Regulatory Overlap:Dual compliance pathways for imported equipment create certification friction and extend market access timelines.
Strategic Opportunities
- Marginal Field Modularization:Smaller reservoirs bypassed by super-rig operators present white space for compact, rapidly deployable rig platforms.
- Geothermal Exploration Adjacency:Subsurface investigation capabilities developed for hydrocarbon drilling transfer directly to Saudi geothermal resource assessment programs.
- Aramco Localization Directives:Domestic content requirements create procurement preference for in-country rig assembly and component sourcing.
Industry Challenges
- Directional Drilling Skill Scarcity:Lateral complexity in mature field redevelopment outpaces the supply of qualified wellbore engineers.
- Legacy Rig Integration Friction:Retrofitting automated systems onto conventional mast structures demands custom engineering and extends commissioning windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Drilling Rigs Market |
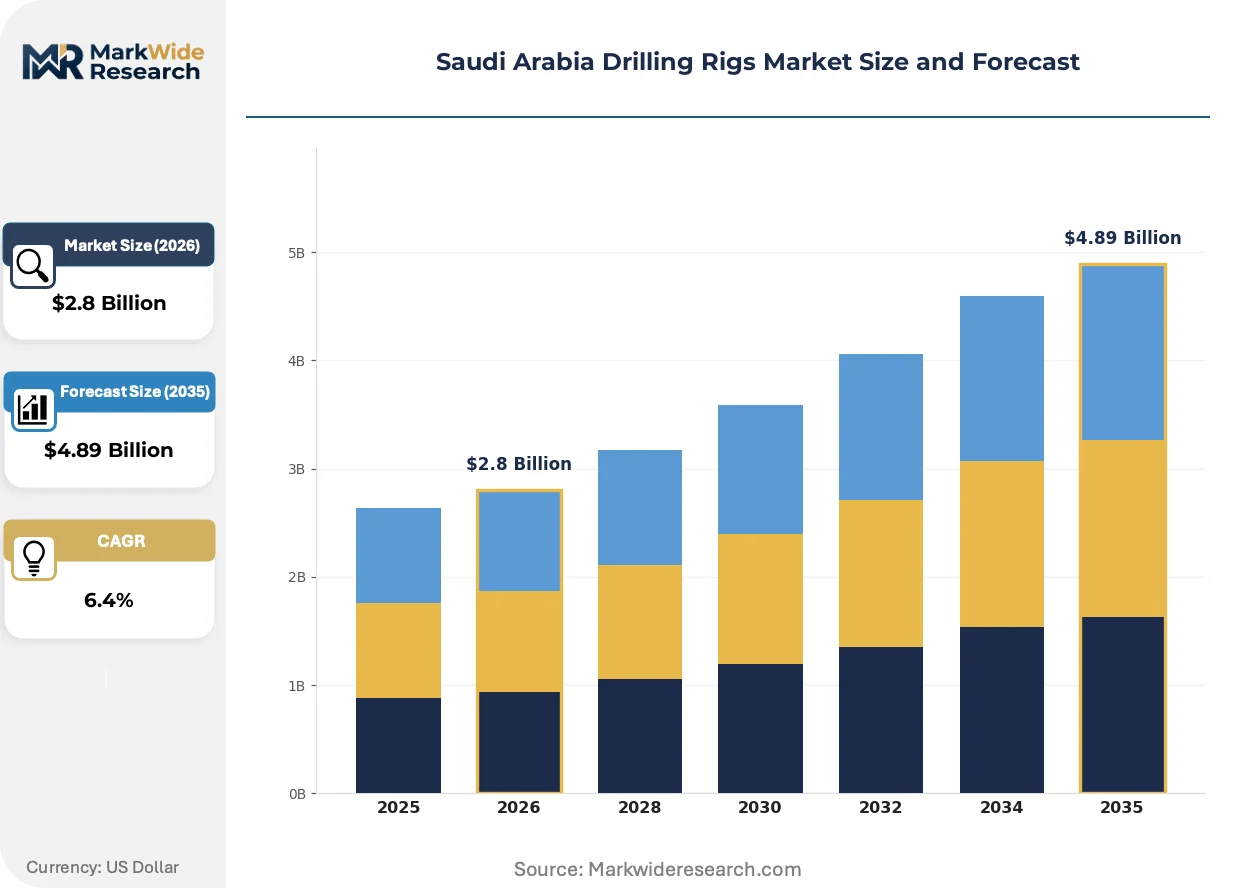
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Rigs, Offshore Rigs, Modular Rigs, Smart Rigs Service Type: Drilling Services, Maintenance Services, Inspection Services, Support Services Technology: Rotary Drilling, Directional Drilling, Horizontal Drilling, Plug and Abandonment End User: Oil Companies, Exploration Firms, Service Providers, Government Agencies |
| Companies Covered | Arabian Drilling Company, ARO Drilling, ADES Holding Company, Shelf Drilling Holdings Ltd, Saipem S.p.A., KCA Deutag Group, Noble Corporation plc, Schlumberger Limited, Halliburton Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Drilling Rigs Market Evolving Landscape
Digitalization of rig operations is compressing well construction timelines while environmental compliance hardens equipment specifications across Aramco's supplier base.
Smart rig systems are integrating machine learning-based predictive maintenance with automated tripping sequences. Aramco's drilling contractors are deploying these platforms fastest in high-volume onshore programs. This convergence is integrating real-time diagnostics directly into day-rate contracting structures, shifting supplier revenue toward performance-linked models.
SASO technical regulations for imported drilling equipment are tightening electromagnetic compatibility and structural load-testing requirements. Non-domestic rig manufacturers must now certify through Saudi-based testing facilities before market entry. Offshore jack-up suppliers face the steepest compliance ramps given the coastal zone environmental overlays.
Service unbundling is separating directional drilling packages from integrated rig contracts. Independent directional specialists are capturing margin pools previously retained by full-service rig operators. This fragmentation is most visible in Ghawar redevelopment programs where lateral complexity demands specialized geosteering expertise beyond standard rig crew capabilities.
Saudi Arabia Drilling Rigs Market Segmentation
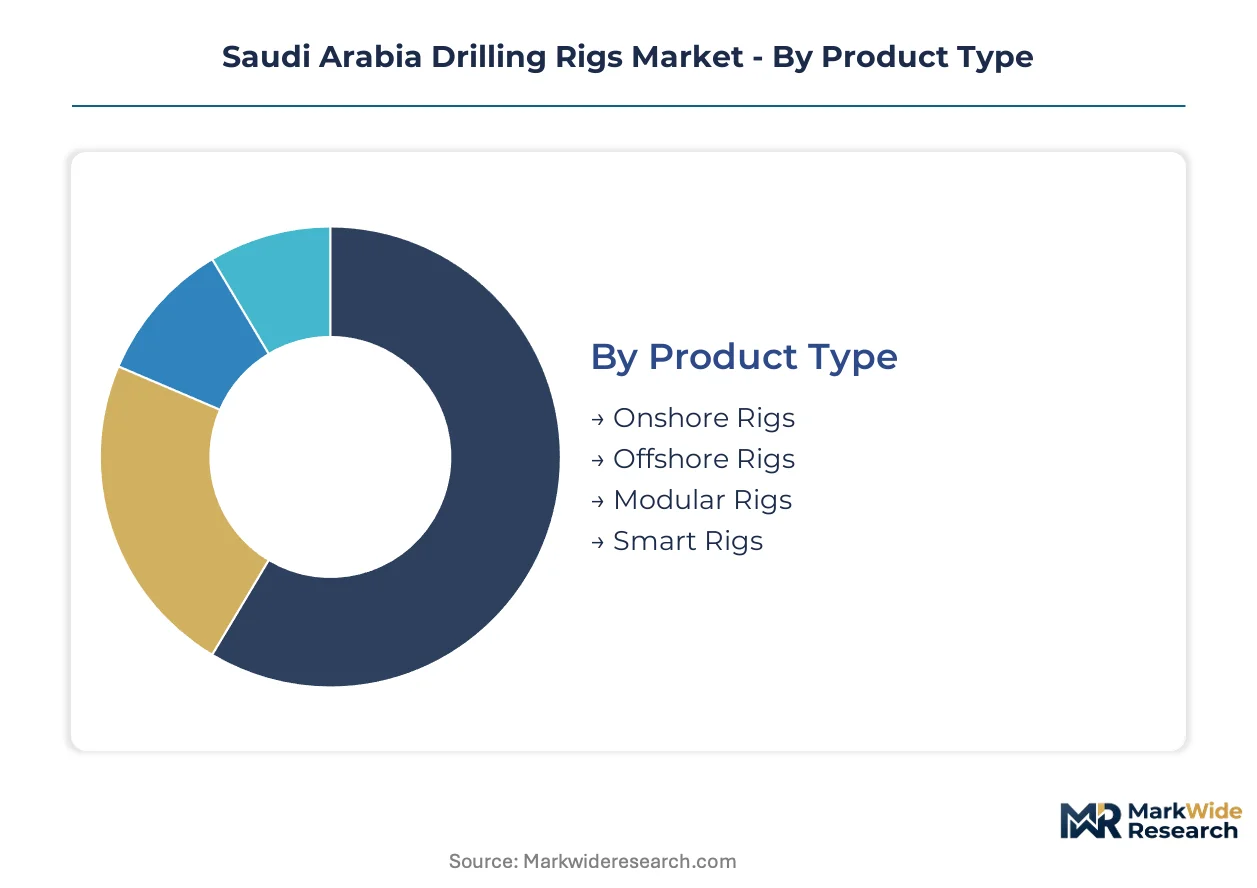
Saudi Arabia's drilling rigs market fragments across four distinct category axes. Each segmentation layer reveals how Aramco's procurement priorities and field development geography reshape supplier positioning and technology investment.
Product Type:
Buyers differentiate by field location, reservoir scale, and automation requirements rather than price alone.
- Onshore Rigs:These mast-mounted systems handle hook loads exceeding one million pounds across desert terrain. Ghawar field redevelopment concentrates demand in the Eastern Province, where super-giant reservoirs require continuous high-volume drilling. Volume sits with onshore rigs; growth tilts toward smart rigs.
- Offshore Rigs:Jack-up platforms with cantilevered drilling packages command premium positioning in Safaniya and Manifa shallow-water developments. SFDA coastal zone emissions mandates are hardening equipment specifications for diesel-powered packages operating near protected shorelines.
- Modular Rigs:Rapidly deployable skidded systems target marginal fields bypassed by super-rig operators. ADES Holding Company leverages this format to capture contracts that larger incumbents decline.
- Smart Rigs:Automated pipe handling and real-time diagnostics compress non-productive time. Aramco's drilling contractors deploy these platforms fastest in high-volume onshore programs.
Onshore rigs anchor the installed base; smart rigs are expanding most quickly as automation contracts reshape day-rate structures.
Service Type:
Procurement patterns track where Aramco externalizes versus internalizes capability across the well lifecycle.
- Drilling Services:Integrated rig crews execute borehole construction from spud to total depth. Arabian Drilling Company anchors this segment through its long-standing Aramco partnership across Ghawar and Khurais developments.
- Maintenance Services:Preventive overhaul of hoisting, rotating, and circulation systems extends rig operating life. Aging fleet replacement cycles concentrate demand in coastal fields where SFDA safety mandates accelerate equipment refresh.
- Inspection Services:Structural load testing and electromagnetic compatibility certification for SASO compliance. Non-domestic manufacturers must route equipment through Saudi-based testing facilities before market entry.
- Support Services:Logistics, camp management, and supply chain coordination for remote field operations. Eastern Province cluster density creates procurement scale effects for bundled support packages.
Drilling services capture the largest contract value; inspection services face the steepest compliance ramps.
Technology:
Technology selection correlates directly with reservoir maturity and lateral complexity requirements.
- Rotary Drilling:Conventional rotary table or top-drive systems for vertical wellbores in conventional reservoirs. Remains the workhorse technology for greenfield development in less complex formations.
- Directional Drilling:Steered bottom-hole assemblies with real-time geosteering for deviated trajectories. Skill scarcity for qualified wellbore engineers constrains expansion in Ghawar redevelopment programs.
- Horizontal Drilling:Extended-reach laterals maximizing reservoir contact in tight carbonate formations. Mature field redevelopment drives adoption as producers target bypassed oil zones.
- Plug and Abandonment:Specialized rigs and cementing packages for well decommissioning. SFDA well integrity regulations are tightening abandonment standards for aging coastal producers.
Rotary drilling dominates well count; horizontal drilling claims the steepest expansion trajectory.
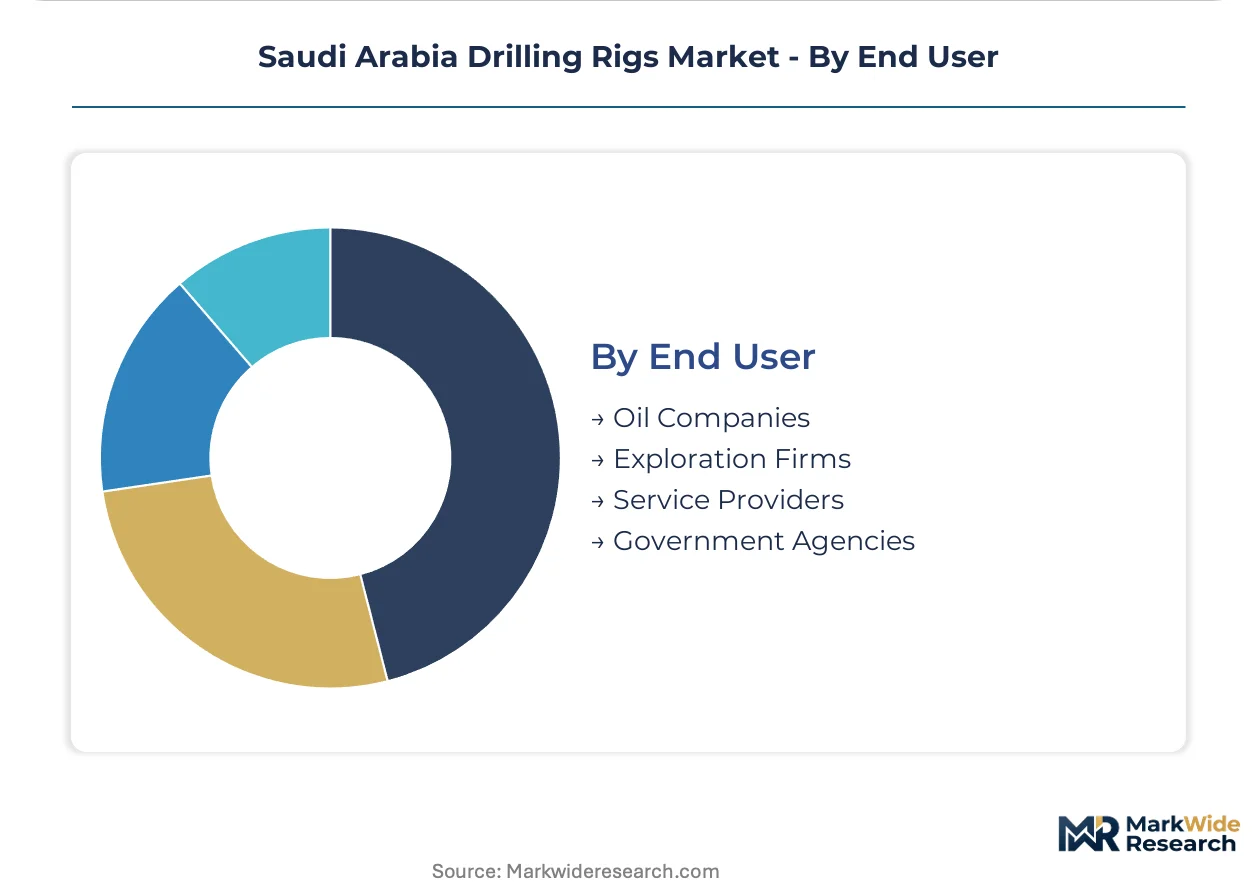
End User:
Customer type determines contract structure, localization requirements, and technology specification authority.
- Oil Companies:Saudi Aramco and joint venture operators specify rig requirements and award master service agreements. Aramco's localization directives reshape supplier qualification criteria across the Eastern Province cluster.
- Exploration Firms:Independent operators targeting unconventional or frontier acreage. Marginal field opportunities attract specialized contractors with modular rig platforms.
- Service Providers:Directional drilling specialists and independent equipment lessors unbundling from integrated rig contracts. These firms capture margin pools previously retained by full-service operators.
- Government Agencies:Saudi Geological Survey and geothermal exploration programs repurposing hydrocarbon drilling capabilities. Subsurface investigation technology transfers directly to renewable resource assessment.
Oil companies control procurement volume; service providers are gaining share fastest through unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in Jubail and Dammam anchor rig manufacturing capacity across the Arabian Gulf basin. Eastern Province hydrocarbon reserves concentrate procurement gravity where super-giant field redevelopment programs compress deployment timelines. SFDA coastal zone mandates and Aramco localization directives reshape supplier qualification criteria across this industrial corridor.
Eastern Province
Ghawar and Safaniya field developments command the majority of new rig orders as Aramco accelerates mature reservoir redevelopment. SFDA equipment safety protocols for hoisting systems are accelerating replacement cycles for aging coastal fleets. Dammam and Al-Khobar host the densest contractor clustering, where Arabian Drilling Company and ARO Drilling maintain operational headquarters and maintenance yards.
Riyadh
Administrative capital functions concentrate procurement decision-making and supplier qualification authority for national drilling programs. SASO technical regulations are administered through Riyadh-based certification facilities that non-domestic rig manufacturers must navigate before market entry. The Riyadh-Jubail industrial corridor supports steel alloy supply chains feeding mast and derrick fabrication for onshore rig assembly.
Western Region
Red Sea coastal exploration programs generate intermittent demand for modular rig platforms suitable for frontier acreage assessment. Environmental overlays on diesel-powered equipment operate with lighter regulatory density than Arabian Gulf zones, though SFDA baseline mandates still apply. Jeddah and Yanbu serve as logistics nodes for equipment import and coastal mobilization rather than primary drilling hubs.
NEOM Northwest
Geothermal resource assessment programs are repurposing hydrocarbon drilling capabilities for subsurface investigation of renewable energy potential. NEOM regulatory frameworks operate with distinct procurement pathways separate from Aramco's standard master service agreement structures. Tabuk province hosts early-stage exploration drilling where government agencies rather than oil companies specify rig requirements.
Saudi Arabia Drilling Rigs Market Competitive Landscape
Global majors compete with regional champions across fleet scale and localization compliance. The supplier base organizes into three tiers: integrated full-service operators with Aramco master agreements, specialized offshore jack-up providers, and modular rig specialists targeting marginal field white space. Consolidation pressure is intensifying as multi-source contracting hardens and domestic content requirements reshape qualification criteria. Competitive moves cluster around fleet automation upgrades and in-country assembly partnerships.
Within the integrated full-service tier, Arabian Drilling Company and ARO Drilling exemplify the dominant operational archetype through long-standing NOC relationships. ADES Holding Company occupies a distinct position among modular rig specialists, leveraging rapidly deployable platforms for reservoir scales that larger incumbents bypass. These three anchors represent how supplier positioning fragments across field complexity, fleet scale, and localization depth rather than converging on uniform service models.
| Leading Market Players |
|---|
| Arabian Drilling Company |
| ARO Drilling |
| ADES Holding Company |
| Shelf Drilling Holdings Ltd |
| Saipem S.p.A. |
| KCA Deutag Group |
| Noble Corporation plc |
| Schlumberger Limited |
| Halliburton Company |
| Others |
Value Network & Pricing Analysis
Aramco's master service agreement concentration with integrated full-service operators underwrites a contract-based long-term offtake model where day-rate structures bundle rig crews with automated equipment tiers. SFDA equipment certification mandates and SASO technical regulations for imported equipment create compliance cost layers that feed directly into supplier qualification premiums.
Pricing Analysis
After-sales service bundling separates integrated rig contracts from unbundled directional drilling packages where independent specialists now capture standalone margin pools. Three-tier pricing structure across premium smart-rig automation, standard mast-mounted systems, and economy modular platforms reflects certification grade and localization depth. Cost compression in standard onshore tiers is intensifying because Aramco's multi-source contracting hardens procurement leverage. Marginal field operators show highest price sensitivity; super-giant field developers prioritize non-productive time reduction over day-rate minimization.
Supply Chain Analysis
SFDA-SASO regulatory overlap for hoisting and rotating system certification gates market access before fabrication contracts execute. High-grade structural steel supply concentrates in South Korea, Japan, and domestic Saudi steel clusters at Jubail. Mast and derrick fabrication draws from specialized alloy inputs, hydraulic control systems, and top-drive assemblies. Single-source vulnerability runs through jack-up cantilever packages where shallow-water fleet availability clusters with limited specialized operators. Distribution runs through Dammam and Al-Khobar maintenance yards serving the Eastern Province field cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA equipment safety mandates have erected a cost-of-compliance moat where certified incumbent suppliers command procurement preference and replacement-cycle acceleration locks out unqualified competitors.
For Market Incumbents: Anchor fleet automation upgrades to capture performance-linked day-rate contracts as Aramco compresses well construction timelines. Deepen in-country assembly partnerships to satisfy localization directives and defend against modular rig specialists targeting marginal field white space. Certification investment in Saudi-based testing facilities represents the priority lever for maintaining master service agreement positioning. For New Entrants and Emerging Players: NEOM geothermal exploration programs in Tabuk province open a window for subsurface investigation capability providers repurposing hydrocarbon drilling technology. Target government agency procurement pathways that operate outside Aramco's standard contracting structures. Marginal field modularization presents the most penetrable segment for rapidly deployable skidded platforms bypassed by super-rig operators. For Investors and Strategic Acquirers: The window for entry favors directional drilling specialists with geosteering expertise as service unbundling fragments integrated rig contracts. Long-term viability hinges on technology transfer capabilities spanning hydrocarbon and renewable subsurface applications. Watch Aramco localization directive enforcement intensity as the inflection indicator for domestic content requirement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Rig Fleet Automation | Machine learning-based predictive maintenance compresses non-productive time in Ghawar high-volume programs. |
| In-Country Assembly Partnership | Domestic content requirements reshape supplier qualification criteria across the Eastern Province cluster. |
| Directional Drilling Capability Buildout | Lateral complexity in mature field redevelopment outpaces supply of qualified wellbore engineers. |
| Modular Rig Platform Expansion | Compact rapidly deployable systems capture marginal field contracts larger incumbents bypass. |
| Geothermal Technology Transfer | Subsurface investigation capabilities developed for hydrocarbon drilling apply to Saudi renewable assessment. |
Research Methodology
Independent corroboration across drilling contractor operations directors, Aramco procurement specialists, and SFDA certification officials underwrites the qualitative findings. Primary fieldwork with rig fleet managers, maintenance yard supervisors, and directional drilling engineers combined with secondary validation from SASO technical regulations, customs import records, and Aramco supplier qualification databases. Bottom-up rig deployment tallies and top-down capital expenditure analysis triangulate market sizing.
Comparable historical rig deployment cycles anchored the forecast window to replacement-driven demand patterns across the projection horizon. The analytical framework models product type, service tier, technology complexity, and end-user procurement authority as segmentation dimensions. CAGRs derive from rig day-rate trajectory analysis and capital program commitment visibility. Forecast inputs incorporate SFDA equipment refresh mandates and Aramco localization directive enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for smart rig automation penetration would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and steel alloy input stability. A model refresh is warranted upon material change in Aramco upstream capital allocation or SFDA certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Colombia Oil and Gas Downstream Market