
 Europe Digital Oilfield Market | 2026-2036
Europe Digital Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Oilfield Market Foresight
The EU Green Deal is restructuring investment priorities across European upstream operations, compelling operators to deploy emissions-tracking digital infrastructure. Schlumberger Limited leverages its subsurface intelligence platforms to anchor long-term contracts with North Sea producers. Baker Hughes Company differentiates through integrated turbomachinery diagnostics that sustain operational uptime under methane-reduction mandates. Siemens AG competes on industrial edge computing architectures that dominate onshore processing automation in the Netherlands and Germany.
Digital oilfield denotes the integration of sensor networks, data analytics platforms, and automated control systems to optimize hydrocarbon extraction through real-time reservoir characterization and predictive equipment maintenance. IoT-enabled downhole monitoring now represents the most capital-intensive technology layer, while cloud computing deployments are expanding fastest among independent North Sea operators seeking scalable infrastructure without heavy on-premises investment. Advanced Analytics applications in production monitoring command premium pricing due to their direct linkage with recovery-rate improvements and regulatory compliance verification.
REACH and the EU F-Gas Regulation shape equipment standards and chemical disclosure requirements for digital instrumentation deployed across European basins, while ECHA substance restrictions influence sensor material selection and supply chain qualification. Norway's Petroleum Safety Authority and the UK North Sea Transition Authority impose functional safety standards that drive demand for certified automation architectures. Stakeholders must weigh the capital efficiency of hybrid deployment models against tightening EU methane-performance benchmarks as project sanctioning criteria evolve.
Market Dynamics
The EU Green Deal is compressing capital allocation timelines across European upstream operations, forcing operators to reconfigure digital infrastructure around real-time emissions verification rather than incremental production optimization.
Growth Catalysts
- EU F-Gas Regulation:Mandates for fluorinated gas monitoring are compelling offshore platforms to deploy continuous leak-detection sensor networks.
- North Sea decommissioning wave:Aging infrastructure requires predictive maintenance systems to extend asset life while minimizing manned interventions.
- Subsea fiber optics:Distributed acoustic sensing technology enables reservoir characterization at depths previously inaccessible to conventional monitoring.
Market Restraints
- Specialized component concentration:Subsea pressure-tolerant electronics rely on a narrow supplier base concentrated in Norway and Scotland.
- REACH substance restrictions:ECHA candidate list substances limit material options for downhole sensor housings, extending qualification cycles.
- Cloud latency limitations:Real-time well control demands edge computing architectures that replicate cloud functionality at platform level.
Strategic Opportunities
- Netherlands onshore processing:Groningen field transition creates demand for digital abandonment and site remediation monitoring systems.
- EU AI Act compliance:Automated drilling decision systems require explainable AI architectures that European vendors can architect as first-movers.
- Carbon capture integration:Digital oilfield platforms can extend into CO2 injection monitoring, leveraging existing subsea sensor infrastructure.
Industry Challenges
- Subsea systems engineering talent:Deepwater automation expertise concentrates among retiring specialists in Stavanger and Aberdeen.
- Legacy SCADA integration:Proprietary protocols from 1990s platform installations resist interoperability with modern analytics stacks.
- Functional safety certification:IEC 61511 compliance for safety instrumented systems extends deployment timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Oilfield Market |
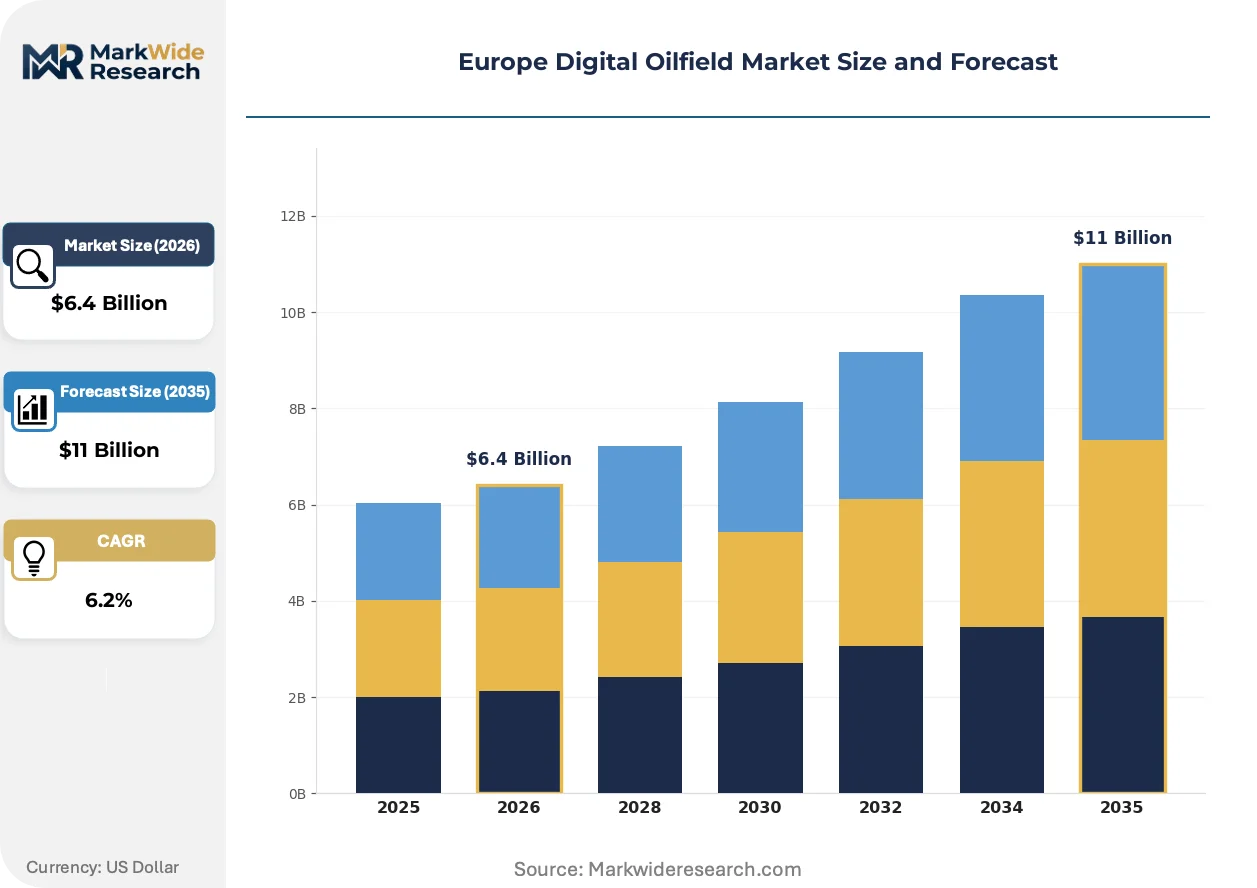
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Advanced Analytics, Cloud Computing, Automation End User: Oil Producers, Service Providers, Equipment Manufacturers, Geological Survey Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Production Monitoring, Asset Management, Data Integration, Remote Operations |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Siemens AG, ABB Ltd, Schneider Electric SE, National Oilwell Varco, Emerson Electric Co., Weatherford International plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Oilfield Market Shifts & Advancements
Digital twin architectures are displacing static reservoir models across European basins, enabling continuous recalibration against live production data. This shift is restructuring vendor relationships around platform-as-a-service contracts rather than perpetual license sales.
Edge-native artificial intelligence is expanding into subsea production control, processing sensor streams locally to eliminate round-trip latency to onshore data centers. Norwegian deepwater operators are deploying these architectures in the Barents Sea where fiber connectivity remains intermittent. The technology is expanding into methane detection workflows, compressing response times from minutes to seconds for regulatory compliance verification.
CSRD disclosure requirements are mandating granular Scope 3 emissions reporting from European oil and gas producers. This is forcing integration between production accounting systems and supply chain carbon tracking platforms. Offshore operators in Denmark and Germany are most affected, reconfiguring procurement specifications to favor vendors with certified emissions data APIs.
Performance-based contracting is displacing capital expenditure models for digital oilfield deployments. Independent North Sea producers are leasing predictive maintenance capabilities rather than owning software licenses, transferring operational risk to service providers. This pattern is most visible among UK continental shelf operators facing constrained balance sheets under windfall taxation regimes.
Europe Digital Oilfield Market Segmentation
Digital oilfield procurement in Europe fragments across technology layers, operational models, and end-user capabilities. Each segmentation axis reveals distinct supply-side concentrations and capital allocation patterns that shape vendor positioning across Norwegian deepwater, North Sea offshore, and continental onshore processing environments.
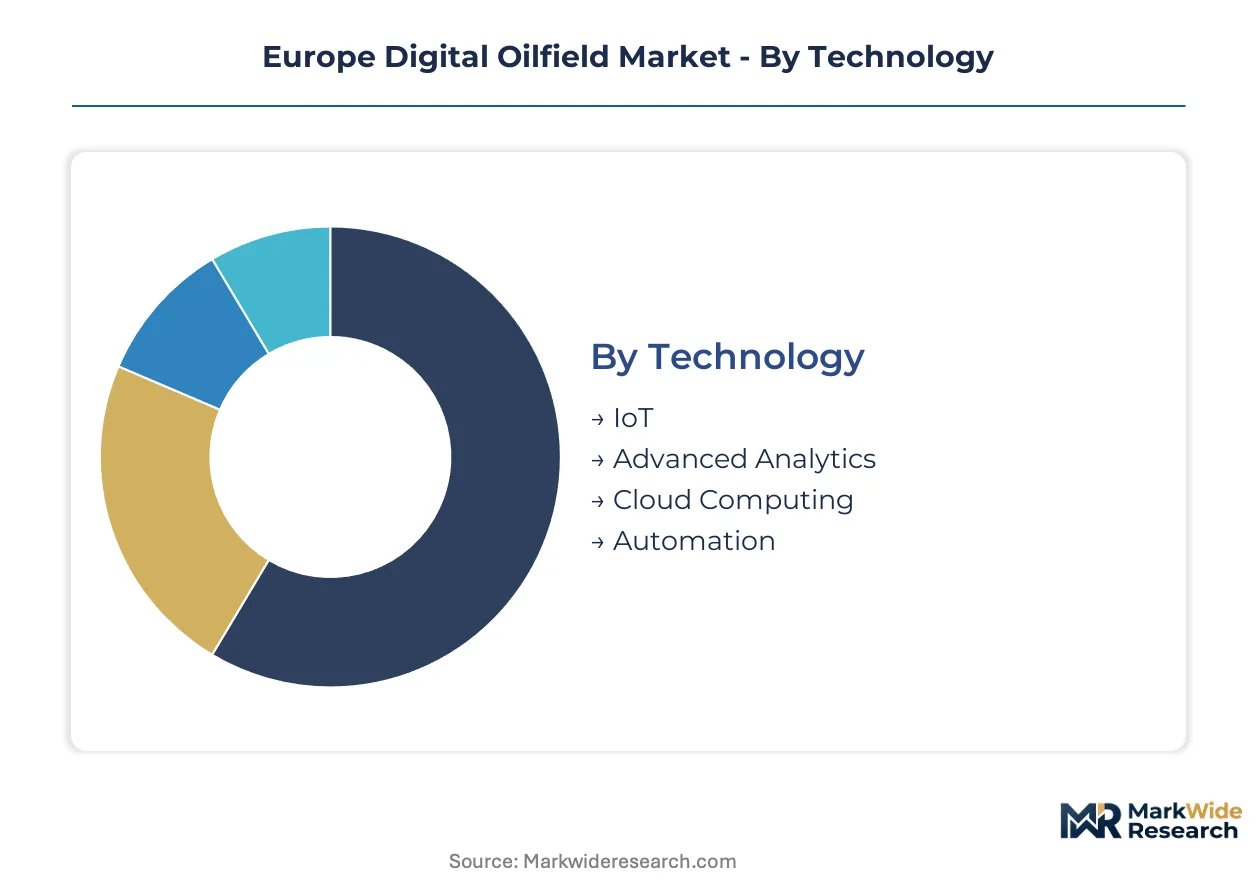
Technology:
Supply concentration in sensor hardware and analytics platforms concentrates procurement leverage among Norwegian and German industrial automation specialists.
- IoT:Downhole sensor networks and subsea monitoring arrays constitute the most capital-intensive technology layer. Norwegian deepwater operators in the Barents Sea and North Sea basins drive demand for pressure-tolerant electronics that withstand 300-bar environments, with REACH substance restrictions limiting housing material options and extending supplier qualification cycles.
- Advanced Analytics:Machine learning platforms for reservoir characterization and predictive maintenance command premium pricing due to direct linkage with recovery-rate improvements. UK continental shelf producers under windfall taxation regimes favor these tools to maximize output from aging assets without major capital redeployment.
- Cloud Computing:Scalable infrastructure adoption accelerates among independent North Sea operators seeking to avoid heavy on-premises investment.
- Automation:Safety instrumented systems and robotic intervention tools face IEC 61511 certification requirements that extend deployment timelines.
IoT absorbs the bulk of installed capacity; Advanced Analytics is expanding most quickly.
End User:
Customer type determines contract structure, with capital availability and in-house technical capability shaping vendor engagement models.
- Oil Producers:Majors and independents operating Norwegian deepwater licenses and UK North Sea assets constitute the primary demand source. These operators increasingly lease predictive maintenance capabilities through platform-as-a-service contracts rather than owning software licenses, transferring operational risk to service providers under constrained balance sheet conditions.
- Service Providers:Drilling contractors and integrated service companies deploy digital oilfield tools to differentiate performance-based contracts. These firms concentrate procurement in the Netherlands and Germany where industrial edge computing architectures support onshore processing automation.
- Equipment Manufacturers:Subsea hardware suppliers integrate sensor networks into original equipment specifications to meet EU F-Gas monitoring mandates.
- Geological Survey:National data repositories and academic consortia utilize digital twin architectures for basin modeling and resource assessment.
Oil Producers command the dominant share of technology deployment; Service Providers are gaining share fastest through performance-based contracting expansion.
Deployment:
Infrastructure configuration choices reflect connectivity constraints, data sovereignty requirements, and real-time control demands across European operating environments.
- On-Premises:Legacy platform installations in the UK and Norwegian North Sea retain substantial installed base, though proprietary SCADA protocols from 1990s deployments resist interoperability with modern analytics stacks. These systems persist where fiber connectivity remains unreliable or regulatory data localization requirements apply.
- Cloud-Based:Independent operators across Denmark and Germany favor scalable infrastructure without heavy capital commitment. CSRD disclosure requirements are forcing integration between production accounting systems and supply chain carbon tracking platforms, favoring cloud-native architectures with certified emissions data APIs.
- Hybrid:Split architectures balance sensitive reservoir data on-premises with computational workloads in cloud environments.
- Edge Computing:Platform-level processing eliminates round-trip latency for well control applications.
On-Premises retains the largest installed base; Cloud-Based deployments are climbing the fastest among capital-constrained independents.
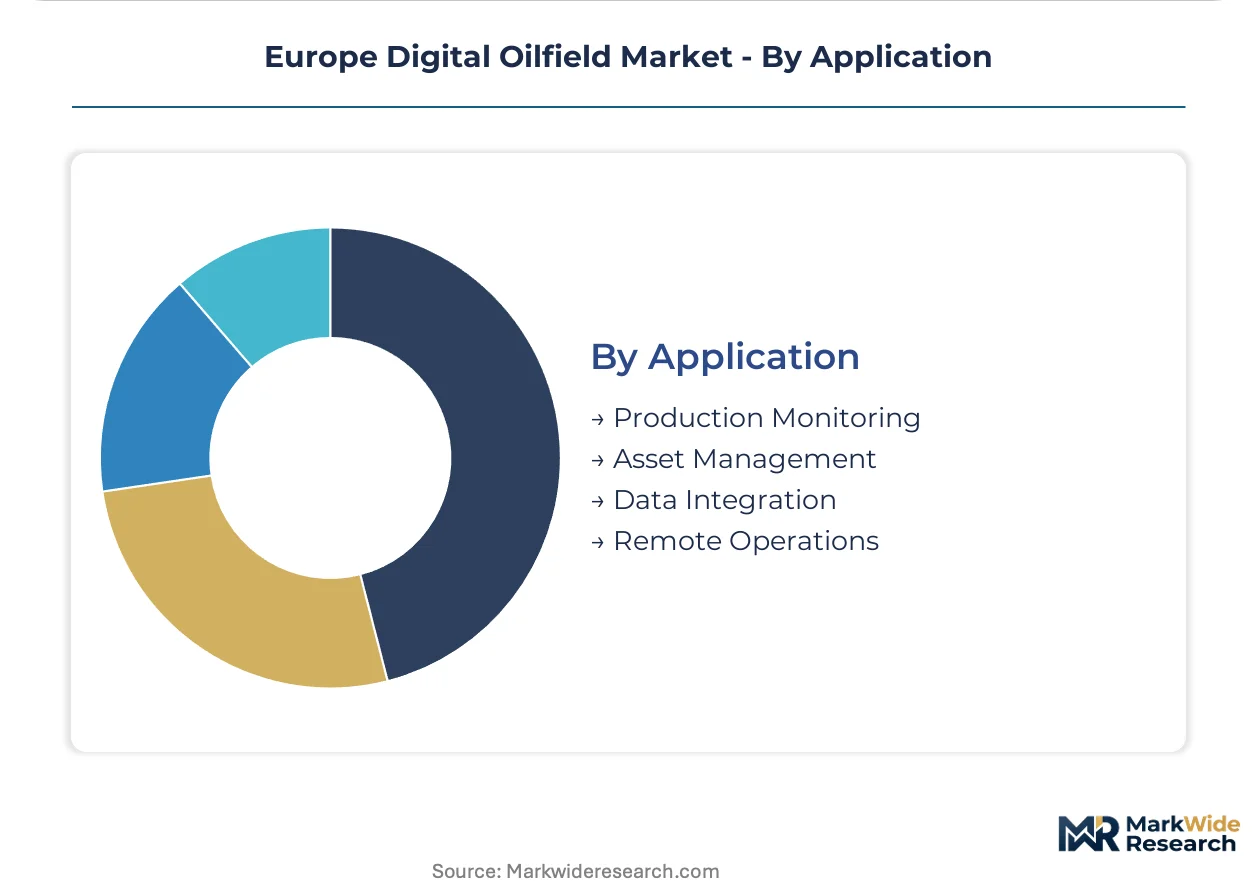
Application:
Functional use case segmentation aligns with regulatory compliance priorities and asset lifecycle stage across European basins.
- Production Monitoring:Real-time reservoir characterization and flow assurance systems dominate capital allocation. Norwegian operators deploy distributed acoustic sensing through subsea fiber optics to characterize reservoirs at depths previously inaccessible, with EU Green Deal emissions-verification requirements restructuring investment toward continuous monitoring infrastructure.
- Asset Management:Predictive maintenance platforms extend asset life during the North Sea decommissioning wave. Aging infrastructure requires these systems to minimize manned interventions while maintaining output, with performance-based contracting transferring operational risk from operators to service providers.
- Data Integration:Unified platforms consolidating seismic, production, and maintenance data face legacy protocol interoperability challenges.
- Remote Operations:Reduced-manning platform concepts accelerate adoption in high-cost labor environments.
Production Monitoring captures the dominant technology investment; Asset Management is gaining share fastest amid decommissioning timelines and methane-reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe produces minimal hydrocarbons relative to its consumption, creating asymmetric investment patterns where Norwegian and UK operators deploy capital-intensive digital infrastructure while continental demand centers import technology services. The regional market fragments between deepwater production zones in the North Sea and onshore processing hubs in the Netherlands and Germany.
Norway
Barents Sea and North Sea deepwater licenses drive demand for pressure-tolerant subsea electronics that withstand 300-bar environments. The Petroleum Safety Authority imposes functional safety standards that extend IEC 61511 certification timelines for automation architectures. Stavanger anchors the regional subsea engineering talent pool, though demographic pressures concentrate expertise among retiring specialists.
United Kingdom
UK continental shelf operators under windfall taxation regimes favor performance-based contracting for predictive maintenance platforms to transfer operational risk. The North Sea Transition Authority mandates emissions-verification infrastructure that restructures capital allocation toward continuous monitoring systems. Aberdeen retains legacy platform installations where proprietary SCADA protocols from 1990s deployments resist interoperability with modern analytics stacks.
Germany
Industrial edge computing architectures dominate onshore processing automation, with REACH substance restrictions limiting sensor housing material options and extending supplier qualification cycles. The EU AI Act creates compliance requirements for automated drilling decision systems that European vendors can architect as first-movers. Ruhr industrial clusters and Lower Saxony processing facilities concentrate procurement for turbomachinery diagnostics.
Netherlands
Groningen field transition generates demand for digital abandonment and site remediation monitoring systems as production winds down. CSRD disclosure requirements force integration between production accounting systems and supply chain carbon tracking platforms, favoring cloud-native architectures with certified emissions data APIs. Rotterdam and Amsterdam harbor zones concentrate service provider procurement for drilling contractors.
Denmark
Offshore operators face CSRD-mandated granular Scope 3 emissions reporting that reconfigures procurement specifications toward vendors with certified emissions data APIs. The EU F-Gas Regulation compels continuous leak-detection sensor network deployment across aging offshore infrastructure. Copenhagen-based independents favor cloud-based scalable infrastructure without heavy on-premises capital commitment.
Europe Digital Oilfield Market Competitive Landscape
The competitive structure tilts toward integrated energy technology conglomerates with subsurface intelligence platforms anchoring long-term North Sea contracts. Market concentration remains moderate, with industrial automation specialists competing against oilfield service majors for platform-level deployments. Two strategic archetypes dominate: full-stack subsurface intelligence providers and industrial edge computing architects. Competitive moves center on performance-based contracting structures and hybrid cloud-edge deployment partnerships that transfer operational risk from capital-constrained operators.
Within the integrated technology tier, Schlumberger Limited and Baker Hughes Company exemplify archetypes that leverage subsurface platforms and turbomachinery diagnostics respectively to sustain contract tenure under methane-reduction mandates. Siemens AG occupies a position among industrial automation specialists competing on edge computing architectures for continental onshore processing. These three entities represent the spectrum from oilfield-centric to industrial-automation-centric competitive positioning across European basins.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| National Oilwell Varco |
| Emerson Electric Co. |
| Weatherford International plc |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement specifications for emissions-verification infrastructure are forcing North Sea operators toward platform-as-a-service contracts rather than perpetual licenses, compressing supplier margins while extending contract tenures for compliant vendors.
Pricing Analysis
Value-based pricing anchored to methane-reduction outcomes and production uptime guarantees dominates North Sea contracting. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61511-certified safety systems from uncertified alternatives and basic monitoring packages. Cost compression in mid-tier edge computing bundles is intensifying because independent operators under windfall taxation demand risk-transfer mechanisms. Capital-constrained UK independents exhibit highest price sensitivity; Norwegian majors with long-term license security show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and Scottish suppliers of pressure-tolerant subsea electronics rated for 300-bar environments. Geographic supply concentration centers on Germany for industrial automation components and the Netherlands for turbomachinery diagnostics. Raw material dependencies include REACH-restricted sensor housing alloys, subsea fiber optic cables, and edge computing chipsets. Tariff exposure on Chinese-manufactured IoT components threatens cost structures. Distribution runs through Stavanger and Aberdeen engineering clusters serving platform-level integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Digital Oilfield Market operates as a cost-of-compliance story where EU F-Gas Regulation certification requirements erect barrier-to-entry moats favoring incumbents with pre-qualified sensor networks and established Petroleum Safety Authority relationships.
For Market Incumbents: Lock in long-term platform-as-a-service contracts with UK independents facing windfall taxation pressure, transferring operational risk while capturing recurring revenue streams. Deepen backward integration into subsea pressure-tolerant electronics manufacturing to offset supplier concentration in Norway and Scotland. Prioritize IEC 61511 certification maintenance as emerging entrants without safety instrumented systems expertise threaten mid-tier accounts. For New Entrants and Emerging Players: EU AI Act compliance requirements in Germany open a window for explainable AI architectures in automated drilling decision systems where European vendors can establish first-mover positioning. Target Netherlands onshore processing abandonment monitoring as Groningen field transition creates white-space demand unaddressed by offshore-focused incumbents. Pursue cloud-native carbon tracking API development as CSRD disclosure mandates reconfigure procurement specifications. For Investors and Strategic Acquirers: The window for entry favors industrial automation specialists with edge computing architectures applicable to methane-detection workflows. Long-term viability hinges on regulatory compliance infrastructure becoming embedded in operator procurement specifications. Acquisition target archetype: mid-cap subsea sensor integrators with REACH-qualified supply chains and existing Petroleum Safety Authority relationships. Watch for EU methane-performance benchmark tightening as inflection indicator accelerating replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-as-a-Service Contract Expansion | Transfers operational risk from capital-constrained UK independents to service providers under windfall taxation. |
| Backward Integration into Subsea Electronics | Captures margin from Norwegian and Scottish pressure-tolerant component suppliers while reducing lead time exposure. |
| EU AI Act Compliance Architecture Development | Positions German edge computing vendors as first-movers in explainable automated drilling decision systems. |
| CSRD-Aligned Carbon Tracking API Certification | Enables cloud-native procurement preference among Denmark and Germany offshore operators facing Scope 3 mandates. |
| IEC 61511 Safety Instrumented Systems Investment | Extends certification timelines into competitive moat against uncertified entrants in Norwegian deepwater markets. |
Research Methodology
Document review covered EU regulatory filings including ECHA substance restriction updates, Petroleum Safety Authority safety bulletins, and UK North Sea Transition Authority emissions guidelines, complemented by interviews with subsea engineering directors, platform automation managers, and procurement leads at integrated operators and independent producers. Secondary validation drew from customs trade data on subsea electronics imports, SEC filings of listed oilfield service providers, and EU Green Deal implementation progress reports. Bottom-up project pipeline analysis triangulated against top-down capital expenditure surveys across Norwegian, UK, Dutch, German, and Danish operating environments.
Segment-level outputs across technology layers, deployment models, end-user categories, and application functions were generated through the projection horizon. The analytical framework incorporated deployment architecture choices, regulatory compliance tier requirements, and asset lifecycle stage as primary segmentation dimensions. CAGRs were derived from installation base expansion rates, replacement cycle acceleration under methane mandates, and cloud migration patterns among capital-constrained independents. Industry-specific inputs included subsea fiber optic deployment timelines, REACH substance restriction phase-in schedules, and windfall taxation impact on operator balance sheet capacity.
Caveats apply where EU methane-performance benchmark revisions, REACH substance list expansions, or North Sea decommissioning timeline accelerations could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement consistency, supplier qualification cycle durations, and fiber connectivity reliability in Barents Sea frontier developments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Seismic Services Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Smart Well Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Turkmenistan Oil and Gas Market