
 LDL Test Market | 2026-2036
LDL Test Market Size, Share, and Industry Trends Forecast 2026-2036
LDL Test Market Outlook
Diagnostic reagent manufacturing in Germany is expanding as European laboratories automate high-throughput lipid profiling. Siemens Healthineers leverages its embedded automation footprint across European hospital networks. Roche Diagnostics sustains competitive intensity through proprietary enzymatic assay chemistry. Abbott Laboratories anchors its position in point-of-care lipid testing with handheld analyzer platforms deployed in primary care settings.
LDL testing quantifies low-density lipoprotein cholesterol concentration in serum or plasma through enzymatic hydrolysis, selective surfactant-mediated clearance, or homogeneous immunoseparation, with results expressed in milligrams per deciliter to assess cardiovascular disease risk and guide statin therapy decisions. Reagents and assay kits dominate current revenue flows due to recurring consumption tied to expanding test volumes in hospital laboratories. Point-of-care testing represents the fastest-growing end-user channel as clinics seek same-day lipid results without central lab routing. Immunoassay technology leads in precision performance while enzymatic methods retain cost advantages in high-volume screening programs.
The FDA regulates LDL test systems as Class II medical devices requiring 510(k) clearance, while CLIA establishes complexity tiers that determine operator certification requirements and site eligibility. Germany's G-BA (Federal Joint Committee) sets reimbursement benchmarks for lipid diagnostics within statutory health insurance, directly influencing test accessibility and laboratory purchasing decisions. Stakeholders must monitor evolving harmonization between FDA point-of-care waiver pathways and EU IVDR performance standards as dual certification becomes essential for multinational instrument deployments.
Market Dynamics
Automation of lipid panel workflows is compressing turnaround times in high-throughput hospital laboratories while CLIA complexity tiers redirect capital toward waived-test platforms that bypass certified technician requirements.
Growth Catalysts
- Statutory screening mandates:Germany's Federal Joint Committee mandates regular lipid screening for high-risk patient cohorts under statutory health insurance, creating predictable test volume.
- Point-of-care platform expansion:Primary care clinics accelerate adoption of handheld analyzer platforms to deliver same-day results without central laboratory routing.
- Enzymatic assay chemistry:Proprietary surfactant-mediated clearance methods reduce reagent costs per test, enabling high-volume screening program expansion.
Market Restraints
- Reagent supply concentration:European diagnostic reagent manufacturing clusters in Germany and Switzerland create geographic concentration risk for North American laboratories.
- Dual certification burden:Harmonization gaps between FDA 510(k) pathways and EU IVDR performance standards extend product launch timelines for multinational instrument deployments.
- Homogeneous immunoassay cost premium:Precision-grade immunoseparation methods carry 40-60% higher per-test costs than enzymatic alternatives, limiting adoption in budget-constrained public health programs.
Strategic Opportunities
- Outpatient cardiology networks:Germany's distributed cardiology clinic infrastructure remains underpenetrated by automated lipid profiling systems.
- Integrated risk stratification:Convergence of LDL testing with AI-enabled cardiovascular risk scoring creates bundled diagnostic service models.
- Retail pharmacy channels:Pharmacy-based wellness screening programs represent an emerging direct-to-consumer access point for waived-test lipid platforms.
Industry Challenges
- CLIA personnel certification bottlenecks:Moderate-complexity laboratory sites face technician recruitment constraints that delay automated workflow deployment.
- Legacy analyzer integration friction:Hospital laboratories encounter interoperability gaps when connecting new lipid platforms to existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LDL Test Market |
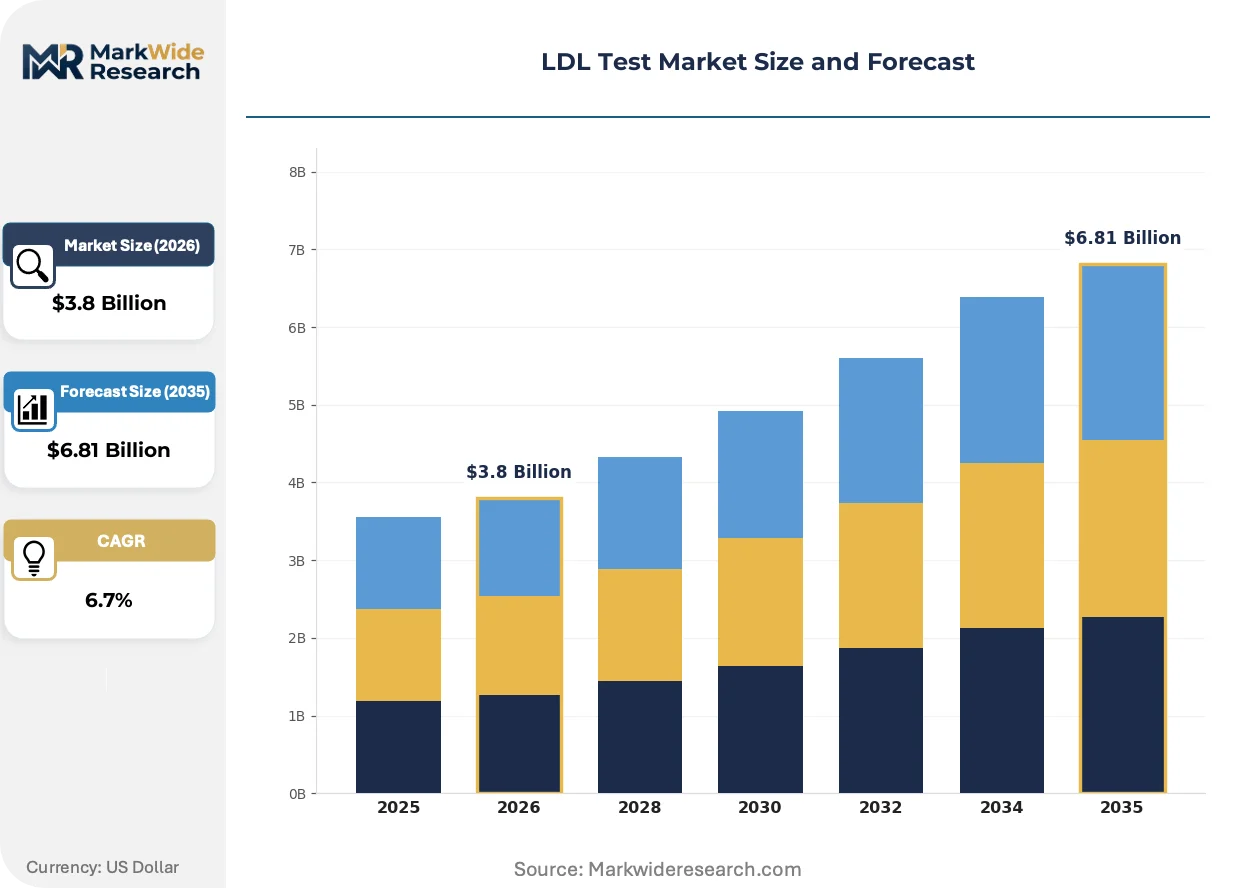
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assay Kits, Instruments, Consumables Application: Diagnostics, Clinical Testing, Research, Screening End User: Hospitals, Reference Laboratories, Point-of-Care Testing, Home Care Technology: Colorimetric, Enzymatic, HPLC, Immunoassay |
| Companies Covered | Siemens Healthineers, Randox Laboratories, Abbott Laboratories, Laboratory Corporation of America Holdings, Bio-Rad Laboratories, Roche Diagnostics, Thermo Fisher Scientific, Beckman Coulter, Quest Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LDL Test Market Strategic Shifts
Homogeneous immunoassay technology is consolidating precision-performance advantages while regulatory complexity accelerates platform specialization. Three intersecting developments are reshaping competitive positioning.
Homogeneous immunoassay technology is consolidating market share in reference laboratories requiring precise LDL quantification for statin therapy titration. Academic medical centers and specialty cardiovascular centers adopt these platforms despite premium pricing. The technology is consolidating high-margin testing segments while compressing enzymatic method viability in precision-critical applications.
EU IVDR performance standards are tightening analytical validation requirements for in-vitro diagnostic devices. Manufacturers must generate expanded clinical evidence packages for CE marking renewal. European hospital networks are responding by consolidating purchasing around platforms with pre-validated IVDR technical documentation.
Same-day diagnostic expectations are compressing patient routing through traditional central laboratory channels. Primary care clinics and urgent care networks now prioritize waived-test platforms that eliminate specimen transport delays. This behavioral shift is most visible in United States metropolitan markets where patient satisfaction metrics influence clinic reimbursement.
LDL Test Market Segmentation
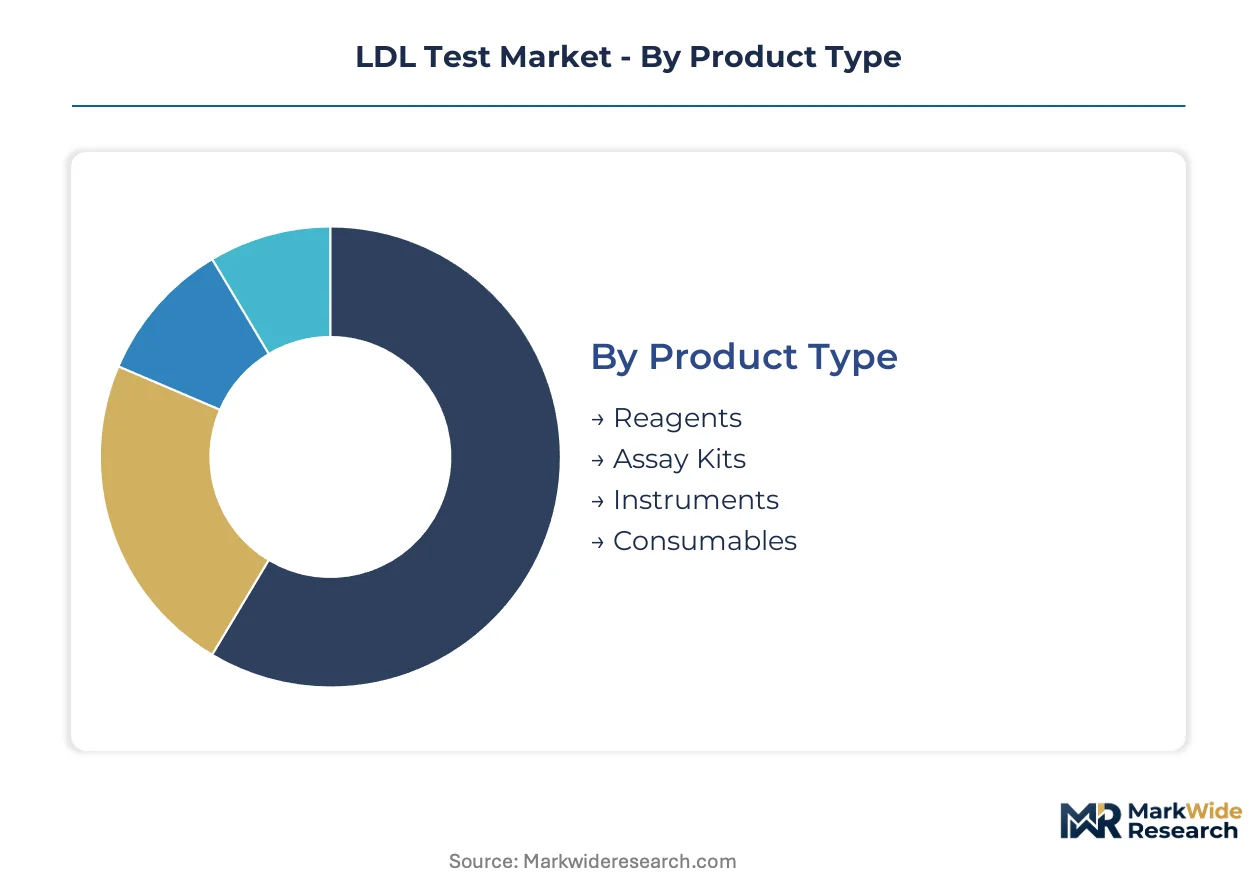
LDL test market segmentation reveals distinct regulatory pathways and purchasing behaviors across product configurations. Certification requirements vary sharply between centralized laboratory systems and waived-test platforms, shaping vendor R&D allocation and geographic launch sequencing.
Product Type:
FDA 510(k) clearance timelines diverge significantly across this category, with instruments facing 12-18 month review cycles while reagents navigate abbreviated pathways. EU IVDR technical documentation requirements impose additional validation burdens on assay kits and consumables destined for European hospital networks.
- Reagents:Liquid-stable enzymatic formulations with surfactant-mediated clearance chemistry dominate high-throughput hospital laboratory procurement. Demand concentrates in German diagnostic manufacturing clusters serving statutory health insurance-mandated screening programs, with supply contracts tied to multi-year analyzer placements.
- Assay Kits:Pre-calibrated reagent packs with barcoded lot tracking reduce technician handling errors in moderate-complexity CLIA sites. German outpatient cardiology networks drive kit standardization, as G-BA reimbursement benchmarks favor predictable per-test economics over open reagent systems.
- Instruments:Automated lipid analyzers with embedded quality control protocols.
- Consumables:Cuvettes, pipette tips, and calibrator vials with instrument-locked compatibility.
Leading the category by volume: Reagents. Growing fastest: Assay Kits.
Application:
End-use setting determines reimbursement tier and regulatory scrutiny intensity. CLIA-waived platforms access distinct reimbursement codes in US primary care, while German statutory insurance creates volume concentration in outpatient diagnostic channels.
- Diagnostics:Quantitative LDL measurement for cardiovascular risk stratification and statin therapy monitoring. Hospital laboratories in the United States anchor diagnostic volume, with automated workflow integration compressing turnaround times for emergency department lipid panels.
- Clinical Testing:Therapeutic drug monitoring and familial hypercholesterolemia confirmation. German reference laboratories specialize in clinical testing precision, leveraging homogeneous immunoassay methods for borderline cases requiring definitive quantification.
- Research:Epidemiological studies and pharmaceutical trial endpoints.
- Screening:Population-level cardiovascular risk identification in wellness programs.
Diagnostics commands the largest revenue base. Screening expands most quickly through retail pharmacy and employer wellness channels.
End User:
Site certification tier directly constrains platform selection, with CLIA complexity categories filtering available technologies. Waived-test eligibility unlocks point-of-care deployment without certified laboratory technician requirements.
- Hospitals:High-throughput centralized laboratories with integrated laboratory information systems. German university hospital networks prioritize IVDR-prevalidated platforms, consolidating purchasing around vendors with completed technical documentation packages.
- Reference Laboratories:Specialized lipid profiling with standardized calibration traceability. United States academic medical centers anchor reference laboratory demand, adopting homogeneous immunoassay technology for statin therapy titration despite premium pricing.
- Point-of-Care Testing:CLIA-waived handheld analyzers in primary care and urgent care settings.
- Home Care:Patient-operated lipid monitoring with telemedicine integration.
Hospitals generate the highest absolute test volumes. Point-of-Care Testing climbs the fastest as same-day result expectations reshape patient routing.
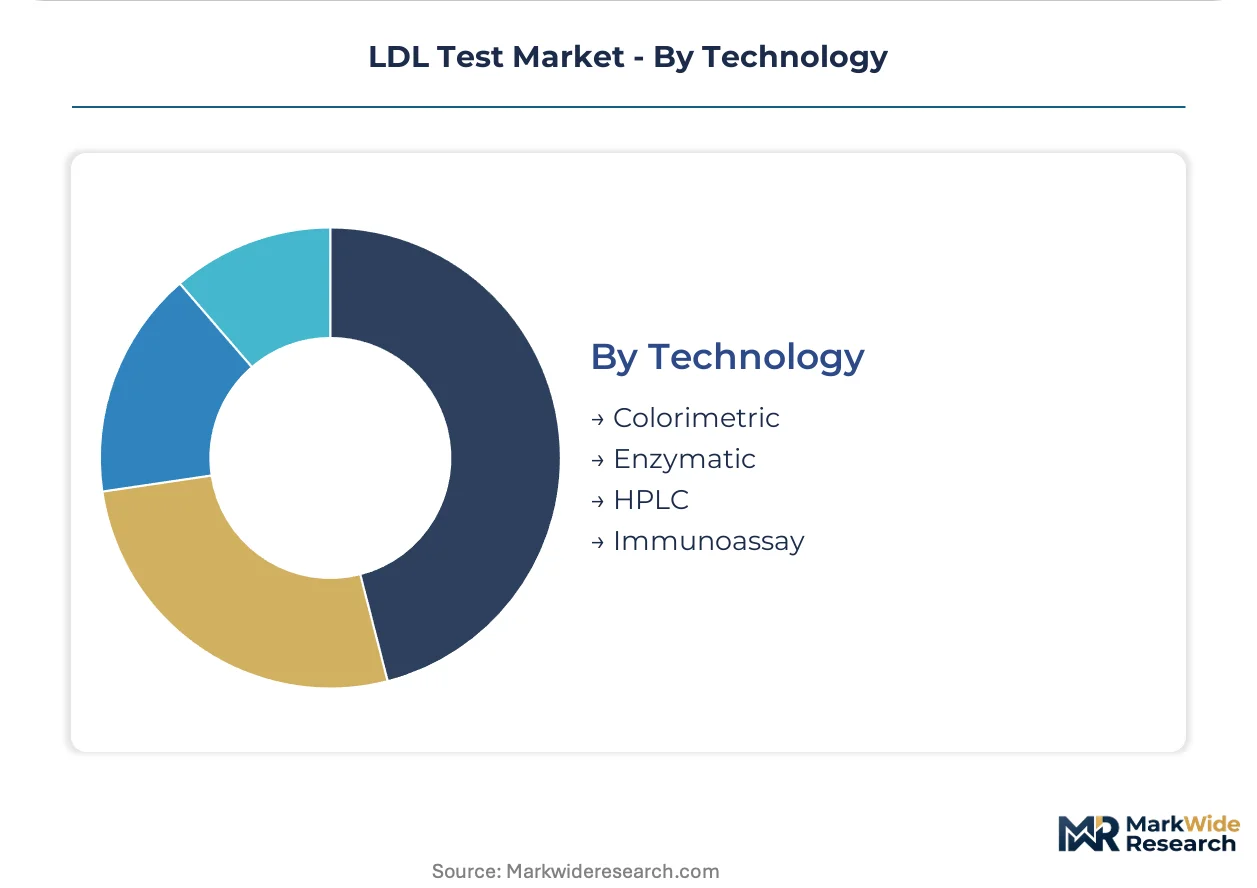
Technology:
Performance tier and cost structure segment technology adoption, with precision-critical applications tolerating premium pricing while high-volume screening demands reagent economy.
- Enzymatic:Selective surfactant-mediated clearance with colorimetric endpoint detection. German statutory screening programs anchor enzymatic demand, where 40-60% lower per-test costs than immunoassay alternatives enable population-scale deployment.
- Immunoassay:Homogeneous immunoseparation with direct LDL quantification without pretreatment. United States specialty cardiovascular centers concentrate immunoassay adoption, prioritizing precision for statin therapy decisions in high-risk patient cohorts.
- Colorimetric:Simplified photometric detection for resource-limited settings.
- HPLC:Gold-standard reference method for lipid fractionation and validation.
Enzymatic methods dominate by test volume. Immunoassay gains share fastest in precision-critical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German diagnostic reagent manufacturing clusters anchor European supply chains for lipid profiling consumables, while United States hospital laboratories drive North American automation adoption. Japanese precision instrument makers and Chinese point-of-care platform developers complete the geographic matrix.
United States
Hospital laboratory automation and primary care point-of-care deployment generate dual demand channels. FDA 510(k) clearance pathways and CLIA complexity tiers shape platform selection, with waived-test eligibility unlocking clinic-based lipid screening. The Boston-Cambridge medical technology corridor concentrates analyzer development activity.
Germany
Statutory health insurance mandates for high-risk patient lipid screening create predictable test volumes. The Federal Joint Committee (G-BA) reimbursement benchmarks directly influence laboratory purchasing decisions. The Rhine-Main and Munich metropolitan areas host dense clusters of diagnostic reagent manufacturing and automated platform integration specialists.
Japan
Precision enzymatic assay chemistry and homogeneous immunoassay development anchor domestic demand. The Pharmaceuticals and Medical Devices Agency (PMDA) regulatory framework emphasizes analytical validation rigor. The Kanto region around Tokyo concentrates reference laboratory networks and academic medical center adoption of advanced lipid quantification methods.
China
Expanding hospital laboratory networks and retail pharmacy wellness screening programs drive platform deployment. The National Medical Products Administration (NMPA) oversees Class II medical device registration for diagnostic instruments. The Yangtze River Delta region, particularly Shanghai and surrounding provinces, concentrates domestic point-of-care analyzer manufacturing capacity.
Switzerland
Specialized diagnostic reagent manufacturing and precision immunoassay chemistry development sustain niche export positioning. Swissmedic regulatory standards align with EU IVDR requirements for European market access. The Basel-Zurich corridor hosts concentrated life sciences infrastructure serving both European hospital networks and global reference laboratory customers.
LDL Test Market Competitive Environment
Global majors compete with regional champions across regulatory certification and automation integration capabilities. The vendor base organizes around three tiers: diversified conglomerates with full diagnostic portfolios, specialized lipid testing platform developers, and regional reagent suppliers serving statutory screening programs. Strategic moves concentrate on IVDR technical documentation pre-validation and point-of-care waiver pathway navigation.
Within the diversified diagnostics tier, Siemens Healthineers and Roche Diagnostics occupy positions spanning European hospital network automation and precision assay chemistry development. Abbott Laboratories exemplifies the point-of-care specialization archetype, with its handheld analyzer platforms deployed across primary care settings. These three entities represent distinct competitive vectors: embedded automation infrastructure, proprietary enzymatic and immunoassay intellectual property, and waived-test regulatory positioning.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Randox Laboratories |
| Abbott Laboratories |
| Laboratory Corporation of America Holdings |
| Bio-Rad Laboratories |
| Roche Diagnostics |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Quest Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Captive reagent manufacturing in Germany anchors both supply security and pricing power for European diagnostic networks, with Siemens Healthineers and Roche Diagnostics leveraging in-house enzymatic chemistry production to defend margin structures against commoditization pressure from Asian consumable suppliers.
Pricing Analysis
Service bundling separates instrument placement economics from reagent consumption contracts, with multi-year analyzer leases embedding preventive maintenance and calibration support while per-test reagent pricing remains unbundled and volume-negotiated. Three-tier pricing structure across premium homogeneous immunoassay, standard enzymatic, and economy colorimetric levels reflects certification grade and precision performance. Cost compression in economy tiers is intensifying because of Chinese point-of-care platform imports. Public health screening programs in Germany exhibit highest price sensitivity; United States academic medical centers show lowest sensitivity due to precision requirements for statin therapy decisions.
Supply Chain Analysis
Surfactant-mediated clearance chemistry rests on German and Swiss specialty reagent producers, with enzymatic substrate supply anchored in Japanese precision chemical manufacturing and plastic consumable molding concentrated in Chinese Yangtze River Delta facilities. Critical dependencies include liquid-stable enzyme formulations, barcoded calibrator vials, and instrument-locked cuvette geometries. Single-source vulnerability concentrates in European surfactant chemistry where IVDR validation timelines deter supplier switching. Distribution runs through hospital group purchasing organizations in the United States and statutory health insurance tender processes in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around IVDR-prevalidated platform portfolios, with harmonization gaps between FDA 510(k) and EU IVDR pathways forcing smaller reagent suppliers toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into surfactant chemistry production and accelerated IVDR technical documentation completion for core assay kits. Siemens Healthineers and Roche Diagnostics must preempt emerging Chinese point-of-care platforms by locking German outpatient cardiology networks into multi-year reagent supply contracts before NMPA-cleared instruments achieve CE marking. For New Entrants and Emerging Players: Enter via retail pharmacy wellness screening channels in the United States, where CLIA-waived eligibility requirements are less stringent than hospital laboratory certification and same-day consumer demand outpaces incumbent handheld analyzer deployment. Target employer wellness program procurement, which lacks the GPO contract lock-in that protects hospital incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified diagnostics conglomerates seeking IVDR-validated reagent portfolios. Mid-cap enzymatic assay specialists with completed German G-BA reimbursement dossiers represent prime acquisition targets. Watch FDA point-of-care waiver pathway expansion announcements as the critical inflection signal for point-of-care testing valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Pre-validation | CE marking renewal timelines compress competitive windows for European hospital network procurement. |
| CLIA Waiver Pathway Navigation | FDA 510(k) clearance for waived-test platforms unlocks primary care clinic deployment without certified technician requirements. |
| Backward Integration into Surfactant Chemistry | In-house reagent production insulates margin structures from German-Swiss supply concentration risk. |
| Hospital System Partnership | Integrated laboratory information system connectivity secures high-throughput lipid panel workflow automation contracts. |
| Retail Pharmacy Channel Development | Direct-to-consumer wellness screening access points bypass traditional central laboratory routing economics. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU IVDR technical documentation registries, and German G-BA reimbursement benchmark publications, complemented by interviews with hospital laboratory directors, diagnostic reagent procurement managers, point-of-care clinic operators, and CLIA compliance officers. Secondary validation drew from CMS Medicare laboratory utilization data, hospital group purchasing organization contract filings, and statutory health insurance screening program reports. Bottom-up test volume modeling and top-down market sizing triangulated segment-level outputs.
Segmentation outputs across product type, application, end user, technology, and regional regulatory cluster fed into the analytical framework. CAGRs were derived from test volume expansion trajectories weighted by reimbursement tier evolution and platform substitution elasticity. Forecast inputs incorporated CLIA complexity tier reclassification probability and IVDR implementation timeline uncertainty across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA point-of-care waiver pathway acceleration or German G-BA screening mandate expansion scenarios. Forecasts reflect assumptions about enzymatic-immunoassay technology substitution rates and European reagent supply chain stability. Regulatory harmonization delays and surfactant chemistry supply disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Poultry Diagnostics Market