
 Epilepsy Diagnosis and Treatment Market | 2026-2036
Epilepsy Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Epilepsy Diagnosis and Treatment Market Analysis
The capability gap between capital-intensive neurostimulation manufacturers and traditional pharmaceutical developers is collapsing as device economics improve. Medtronic leverages its deep implantable device heritage to sustain leadership in responsive neurostimulation systems. UCB Pharma anchors its position through specialized antiepileptic drug portfolios with strong European regulatory foundations. Jazz Pharmaceuticals differentiates via targeted therapies for rare epilepsy syndromes.
Epilepsy diagnosis and treatment encompasses the clinical identification of seizure disorders through electrophysiological monitoring and neuroimaging, coupled with pharmacological, surgical, and device-based interventions to reduce seizure frequency and severity. Electroencephalography remains the functional cornerstone, with 24-hour video-EEG monitoring providing diagnostic specificity for surgical candidacy assessments. Antiepileptic drugs occupy the mature core of the market, while neurostimulation devices represent the fastest-expanding margin pool as reimbursement frameworks broaden. Imaging systems compete on resolution and throughput in hospital radiology departments, whereas homecare settings drive demand for ambulatory EEG and remote monitoring configurations.
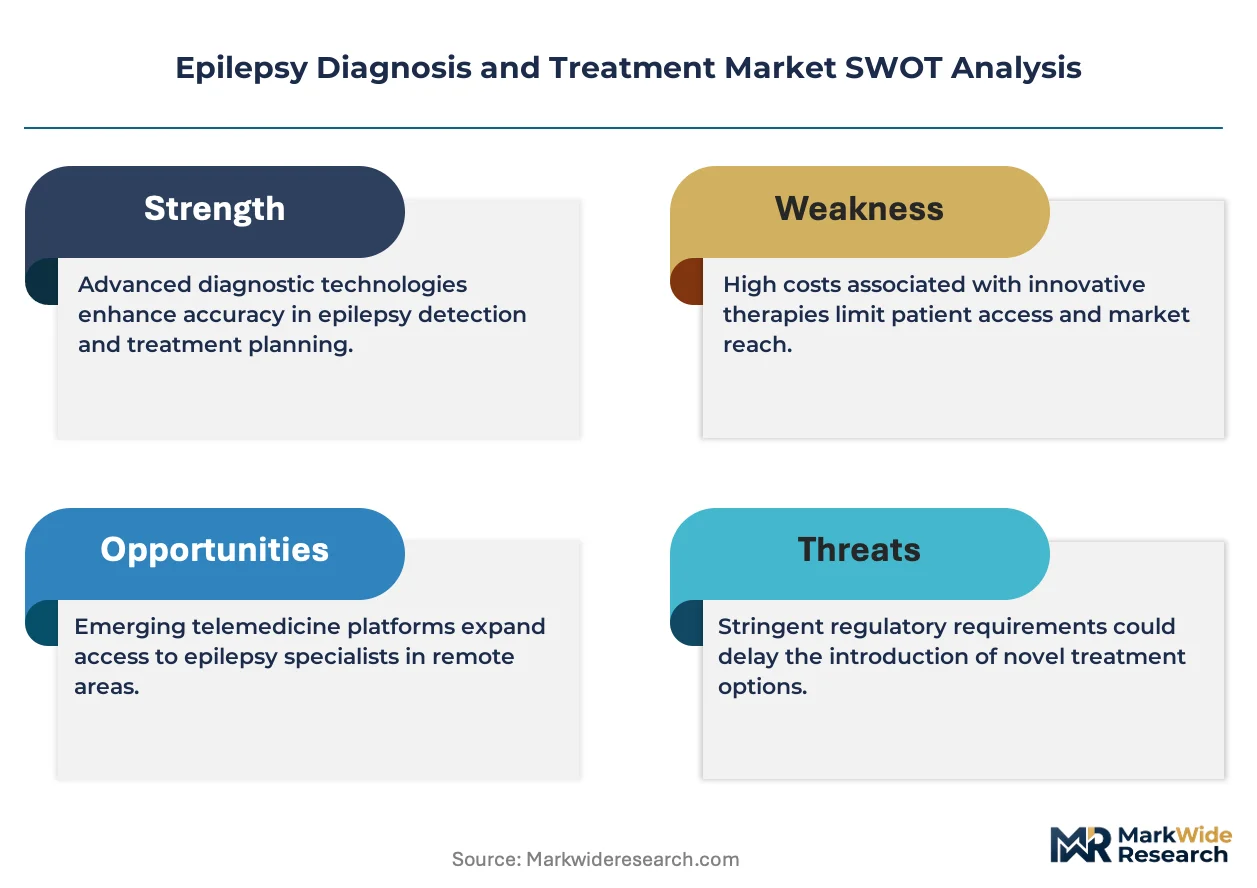
FDA premarket approval pathways and the EU Medical Device Regulation shape neurostimulation commercialization timelines, while the EMA's centralized procedure governs novel antiepileptic drug launches across European markets. The US Drug Enforcement Administration's scheduling requirements for controlled substances impose additional compliance layers on benzodiazepine-based rescue therapies. Stakeholders must monitor reimbursement parity between invasive neurostimulation and optimized drug regimens as health technology assessment bodies recalibrate value thresholds.
Market Dynamics
The FDA's streamlined breakthrough device designation is collapsing approval timelines for closed-loop neurostimulation systems, compressing the historical 5-7 year regulatory runway into 18-24 month cycles and redrawing competitive entry barriers.
Growth Catalysts
- Expanded Reimbursement Codes:CMS coverage determinations for ambulatory EEG monitoring in the United States are unlocking home-based diagnostic revenue streams previously confined to inpatient settings.
- Biomarker-Guided Dosing:Pharmacogenomic testing protocols are enabling precision titration of antiepileptic drugs, reducing adverse event rates and therapy discontinuation in European treatment centers.
- Level 4 Epilepsy Center Expansion:Academic medical centers across Germany, France, and the United Kingdom are commissioning integrated surgical evaluation units with 24-hour video-EEG capacity.
Market Restraints
- Neurostimulator Battery Supply Concentration:Lithium thionyl chloride cell production concentrates among three East Asian suppliers, exposing device manufacturers to raw material allocation volatility.
- EU MDR Technical Documentation Burden:The Medical Device Regulation's clinical evidence requirements are extending neurostimulation recertification cycles by 14-18 months.
- Generic AED Substitution Pressure:Patent cliffs for levetiracetam and lamotrigine formulations are compressing branded pharmaceutical margins in price-sensitive European markets.
Strategic Opportunities
- Underpenetrated Pediatric Surgery:Corpus callosotomy and hemispherectomy volumes in India remain 60-70% below epidemiologically indicated levels due to referral pathway fragmentation.
- Remote Monitoring Integration:Cloud-based seizure diary platforms paired with consumer wearables are creating subscription revenue models outside traditional device sales.
- Japan's Dementia-Comorbidity Protocol:METI-funded research programs are validating EEG-based early seizure detection in elderly populations with overlapping neurodegenerative conditions.
Industry Challenges
- Electrophysiologist Training Pipeline:Fellowship programs producing surgical epileptologists with intracranial monitoring expertise are failing to match Level 4 center expansion rates.
- Legacy EMR Integration Complexity:Video-EEG data formats lack interoperability with hospital information systems, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epilepsy Diagnosis and Treatment Market |
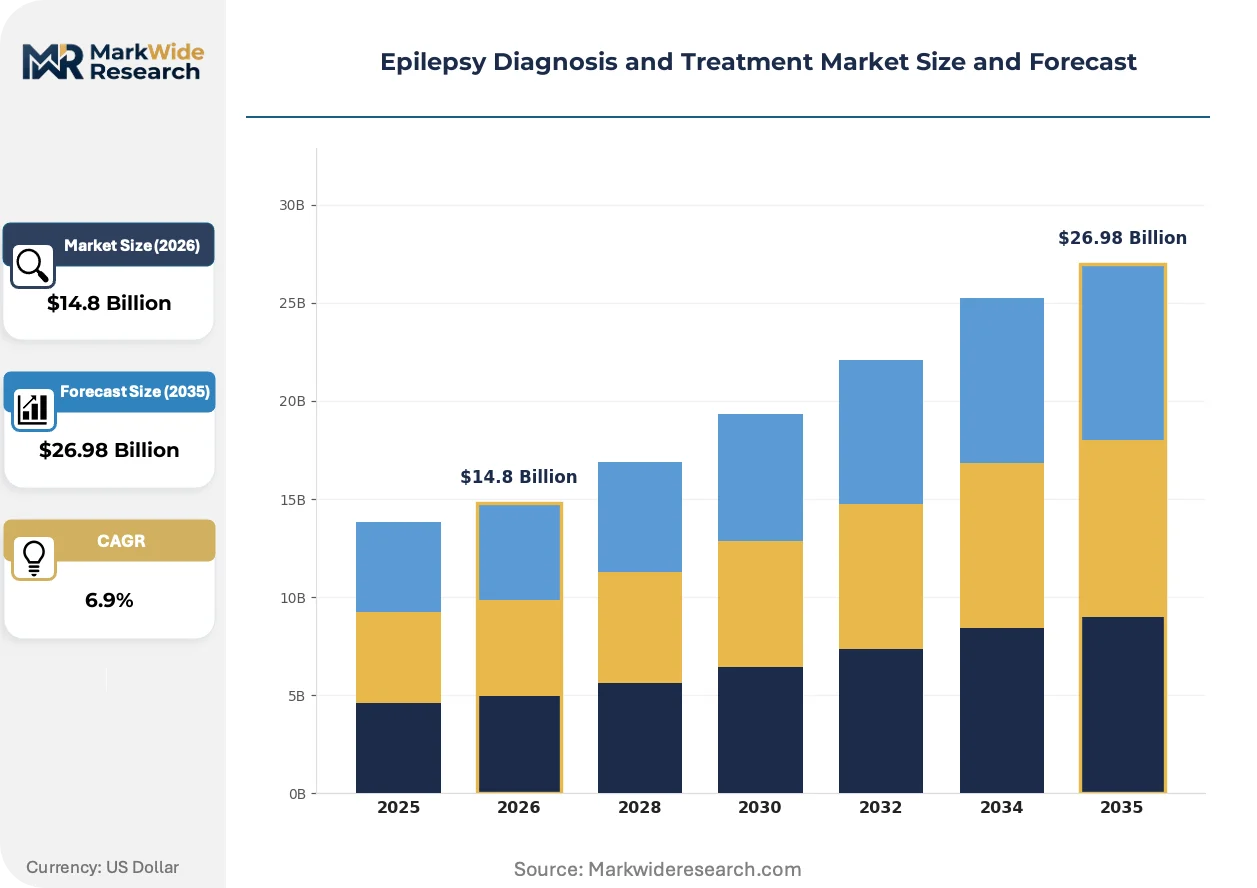
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiepileptic Drugs, EEG Devices, Neurostimulation Devices, Imaging Systems Treatment Approach: Medication, Surgery, Lifestyle Modification, Neurostimulation End User: Hospitals, Homecare, Rehabilitation Centers, Clinics Therapy Area: Generalized Epilepsy, Focal Epilepsy, Lennox-Gastaut Syndrome, Others |
| Companies Covered | Pfizer, UCB Pharma, GlaxoSmithKline, Eisai, Novartis, Medtronic, GE Healthcare, Jazz Pharmaceuticals, Xenon Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epilepsy Diagnosis and Treatment Market Emerging Trajectories
Artificial intelligence is penetrating seizure detection and prediction workflows, shifting diagnostic labor from human readers to algorithmic classifiers while raising new questions about liability allocation and clinical validation standards.
Machine learning-based EEG interpretation is fragmenting the traditional electroencephalographer role. Community hospitals in the United States are adopting FDA-cleared automated spike detection software to interpret routine studies without on-site neurologist coverage. This capability diffusion is compressing referral volumes to academic interpretation services and enabling point-of-care diagnostic expansion.
The EU Medical Device Regulation's software-as-a-medical-device classification is forcing algorithm developers to submit clinical validation packages previously reserved for hardware implants. European epilepsy monitoring unit directors are delaying procurement of AI-enabled detection systems pending notified body certification. German university hospitals are piloting hybrid workflows combining automated screening with mandatory specialist confirmation to satisfy liability protocols.
Hospital procurement committees are unbundling device acquisition from long-term service contracts. Level 4 epilepsy centers in the United States are negotiating separate pricing for neurostimulator hardware, programming services, and remote monitoring subscriptions. This contract decomposition is most advanced in California and Massachusetts, where integrated delivery networks wield concentrated purchasing leverage over device manufacturers.
Epilepsy Diagnosis and Treatment Market Segmentation
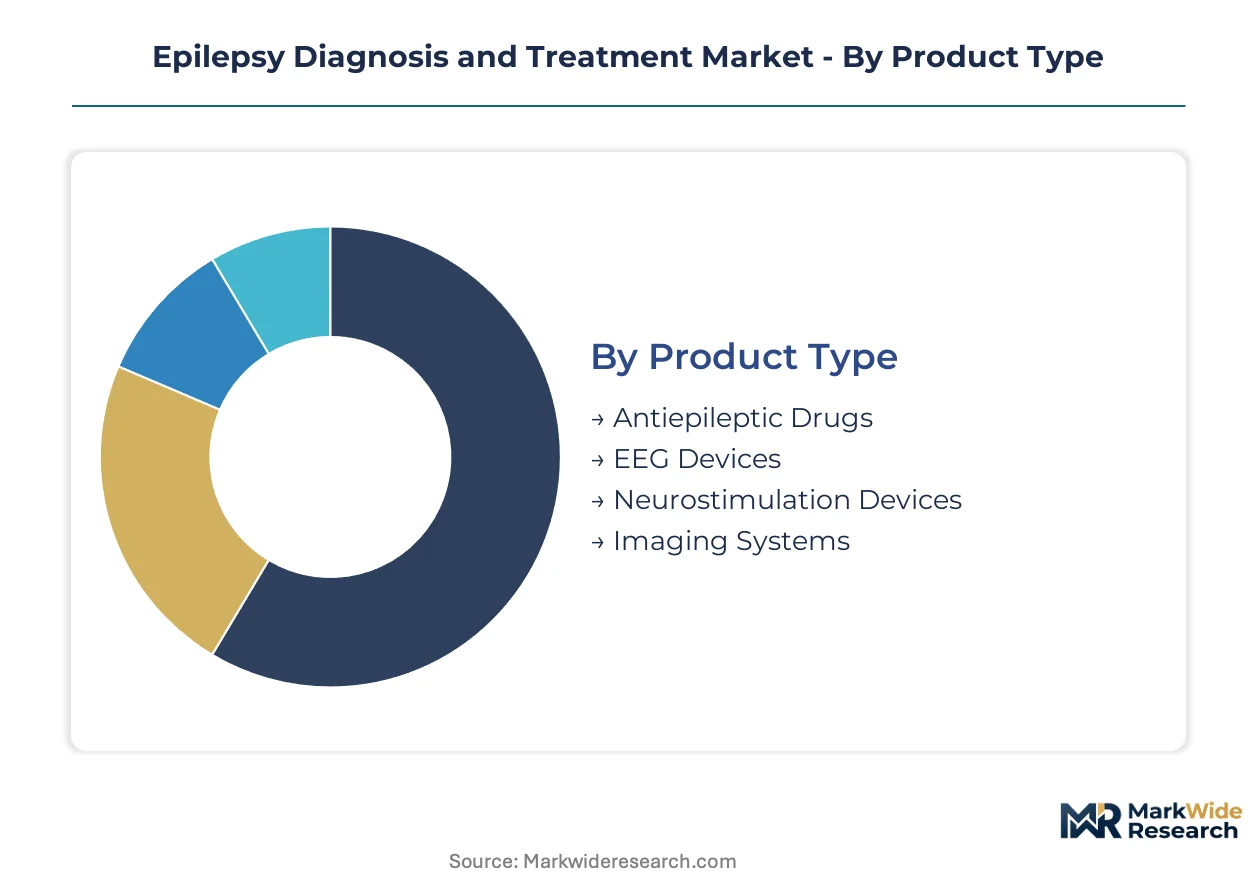
Epilepsy diagnosis and treatment markets fragment across therapeutic modalities, diagnostic technologies, and care delivery settings. Channel economics differ sharply between capital-intensive neurostimulation systems and recurring pharmaceutical revenues.
Product Type:
Hospital procurement committees source these categories through divergent channels: imaging systems and EEG devices flow through capital equipment budgets with 5-7 year depreciation cycles, while antiepileptic drugs and neurostimulation implants generate recurring revenue through pharmacy and surgical supply chains.
- Antiepileptic Drugs:Small-molecule formulations and biologics administered chronically to suppress seizure activity. Demand concentrates in retail and hospital pharmacy channels across Germany and France, where EMA centralized approvals accelerate formulary access. Generic substitution pressures compress branded margins in price-sensitive markets.
- EEG Devices:Electrophysiological recording systems ranging from portable ambulatory units to high-density inpatient configurations. Academic medical centers in Massachusetts and California drive demand for 256-channel invasive monitoring setups with integrated video synchronization.
- Neurostimulation Devices:Implantable pulse generators with responsive or open-loop stimulation protocols for drug-resistant cases.
- Imaging Systems:MRI and PET scanners deployed for structural lesion identification and surgical planning.
By volume, antiepileptic drugs lead. By growth pace, neurostimulation devices are climbing the fastest.
Treatment Approach:
Cost tiers separate these modalities: medication management occupies the lowest per-patient expenditure band, while surgical intervention and implanted neurostimulation require substantial upfront investment with extended payback horizons.
- Medication:First-line pharmacological intervention using sodium channel blockers, GABA agonists, and glutamate antagonists. Primary care networks in the United Kingdom and community neurology practices in Texas generate high prescription volumes for established molecules.
- Surgery:Resective procedures including temporal lobectomy and lesionectomy for localized epileptogenic foci. Level 4 epilepsy centers at Cleveland Clinic and NYU Langone concentrate resection volumes, with candidacy determined through intracranial monitoring.
- Lifestyle Modification:Dietary protocols and behavioral interventions as adjunctive management.
- Neurostimulation:Vagus nerve stimulation, responsive neurostimulation, and deep brain stimulation for refractory cases.
By patient volume, medication dominates. By revenue intensity per case, surgery and neurostimulation are gaining share fastest.
End User:
Customer type determines purchasing authority and decision timelines: hospital committees negotiate capital equipment, while homecare settings drive demand for wearable diagnostics and remote monitoring subscriptions.
- Hospitals:Integrated delivery networks with Level 3 and Level 4 epilepsy monitoring capabilities. Johns Hopkins Hospital and Mayo Clinic Rochester anchor inpatient diagnostic and surgical volumes in the United States.
- Homecare:Ambulatory EEG services and remote seizure monitoring for stable patients. Medicare coverage determinations in the United States are unlocking reimbursement for home-based video-EEG, expanding addressable volume beyond traditional inpatient capture.
- Rehabilitation Centers:Post-surgical recovery and therapy optimization for seizure control.
- Clinics:Outpatient neurology practices managing stable epilepsy with routine pharmacological oversight.
By installed base, hospitals lead. By expansion trajectory, homecare is pulling ahead.
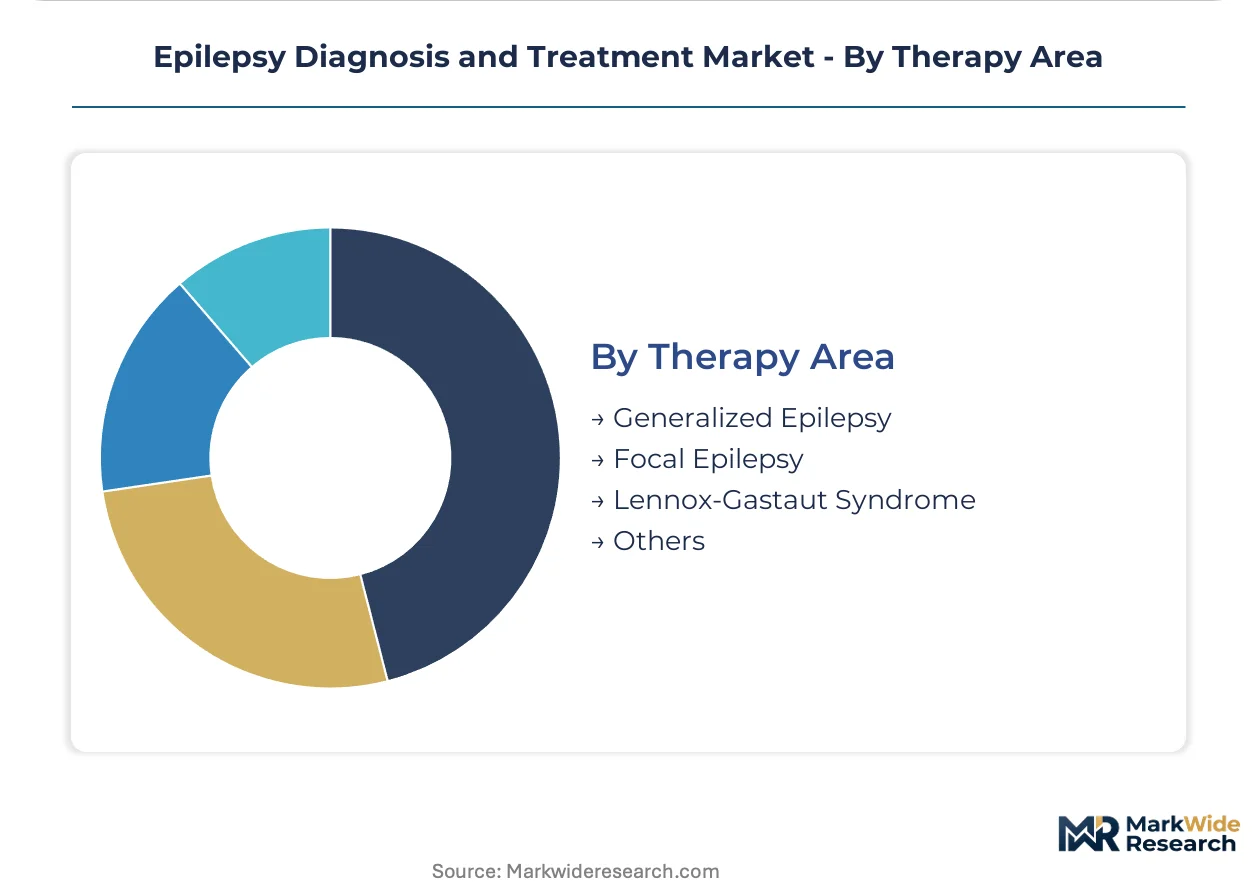
Therapy Area:
Maturity gradients separate these indications: focal epilepsy carries the deepest clinical evidence base and established surgical pathways, while rare syndromes command premium pricing for targeted therapies.
- Generalized Epilepsy:Seizure types involving bilateral cortical networks from onset. Treatment centers in Paris and London manage high volumes of juvenile myoclonic and absence epilepsy variants through standardized medication protocols.
- Focal Epilepsy:Seizures originating in discrete cortical regions amenable to surgical resection or targeted neurostimulation. Massachusetts General Hospital and University of California San Francisco concentrate resection volumes for mesial temporal sclerosis cases.
- Lennox-Gastaut Syndrome:Severe developmental and epileptic encephalopathy with multiple seizure types.
- Others:Rare syndromes including Dravet syndrome and tuberous sclerosis complex.
By treated prevalence, focal epilepsy leads. By unmet need and therapy development activity, Lennox-Gastaut syndrome and rare syndromes are advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity for neurostimulation systems, while Indian hospital procurement committees remain highly sensitive to device costs despite expanding surgical volumes.
United States
Academic medical centers in Massachusetts and California drive demand for 256-channel invasive EEG monitoring systems with integrated video synchronization. FDA breakthrough device designation pathways compress neurostimulation approval timelines from historical 5-7 year cycles to 18-24 months. Cleveland Clinic and Mayo Clinic Rochester anchor the nation's deepest surgical epilepsy volumes.
Germany
University hospitals in Bavaria and North Rhine-Westphalia commission integrated Level 4 epilepsy monitoring units with 24-hour video-EEG capacity. EU Medical Device Regulation technical documentation requirements extend neurostimulation recertification cycles by 14-18 months. Berlin-Brandenburg clusters concentrate pharmacogenomic testing protocols enabling precision AED titration.
Japan
METI-funded research programs validate EEG-based early seizure detection in elderly populations with overlapping neurodegenerative conditions. PMDA consultation pathways streamline novel antiepileptic drug submissions for rare syndrome indications. Kanto region hospitals in Tokyo concentrate the nation's deepest intracranial monitoring expertise.
India
Corpus callosotomy and hemispherectomy volumes remain 60-70% below epidemiologically indicated levels due to referral pathway fragmentation. CDSCO medical device rules impose additional clinical trial requirements for imported neurostimulation systems. Maharashtra and Karnataka host the strongest clusters of pediatric epilepsy surgical programs.
United Kingdom
Primary care networks generate high prescription volumes for established antiepileptic drug molecules across England and Scotland. NHS England coverage determinations for ambulatory EEG monitoring expand home-based diagnostic reimbursement. London and Greater Manchester concentrate the nation's Level 4 epilepsy center capacity.
Epilepsy Diagnosis and Treatment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the epilepsy diagnosis and treatment market. Consolidated pharmaceutical developers with antiepileptic drug portfolios compete against diversified medical device manufacturers with implantable neurostimulation heritage. Three archetypes dominate: integrated neuromodulation conglomerates, specialized antiepileptic drug developers, and diagnostic imaging system manufacturers. Competitive moves concentrate on M&A to fill portfolio gaps and strategic partnerships to combine drug-device therapy protocols.
Within the integrated neuromodulation tier, Medtronic exemplifies deep implantable device heritage applied to responsive neurostimulation systems. UCB Pharma and Jazz Pharmaceuticals anchor the specialized pharmaceutical developer archetype, with the former representing strong European regulatory foundations and the latter occupying a position in targeted therapies for rare epilepsy syndromes.
| Leading Market Players |
|---|
| Pfizer |
| UCB Pharma |
| GlaxoSmithKline |
| Eisai |
| Novartis |
| Medtronic |
| GE Healthcare |
| Jazz Pharmaceuticals |
| Xenon Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough device designation and EU MDR certification tiers simultaneously gate supplier qualification and stratify price bands across neurostimulation and diagnostic device categories, compressing approval timelines for premium-tier entrants while extending recertification burdens that feed into service-contract pricing power.
Pricing Analysis
Remote monitoring subscriptions and programming service contracts drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates integrated delivery networks with concentrated purchasing leverage from community hospitals and homecare settings. Cost compression in the generic antiepileptic drug tier is intensifying because patent cliffs for levetiracetam and lamotrigine expose branded formulations to substitution pressure. Indian hospital procurement committees demonstrate highest price sensitivity, while German and Swiss academic centers show lowest elasticity for neurostimulation systems.
Supply Chain Analysis
Lithium thionyl chloride cell production concentrates among South Korean, Japanese, and Chinese suppliers, exposing device manufacturers to raw material allocation volatility. Neurostimulator assembly draws from specialized battery chemistry, implantable-grade titanium housings, and biocompatible lead materials. Single-source vulnerability in East Asian battery supply creates disruption exposure for responsive neurostimulation system manufacturers. Distribution runs through hospital procurement committees for capital equipment, pharmacy supply chains for pharmaceuticals, and direct-to-clinic arrangements for ambulatory EEG services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based seizure diary platforms paired with consumer wearables are shifting epilepsy care toward platform economics, where data interoperability and algorithmic validation protocols determine ecosystem participation rather than standalone device superiority.
For Market Incumbents: Compound defensive moats through backward integration into implantable battery supply and captive development of AI-enabled EEG interpretation algorithms. Generic substitution pressure in European antiepileptic drug markets and algorithmic disruption of traditional electroencephalographer roles demand consolidation of service-contract relationships with Level 4 epilepsy centers to lock in programming and remote monitoring revenue streams. For New Entrants and Emerging Players: Pediatric surgical epilepsy programs in Maharashtra and Karnataka present underpenetrated service-layer gaps where referral pathway fragmentation has suppressed corpus callosotomy and hemispherectomy volumes below epidemiological indications. Homecare ambulatory EEG reimbursement expansion under Medicare coverage determinations creates the most penetrable segment for subscription-based remote monitoring platforms, with direct-to-patient go-to-market angles bypassing hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-a-medical-device categories as algorithm developers absorb clinical validation burdens previously reserved for hardware implants, compressing capital requirements for seizure detection and prediction entrants. Long-term viability over the next decade favors acquisition targets with FDA-cleared automated spike detection software and established notified body relationships under EU MDR software classification. The signal to watch is CMS reimbursement parity determinations between invasive neurostimulation and optimized drug regimens as health technology assessment bodies recalibrate value thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compresses neurostimulation approval timelines from 5-7 year cycles to 18-24 months for responsive systems. |
| EU MDR Software Classification | Forces algorithm developers to submit clinical validation packages previously reserved for hardware implants. |
| Hospital System Partnership | Level 4 epilepsy centers in Massachusetts and California negotiate unbundled pricing for hardware, programming, and remote monitoring. |
| Reimbursement Strategy | Medicare coverage determinations for ambulatory EEG unlock home-based diagnostic revenue beyond inpatient capture. |
| Software Companion Development | Cloud-based seizure diary platforms paired with consumer wearables create subscription revenue outside device sales. |
Methodological Framework
A standing panel of surgical epileptologists, hospital procurement managers, biomedical engineers, and GPO contracts specialists provided ongoing calibration across primary interview cycles. FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data furnished secondary validation. Bottom-up volume modeling across therapeutic modalities and diagnostic technologies triangulated against top-down market sizing from antiepileptic drug prescription databases and neurostimulation implant registry tracking.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include treatment approach, product type, end user setting, and therapy area, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO pathway differentiation. CAGRs were derived from fitted growth curves anchored to epidemiological prevalence data and surgical volume trends. Forecast inputs incorporated pharmacogenomic testing protocol adoption rates and Level 4 epilepsy center expansion pipelines.
Forecasts assume regulatory continuity in FDA breakthrough device pathways and EU MDR technical documentation requirements; material policy shifts would require re-modeling approval timeline and recertification cycle assumptions. Revision becomes warranted when reimbursement parity determinations between invasive neurostimulation and optimized drug regimens cross thresholds that alter health technology assessment body value calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fructosamine Test Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Animal Diagnostics Market