
 Microfinance Market | 2026-2036
Microfinance Market Size, Share, and Industry Trends Forecast 2026-2036
Microfinance Market Outlook
Agricultural lending among rural smallholders is realigning the customer base for microfinance providers across emerging economies. Grameen Bank anchors group-based lending methodologies that sustain repayment discipline in Bangladesh's rural hinterlands. Bandhan Bank leverages its banking license to extend regulated deposit products alongside credit, differentiating its liability management from unregulated competitors. FINCA International operates savings-led models in multiple geographies, competing on client retention rather than loan velocity alone.
Microfinance comprises small-scale financial services—typically loans under $1,000, voluntary savings facilities, and microinsurance—delivered to low-income borrowers excluded from conventional banking, with group guarantee mechanisms replacing traditional collateral requirements. The service type dimension shows microloans commanding the largest transaction volume while mobile platform delivery models generate the fastest portfolio growth through reduced operational overhead. Customer type segmentation reveals women borrowers producing superior repayment rates, concentrating margin pools in gender-targeted lending programs across South Asia and Sub-Saharan Africa.
India's RBI priority sector lending rules and Bangladesh's Microcredit Regulatory Authority licensing framework shape capital allocation and interest rate caps across South Asian markets. Indonesia's OJK supervises sharia-compliant microfinance through Bank Rakyat Indonesia's rural unit network, embedding religious compliance into product architecture. Stakeholders must monitor how digital identity systems and real-time payment rails reshape customer acquisition costs and fraud exposure across regulated and informal lending channels.
Market Dynamics
Mobile-first origination platforms are compressing customer acquisition costs and displacing branch-heavy distribution models across South Asian microfinance. RBI's priority sector lending mandates and Bangladesh's Microcredit Regulatory Authority licensing framework are accelerating capital flows toward digitized delivery channels.
Growth Catalysts
- Priority sector lending mandates:India's RBI rules compel commercial banks to allocate 40% of adjusted net bank credit to underserved segments, channeling institutional liquidity toward microfinance intermediaries.
- Mobile money interoperability:Real-time payment rails across Bangladesh and India enable instant loan disbursement and automated repayment collection, reducing field officer dependency.
- Women-centered group lending:Grameen-style solidarity groups produce superior repayment discipline, concentrating portfolio quality in gender-targeted programs across rural South Asia.
Market Restraints
- Interest rate caps:Bangladesh's Microcredit Regulatory Authority imposes lending rate ceilings that compress net interest margins for regulated institutions.
- Deposit mobilization constraints:Unregulated microfinance institutions lack banking licenses, forcing reliance on wholesale borrowing at higher cost than retail deposits.
- Collateral substitution limits:Group guarantee mechanisms fail in urban informal settlements where social cohesion is weaker than rural village networks.
Strategic Opportunities
- Sharia-compliant product expansion:Indonesia's OJK supervision of Islamic microfinance through Bank Rakyat Indonesia's rural unit network embeds religious compliance into scalable architecture.
- Microinsurance bundling:Climate-indexed crop insurance attached to agricultural microloans addresses rainfall volatility exposure among smallholder borrowers.
- Digital identity integration:India's Aadhaar-linked e-KYC reduces documentation friction for first-time borrowers previously excluded from formal credit bureaus.
Industry Challenges
- Field officer recruitment and retention:Rural credit officer positions face high turnover, eroding borrower relationship continuity and repayment monitoring effectiveness.
- Legacy core banking integration:Microfinance institutions migrating from spreadsheet-based portfolio management to regulated banking software encounter data migration complexity and parallel system costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfinance Market |
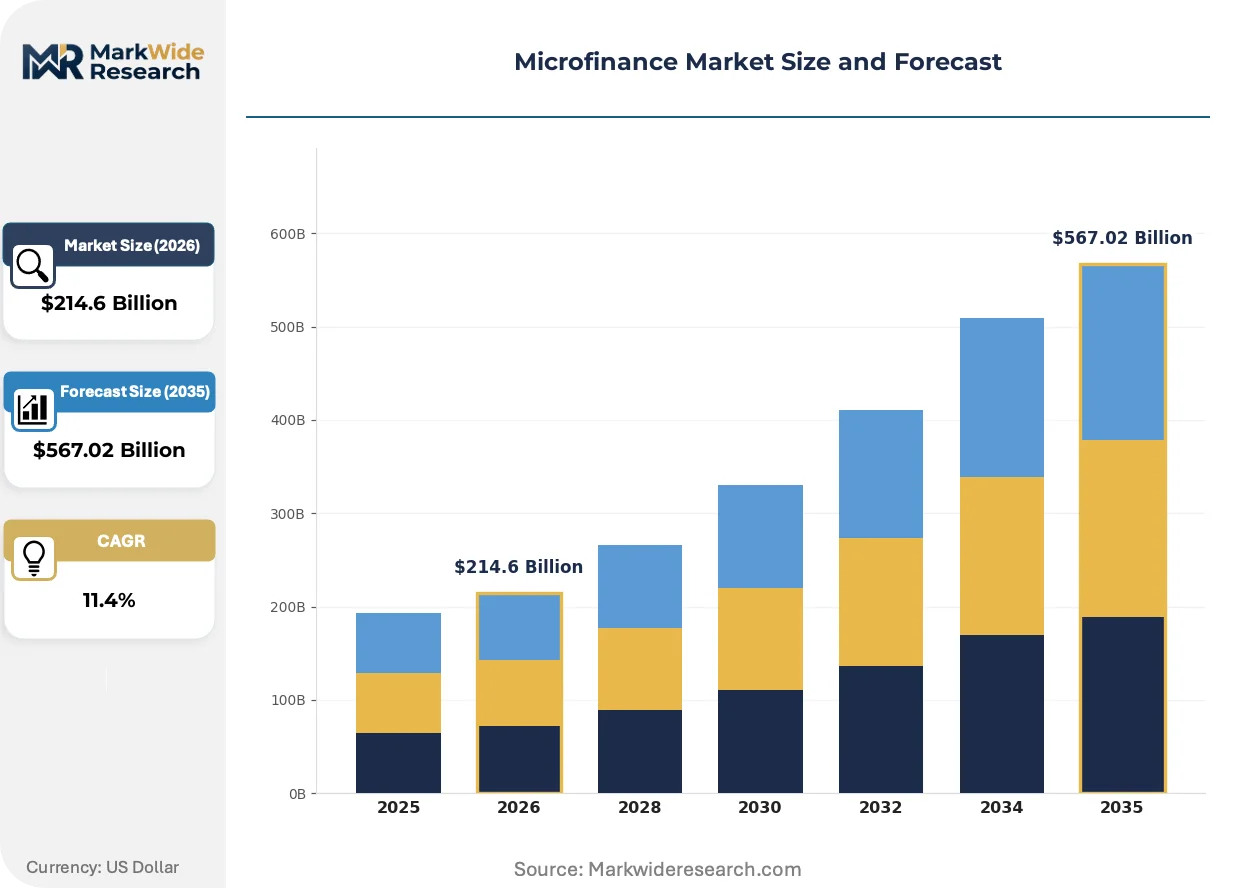
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $567.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microloans, Savings Accounts, Insurance, Financial Education Customer Type: Small Entrepreneurs, Low-Income Households, Women, Youth Delivery Model: Direct Lending, Peer-to-Peer, Mobile Platforms, Cooperative Model Loan Purpose: Business Expansion, Agriculture, Education, Housing |
| Companies Covered | Grameen Bank, Bandhan Bank, Accion International, ASA International, Compartamos Banco, SKS Microfinance, BRAC, FINCA International, Bank Rakyat Indonesia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfinance Market Strategic Shifts
Agent banking networks and API-based core banking platforms are compressing operational cost structures across emerging market microfinance. Technology convergence between biometric identity verification and real-time payment settlement is reshaping customer onboarding workflows.
Artificial intelligence-powered credit scoring is consolidating alternative data sources—mobile money transaction histories, utility payment records, and psychometric testing—into automated underwriting engines. Rural cooperatives in Bangladesh and India are adopting these tools to serve thin-file borrowers excluded from traditional bureau scoring. The shift is consolidating risk assessment functions previously performed by field credit officers into centralized algorithmic decisioning.
India's RBI digital lending guidelines and Bangladesh's Microcredit Regulatory Authority data protection directives are mandating consent-based data sharing and algorithmic transparency in automated underwriting. Licensed institutions must now disclose credit decision logic to declined applicants. The regulatory pressure is most acute for non-bank financial companies scaling app-based origination, forcing architecture redesigns to embed explainable AI modules.
Borrower preference is rotating toward fully digital disbursement and repayment channels, displacing cash-heavy field collection models. Agricultural microloan recipients in India's Maharashtra and Karnataka states now demand same-day mobile wallet credit over branch-based check issuance. The behavioral shift is compressing turnaround times from application to disbursement from weeks to hours, rewarding institutions with integrated payment infrastructure.
Microfinance Market Segmentation
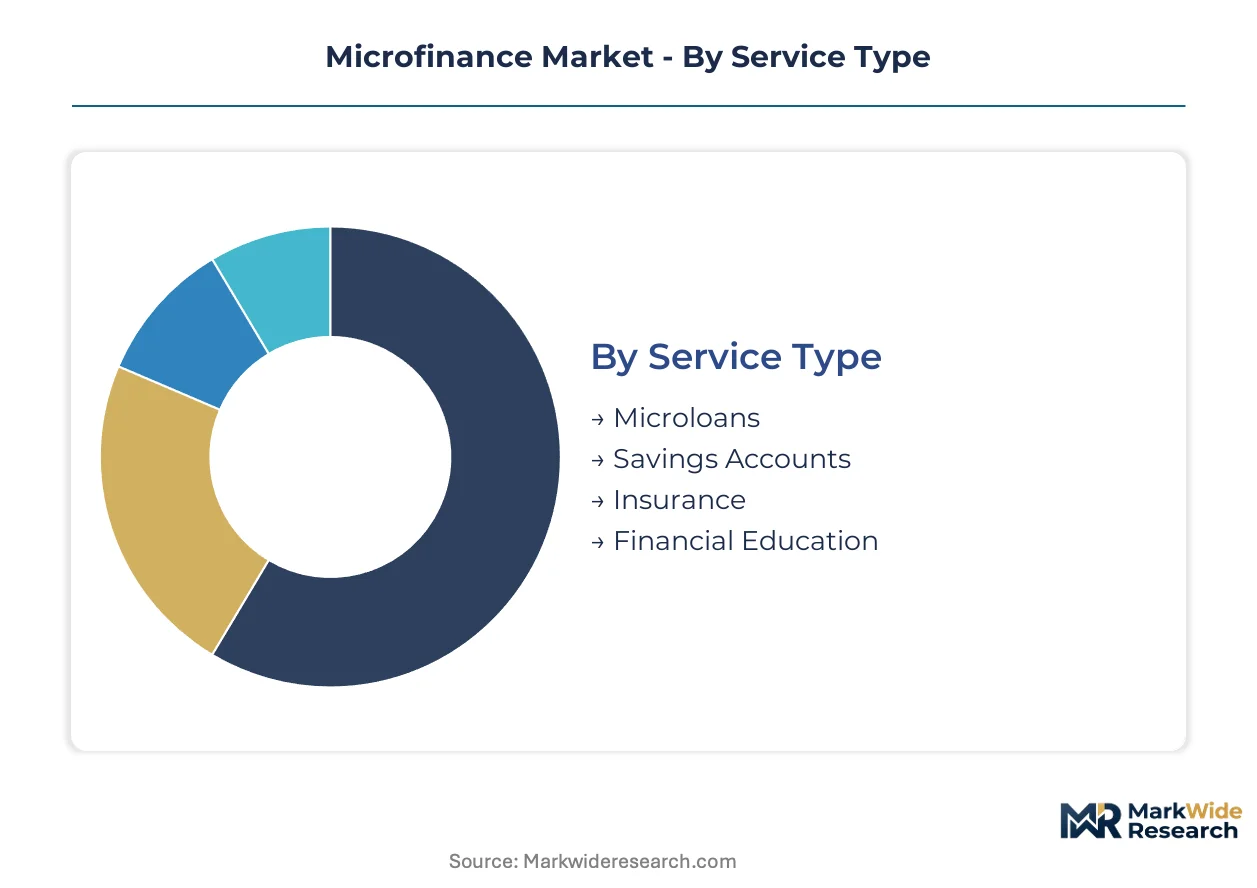
Segmentation in microfinance reveals how capital flows diverge across borrower profiles, delivery technologies, and use cases. Providers calibrate product architecture, pricing, and field operations to each slice's risk-return profile and regulatory treatment.
Service Type:
Credit products dominate transaction volume while deposit mobilization determines funding cost structure and regulatory classification.
- Microloans:Principal revenue engine for most institutions, typically under $1,000 principal with weekly or monthly amortization. Demand concentrates among small entrepreneurs in India's Maharashtra and Bangladesh's Dhaka division, driven by RBI priority sector lending rules channeling bank liquidity toward intermediaries. Group guarantee mechanisms substitute for collateral in rural deployments.
- Savings Accounts:Voluntary deposit products deepen client relationships and reduce wholesale borrowing dependence. Bandhan Bank's banking license enables regulated liability gathering, differentiating its cost structure from unregulated competitors across West Bengal and Assam. Deposit mobilization accelerates where mobile platform integration reduces branch dependency.
- Insurance:Microinsurance bundles—particularly climate-indexed crop coverage—attach to agricultural loan portfolios across India's Karnataka and Bangladesh's Rajshahi division. Premium collection leverages existing field officer networks.
- Financial Education:Non-revenue training modules improve repayment discipline and cross-sell conversion. Deployment tracks group lending programs in rural South Asia where borrower literacy gaps are widest.
Mature deployment sits with Microloans. Newer deployment is concentrated in Insurance.
Customer Type:
Demographic targeting shapes collection methodology, social collateral effectiveness, and regulatory reporting requirements.
- Women:Grameen-style solidarity groups produce superior repayment rates through peer monitoring and social sanction. Portfolio quality concentrates in gender-targeted programs across rural Bangladesh and India's Bihar state. RBI mandates and donor priorities channel subsidy toward female borrower acquisition.
- Small Entrepreneurs:Microenterprise borrowers generate larger ticket sizes and longer tenors than consumption loans. Demand clusters in Bangladesh's garment supply chain periphery and India's Tamil Nadu manufacturing belts, where working capital gaps persist despite formal banking penetration.
- Low-Income Households:Subsistence-level borrowers require smaller principals and more intensive field officer contact. Deployment tracks agricultural cycles in rain-fed districts where income volatility demands flexible repayment schedules.
- Youth:First-time borrowers with thin credit files attract digital-first origination platforms using alternative data scoring. Mobile money interoperability enables instant disbursement to urban informal settlements where traditional group mechanisms fail.
Women borrowers anchor portfolio quality. Youth segments are climbing the fastest as digital onboarding reduces acquisition friction.
Delivery Model:
Channel economics determine customer acquisition cost, geographic reach, and regulatory capital requirements.
- Mobile Platforms:API-based origination and real-time payment rails compress operational overhead and enable instant disbursement. Concentrated demand in Bangladesh's bKash-integrated corridors and India's UPI-enabled rural districts, where smartphone penetration crosses critical thresholds. Regulatory pressure from RBI digital lending guidelines mandates consent-based data architecture.
- Direct Lending:Branch and field officer networks sustain relationship-intensive underwriting for thin-file borrowers. Deployment persists where social collateral requires physical group formation in Bangladesh's char islands and India's northeastern tribal belts.
- Peer-to-Peer:Platform-mediated individual lending bypasses traditional intermediaries, concentrating in urban India where credit bureau coverage enables algorithmic pricing. Regulatory ambiguity constrains scale relative to licensed institutions.
- Cooperative Model:Member-owned structures mobilize local savings and retain surplus within community boundaries. Prevalent in India's Kerala and Maharashtra where historical cooperative banking infrastructure provides regulatory template.
Direct Lending retains volume leadership. Mobile Platforms are gaining share fastest as payment infrastructure matures.
Loan Purpose:
Use case segmentation dictates tenor structure, collateral substitutes, and climate risk exposure.
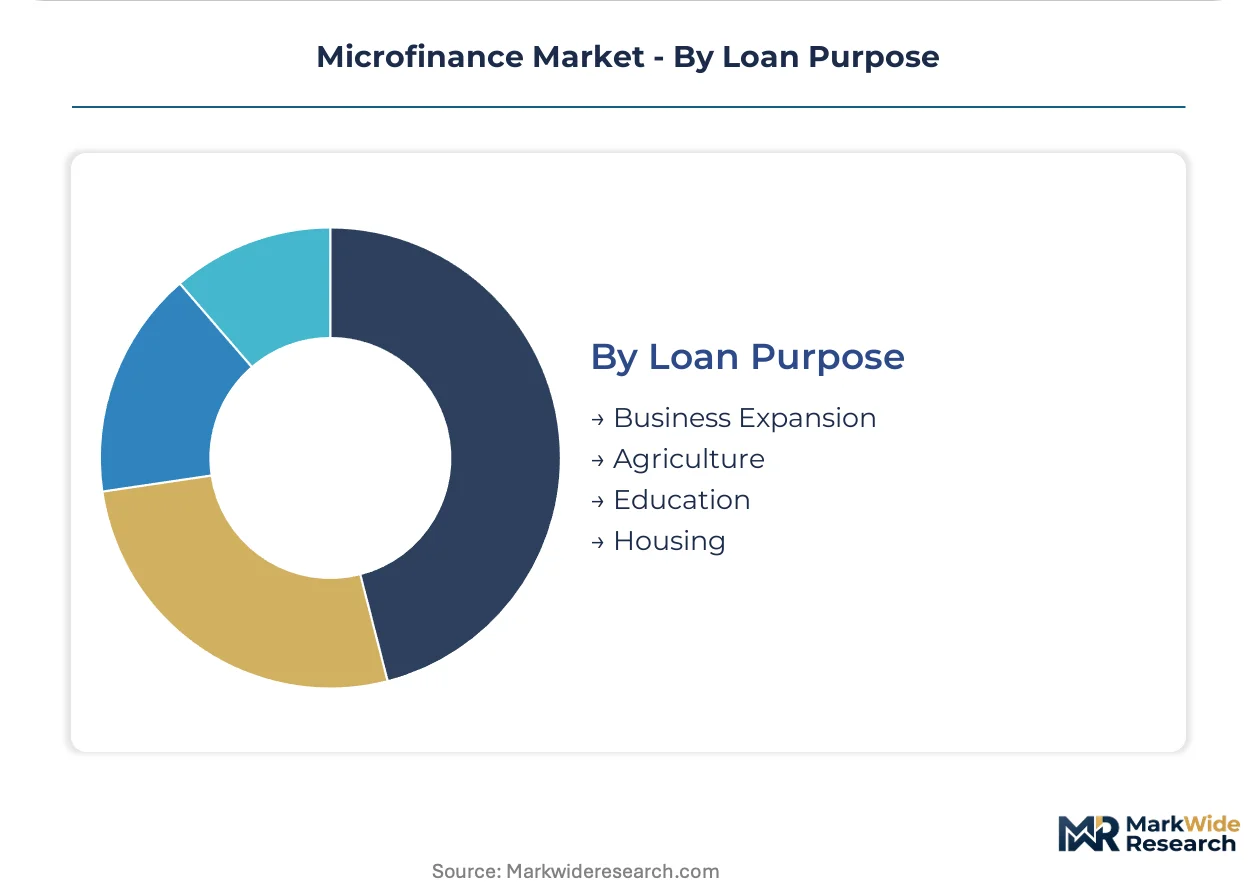
- Business Expansion:Working capital and fixed asset financing for microenterprises generates highest yield but concentrated default risk during demand shocks. Demand anchors in Bangladesh's Dhaka-Chittagong corridor and India's Gujarat industrial clusters.
- Agriculture:Seasonal input financing and post-harvest liquidity align with crop cycles. Climate-indexed insurance bundles mitigate rainfall volatility exposure in India's Maharashtra and Bangladesh's drought-prone northwest. RBI priority sector classification channels subsidized refinance.
- Education:School fee and vocational training loans carry longer tenors and moral hazard challenges where borrower and beneficiary diverge. Deployment tracks urban migration corridors in India and Bangladesh.
- Housing:Incremental construction finance for rural shelter improvements requires extended repayment schedules and land title verification. Concentrated in India's Tamil Nadu and Bangladesh's maturing microfinance markets where graduated borrowers seek asset accumulation.
Business Expansion commands margin concentration. Agriculture is expanding most quickly as climate insurance products mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export processing zones across South Asia concentrate microfinance operations where garment workers and small entrepreneurs cluster. India's special economic zones in Maharashtra and Tamil Nadu anchor demand from informal sector employees seeking working capital. Bangladesh's export-oriented manufacturing belts drive concentrated portfolio growth among female factory workers.
India
Maharashtra's sugar belt and Tamil Nadu's textile corridors generate concentrated demand for crop and working capital financing. RBI's priority sector lending mandates compel commercial banks to allocate 40 percent of adjusted net bank credit to underserved segments. Karnataka's Bangalore Rural district demonstrates mobile platform penetration where smartphone-enabled disbursement replaces branch dependency.
Bangladesh
Dhaka's garment supply chain periphery and Chittagong's port-centered logistics networks anchor microenterprise borrowing. The Microcredit Regulatory Authority imposes lending rate ceilings that compress margins while licensing formal institutions. Grameen Bank's original service territory in Tangail district sustains group-based methodologies that rural cooperatives replicate nationwide.
Indonesia
Java's rice-growing provinces and Sumatra's palm oil belt generate seasonal demand for agricultural input financing. OJK supervision embeds sharia compliance into product architecture through Bank Rakyat Indonesia's rural unit network. East Java's Surabaya corridor demonstrates technology convergence between cooperative structures and mobile payment rails.
Kenya
Nairobi's urban informal settlements and Rift Valley's dairy cooperatives anchor divergent delivery models for youth and agricultural borrowers. The central bank's digital credit regulations mandate transparency in automated underwriting algorithms. M-Pesa integration across the Safaricom network enables instant disbursement that compresses turnaround times from weeks to hours.
Mexico
Mexico City's metropolitan periphery and Oaxaca's indigenous communities generate demand for solidarity group lending adapted to urban informal settlements. CNBV microfinance regulations govern non-bank financial institutions with tiered capital requirements. Puebla's automotive supplier belt demonstrates working capital gaps among second-tier manufacturing subcontractors.
Microfinance Market Competitive Environment
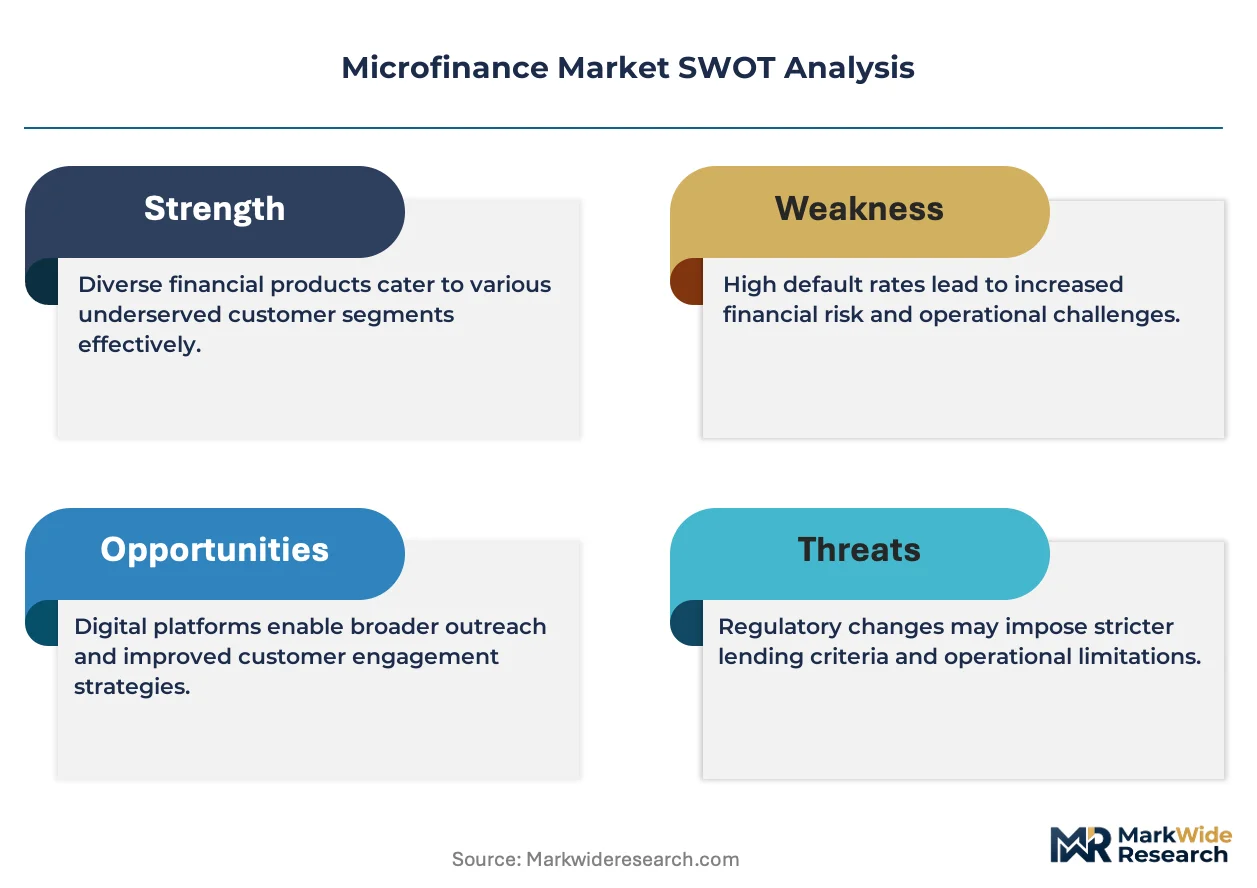
Top-tier vendors anchor regulated banking licenses, while unregulated non-bank financial companies compete on origination velocity. The market structure fragments across cooperative networks, commercial bank subsidiaries, and specialized microfinance institutions with divergent funding costs. Strategic archetypes include deposit-taking banks with liability advantages, technology-enabled non-banks with compressed acquisition costs, and member-owned cooperatives with localized social collateral. Dominant competitive moves encompass mobile platform integration and portfolio diversification into insurance and savings products.
Among Bangladesh-based institutions, Grameen Bank exemplifies the cooperative archetype with its foundational group-lending methodology, while BRAC occupies a position spanning microfinance and broader development services. Bandhan Bank represents the licensed banking trajectory, having converted from non-bank status to capture deposit-taking privileges. These three entities anchor distinct strategic positions within South Asian microfinance without overlapping operational models.
| Leading Market Players |
|---|
| Grameen Bank |
| Bandhan Bank |
| Accion International |
| ASA International |
| Compartamos Banco |
| SKS Microfinance |
| BRAC |
| FINCA International |
| Bank Rakyat Indonesia |
| Others |
Value Chain & Pricing Dynamics
Mobile-first origination platforms are compressing field officer deployment costs while simultaneously concentrating liquidity access among licensed deposit-taking institutions. This technology shift reshapes cost economics by displacing branch-heavy distribution models and amplifying pricing power for entities with integrated payment infrastructure.
Pricing Analysis
Lead-time-driven pricing separates instant-disbursement digital loans from branch-processed credit with multi-week turnaround. Premium pricing attaches to same-day mobile wallet disbursement in India's UPI-enabled corridors, while spot inventory of pre-approved credit lines commands discounts. Price differentiation hinges on regulatory licensing status and geographic delivery density. Pricing pressure stems from Bangladesh's Microcredit Regulatory Authority interest rate ceilings compressing net interest margins. Unregulated non-bank financial companies exhibit highest price sensitivity due to wholesale funding dependence.
Supply Chain Analysis
Capital supply rests on commercial bank wholesale lending, development finance institution facilities, and retail deposit mobilization. India, Bangladesh, and Indonesia anchor liquidity concentration through RBI priority sector mandates, MRA licensing frameworks, and OJK sharia supervision respectively. Raw material dependencies include field officer labor pools, core banking software licenses, and biometric identity verification infrastructure. Single-source vulnerability concentrates in legacy core banking system migrations. Distribution runs through agent banking networks, mobile money interoperability rails, and cooperative member structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deposit-taking license scarcity props pricing power for regulated institutions while constraining capital access for unregulated competitors. This supply-constrained dynamic concentrates margin pools among banking-license holders.
For Market Incumbents: Hedge against interest rate compression by deepening mobile platform integration to reduce cost-to-serve. Expand liability management through savings-led products that lower wholesale borrowing dependence. Acquire field officer retention capabilities as talent scarcity threatens portfolio quality in rural Bangladesh and India's northeastern states. For New Entrants and Emerging Players: Launch via API-based origination partnerships with established mobile money operators to bypass branch infrastructure requirements. Target youth segments in urban informal settlements where traditional group guarantee mechanisms fail and alternative data scoring enables thin-file underwriting. Pursue white-space in climate-indexed microinsurance bundling for agricultural borrowers. For Investors and Strategic Acquirers: Exit pathways concentrate in deposit-taking license conversions and technology-enabled non-bank acquisitions. Long-term viability favors institutions with integrated payment infrastructure and diversified product portfolios spanning credit, savings, and insurance. Watch regulatory treatment of algorithmic underwriting transparency as inflection indicator for digital lending scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Deposit-Taking License Conversion | Captures retail funding cost advantage under RBI and MRA supervision frameworks. |
| Mobile Platform Integration | Compresses customer acquisition costs through bKash and UPI interoperability rails. |
| Sharia-Compliant Product Expansion | Accesses religiously constrained borrower segments via OJK-supervised architecture. |
| Climate-Indexed Insurance Bundling | Mitigates rainfall volatility exposure for Maharashtra and Rajshahi agricultural portfolios. |
| Alternative Data Scoring Deployment | Enables thin-file youth underwriting through psychometric and mobile money transaction analysis. |
Study Parameters
Independent corroboration across microfinance institution portfolio managers, central bank regulatory supervisors, and mobile money platform executives underwrites the qualitative findings. Secondary validation draws from RBI circulars, Bangladesh Bank annual reports, OJK regulatory filings, and CGAP industry databases. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from pricing evolution and mix-shift effects throughout the forecast period. Segmentation dimensions encompass service type, customer demographic, delivery channel, and loan purpose categories. CAGRs derive from time-series regression of historical portfolio growth adjusted for regulatory intervention points. Forecast inputs incorporate mobile penetration trajectories and priority sector lending mandate compliance rates.
Regulatory rate cap adjustments, mobile money interoperability failures, and field officer labor market tightening are the dominant revision risks. Forecasts reflect documented assumptions regarding technology adoption curves and supervisory enforcement intensity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Truck Financial Leasing Market