
 Car Finance Market | 2026-2036
Car Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Car Finance Market Intelligence
Captive finance arms of major automakers is broadening their balance-sheet capacity across North America and Asia. Toyota Financial Services leverages its parent manufacturer's dealer network to sustain low-cost funding advantages. Ally Financial anchors its position through direct-to-consumer digital channels that bypass traditional dealership intermediaries. GM Financial differentiates by integrating lease-end vehicle remarketing with new origination flows.
Car finance encompasses secured and unsecured credit instruments used to fund vehicle acquisition, typically structured with fixed or floating interest rates, loan terms spanning 36 to 84 months, and collateralized by the underlying automobile. Its primary commercial purpose is to convert high-ticket durable goods into affordable periodic payments, expanding addressable demand beyond cash buyers. Loans dominate origination volumes across prime and super-prime credit profiles, where interest rate compression has eroded margin pools and forced scale-dependent profitability. Subprime and near-prime segments command higher yield spreads but carry elevated loss severity, concentrating risk-adjusted returns among specialty servicers with granular underwriting capabilities. Online platforms within direct lending are displacing indirect dealership-arranged financing as borrowers prioritize rate transparency and pre-approval speed.
Federal Reserve policy on benchmark interest rates shapes consumer affordability and lender net interest margins across the United States. The Consumer Financial Protection Bureau enforces fair lending standards and disclosure protocols that constrain pricing flexibility and documentation requirements. Basel III capital adequacy frameworks impose risk-weighted asset treatment on automotive loan portfolios, influencing bank-held versus securitized funding strategies. Stakeholders must monitor central bank rate trajectories and regulatory capital rules to calibrate origination appetite and funding mix through the forecast horizon.
Market Dynamics
Digital lending infrastructure is compressing origination timelines from days to minutes, forcing traditional bank channels to rebuild their front-end workflows around API-first credit decisioning engines.
Growth Catalysts
- Embedded finance APIs:Auto dealers in Germany and France are integrating white-label lending modules directly into digital showrooms, collapsing the financing-application abandonment rate.
- India's PLI scheme for automotive manufacturing:Domestic vehicle production subsidies are expanding the addressable pool of financeable assets for non-bank financial companies.
- Alternative data underwriting:Cash-flow-based credit models using real-time banking transaction feeds are extending approval coverage to thin-file borrowers previously excluded from prime rate tiers.
Market Restraints
- Central bank rate volatility:Federal Reserve benchmark adjustments transmit directly into consumer APRs, compressing net interest margins for fixed-rate originators during hiking cycles.
- Residual value uncertainty:Battery degradation curves in electric vehicles lack standardized depreciation tables, elevating lease-end risk for captive finance arms.
- Securitization market concentration:Automotive ABS distribution depends on a narrow base of institutional buyers in the United States and United Kingdom, amplifying funding cost spikes during credit stress.
Strategic Opportunities
- Subscription-to-ownership bridges:Flexible term structures allowing lessees to convert monthly payments toward equity accumulation are penetrating urban markets in Spain and Italy.
- EU Green Deal vehicle incentives:Member-state tax credits for zero-emission fleet acquisitions are creating dedicated green auto loan product lines with preferential capital treatment.
- Telematics-integrated pricing:Usage-based insurance data streams merged with loan servicing platforms enable dynamic rate adjustments tied to actual driving behavior.
Industry Challenges
- Legacy core system fragmentation:Regional bank lenders operate on decades-old loan origination software that cannot support real-time API integrations with dealer management systems.
- Cross-border regulatory arbitrage:Fintech platforms originating in jurisdictions with lighter consumer protection frameworks face enforcement actions when serving borrowers in stricter markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Finance Market |
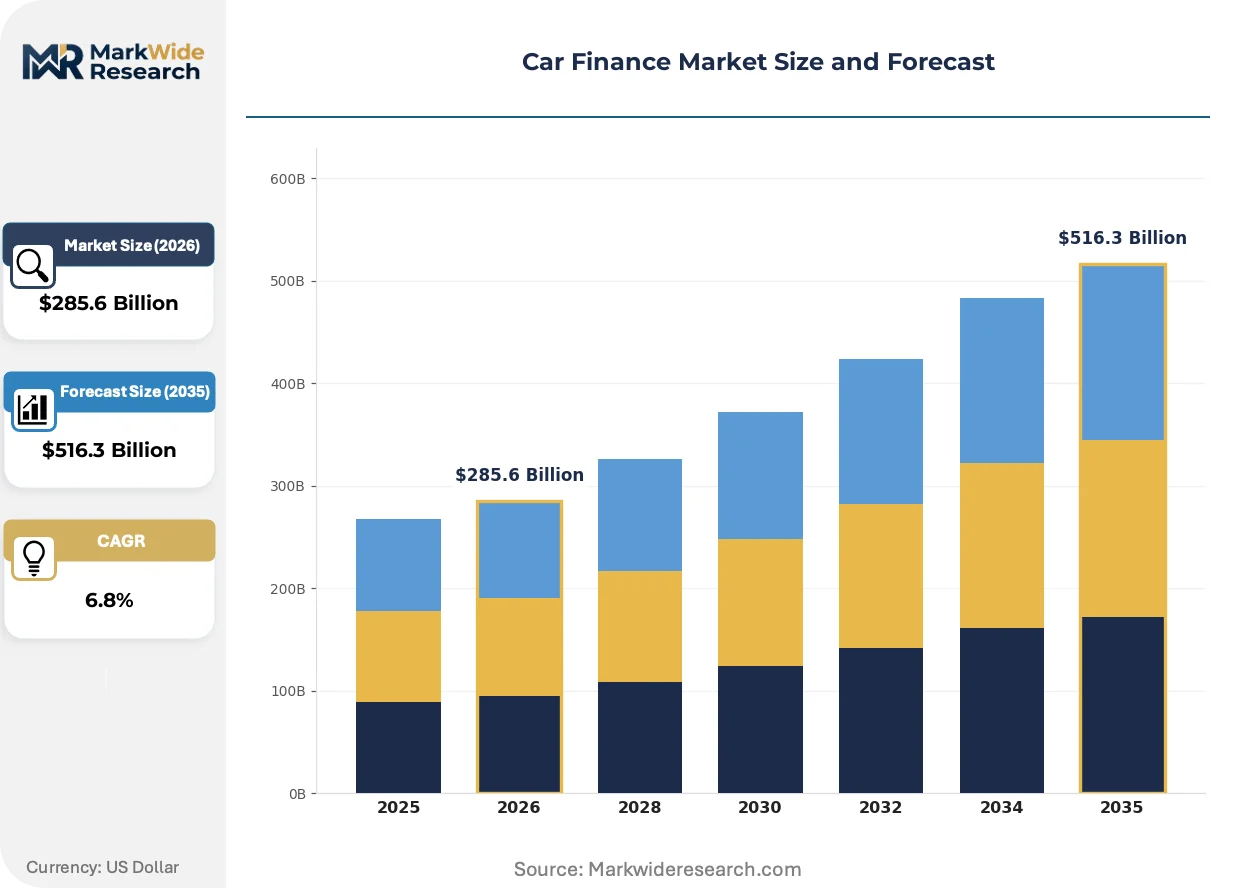
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $516.3 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loans, Leases, Hire Purchase, Balloon Payments Customer Type: Individuals, Businesses, Fleet Operators, Dealerships Service Type: Direct Lending, Indirect Lending, Credit Unions, Online Platforms Credit Profile: Prime, Subprime, Super Prime, Near Prime |
| Companies Covered | Ford Motor Credit, Bank of America, Ally Financial, Santander Consumer USA, JPMorgan Chase Auto, Toyota Financial Services, GM Financial, Wells Fargo Auto, Capital One Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Finance Market Strategic Shifts & Innovations
Artificial intelligence is rewiring credit risk assessment from static FICO scores toward dynamic behavioral scoring, while regulatory pressure on algorithmic fairness is forcing transparency into previously opaque machine-learning models.
Machine-learning credit decisioning is electrifying the speed and granularity of subprime borrower evaluation. Specialty auto lenders in Texas and Florida are deploying neural networks that ingest rent-payment histories and gig-economy income verification. This compression of underwriting cycle time is enabling same-day vehicle delivery for borrowers previously subject to multi-day manual review queues.
The Consumer Financial Protection Bureau's adverse action notice requirements are tightening documentation standards for automated credit denials. Lenders must now produce specific reasons derived from model outputs rather than generic decline codes. The subprime segment faces the steepest compliance cost increases as legacy systems require retrofitting for interpretable AI architectures.
Fleet procurement departments are consolidating vehicle acquisition decisions into centralized procurement functions with dedicated finance desks. This organizational shift is displacing the traditional model where individual location managers arranged financing through local dealer relationships. The transformation is most visible among last-mile delivery operators in California and Illinois seeking standardized national rate structures.
Car Finance Market Segmentation
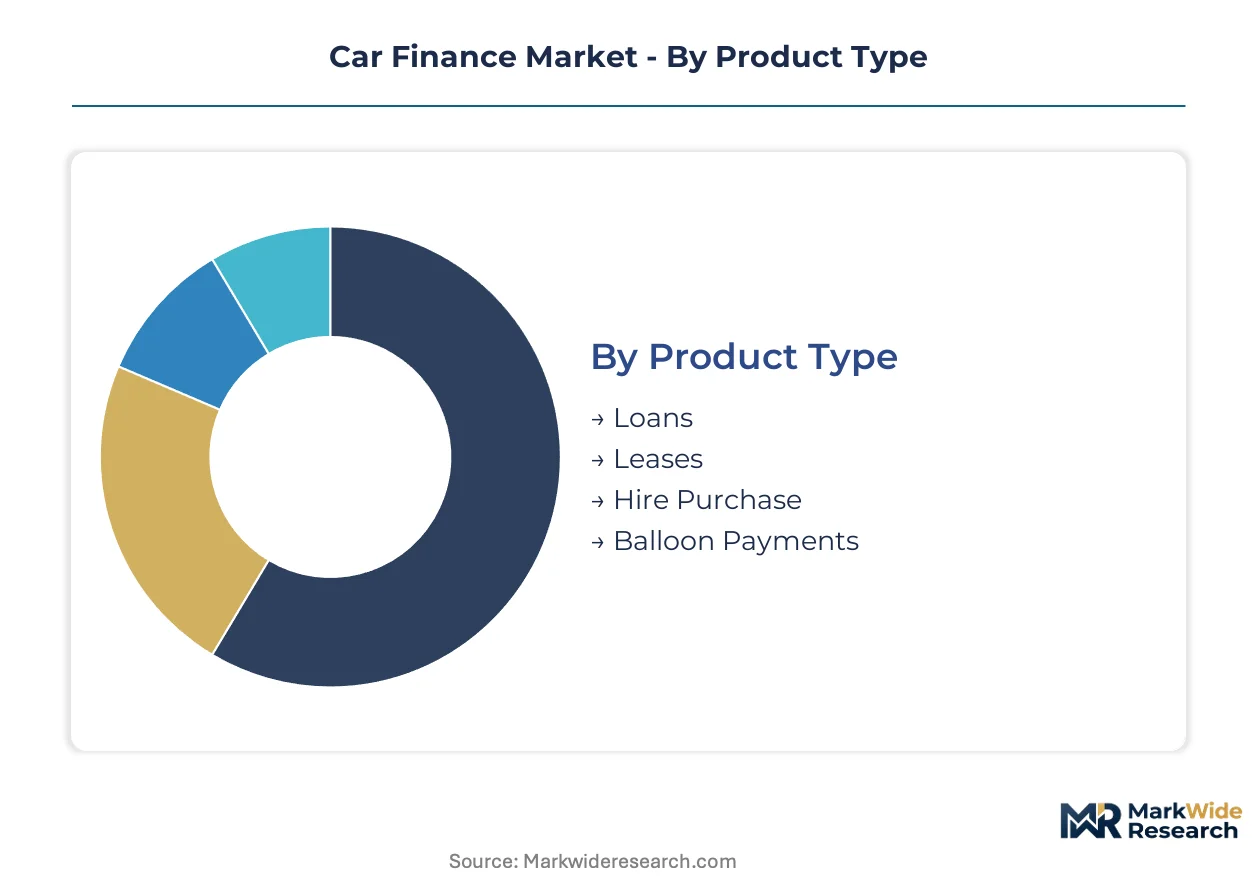
Car finance segmentation reveals how capital flows differently across product structures, borrower profiles, and distribution channels. Each dimension carries distinct risk-weighting implications for lender balance sheets and regulatory capital requirements.
Product Type:
Supply concentration in installment credit products dominates lender origination systems, with lease structures demanding specialized residual value infrastructure.
- Loans:Fixed-term amortizing debt instruments collateralized by vehicle titles. Banks in the United States and Germany concentrate term-loan origination for prime borrowers seeking 60-84 month maturities, though rising central bank rates compress net interest margins.
- Leases:Closed-end contracts transferring residual value risk to captive finance arms. European fleet operators in France and Italy favor operating leases for tax-advantaged balance sheet treatment, while battery degradation uncertainty elevates end-of-term risk for electric vehicle portfolios.
- Hire Purchase:Title-retention structures common in British Commonwealth markets. UK non-bank lenders dominate this segment through dealer-integrated installment plans.
- Balloon Payments:Low-monthly structures with large terminal obligations. Spanish and Portuguese borrowers favor these for cash-flow management, though refinancing risk concentrates at contract maturity.
Loans absorb the bulk of installed capacity; balloon payments are expanding most quickly in Southern European markets.
Customer Type:
Cost tier differentiation separates retail borrowers seeking rate transparency from commercial accounts demanding centralized procurement terms.
- Individuals:Retail borrowers accessing credit through dealership-arranged or direct channels. Digital pre-approval tools in the United States and United Kingdom accelerate purchase decisions for prime-rated consumers.
- Businesses:Corporate entities financing commercial vehicle fleets. German Mittelstand manufacturers favor captive finance for standardized national rate structures across multi-location operations.
- Fleet Operators:Specialized logistics and delivery companies with centralized acquisition desks. Last-mile operators in California and Illinois consolidate procurement decisions into dedicated finance functions displacing local dealer relationships.
- Dealerships:Inventory floorplan financing and captive-arranged retail originations. US dealer groups leverage scale for preferential wholesale funding terms from manufacturer finance subsidiaries.
Individuals generate the highest origination volumes; fleet operators command the steepest pricing discounts.
Service Type:
Application-based channel segmentation distinguishes legacy intermediary models from API-first direct distribution.
- Direct Lending:Borrower-initiated applications bypassing dealership intermediaries. Ally Financial anchors US market share through digital rate-comparison platforms.
- Indirect Lending:Dealer-arranged financing through captive or third-party lender networks. Toyota Financial Services leverages parent manufacturer dealer density for low-cost funding advantages.
- Credit Unions:Member-owned cooperatives offering below-market rates. US community-chartered institutions concentrate auto lending in Midwest and Southeast states.
- Online Platforms:API-integrated digital lenders compressing origination timelines to minutes. German and French auto dealers embed white-label modules into digital showrooms, collapsing application abandonment rates.
Indirect lending retains the largest transaction share; online platforms gain share fastest through mobile-first borrower acquisition.
Credit Profile:
Margin stratification concentrates profitability in non-prime segments where specialized underwriting capabilities justify yield spreads.
- Prime:Borrowers with established credit histories and stable income documentation. Interest rate compression in this segment forces scale-dependent profitability at major bank lenders.
- Subprime:Higher-risk borrowers with impaired credit histories or thin files. Texas and Florida specialty lenders deploy machine-learning models ingesting rent payments and gig-economy verification to compress underwriting cycles.
- Super Prime:Top-tier credit scores qualifying for manufacturer-subsidized promotional rates. Captive finance arms use this segment to drive new vehicle sales volume.
- Near Prime:Transitional borrowers between prime and subprime classifications. Alternative data underwriting using real-time banking feeds extends approval coverage previously excluded from standard rate tiers.
Prime segments dominate balance-sheet deployment; subprime origination delivers the steepest risk-adjusted returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum refining clusters along the Gulf Coast supply the polymer feedstocks essential to automotive interior manufacturing. Vehicle finance penetration rates correlate with regional industrial employment density and dealership network maturity.
United States
Subprime lending demand concentrates in Texas and Florida where specialty lenders deploy machine-learning underwriting models. The Consumer Financial Protection Bureau enforces adverse action notice requirements that tighten documentation standards for automated credit denials. Dallas-Fort Worth anchors captive finance operations with centralized lease-end remarketing facilities.
Germany
Mittelstand manufacturers favor captive finance for standardized national rate structures across multi-location fleet operations. The KBA enforces type-approval standards that influence residual value calculations for lease pricing. Stuttgart's automotive finance cluster integrates white-label lending modules into digital dealer showrooms.
China
Domestic vehicle production subsidies under the MIIT framework expand the addressable pool of financeable assets for non-bank financial companies. The NMPA regulates consumer credit disclosure protocols that constrain pricing flexibility. Shanghai's Yangtze River Delta concentration hosts API-first digital lending platforms compressing origination timelines.
India
Non-bank financial companies penetrate tier-2 and tier-3 cities where traditional bank branch density remains thin. The RBI governs priority sector lending norms that influence auto loan portfolio composition. Maharashtra's Mumbai-Pune corridor anchors captive finance arms serving commercial vehicle fleet operators.
United Kingdom
Hire purchase structures retain dominance through dealer-integrated installment plans administered by non-bank lenders. The Financial Conduct Authority enforces consumer credit affordability assessments that extend documentation requirements. London's fintech cluster develops alternative data underwriting using real-time banking transaction feeds.
Car Finance Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue embedded finance APIs and telematics-integrated pricing models. The market structure concentrates around captive finance subsidiaries of major automakers, diversified bank holding companies, and specialty non-bank lenders. Three archetypes dominate: manufacturer-captive funders leveraging dealer network density, direct-to-consumer digital platforms, and subprime specialists deploying granular underwriting capabilities. Competitive moves center on strategic partnerships with auto dealers and technology licensing for real-time credit decisioning engines.
Within the captive finance tier, Toyota Financial Services and GM Financial exemplify manufacturer-anchored funding advantages. Ally Financial occupies a position among direct-to-consumer digital lenders bypassing traditional dealership intermediaries. These three entities represent the dominant competitive archetypes shaping origination flow distribution across prime and non-prime segments.
| Leading Market Players |
|---|
| Ford Motor Credit |
| Bank of America |
| Ally Financial |
| Santander Consumer USA |
| JPMorgan Chase Auto |
| Toyota Financial Services |
| GM Financial |
| Wells Fargo Auto |
| Capital One Financial |
| Others |
Cost & Logistics Intelligence
Benchmark interest rate spreads feed directly into consumer APR tiers, compressing net interest margins for fixed-rate originators while floating-rate structures pass volatility through to borrower payments. Central bank policy trajectories in the United States and eurozone determine funding cost differentials across prime, near-prime, and subprime credit stratifications.
Pricing Analysis
Warranty and service bundling separates captive finance pricing from third-party lender offerings, with manufacturer-backed entities integrating maintenance packages and residual value guarantees into lease structures. Three-tier pricing stratification across promotional subvented rates, standard retail APRs, and risk-adjusted subprime yields reflects credit score segmentation and collateral type. Pricing pressure stems from Federal Reserve benchmark adjustments that transmit immediately into consumer affordability calculations. Fleet operators exhibit lowest price sensitivity due to centralized procurement scale, while thin-file retail borrowers face steepest rate spreads.
Supply Chain Analysis
Dual-sourcing requirements for ABS distribution channels mandate relationships with multiple institutional buyers to mitigate funding cost spikes during credit stress periods. Securitization infrastructure concentrates in the United States and United Kingdom, with automotive ABS issuance drawing from dealer floorplan receivables, retail installment contracts, and lease residuals. Raw material dependencies center on vehicle production volumes, polymer feedstocks for interior components, and lithium-ion battery supply chains. Single-source vulnerability exists in institutional investor concentration for subprime ABS tranches. Distribution runs through captive finance arms, bank holding companies, and specialty non-bank lenders with distinct funding cost structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance cost escalation under the Consumer Financial Protection Bureau's adverse action notice requirements erects barrier-to-entry moats favoring incumbents with interpretable AI architectures and legacy system retrofitting capital.
For Market Incumbents: Extend balance-sheet capacity into subprime segments where specialized underwriting capabilities justify yield spreads, while embedding white-label lending APIs into dealer management systems to defend against direct-to-consumer digital platforms. Machine-learning credit decisioning from emerging fintechs threatens dealership-arranged origination flows. Vertical integration into lease-end remarketing infrastructure anchors residual value realization. For New Entrants and Emerging Players: API-first origination platforms offer technology-first wedge into indirect lending channels where legacy bank systems cannot support real-time dealer integrations. White-space targets include tier-2 and tier-3 cities in India where non-bank financial company penetration remains thin, and near-prime borrower segments underserved by alternative data underwriting. Go-to-market positioning should emphasize cash-flow-based credit models using real-time banking transaction feeds. For Investors and Strategic Acquirers: Captive finance arm divestiture announcements from distressed OEMs signal the leading indicator that balance-sheet consolidation opportunities are materializing. Long-term viability favors lenders with granular subprime underwriting capabilities and diversified funding mixes beyond securitization concentration. Target acquisition archetypes include specialty servicers with machine-learning infrastructure and established dealer relationships. Watch for central bank rate trajectory inflection as the primary demand sensitivity trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Deployment | White-label lending modules integrated into German and French digital showrooms collapse application abandonment rates. |
| Alternative Data Underwriting Infrastructure | Real-time banking transaction feeds extend approval coverage to thin-file borrowers previously excluded from prime tiers. |
| Lease-End Remarketing Integration | GM Financial's captive structure demonstrates how residual value realization anchors new origination flow economics. |
| Telematics-Integrated Pricing Development | Usage-based insurance data merged with loan servicing enables dynamic rate adjustments tied to actual driving behavior. |
| Green Auto Loan Product Line Launch | EU Green Deal member-state tax credits create dedicated zero-emission fleet financing with preferential capital treatment. |
Research Approach
Multi-period observation of central bank rate trajectories, securitization issuance volumes, and dealer inventory financing patterns anchored the trend analysis, supplemented by interviews with captive finance executives, subprime specialty lender underwriting heads, dealership operations managers, and institutional ABS portfolio managers. Secondary validation drew from Federal Reserve consumer credit data, Consumer Financial Protection Bureau enforcement actions, Basel Committee regulatory filings, and vehicle registration databases. Bottom-up origination volume modeling triangulated against top-down macroeconomic demand projections.
Input-output matrices mapped credit supply drivers against borrower demand segments across the projection horizon. Segmentation dimensions modeled encompass product type, credit profile tier, distribution channel, and regional regulatory framework. CAGRs derived from trend extrapolation of origination volumes adjusted for interest rate elasticity and loss severity assumptions. Industry-specific forecast inputs included battery degradation curve development for electric vehicle residual value modeling and embedded finance API adoption curves.
Several conditions sit outside the modeled scope, including geopolitical disruptions to automotive supply chains, abrupt regulatory shifts in consumer protection frameworks, and technological discontinuities in autonomous vehicle deployment. Forecasts reflect assumptions regarding central bank policy normalization paths and securitization market liquidity conditions. Deviation in Federal Reserve benchmark rate trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Japan Car Loan Market