

2-Ethoxy Propene Market Size, Share, and Industry Trends Forecast 2026-2036
2-Ethoxy Propene Market Insights
ISO 9001 certification for chemical intermediate suppliers is rotating the competitive landscape, filtering out unqualified producers and elevating contract manufacturers with documented quality systems. BASF leverages its integrated petrochemical network to secure feedstock continuity for 2-ethoxy propene derivatives. Dow anchors North American supply through its Gulf Coast manufacturing infrastructure. Sumitomo Chemical specializes in high-purity grades serving Japanese pharmaceutical customers with exacting specifications.
2-Ethoxy propene is a vinyl ether compound with the molecular formula C5H10O, manufactured through acid-catalyzed dehydration of acetaldehyde diethyl acetal or ethoxylation pathways, functioning primarily as a protected ketone equivalent and reactive intermediate in organic synthesis. Pharmaceutical synthesis applications dominate value capture due to stringent purity requirements and long qualification cycles for active pharmaceutical ingredient precursors. Agrochemical production segments compete on volume scale, while specialty chemicals occupy narrower margin pools with customized specifications.
EPA oversight under the Toxic Substances Control Act shapes manufacturing site approvals and emission controls for 2-ethoxy propene producers in the United States, while REACH registration requirements in Europe govern import volumes and substance data documentation. China's MEE enforces wastewater and air emission standards that affect operating costs at domestic production facilities. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance-driven supply reallocations and qualification burden shifts.
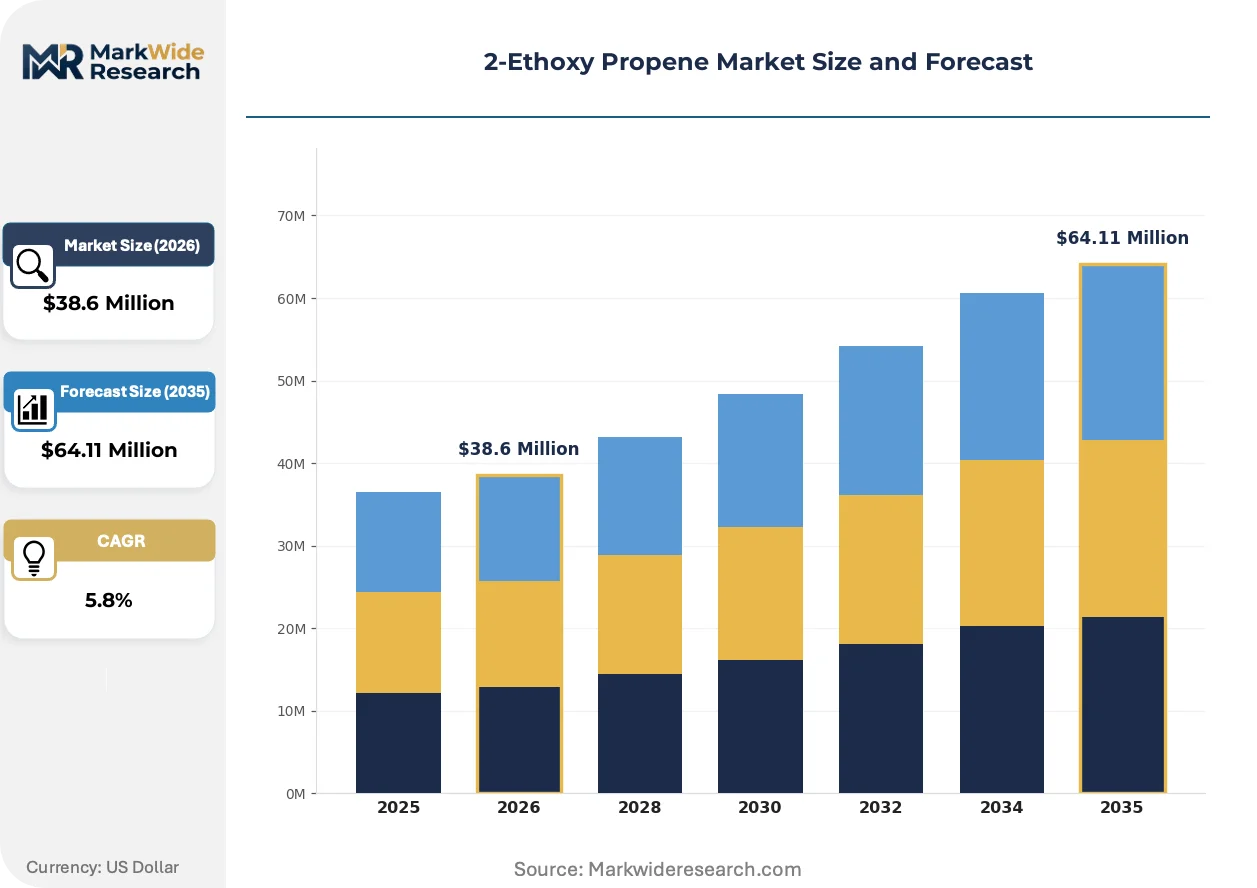
Market Dynamics
REACH registration requirements and EPA Toxic Substances Control Act enforcement are forcing specialty chemical manufacturers to requalify supply chains around documented purity thresholds, compressing the qualified supplier base for pharmaceutical-grade 2-ethoxy propene intermediates.
Growth Catalysts
- Contract manufacturing expansion:Pharmaceutical outsourcing to India and China is pulling demand for protected ketone equivalents with established pharmacopeial documentation.
- Agrochemical patent cliffs:Off-patent crop protection molecules require cost-efficient synthetic routes where vinyl ether intermediates reduce step count.
- ISO 9001 certification mandates:Procurement policies at Japanese and European formulators now exclude uncertified alkene suppliers from approved vendor lists.
Market Restraints
- Feedstock volatility:Acetaldehyde pricing swings tied to ethylene cracker economics transmit directly to 2-ethoxy propene production costs.
- Supplier concentration:Three integrated petrochemical groups control over 60% of merchant acetaldehyde diethyl acetal supply in East Asia.
- Substitution pressure:Methyl vinyl ether and isopropenyl acetate compete in selected deprotection chemistry applications.
Strategic Opportunities
- Indian pharmaceutical clusters:Hyderabad and Ahmedabad formulators are localizing intermediate procurement to reduce import duty exposure.
- Continuous flow synthesis:Microreactor technology for acid-catalyzed dehydration is opening modular production footprints below traditional scale thresholds.
- EU Green Deal alignment:Bio-based acetaldehyde feedstock pathways qualify for CSRD reporting benefits and green procurement preferences.
Industry Challenges
- Analytical capability gaps:Smaller producers lack in-house GC-MS and NMR infrastructure to generate REACH-compliant substance data dossiers.
- Qualification timeline compression:Pharmaceutical customers now demand 12-month stability data packages that strain undercapitalized contract manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Ethoxy Propene Market Trends and Innovations
Process intensification and regulatory data automation are restructuring how 2-ethoxy propene manufacturers compete, with technology adoption separating integrated producers from merchant specialists.
Continuous flow microreactor systems for acid-catalyzed dehydration are decomposing the traditional batch-reactor economics that favored large-scale petrochemical complexes. Mid-size Indian and Chinese manufacturers are piloting skid-mounted units to serve regional pharmaceutical clusters without building dedicated plants. This technology is decomposing capital barriers that previously locked out non-integrated entrants.
EU REACH Article 33 supply chain communication obligations are forcing substance data transmission through digital platforms rather than paper certificates of analysis. Downstream formulators in Germany and France now reject manual documentation for high-purity intermediates. Pharmaceutical API producers face the steepest compliance burden and are consolidating purchases with suppliers offering automated regulatory data interfaces.
Long-term offtake contracts with embedded price-adjustment mechanisms are displacing spot market purchasing for pharmaceutical-grade material. Japanese and Swiss generic drug manufacturers are locking in three-year supply agreements to secure qualification continuity. This pattern is most visible in Basel and Tokyo pharmaceutical corridors where regulatory changeover costs exceed raw material savings from competitive bidding.
2-Ethoxy Propene Market Segmentation
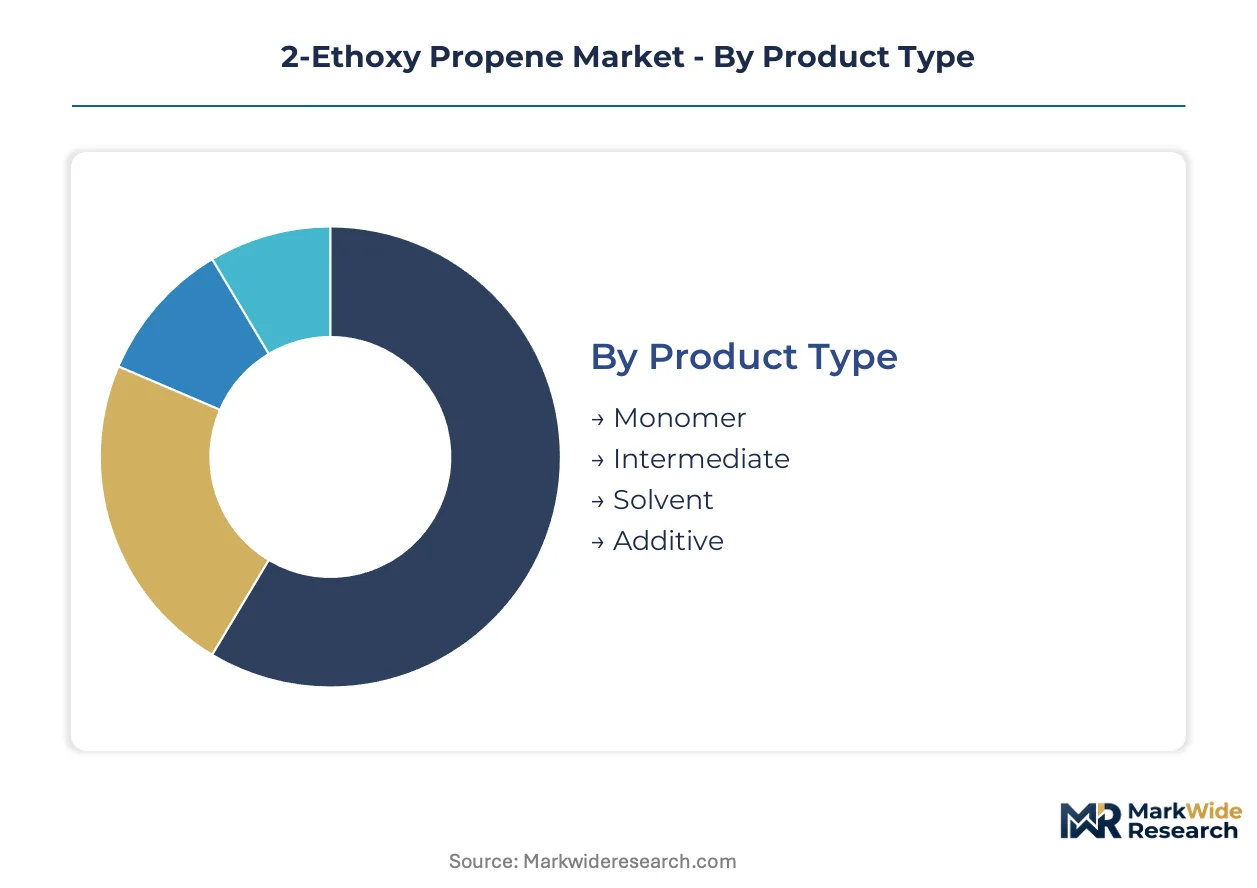
Segmentation in the 2-ethoxy propene market separates margin capture from volume throughput. Pharmaceutical-grade specifications command qualification premiums while agrochemical volumes compete on delivered cost per kilogram.
Product Type:
Margin pools concentrate in intermediates and monomers where purity documentation drives pricing power, while solvents and additives compete on functional equivalence.
- Monomer:Vinyl ether functionality enables polymerization and copolymerization chemistry. Demand clusters at BASF's Ludwigshafen complex and Dow's Freeport facility where captive acetaldehyde integration secures feedstock cost stability.
- Intermediate:Protected ketone equivalent specifications serve multi-step API synthesis with documented impurity profiles. Swiss and Japanese formulators in Basel and Tokyo pharmaceutical corridors lock in three-year offtake agreements to avoid requalification costs.
- Solvent:Hydrocarbon-compatible dissolution properties for coating formulations.
- Additive:Modification agent for polymer rheology and processing aids.
Intermediate holds installed capacity. Monomer is rotating up the share rankings.
Application:
Application segmentation tracks where synthetic route economics determine adoption velocity, with step-count reduction in complex molecules driving specification premiums.
- Pharmaceutical Synthesis:Deprotection chemistry and carbonyl protection in steroid and alkaloid routes. Hyderabad and Ahmedabad clusters are localizing procurement to reduce Indian import duty exposure on qualified material.
- Agrochemical Production:Off-patent crop protection molecules require cost-efficient synthetic routes. Chinese manufacturers in Jiangsu and Shandong provinces scale vinyl ether consumption for generic herbicide and fungicide actives.
- Coatings:UV-curable and moisture-cure systems for industrial finishes.
- Adhesives:Reactive diluent and tackifier modification in sealant formulations.
- Specialty Chemicals:Custom synthesis and fine chemical building blocks.
Pharmaceutical Synthesis captures value density. Agrochemical Production is expanding most quickly on volume tonnage.
End User Industry:
Customer type segmentation reveals procurement sophistication gaps, with pharmaceutical qualification requirements filtering supplier bases that chemical manufacturers access freely.
- Chemical Manufacturers:Merchant market participants purchasing on specification and delivery reliability. Sumitomo Chemical's high-purity grades serve Japanese pharmaceutical customers with exacting documentation requirements.
- Pharmaceutical Companies:API producers and contract development organizations demanding stability data packages. CDSCO registration requirements in India and FDA oversight in the United States shape documentation burdens that consolidate purchasing with qualified suppliers.
- Paints & Coatings Firms:Formulators prioritizing VOC compliance and cure speed.
- Agrochemical Producers:Generic manufacturers optimizing synthetic route economics.
Pharmaceutical Companies concentrate purchasing power. Chemical Manufacturers are gaining share fastest through continuous flow technology adoption.
Packaging Type:
Packaging segmentation reflects logistics cost structures, with bulk formats capturing scale economies and small containers serving distributed formulation sites.
- Bulk Tanks:Dedicated tanker delivery for high-volume pharmaceutical and agrochemical producers. Gulf Coast manufacturing infrastructure anchors North American supply through Dow's integrated logistics network.
- ISO Containers:Intermodal flexibility for qualified material moving between Basel, Tokyo, and Singapore pharmaceutical corridors. REACH Article 33 supply chain communication obligations force digital substance data transmission for these cross-border shipments.
- Drums:Standard 200-liter units for mid-scale chemical manufacturers.
- Bottles:Laboratory and pilot-scale quantities for R&D and custom synthesis.
Bulk Tanks dominate throughput volume. ISO Containers are climbing the fastest on international pharmaceutical trade expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in Basel, Tokyo, and Hyderabad drive qualified material procurement, while agrochemical manufacturers in Jiangsu and Shandong scale vinyl ether consumption for generic actives.
United States
EPA Toxic Substances Control Act enforcement shapes manufacturing site approvals for 2-ethoxy propene producers. Gulf Coast petrochemical infrastructure anchors North American supply through integrated acetaldehyde networks. Dow's Freeport facility leverages captive feedstock continuity to serve contract pharmaceutical manufacturers.
Germany
REACH registration requirements and Article 33 supply chain communication obligations compress the qualified supplier base for pharmaceutical-grade intermediates. ECHA substance data documentation standards govern import volumes from non-EU sources. BASF's Ludwigshafen complex dominates merchant supply through backward integration into acetaldehyde diethyl acetal production.
China
MEE wastewater and air emission standards raise operating costs at domestic production facilities in Jiangsu province. NMPA oversight of pharmaceutical intermediates aligns with international pharmacopeial documentation requirements. Shandong and Jiangsu manufacturing clusters scale vinyl ether consumption for agrochemical actives and API precursors.
India
CDSCO registration requirements and import duty exposure drive localization of intermediate procurement by Hyderabad and Ahmedabad formulators. PLI scheme incentives for active pharmaceutical ingredients accelerate backward integration into specialty chemical manufacturing. Gujarat and Telangana pharmaceutical corridors consolidate purchases with ISO 9001-certified alkene suppliers.
Japan
PMDA pharmacopeial standards and METI industrial chemical regulations enforce exacting purity specifications for protected ketone equivalents. JIS quality management requirements filter uncertified suppliers from approved vendor lists. Sumitomo Chemical anchors domestic supply through high-purity grades serving Tokyo and Osaka pharmaceutical customers.
2-Ethoxy Propene Market Competitive Landscape
Player mix skews toward integrated petrochemical groups with captive acetaldehyde supply and specialized high-purity manufacturers serving pharmaceutical corridors. Three strategic archetypes dominate: backward-integrated commodity producers, ISO-certified pharmaceutical-grade specialists, and regional contract manufacturers adopting continuous flow technology. Competitive moves center on long-term offtake contracting with embedded price-adjustment mechanisms and modular microreactor deployment for distributed production footprints.
Among integrated petrochemical groups, BASF and Dow exemplify the backward-integrated archetype through Ludwigshafen and Gulf Coast manufacturing infrastructure. Sumitomo Chemical occupies a position within the high-purity specialist tier, serving Japanese pharmaceutical customers with documented quality systems. These three anchors represent contrasting scale-to-specialization strategies that structure competitive positioning across pharmaceutical and agrochemical demand segments.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Syngenta |
| Bayer CropScience |
| FMC Corporation |
| UPL |
| Corteva |
| Sumitomo Chemical |
| Nippon Soda |
| Others |
Pricing and Supply Chain Analysis
REACH registration requirements and EPA Toxic Substances Control Act enforcement gate both supply qualification and price differentiation simultaneously, compressing the qualified supplier base for pharmaceutical-grade material while elevating documentation premiums over commodity grades. ISO 9001 certification mandates from Japanese and European formulators now exclude uncertified alkene suppliers from approved vendor lists, creating a dual-track market where certified producers capture qualification premiums and uncertified merchants compete on spot pricing.
Pricing Analysis
Long-term offtake contracts with embedded acetaldehyde price indexation dominate pharmaceutical-grade procurement, locking in three-year supply agreements between Basel and Tokyo formulators and their qualified suppliers. Price differentiation separates pharmacopeial-grade intermediates with documented impurity profiles from technical-grade monomers serving agrochemical applications. Cost compression in the technical-grade tier is intensifying because Chinese manufacturers in Jiangsu and Shandong are scaling vinyl ether consumption for generic herbicide actives. Agrochemical producers exhibit the highest price sensitivity, while Swiss and Japanese generic drug manufacturers prioritize qualification continuity over raw material savings.
Supply Chain Analysis
Merchant acetaldehyde diethyl acetal supply from integrated petrochemical groups in Germany, the United States, and Japan creates a feedstock chokepoint that underwrites cost stability for backward-integrated producers. Captive acetaldehyde networks at BASF's Ludwigshafen complex and Dow's Gulf Coast infrastructure rest on ethylene cracker economics that transmit volatility directly to vinyl ether production costs. Single-source vulnerability concentrates in East Asia where three integrated groups control over sixty percent of merchant acetaldehyde diethyl acetal supply. Distribution runs through dedicated tanker delivery for high-volume pharmaceutical and agrochemical producers, with ISO containers serving intermodal flexibility for qualified material moving between Basel, Tokyo, and Singapore pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from methyl vinyl ether and isopropenyl acetate in selected deprotection chemistry applications, defending their position through qualification depth rather than price competition alone.
For Market Incumbents: Compound backward integration into acetaldehyde diethyl acetal production to secure feedstock continuity against ethylene cracker volatility, while embedding automated regulatory data interfaces to meet REACH Article 33 supply chain communication obligations. ISO 9001 certification investment represents the critical lever for maintaining approved vendor status with Japanese and European formulators. Capacity addition in Gujarat and Telangana pharmaceutical corridors captures localization demand driven by CDSCO registration requirements and Indian import duty exposure. For New Entrants and Emerging Players: ISO 9001 certification fast-track through accredited bodies unlocks access to Hyderabad and Ahmedabad formulators localizing intermediate procurement to reduce import duty exposure. Continuous flow microreactor technology decomposes traditional capital barriers, enabling modular production footprints below conventional scale thresholds. The most penetrable segment sits in mid-scale pharmaceutical-grade intermediates where qualification timelines strain undercapitalized contract manufacturers. A go-to-market angle anchored to automated substance data transmission platforms addresses the steepest compliance burden facing downstream API producers. For Investors and Strategic Acquirers: EU Green Deal alignment reshapes the acquisition landscape by qualifying bio-based acetaldehyde feedstock pathways for CSRD reporting benefits and green procurement preferences. Long-term viability across a five-to-ten year window favors targets with documented quality systems and captive feedstock integration over merchant specialists exposed to commodity volatility. The acquisition target archetype combines ISO 9001 certification with backward-integrated acetaldehyde supply or continuous flow technology adoption. The signal to watch is regulatory divergence between REACH, EPA, and China's MEE enforcement patterns that could trigger supply reallocations and qualification burden shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acetaldehyde supply at BASF's Ludwigshafen complex secures feedstock cost stability against ethylene cracker volatility. |
| Long-term Supply Agreement | Three-year offtake contracts with Swiss and Japanese generic drug manufacturers lock in qualification continuity. |
| Green Manufacturing Transition | Bio-based acetaldehyde feedstock pathways qualify for EU CSRD reporting benefits and green procurement preferences. |
| Capacity Expansion | Modular microreactor deployment enables distributed production footprints serving regional pharmaceutical clusters. |
| Joint Venture | Technology partnerships between Indian contract manufacturers and European equipment suppliers accelerate continuous flow adoption. |
Research Methodology
Operator-level perspectives from plant managers at integrated petrochemical complexes, procurement leads at downstream pharmaceutical formulators, distribution channel partners serving agrochemical manufacturers, and technical R&D directors developing vinyl ether applications anchored the qualitative base. These primary interviews combined with customs and trade data from China and India, ACC and Cefic chemical industry reports, and SEC 10-K filings from publicly traded producers underwent bottom-up and top-down triangulation to validate volume and value estimates.
Sensitivity analysis across feedstock price scenarios, regulatory enforcement intensities, and substitution adoption rates informed the analytical framework. Segmentation dimensions modeled include grade tier separating pharmaceutical from technical specifications, end-use industry tracking pharmaceutical synthesis against agrochemical production, packaging format distinguishing bulk tanks from ISO containers, and regional production hub concentration in Germany, the United States, China, and India. CAGRs were derived from trend extrapolation anchored to documented contract manufacturing expansion and agrochemical patent cliff dynamics. Industry-specific forecast inputs incorporated REACH registration timelines and CDSCO localization incentives.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical outsourcing to India and China or accelerated continuous flow technology adoption would require recalibration. Forecasts reflect assumptions around regulatory enforcement continuity and feedstock price correlation patterns. Practitioners should keep alternative scenarios live as MEE wastewater standards, EPA site approval timelines, and EU Green Deal implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.