
 Nano-Bubble Generator Market | 2026-2036
Nano-Bubble Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Nano-Bubble Generator Market Analytics
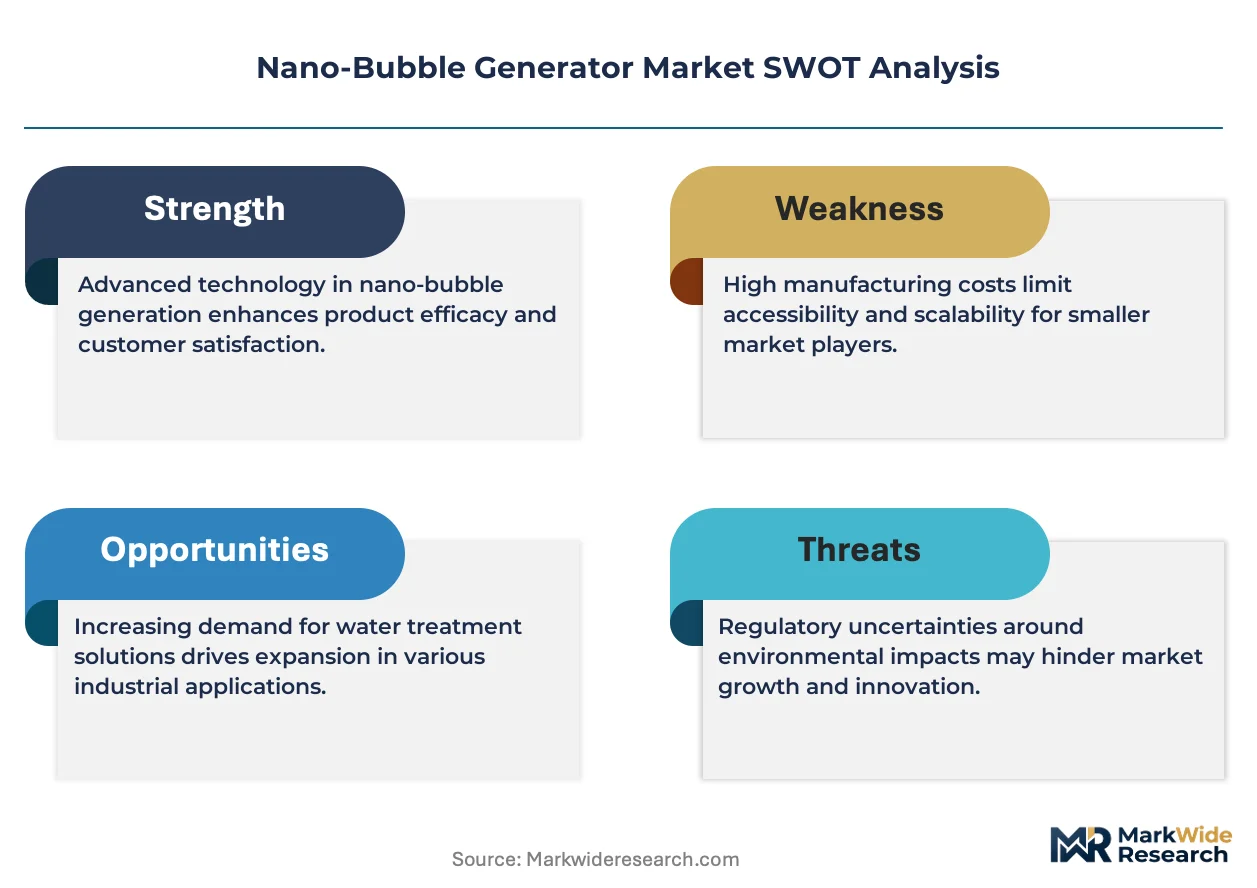
Japanese equipment manufacturing is hardening as a supply anchor for precision nano-bubble systems. TAISEI KOGYO leverages decades of fluid engineering expertise to dominate high-consistency generator output. Moleaer Inc. anchors North American demand through specialized aquaculture and agriculture deployments. Shandong Sundon Technology Co., Ltd. competes on manufacturing scale across fluidic and electrochemical product lines.
A nano-bubble generator produces gas-filled cavities below 200 nanometers in diameter through controlled hydrodynamic cavitation, pressure dissolution, or electrochemical methods, achieving mass transfer efficiencies exceeding conventional aeration by an order of magnitude. Fluidic generators lead commercial shipments due to simpler maintenance profiles and lower energy thresholds, while electrochemical variants capture premium positioning in medical and laboratory settings where bubble size distribution demands tight tolerances. Ultrasonic technology segments sustain higher margins despite capital intensity, whereas venturi-based systems dominate wastewater treatment installations where throughput volume governs procurement decisions.
The US EPA enforces effluent limitation guidelines that tighten biological oxygen demand thresholds, directly expanding generator retrofit cycles at municipal water treatment plants. Japan's METI and the EU REACH framework collectively steer material compatibility standards for wetted components, constraining supplier qualification pathways. China's Ministry of Ecology and Environment (MEE) has embedded nano-bubble aeration into provincial water quality improvement mandates, accelerating domestic certification requirements. Stakeholders must monitor evolving interoperability standards between generator control systems and smart water infrastructure platforms.
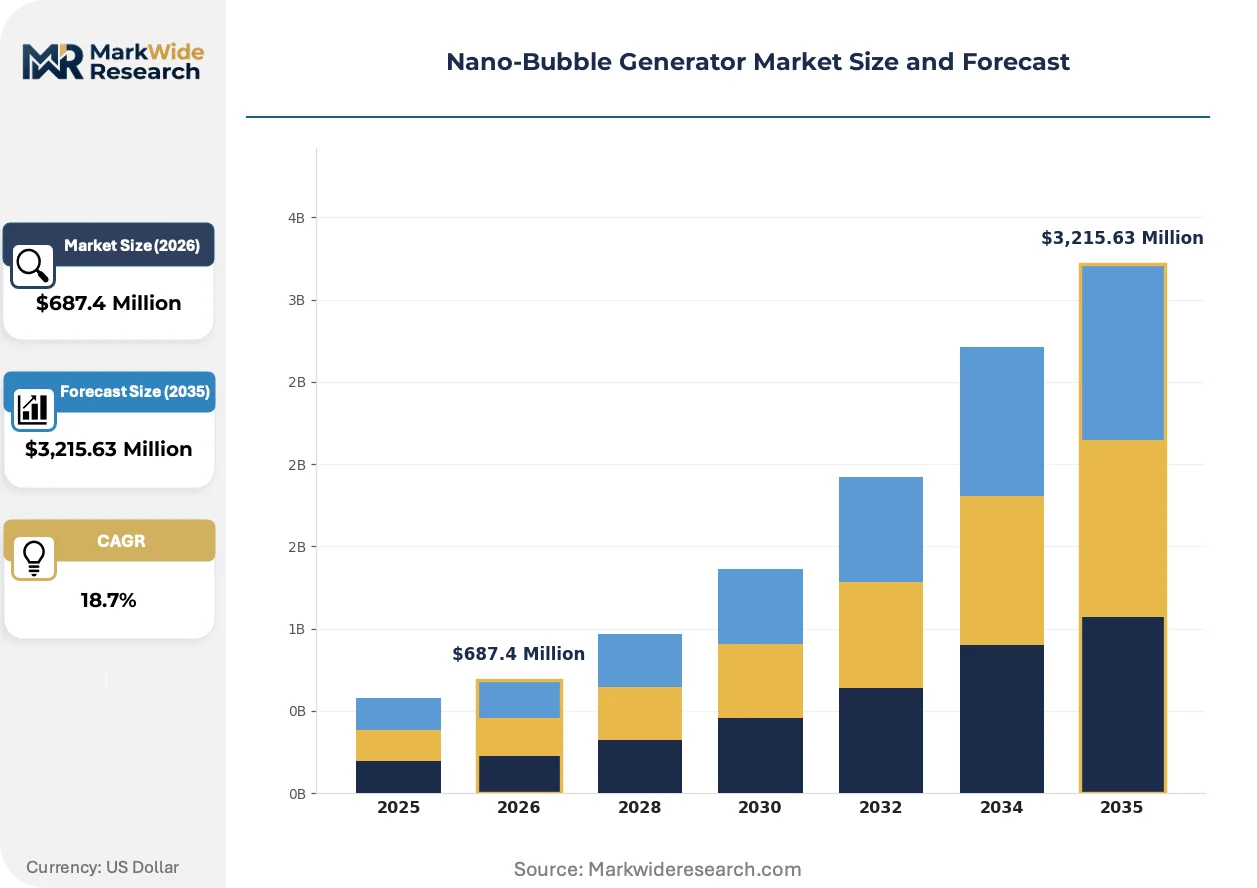
Market Dynamics
Japan's METI is tightening industrial water reuse standards, compelling municipal and industrial facilities across Asia-Pacific to retrofit aeration infrastructure with nano-bubble systems that deliver oxygen transfer efficiencies an order of magnitude above conventional methods.
Growth Catalysts
- Regulatory stringency in Germany:Municipal wastewater treatment plants face escalating biological oxygen demand thresholds under EU Water Framework Directive implementations, forcing generator adoption.
- Coastal aquaculture zones:Vietnam and Indonesia deploy dissolved oxygen management systems where nano-bubble generators determine shrimp and finfish yield outcomes.
- Electrochemical refinement:Medical and laboratory settings demand tight bubble size distribution tolerances that fluidic generators cannot achieve.
Market Restraints
- Precision component sourcing:High-consistency generator output requires specialized fluid engineering components concentrated among Japanese suppliers.
- Capital intensity threshold:Ultrasonic technology segments sustain higher margins but demand substantial upfront investment that constrains municipal procurement cycles.
- Material compatibility constraints:EU REACH framework and Japan's METI collectively steer wetted component standards, narrowing supplier qualification pathways.
Strategic Opportunities
- China's provincial mandates:Ministry of Ecology and Environment has embedded nano-bubble aeration into water quality improvement directives, accelerating domestic certification requirements.
- Smart water infrastructure convergence:Interoperability standards between generator control systems and digital water platforms create integration service revenue streams.
- US retrofit cycles:EPA effluent limitation guidelines tighten biological oxygen demand thresholds, expanding replacement demand at aging municipal plants.
Industry Challenges
- Skill scarcity in fluid engineering:Generator maintenance and optimization require specialized technicians that outpace vocational training pipeline output.
- Legacy system integration:Municipal water treatment facilities operate decades-old aeration infrastructure that complicates nano-bubble generator retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano-Bubble Generator Market |
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $3,215.63 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Generators, Fluidic Generators, Mechanical Generators, Electrochemical Generators Technology: Ultrasonic Technology, Microfluidic Technology, Venturi Technology, Diffusion Technology Application: Aquaculture, Wastewater Treatment, Agriculture, Industrial Cleaning End User: Fisheries, Water Treatment Plants, Farms, Manufacturing Facilities |
| Companies Covered | TAISEI KOGYO, Shandong Sundon Technology Co., Ltd., Moleaer Inc., Agrona B.V., Pacific Water Technology, Acniti LLC, Shibata, Fine Bubble Technologies, Shanghai Mutao Environmental Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano-Bubble Generator Market Evolving Landscape
Equipment manufacturers are hardening supply positions through precision engineering investments while end-users pivot toward outcome-based performance contracts that transfer operational risk to technology providers.
Electrochemical nano-bubble generation is electrifying medical sterilization and laboratory applications through sub-200-nanometer bubble size precision that hydrodynamic methods cannot replicate. Pharmaceutical cleanrooms and diagnostic laboratories in Japan and Germany are adopting these systems at accelerating pace. The technology is electrifying premium market tiers while compressing fluidic generator margins in standardized applications.
China's Ministry of Ecology and Environment has embedded nano-bubble aeration into provincial water quality improvement mandates with binding compliance timelines. Industrial facilities in coastal provinces face escalating enforcement actions that accelerate capital expenditure approvals. Chemical processing and textile dyeing operations are responding with bundled technology-service procurement models that defray upfront capital burdens.
Buyers are consolidating vendor relationships around full-service performance contracts that unbundle equipment supply from dissolved oxygen guarantee obligations. Municipal water authorities in Germany and Japan increasingly demand operational accountability from generator suppliers rather than capital purchase structures. This shift concentrates procurement influence among integrated technology-service providers with localized technical support capabilities.
Nano-Bubble Generator Market Segmentation
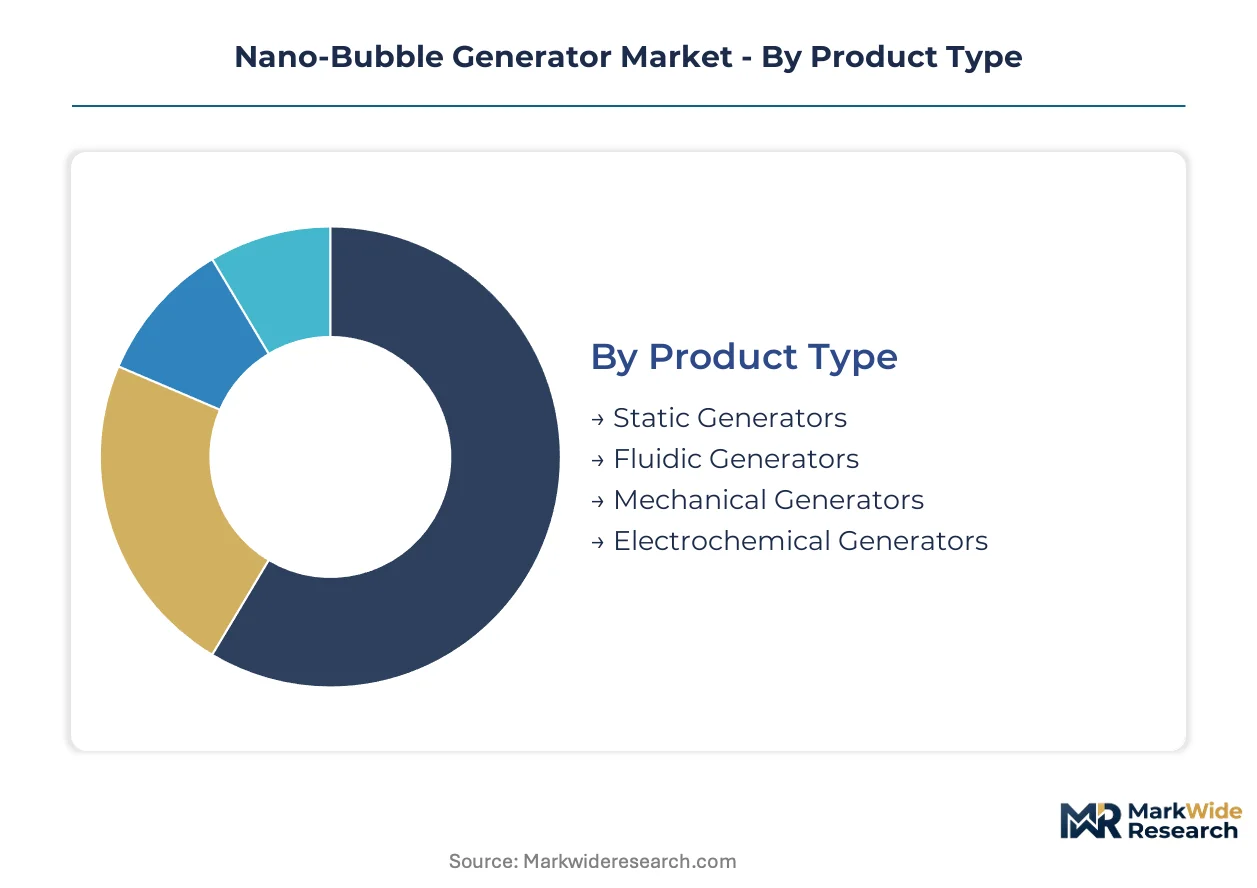
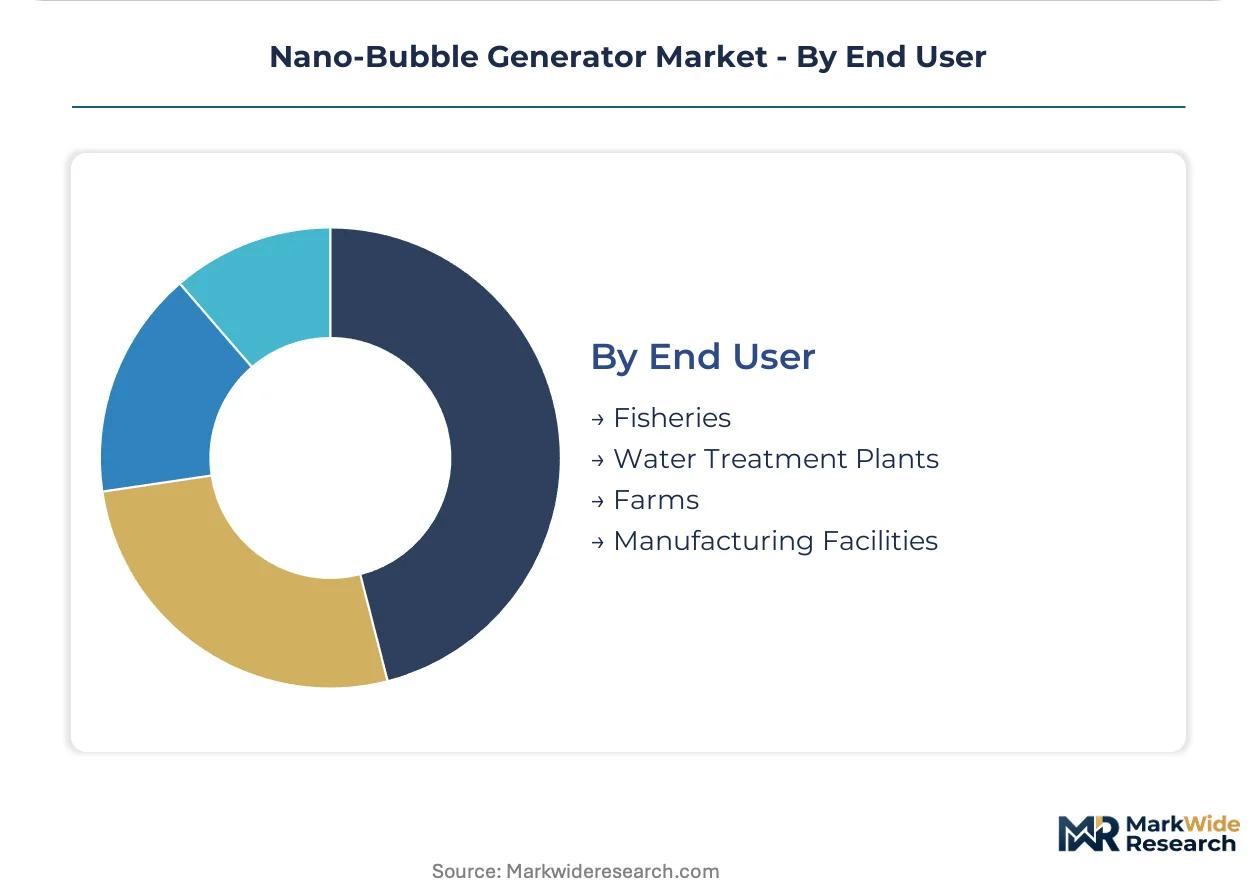
Nano-bubble generator procurement patterns diverge sharply across technical specifications and operational environments. Equipment replacement cycles and upgrade pathways vary by installation scale, regulatory pressure, and dissolved oxygen performance guarantees demanded by end-users.
Product Type:
Generator replacement cycles accelerate where fluid engineering precision directly determines operational uptime and energy efficiency outcomes.
- Fluidic Generators:Hydrodynamic cavitation through precision-engineered orifices produces sub-200-nanometer bubbles with minimal energy input. Municipal wastewater treatment plants in Germany favor these systems for retrofit compatibility with legacy aeration infrastructure.
- Electrochemical Generators:Controlled electrolysis achieves tight bubble size distribution tolerances below 100 nanometers through electrode material selection and current density modulation. Pharmaceutical cleanrooms in Japan and diagnostic laboratories in Germany deploy these for sterilization applications where hydrodynamic methods fail.
- Static Generators:Pressure dissolution chambers without moving parts serve low-throughput aquaculture operations across Vietnam and Indonesia where maintenance simplicity outweighs efficiency optimization.
- Mechanical Generators:Rotating impeller systems generate cavitation through shear forces, occupying mid-tier positioning between fluidic precision and static simplicity.
Fluidic generators sit at the top of the volume ranking, with electrochemical variants climbing the fastest.
Technology:
Capital intensity thresholds and energy efficiency benchmarks reshape technology selection across municipal procurement cycles and industrial deployment scales.
- Venturi Technology:Constricted flow passages create pressure differentials that nucleate nano-bubbles through controlled cavitation. Wastewater treatment installations across Germany and Japan specify venturi systems where throughput volume governs equipment selection and biological oxygen demand compliance timelines tighten.
- Ultrasonic Technology:High-frequency acoustic transducers induce cavitation through pressure wave propagation, achieving narrow bubble size distributions. Medical sterilization applications in Japan and laboratory settings in Germany absorb premium pricing for this precision despite substantial upfront capital requirements.
- Microfluidic Technology:Chip-based channel geometries manipulate gas-liquid interfaces at microscale, serving point-of-use diagnostic and research applications.
- Diffusion Technology:Membrane-based gas transfer through porous ceramics or polymers occupies cost-sensitive agricultural irrigation segments.
Venturi technology dominates installed base by volume, while ultrasonic systems gain share fastest in premium medical and laboratory tiers.
Application:
Dissolved oxygen management requirements and regulatory enforcement intensity concentrate demand across coastal zones and industrial corridors.
- Wastewater Treatment:Biological oxygen demand threshold compliance drives generator adoption at municipal plants facing EPA effluent limitation guidelines in the US and EU Water Framework Directive implementations in Germany. Retrofit cycles accelerate where aging aeration infrastructure fails to meet tightened discharge standards.
- Aquaculture:Shrimp and finfish yield outcomes depend on precise dissolved oxygen control across Vietnam's Mekong Delta and Indonesia's coastal ponds. Nano-bubble systems displace conventional paddlewheel aerators where stocking densities intensify and mortality events threaten harvest viability.
- Agriculture:Irrigation water oxygenation and pesticide reduction applications expand across controlled-environment horticulture operations.
- Industrial Cleaning:Surface preparation and parts washing applications utilize nano-bubble chemistry for reduced detergent loading.
Wastewater treatment sits at the top of the volume ranking, with aquaculture climbing the fastest.
End User:
Procurement authority structures and performance accountability frameworks diverge between public infrastructure operators and private production facilities.
- Water Treatment Plants:Municipal authorities in Germany and Japan increasingly demand outcome-based performance contracts that transfer dissolved oxygen guarantee obligations to technology providers. Capital purchase structures give way to operational expenditure models with localized technical support requirements.
- Fisheries:Private aquaculture operators across Vietnam and Indonesia prioritize equipment reliability and field service responsiveness over technical sophistication, consolidating vendor relationships around integrated supply-maintenance packages.
- Farms:Agricultural adopters span greenhouse operators and open-field irrigators with variable technical sophistication and capital access.
- Manufacturing Facilities:Industrial laundries, food processors, and electronics assemblers deploy cleaning and process water applications with site-specific water quality constraints.
Water treatment plants sit at the top of the volume ranking, with fisheries climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward jurisdictions with favorable cost-of-compliance structures for precision fluid engineering. Japan and Germany maintain premium-tier positioning through stringent METI and REACH standards, while Chinese and Vietnamese production clusters capture volume through streamlined certification pathways.
Germany
Municipal wastewater treatment plants across the Ruhr and Rhine industrial corridors drive retrofit demand as EU Water Framework Directive implementations tighten biological oxygen demand thresholds. The country's national environmental regulator enforces effluent standards that conventional aeration infrastructure cannot meet. Equipment procurement concentrates in North Rhine-Westphalia and Bavaria, where aging plants face binding compliance timelines.
Japan
Precision manufacturing ecosystems in Kansai and Chubu supply high-consistency generator components to domestic and export markets. METI's tightened industrial water reuse standards compel pharmaceutical cleanrooms and electronics assemblers to install advanced electrochemical systems. Tokyo Bay industrial clusters and Osaka pharmaceutical corridors anchor domestic absorption for premium-tier equipment.
China
Provincial water quality mandates from the Ministry of Ecology and Environment accelerate generator adoption across chemical processing and textile dyeing operations. Yangtze River Delta and Pearl River Delta industrial zones face escalating enforcement actions that compress capital expenditure approval cycles. Shandong Peninsula manufacturing bases supply standardized fluidic generators to domestic aquaculture and agricultural irrigation segments.
Vietnam
Coastal aquaculture zones in the Mekong Delta deploy dissolved oxygen management systems where nano-bubble generators determine shrimp yield outcomes. The country's national environmental authority has begun embedding aeration efficiency standards into coastal development licenses. Private operators across Bến Tre and Cà Mau provinces consolidate vendor relationships around integrated supply-maintenance packages.
United States
EPA effluent limitation guidelines expand retrofit cycles at aging municipal plants across the Great Lakes and Gulf Coast regions. Biological oxygen demand thresholds tighten discharge standards that legacy aeration infrastructure cannot satisfy. California and Texas water authorities increasingly demand outcome-based performance contracts that transfer operational accountability to technology providers.
Nano-Bubble Generator Market Competitive Landscape
Japanese producers anchor the premium tier through precision fluid engineering capabilities; Chinese fabricators hold volume positioning through manufacturing scale advantages. The vendor base stratifies across three functional tiers: integrated technology-service providers, specialized component suppliers, and regional system integrators. Dominant competitive moves include strategic partnerships for smart water infrastructure integration and geographic expansion through localized technical support networks.
Within the precision-engineering tier, TAISEI KOGYO exemplifies Japanese fluid engineering heritage through decades of cavitation system development. Shandong Sundon Technology Co., Ltd. occupies a scale-driven position across fluidic and electrochemical product lines. Moleaer Inc. represents North American specialization in aquaculture and agriculture deployment models. These three anchors illustrate how competitive positioning fragments across geographic capability clusters rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| TAISEI KOGYO |
| Shandong Sundon Technology Co., Ltd. |
| Moleaer Inc. |
| Agrona B.V. |
| Pacific Water Technology |
| Acniti LLC |
| Shibata |
| Fine Bubble Technologies |
| Shanghai Mutao Environmental Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Fluid engineering technician scarcity in Japan's Kansai industrial corridor widens pricing-tier spreads between premium electrochemical generators and standardized fluidic units, as labor-cost differentials compound precision-component premiums.
Pricing Analysis
Distributor margin layers absorb 15-25 points between Japanese OEMs and Vietnamese aquaculture end-users, compressing netbacks for mid-tier mechanical generators. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified electrochemical systems from REACH-compliant fluidic units and unbranded static generators. Cost compression in the economy tier is intensifying because Shandong fabricators are flooding Southeast Asian aquaculture markets with undifferentiated venturi systems. Municipal water authorities in Germany exhibit lowest price sensitivity due to outcome-based contract structures, while Indonesian shrimp operators demand bare-bone equipment pricing.
Supply Chain Analysis
Titanium electrode supply rests on Japanese specialty metal producers serving electrochemical generator OEMs. Precision ceramic orifices draw from German and Japanese machining houses, while polymer housings feed from Chinese petrochemical complexes. Single-source vulnerability concentrates in high-purity electrode coatings sourced from Chubu-based suppliers. Distribution runs through authorized technical service networks in developed markets and direct OEM relationships in emerging aquaculture zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through electrochemical tier migration as medical sterilization applications absorb premium pricing.
For Market Incumbents: Deepen backward integration into precision ceramic orifice production to defend against Shandong scale players. Secure METI certification maintenance as EU REACH alignment tightens material qualification pathways. Anchor service revenue through dissolved oxygen guarantee contracts that lock out component-only competitors. For New Entrants and Emerging Players: Electrochemical miniaturization for point-of-use diagnostic applications offers the most penetrable white-space. Target Vietnam's Mekong Delta aquaculture cooperatives with venturi-generator lease models that eliminate upfront capital barriers. Lead with field technician training programs to differentiate from Japanese OEMs with limited local presence. For Investors and Strategic Acquirers: Water technology conglomerates are the most active acquirer in this space, seeking smart infrastructure integration capabilities. Five-to-ten year viability hinges on electrochemical patent estates and localized service network density. Watch for EPA effluent guideline enforcement acceleration as the signal triggering replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive supply of ceramic orifices insulates margin from Japanese supplier concentration. |
| Smart Water Infrastructure Partnership | Generator control system APIs unlock recurring software revenue from German municipal clients. |
| Outcome-Based Performance Contracting | Dissolved oxygen guarantees shift procurement from CapEx to OpEx, favoring integrated providers. |
| Electrochemical Product Line Expansion | Sub-100-nanometer precision opens pharmaceutical cleanroom segments in Japan and Germany. |
| Localized Technical Service Network | Field engineering presence in Vietnam and Indonesia secures aquaculture maintenance contracts. |
Research Methodology
Direct dialogue with municipal water plant engineers, aquaculture operations managers, pharmaceutical facility directors, and precision fluid engineering specialists grounded qualitative assessments. Secondary validation drew from EPA effluent limitation guidelines, METI industrial water reuse standards, EU Water Framework Directive implementations, and customs trade records for nano-bubble generator equipment. Bottom-up installation counts across Germany, Japan, China, Vietnam, and Indonesia triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Segment-level value outputs across the projection horizon reflect modeled adoption curves by product type, technology, application, and end-user category. CAGRs derived from regression analysis against regulatory enforcement timelines and dissolved oxygen performance benchmarks. Forecast inputs incorporated METI certification completion rates, EPA biological oxygen demand threshold trajectories, and aquaculture stocking density intensification patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrochemical patent expiries and Chinese provincial mandate enforcement variability. Assumptions reflect documented regulatory trajectories and equipment replacement cycle patterns. A small set of named triggers—EPA guideline acceleration, METI standard expansion, Vietnamese coastal license embedding—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Industrial Explosives Market