
 N-Ethyl-2-Pyrrolidone Market | 2026-2036
N-Ethyl-2-Pyrrolidone Market Size, Share, and Industry Trends Forecast 2026-2036
N-Ethyl-2-Pyrrolidone Market Foresight
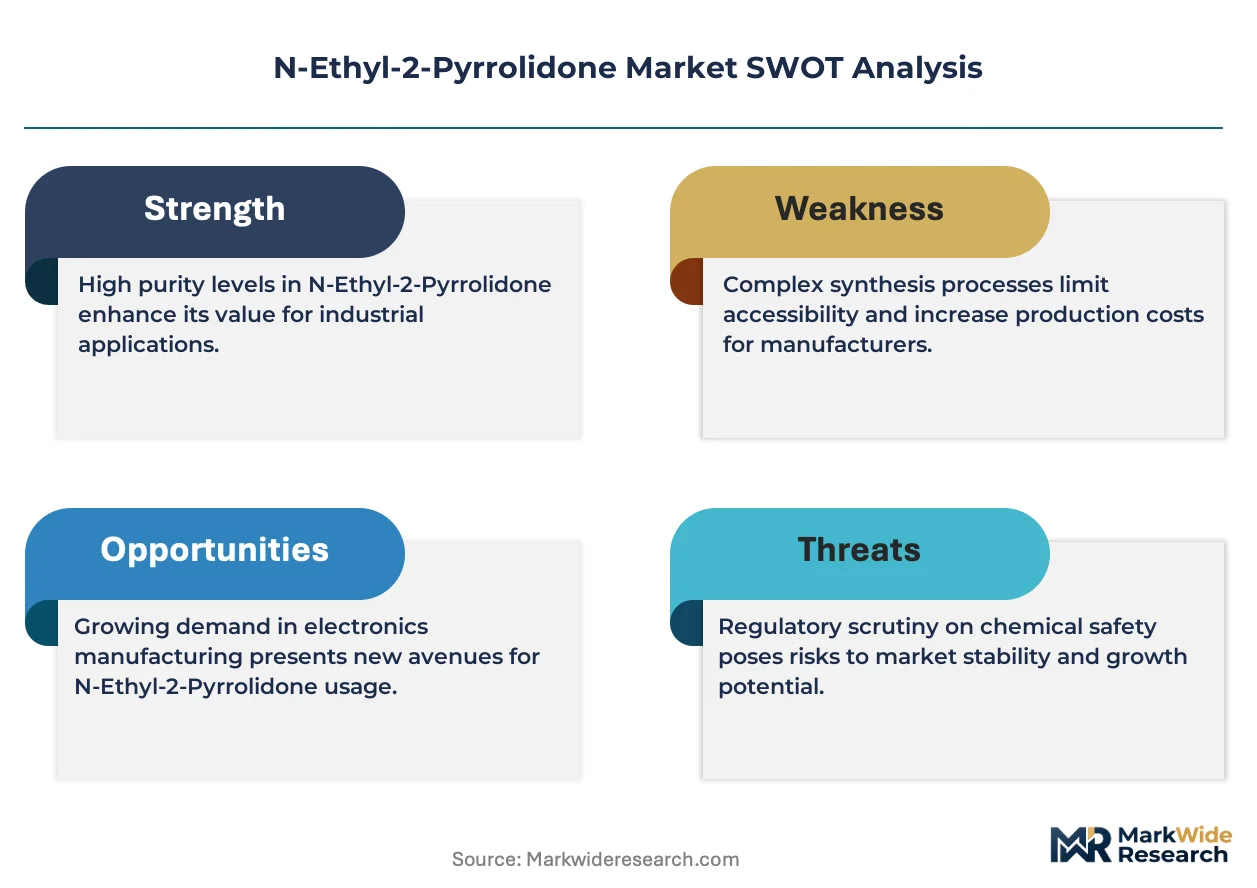
Dimethylformamide is repositioning N-ethyl-2-pyrrolidone in several coating applications where lower toxicity profiles command procurement preference. BASF SE leverages integrated amine-to-pyrrolidone production at its Ludwigshafen complex to sustain feedstock cost discipline. Eastman Chemical Company anchors North American supply through Kingsport manufacturing assets. Mitsubishi Chemical Corporation specializes in electronics-grade purification for photoresist stripping applications.
N-ethyl-2-pyrrolidone is a five-membered lactam with an ethyl substituent on the nitrogen, exhibiting a dipole moment of approximately 4.0 Debye and a boiling point of 97°C at 20 mbar, manufactured via reductive amination of gamma-butyrolactone with ethylamine. It functions primarily as an aprotic polar solvent for extraction, reaction media, and surface treatment in precision manufacturing. Solvent-grade product dominates volume but electronics-grade additive commands the widest margin pool due to sub-ppm metal ion specifications. Cleaning agent applications in semiconductor fabs represent the fastest-expanding demand segment. Paints formulation remains mature with stable offtake from automotive OEM coating lines.
EPA oversight under TSCA governs domestic manufacture and import notification for new chemical exposure scenarios in the United States. ECHA REACH annex XVII restrictions on reproductive toxicants constrain formulation flexibility for European coatings producers. China's MEE enforcement of volatile organic compound emission standards is redirecting solvent selection in Jiangsu and Shandong manufacturing zones. Stakeholders must monitor evolving semiconductor material purity protocols and regional chemical registration deadlines to secure uninterrupted market access.
Market Dynamics
Semiconductor material purity protocols are compressing specification windows for electronics-grade N-ethyl-2-pyrrolidone, forcing solvent suppliers to reconfigure purification trains and recertify against sub-ppm metal ion thresholds.
Growth Catalysts
- Photoresist stripping demand:Advanced node fabrication at 3nm and below requires ultra-high purity solvents for post-etch cleaning, expanding procurement volumes from foundries in Taiwan and South Korea.
- REACH Annex XVII compliance:Reproductive toxicant restrictions on competing N-methylpyrrolidone are redirecting European coatings formulators toward N-ethyl-2-pyrrolidone as a technically viable substitute.
- Jiangsu agrochemical clustering:Formulation plants in China's Jiangsu province are consolidating solvent procurement for pesticide synthesis, creating concentrated demand pull for reaction-grade material.
Market Restraints
- Gamma-butyrolactone feedstock volatility:Crude oil-linked pricing for butanediol precursors transmits cost instability through reductive amination economics.
- Ludwigshafen supply concentration:Integrated amine-to-pyrrolidone production at a single European complex creates geographic vulnerability for regional buyers.
- Dimethylformamide substitution:Lower-toxicity DMF formulations are capturing coating applications where solvent performance specifications permit technical interchangeability.
Strategic Opportunities
- India specialty chemical manufacturing:PLI scheme incentives for agrochemical intermediates are attracting greenfield solvent purification investments to Gujarat and Maharashtra.
- Battery electrode coating:Lithium-ion cell manufacturing for electric vehicles is adopting N-ethyl-2-pyrrolidone as a slurry dispersant for cathode active materials.
- MEE VOC enforcement:China's Ministry of Ecology and Environment emission standards are disqualifying traditional aromatic solvents in Shandong province, opening specification switches.
Industry Challenges
- Semiconductor-grade certification timelines:Sub-ppm metal ion qualification protocols require 18-24 month validation cycles with foundry customers, delaying revenue recognition for new purification capacity.
- Legacy formulation lock-in:Automotive OEM coating lines maintain approved solvent lists that resist specification changes without extensive requalification testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Ethyl-2-Pyrrolidone Market |
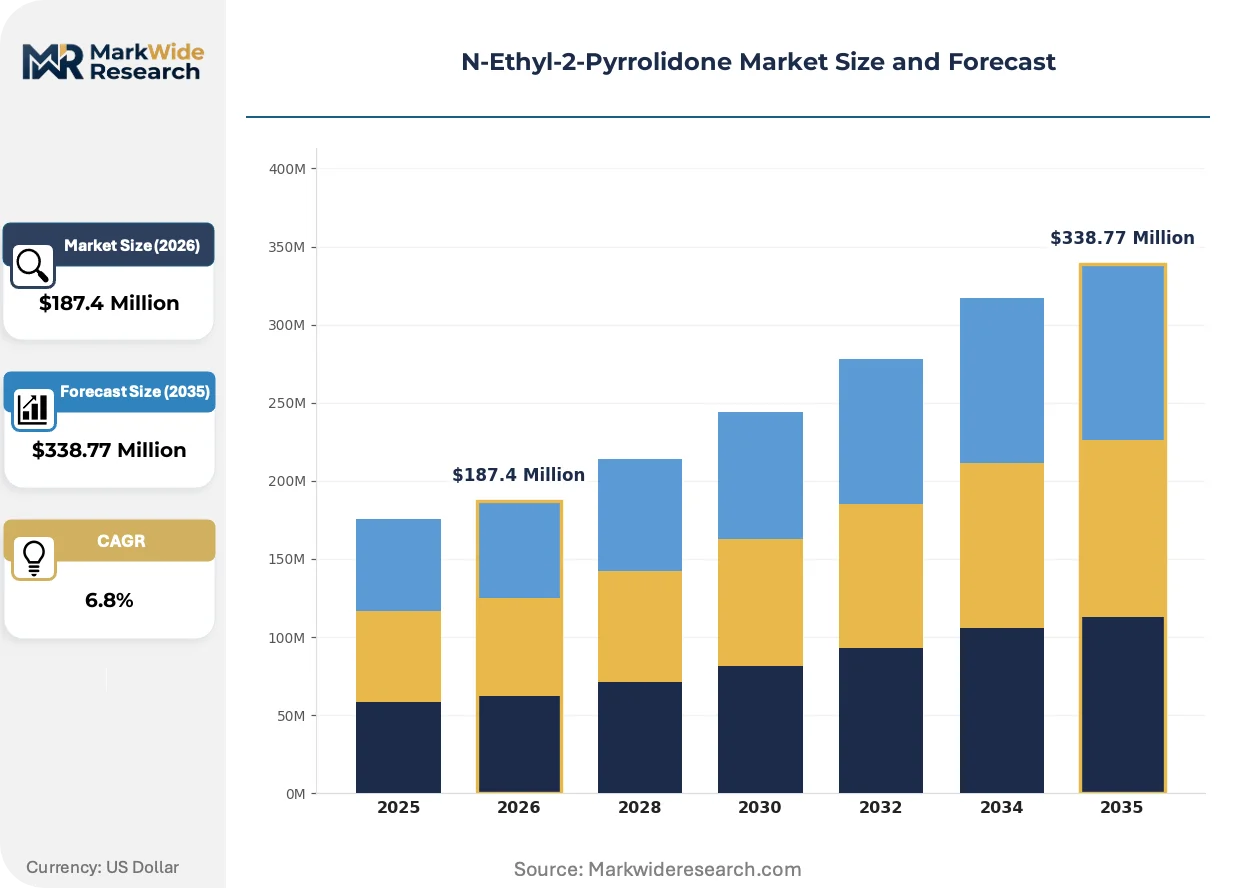
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Additive, Coating, Surfactant End Use Industry: Pharmaceutical, Agriculture, Electronics, Automotive Form: Liquid, Powder, Granule, Concentrate Application: Paints, Adhesives, Cleaning Agents, Chemical Synthesis |
| Companies Covered | BASF SE, Eastman Chemical Company, Solvay SA, Ashland Inc., Mitsubishi Chemical Corporation, LyondellBasell Industries N.V., Huntsman Corporation, Nippon Shokubai Co., Ltd., Puyang Guangming Chemicals Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Ethyl-2-Pyrrolidone Market Shifts & Advancements
Process intensification in solvent purification and regulatory displacement of competing chemistries are restructuring competitive requirements across electronics and industrial coatings segments.
Membrane filtration technology is integrating into electronics-grade production trains as a replacement for energy-intensive distillation sequences. Taiwan-based foundries are specifying membrane-polished material for 2nm pilot lines. This integration is compressing capital requirements for new market entrants and eroding the scale advantages of incumbent integrated producers.
ECHA REACH substance evaluation is expanding reproductive toxicity data requirements for pyrrolidone derivatives used in consumer-facing coatings. Industrial formulators in Germany and France are preemptively reformulating to maintain downstream market access. The professional coatings segment is absorbing compliance costs through specification premiums on certified low-toxicity grades.
Direct procurement contracts between semiconductor fabs and solvent refiners are displacing distributor-mediated supply in East Asia. Long-term offtake agreements with fixed purity escalation clauses are replacing spot market purchases for high-volume consumers. This pattern is most pronounced in South Korea's Pyeongtaek cluster where Samsung and SK Hynix operations anchor demand.
N-Ethyl-2-Pyrrolidone Market Segmentation
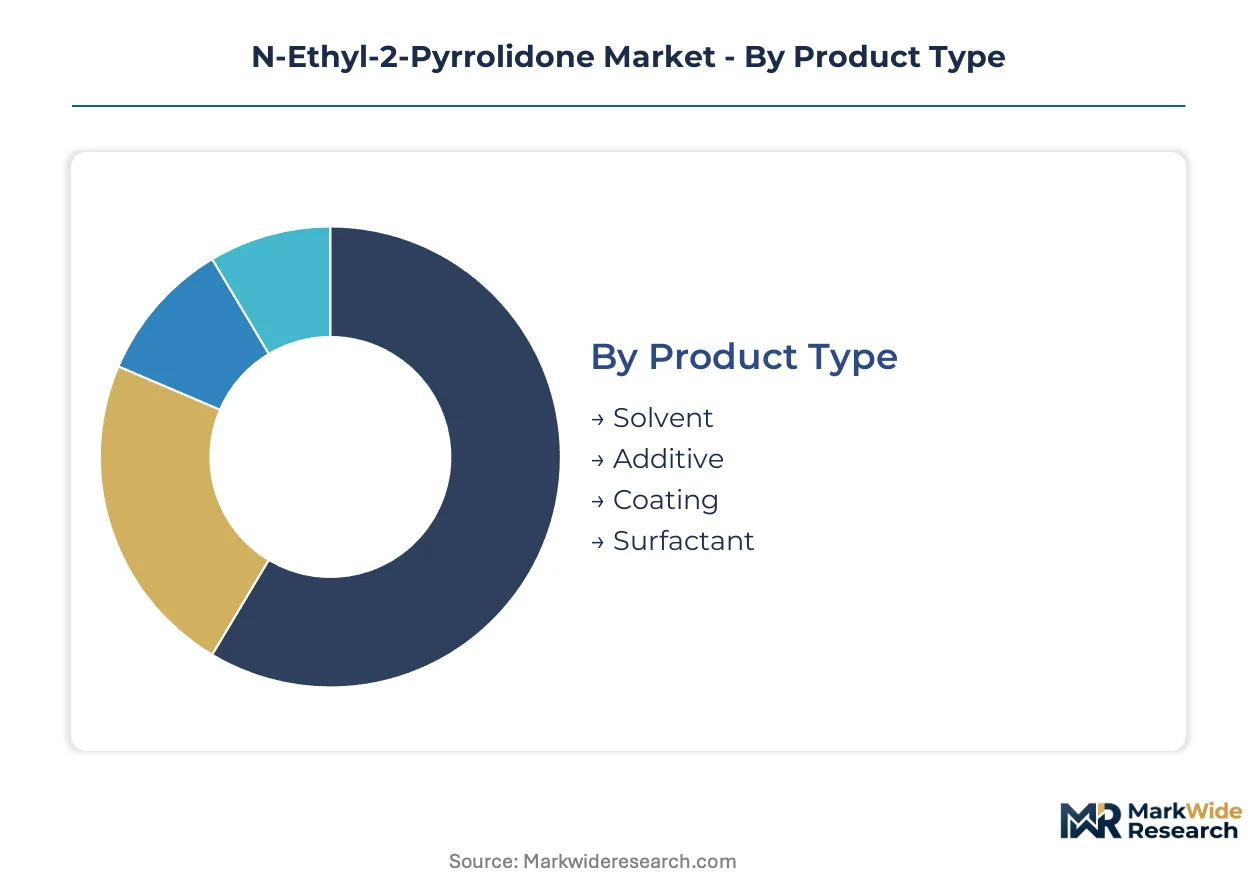
N-Ethyl-2-pyrrolidone market segmentation reveals divergent capital requirements across product grades and end-use specifications. Electronics-grade purification demands multi-million-dollar distillation and membrane infrastructure, while industrial solvent grades operate on substantially leaner asset bases.
Product Type:
Solvent-grade production absorbs the heaviest capital burden through multi-stage purification trains, while additive and coating formulations require less intensive processing infrastructure.
- Solvent:Aprotic polar solvent manufactured via reductive amination of gamma-butyrolactone with ethylamine, serving extraction and reaction media applications. Demand concentrates in China's Jiangsu province where agrochemical formulators cluster for pesticide synthesis operations.
- Additive:Electronics-grade material commanding specification premiums through sub-ppm metal ion thresholds. Procurement volumes are expanding most quickly from Taiwan and South Korea foundries advancing toward 3nm and below fabrication nodes.
- Coating:Surface treatment formulations for automotive OEM lines with stable offtake patterns and mature qualification protocols.
- Surfactant:Dispersant applications in specialty chemical manufacturing with moderate purity requirements.
Solvent absorbs the bulk of installed capacity; additive is expanding most quickly.
End Use Industry:
Electronics and pharmaceutical segments drive margin differentiation through purity certification requirements, while agriculture and automotive sectors compete on volume scale and feedstock efficiency.
- Electronics:Photoresist stripping and post-etch cleaning applications at semiconductor fabs. Taiwan-based foundries are specifying membrane-polished material for 2nm pilot lines, compressing capital requirements for new market entrants.
- Pharmaceutical:Extraction solvent and reaction media for active pharmaceutical ingredient synthesis. EMA and FDA oversight governs impurity profiles and residual solvent limits in drug manufacturing.
- Agriculture:Pesticide formulation and agrochemical intermediate production. Jiangsu province clustering creates concentrated demand pull for reaction-grade material.
- Automotive:OEM coating lines with approved solvent lists that resist specification changes without extensive requalification testing.
Electronics commands the steepest specification premiums; agriculture moves the largest absolute volumes.
Form:
Liquid form dominates commercial distribution through established bulk chemical logistics networks, while solid forms incur additional processing costs for precipitation and drying operations.
- Liquid:Standard commercial presentation for bulk solvent and electronics-grade shipments. Direct procurement contracts between semiconductor fabs and solvent refiners are displacing distributor-mediated supply in East Asia.
- Powder:Solid-state formulations for specialized coating applications requiring precise dosing control.
- Granule:Intermediate physical form for controlled-release agricultural applications.
- Concentrate:High-potency preparations for dilution at point of use in industrial cleaning operations.
Liquid form carries the majority of commercial transactions; concentrate formulations are gaining share fastest in semiconductor maintenance applications.
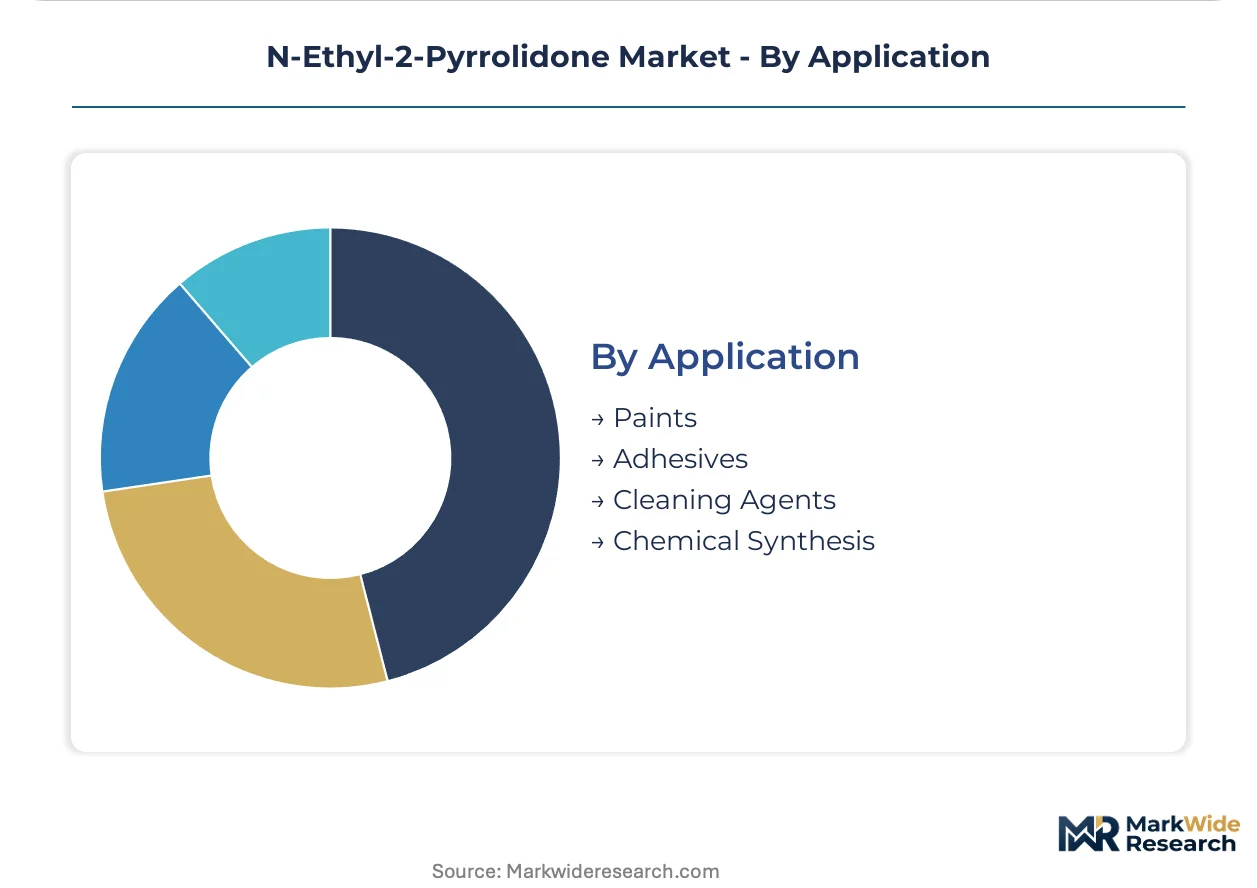
Application:
Cleaning agent applications command the widest margin spreads through semiconductor-grade purity protocols, while paints and adhesives operate in more price-sensitive formulation environments.
- Cleaning Agents:Post-etch photoresist stripping and wafer surface preparation at foundry operations. Sub-ppm metal ion qualification protocols require 18-24 month validation cycles with foundry customers.
- Chemical Synthesis:Reaction media for pharmaceutical and agrochemical intermediate production. REACH Annex XVII reproductive toxicant restrictions on competing N-methylpyrrolidone are redirecting European formulators toward N-ethyl-2-pyrrolidone.
- Paints:Automotive OEM coating lines with stable offtake and established formulation lock-in patterns.
- Adhesives:Industrial bonding applications where lower-toxicity DMF formulations are capturing share where performance specifications permit technical interchangeability.
Cleaning agents capture the highest realized prices; chemical synthesis applications are climbing the fastest on regulatory displacement effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in Taiwan and South Korea drive the steepest specification premiums for electronics-grade material, while agrochemical formulation in China's Jiangsu province anchors absolute volume demand.
United States
Photoresist stripping operations at Arizona and Texas foundries pull ultra-high purity volumes for advanced node production. EPA oversight under TSCA governs import notification thresholds for new chemical exposure scenarios. Greater Phoenix anchors Intel and TSMC expansion projects with solvent qualification protocols extending 18-24 months.
China
Jiangsu province formulators consolidate procurement for pesticide synthesis, creating concentrated demand for reaction-grade material. MEE enforcement of VOC emission standards redirects solvent selection in Shandong manufacturing zones. Yangtze River Delta electronics fabs specify membrane-polished grades for sub-7nm pilot lines.
Germany
Automotive OEM coating lines in Bavaria and Baden-Württemberg maintain approved solvent lists with mature qualification protocols. ECHA REACH Annex XVII restrictions on reproductive toxicants constrain formulation flexibility for coatings producers. BASF's Ludwigshafen complex sustains integrated amine-to-pyrrolidone production for regional supply.
South Korea
Samsung and SK Hynix operations in Pyeongtaek anchor direct procurement contracts with fixed purity escalation clauses. MFDS pharmaceutical oversight governs residual solvent limits in active ingredient manufacturing. Seoul Capital Area foundries specify sub-ppm metal ion thresholds for 3nm and below fabrication.
Japan
Mitsubishi Chemical Corporation specializes in electronics-grade purification for photoresist stripping applications serving domestic fabs. METI industrial standards coordinate with semiconductor material purity protocols. Kyushu Island fabrication clusters demand membrane-polished material for pilot line qualification.
N-Ethyl-2-Pyrrolidone Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers reconfigure purification trains to meet sub-ppm metal ion specifications. The vendor base concentrates around integrated petrochemical majors and specialty chemical refiners with captive amine feedstock positions. Three archetypes define competitive positioning: integrated petrochemical conglomerates with backward control over butanediol precursors, electronics-focused refiners with membrane filtration capabilities, and regional formulators serving agrochemical clusters. Geographic expansion into India and strategic partnerships with semiconductor fabs represent the dominant competitive moves.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify archetypes of feedstock-integrated production. BASF anchors European supply through its Ludwigshafen manufacturing position. Eastman occupies a North American anchor role through Kingsport assets. Mitsubishi Chemical Corporation represents the electronics-specialist archetype with purification capabilities aligned to foundry specifications.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Solvay SA |
| Ashland Inc. |
| Mitsubishi Chemical Corporation |
| LyondellBasell Industries N.V. |
| Huntsman Corporation |
| Nippon Shokubai Co., Ltd. |
| Puyang Guangming Chemicals Co., Ltd. |
| Others |
Supply & Pricing Matrix
Butanediol spot pricing transmits volatility through gamma-butyrolactone conversion economics, cascading into three-tier spreads that separate electronics-grade premiums from industrial solvent baselines. Buyers in Taiwan and South Korea absorb specification premiums for sub-ppm metal ion material while Jiangsu agrochemical formulators negotiate volume discounts on reaction-grade shipments.
Pricing Analysis
Volume absorbs margin compression in solvent-grade material while additive formulations capture widening spreads through foundry qualification premiums. Three-tier pricing structure across electronics-grade, industrial-grade, and agricultural-grade levels reflects certification burden and purity threshold differentiation. Cost compression in standard solvent tiers intensifies because dimethylformamide substitution erodes pricing power in coating applications. Automotive OEM coating lines demonstrate lowest price sensitivity due to requalification friction, while agrochemical intermediates buyers in China negotiate most aggressively on spot purchases.
Supply Chain Analysis
Spent solvent recovery and re-refinement flows are emerging in Taiwan and South Korea as fabs pursue circular material protocols for photoresist stripping operations. Manufacturing concentrates in Germany, China, and the United States with BASF's Ludwigshafen complex, Jiangsu province formulators, and Eastman's Kingsport assets anchoring regional supply. Feedstock draws from crude oil-linked butanediol precursors, ethylamine amination reagents, and membrane filtration equipment. Single-source vulnerability concentrates around Ludwigshafen for European buyers. Distribution runs through direct procurement contracts with semiconductor fabs displacing distributor channels in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is displacing thermal distillation in electronics-grade purification, compressing capital barriers for new entrants and restructuring legacy scale advantages. Incumbents must defend against this technology transition while capturing qualification premiums from foundry customers.
For Market Incumbents: Lock in foundry qualification protocols through 18-24 month validation cycles to delay competitor entry into sub-ppm metal ion supply. BASF and Eastman should deepen backward integration into butanediol precursors to buffer gamma-butyrolactone feedstock volatility. Prioritize membrane filtration R&D to match Taiwan-based foundry specifications for 2nm pilot lines. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for agrochemical intermediates in Gujarat and Maharashtra, where greenfield purification investments face lower qualification barriers than semiconductor-grade supply. Target battery electrode coating applications for electric vehicle manufacturers as the most penetrable segment outside established electronics demand. Pursue toll manufacturing arrangements with regional formulators to bypass capital-intensive distillation infrastructure. For Investors and Strategic Acquirers: The window for entry favors electronics-specialist refiners with membrane filtration capabilities and existing foundry relationships over integrated petrochemical conglomerates. Long-term viability centers on purification technology rather than feedstock scale. Watch semiconductor node transition announcements from Samsung and TSMC as inflection indicators for electronics-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Addition | Taiwan foundries specify membrane-polished material for 2nm pilot line qualification. |
| Backward Integration into Butanediol | BASF's Ludwigshafen complex sustains feedstock cost discipline against crude oil volatility. |
| Long-term Supply Agreement with Foundries | Samsung and SK Hynix anchor direct procurement contracts with fixed purity escalation clauses. |
| Greenfield Investment in India | PLI scheme incentives attract solvent purification capacity to Gujarat agrochemical clusters. |
| REACH Compliance Certification | ECHA Annex XVII reproductive toxicant restrictions redirect European coatings formulators toward certified grades. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings, and ECHA REACH registration databases, complemented by interviews with plant managers at solvent purification facilities, procurement leads at Taiwan and South Korea foundries, distribution channel partners in Jiangsu province, and technical R&D directors at integrated petrochemical producers. Bottom-up demand modeling triangulated against top-down capacity assessments across the analysis window.
Cross-reference between historical price series and expert panel input anchored the projection framework. Segmentation dimensions modeled include product grade tier, end-use industry classification, and regional production hub concentration. CAGRs derived from trend extrapolation adjusted for technology substitution effects and regulatory displacement timelines. Forecast inputs incorporated semiconductor node transition schedules and MEE VOC enforcement intensity in Shandong manufacturing zones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gamma-butyrolactone feedstock price spikes or accelerated dimethylformamide substitution in coating applications. Practitioners should monitor foundry qualification protocol changes and REACH substance evaluation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Global Specialty Oils Market