
 Calciner Market | 2026-2036
Calciner Market Size, Share, and Industry Trends Forecast 2026-2036
Calciner Market Insights
High-temperature refractory-grade specifications is collapsing the gap between commodity calciners and premium process designs. FLSmidth leverages its cement technology heritage to dominate large rotary installations across developing markets. Thyssenkrupp Industrial Solutions anchors European demand through specialized indirect-heating systems for chemical applications. Schenck Process differentiates with integrated material-handling and combustion control platforms.
A calciner is a thermal processing vessel engineered to drive endothermic decomposition reactions, typically operating between 800°C and 1,500°C depending on the feedstock and target oxide or carbonate transformation. Rotary calciners remain the workhorse configuration in cement and lime manufacturing due to their throughput flexibility and tolerance of variable feed particle sizes. Fluidized bed calciners are capturing share in alumina and titanium dioxide applications where precise temperature uniformity improves product purity and energy efficiency. Direct heating technology leads installed capacity, though oxygen-enriched combustion is gaining traction as fuel costs and emissions constraints intensify.
The US EPA enforces Maximum Achievable Control Technology standards for hazardous air pollutants from mineral processing kilns, compelling operators to upgrade combustion controls or face operational restrictions. China's MEE implements GB emission limits on particulate matter and nitrogen oxides from non-ferrous metallurgical calciners, reshaping equipment procurement specifications for domestic suppliers and multinational licensors. India's CEA mandates energy consumption benchmarks for designated consumers in cement and aluminum sectors, directly influencing calciner efficiency requirements in capacity expansions. Stakeholders must weigh retrofit economics against greenfield specifications as regulatory baselines diverge across manufacturing jurisdictions.
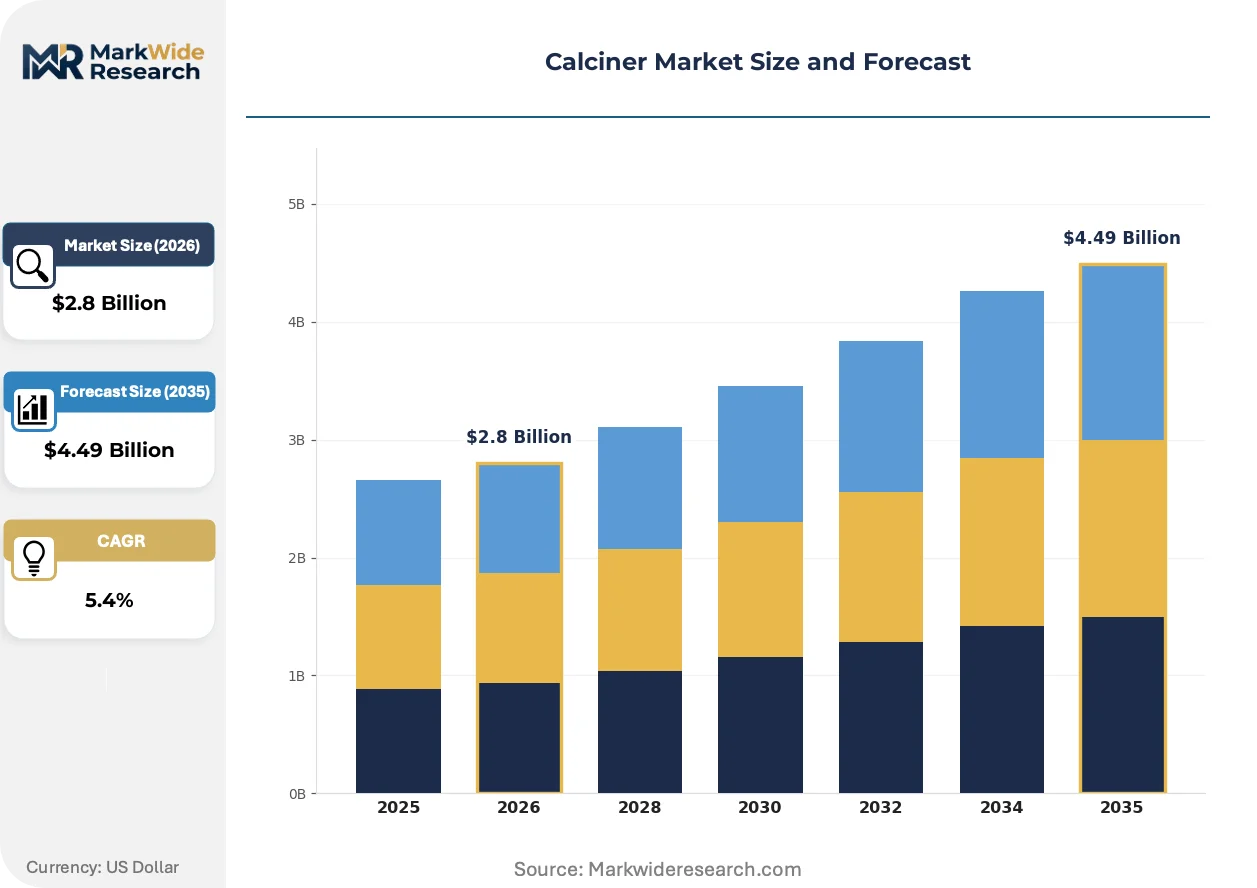
Market Dynamics
Emissions compliance deadlines across major manufacturing jurisdictions are forcing calciner operators to choose between costly retrofits and accelerated replacement cycles, compressing equipment procurement timelines and reshaping supplier relationships.
Growth Catalysts
- India's infrastructure buildout:Massive road, rail, and urban construction projects are accelerating domestic cement and lime calciner orders from state-owned and private producers.
- GB emission limits:China's MEE enforcement of stricter nitrogen oxide and particulate standards is compelling non-ferrous metallurgical operators to upgrade to advanced combustion control systems.
- Oxygen-enriched combustion:This technology is reducing fuel intensity in direct-heating configurations, making retrofits economically viable against rising natural gas and coal prices.
Market Restraints
- Refractory input volatility:High-purity alumina and magnesia prices fluctuate with bauxite mining restrictions in Guinea and Australia, squeezing calciner maintenance budgets.
- Specialized fabricator concentration:European suppliers of indirect-heating systems face extended lead times due to limited certified pressure vessel capacity in Germany and Italy.
- Electrification substitution:Emerging plasma and microwave thermal technologies threaten rotary calciner dominance in specialty chemical applications below 1,200°C.
Strategic Opportunities
- Vietnam's aluminum expansion:New alumina refining capacity along the Central Coast creates demand for fluidized bed calciners with precise temperature uniformity specifications.
- EU Carbon Border Adjustment Mechanism:This framework incentivizes EU-based cement producers to source calcination equipment with embedded emissions tracking and verification capabilities.
- Digital twin convergence:Integration of physics-based modeling with real-time sensor networks enables predictive maintenance contracts that lock in long-term service revenue.
Industry Challenges
- Combustion engineering scarcity:The specialized skill set for optimizing multi-fuel burner configurations in rotary kilns is retiring faster than training programs can replenish.
- Legacy DCS integration:Brownfield sites running 1990s-era distributed control systems face complex retrofitting to accommodate modern emissions monitoring and automated fuel-air ratio adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calciner Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Calciner, Fluidized Bed Calciner, Shaft Calciner, Multiple Hearth Calciner, Flash Calciner Technology: Indirect Heating, Direct Heating, Preheating, Temperature Controlled, Oxygen Enriched Application: Cement Production, Lime Manufacturing, Alumina Processing, Titanium Dioxide Production, Zeolite Manufacturing End User: Construction Material Makers, Metal Refineries, Chemical Producers, Mining Companies, Pigment Manufacturers |
| Companies Covered | Elan Technology, Alloy Engineering Company, FEECO International, Refratechnik, FCT Combustion, Schenck Process, Sackett Waconia, FLSmidth, Thyssenkrupp Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calciner Market Trends and Innovations
Calciner technology trajectories are diverging between commodity-scale efficiency optimization and precision-engineered systems for high-purity industrial minerals, with digitalization threading through both paths.
Fluidized bed calciners with integrated heat recovery loops are displacing traditional rotary configurations in alumina and titanium dioxide production. Specialty chemical producers in Germany and Japan are adopting these systems to achieve tighter temperature uniformity. This displacement is compressing the premium that commodity rotary suppliers can command in non-cement applications.
The EU's Industrial Emissions Directive revision is tightening Best Available Technique reference levels for nitrogen oxides from mineral processing kilns. Cement operators in Poland and Romania must install selective catalytic reduction or face production curtailments. Equipment licensors are responding by bundling DeNOx systems into greenfield proposals to preempt regulatory rejection.
Consolidated procurement by multinational building materials groups is compressing vendor negotiation cycles and unbundling after-sales service from initial equipment contracts. LafargeHolcim and HeidelbergCement are centralizing calciner specifications across their Indian and Southeast Asian subsidiaries. This concentration is most visible in India, where domestic suppliers must now meet global technical standards to remain on approved vendor lists.
Calciner Market Segmentation
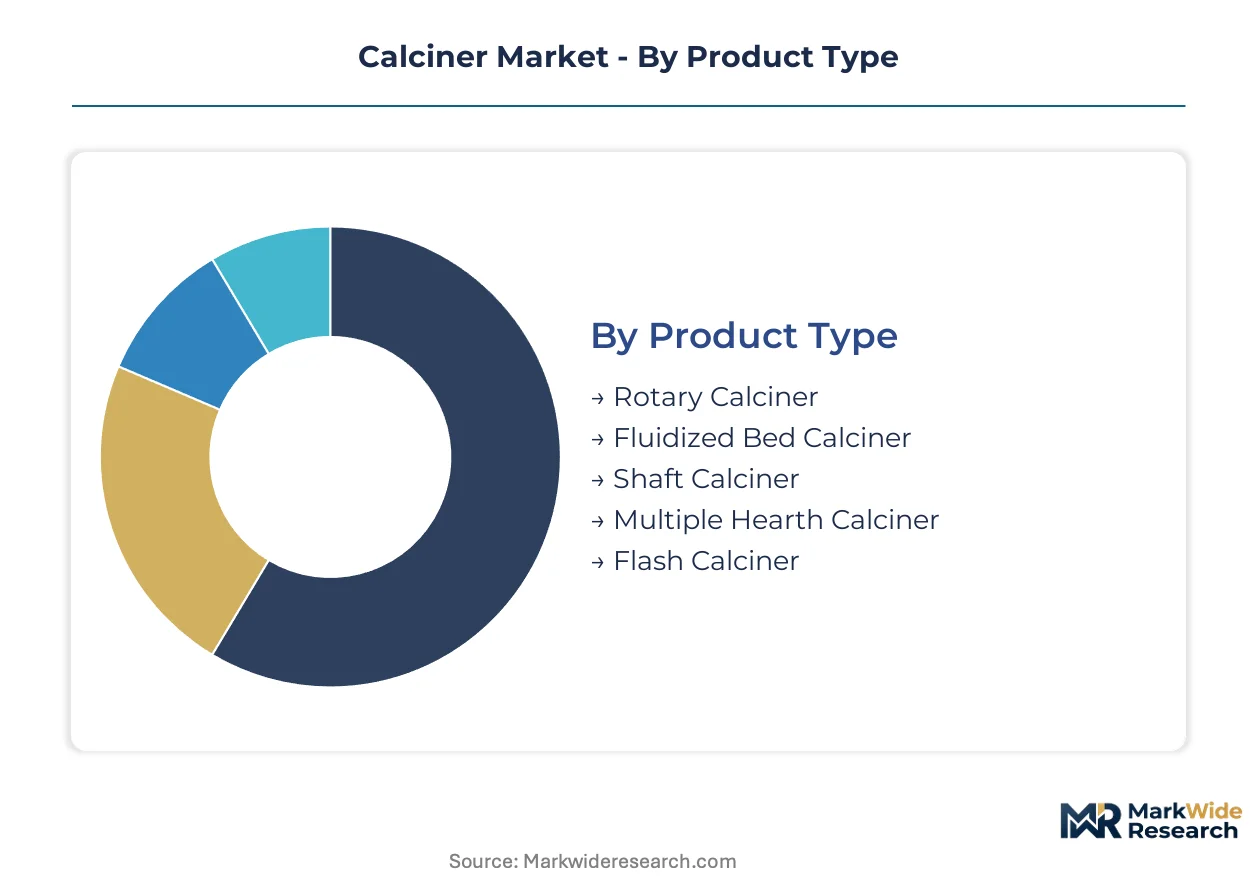
Calciner procurement decisions diverge sharply across product configurations and thermal technologies, with regulatory baselines in India, China, and the US forcing distinct specification tiers. Equipment vendors must align combustion control architectures with jurisdiction-specific emissions enforcement to maintain technical relevance across customer portfolios.
Product Type:
Regulatory differentiation in emissions enforcement shapes equipment selection — rotary units face retrofit mandates under US EPA Maximum Achievable Control Technology standards, while fluidized bed systems gain preference where China's MEE enforces tighter particulate limits on non-ferrous metallurgical operations.
- Rotary Calciner:Cylindrical vessels rotating on inclined axes achieve 800°C to 1,500°C operating ranges with exceptional feed size tolerance. Cement producers in India favor these units for greenfield capacity, though US EPA hazardous air pollutant standards now compel combustion control upgrades that extend procurement timelines.
- Fluidized Bed Calciner:Suspended particle beds deliver precise temperature uniformity through distributed gas injection. Alumina refiners along Vietnam's Central Coast specify these systems to meet purity requirements, while China's GB emission limits on nitrogen oxides accelerate adoption over rotary alternatives in metallurgical applications.
- Shaft Calciner:Vertical counter-current designs optimize thermal efficiency for high-density lime production.
- Multiple Hearth Calciner:Stacked circular hearths enable staged temperature control for complex feedstock decomposition.
- Flash Calciner:Pneumatic conveying systems achieve rapid residence times for ultrafine particle processing.
Established volume favors rotary calciners; emerging adoption favors fluidized bed configurations.
Technology:
Cost tier stratification separates premium oxygen-enriched and temperature-controlled systems from baseline direct-heating installations, with fuel price volatility in Europe and India widening the economic viability gap between technology tiers.
- Direct Heating:Flame-to-material contact delivers maximum thermal transfer efficiency in cement and lime applications. Indian cement producers under CEA energy consumption benchmarks favor these systems for capacity expansions, though rising natural gas prices compress operating margins.
- Oxygen Enriched:Combustion air enrichment reduces fuel intensity and flame temperatures, lowering nitrogen oxide formation. European operators facing EU Industrial Emissions Directive revisions specify these systems to preempt selective catalytic reduction requirements, particularly in Poland and Romania.
- Indirect Heating:Radiant tube or jacketed designs isolate process material from combustion gases for high-purity chemical applications.
- Preheating:Recovered waste heat raises feedstock temperature before calciner entry, improving thermal efficiency.
- Temperature Controlled:Multi-zone thermal management enables precise reaction pathway control for specialty minerals.
Direct heating retains installed base dominance; oxygen enriched configurations are climbing the fastest in new procurement specifications.
Application:
Application concentration reflects infrastructure investment cycles — India's road and rail buildout drives cement and lime demand, while alumina capacity expansion in Vietnam and Indonesia shifts technology preferences toward precision thermal systems.
- Cement Production:Clinker calcination at 1,450°C represents the largest installed calciner base globally. State-owned and private producers in India account for the steepest order acceleration, with consolidated procurement by multinational building materials groups compressing vendor qualification cycles.
- Alumina Processing:Hydrate calcination to smelter-grade alumina demands tight temperature uniformity to avoid alpha-phase contamination. New refining capacity along Vietnam's Central Coast specifies fluidized bed systems with integrated heat recovery, displacing rotary configurations in this application.
- Lime Manufacturing:Calcium carbonate decomposition for steel flux and environmental applications.
- Titanium Dioxide Production:Sulfate or chloride process calcination for pigment manufacturing.
- Zeolite Manufacturing:Controlled thermal activation of aluminosilicate structures for catalytic and adsorbent applications.
Cement production anchors current procurement volume; alumina processing offers the steepest expansion trajectory in technology-specific orders.
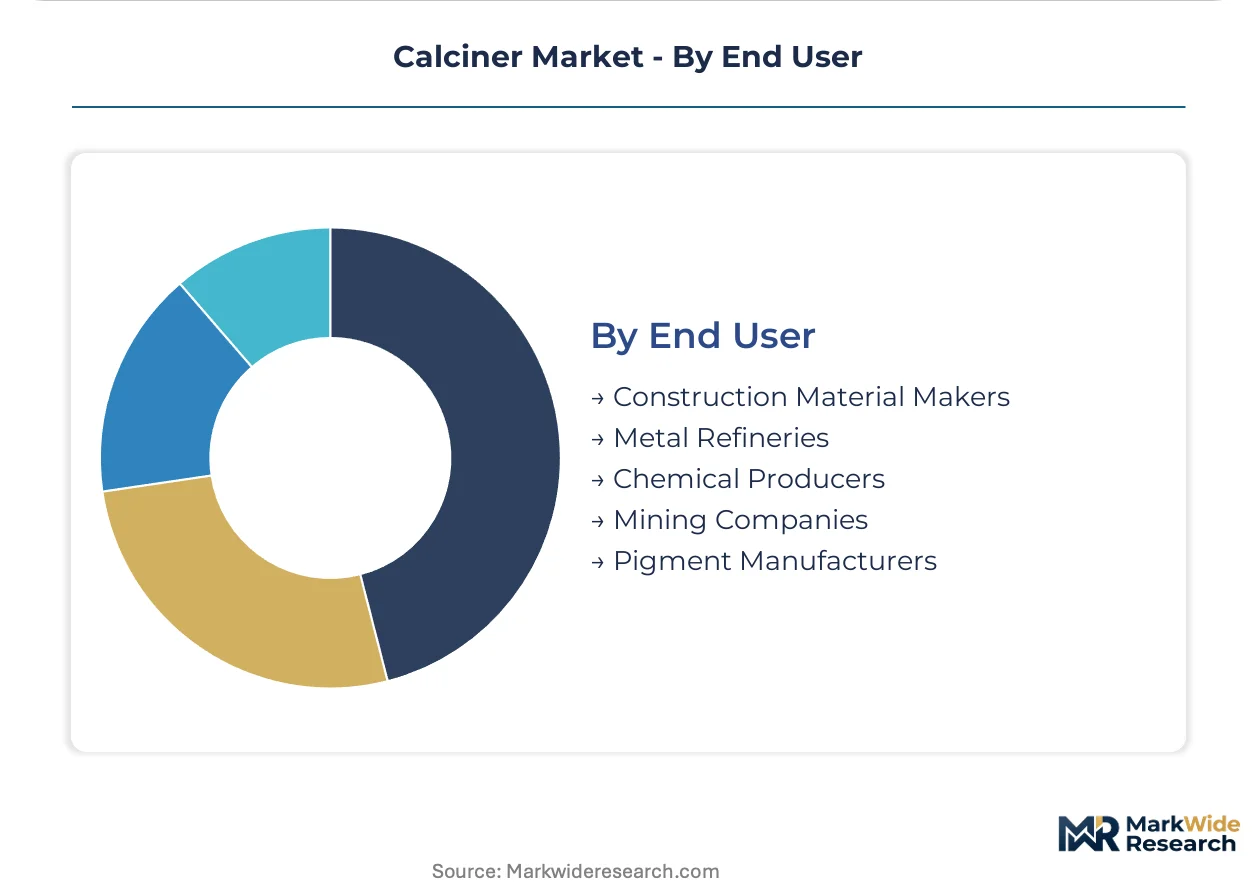
End User:
Customer type determines specification complexity — multinational construction material groups centralize technical standards across subsidiaries, while metal refineries face distinct emissions enforcement that shapes combustion architecture selection.
- Construction Material Makers:Cement and lime producers dominate calciner demand by value. LafargeHolcim and HeidelbergCement subsidiaries in India and Southeast Asia now enforce unified technical specifications, requiring domestic suppliers to meet global standards for approved vendor status.
- Metal Refineries:Non-ferrous metallurgical operators in China face GB emission limits on particulate matter and nitrogen oxides that compel advanced combustion control retrofits. This regulatory pressure creates replacement demand distinct from greenfield cement procurement patterns.
- Chemical Producers:Specialty and commodity chemical manufacturers requiring high-purity oxide outputs.
- Mining Companies:Integrated mineral processors with captive calcination requirements.
- Pigment Manufacturers:Titanium dioxide producers with precise particle size and crystal phase specifications.
Construction material makers concentrate order volume; metal refineries drive fastest-growing retrofit demand under tightening emissions enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters concentrate in Germany, China, and India, with regulatory divergence across these jurisdictions reshaping procurement specifications and supplier qualification requirements.
United States
Cement producers and lime manufacturers drive calciner replacement demand under EPA Maximum Achievable Control Technology standards for hazardous air pollutants. The EPA enforces upgraded combustion controls on mineral processing kilns, compelling operators to retrofit or face operational restrictions. Industrial clusters in Texas and the Midwest anchor domestic procurement, with Houston-area fabricators supplying rotary systems for shale oil-derived lime applications.
China
Non-ferrous metallurgical operators generate retrofit demand as the MEE tightens GB emission limits on nitrogen oxides and particulate matter from thermal processing equipment. The MEE's enforcement of stricter standards is reshaping equipment specifications for both domestic suppliers and multinational licensors. Shandong Province hosts the densest concentration of alumina refineries, where fluidized bed calciner adoption is accelerating over rotary alternatives.
India
State-owned and private cement producers are expanding kiln capacity to meet infrastructure buildout requirements for roads, rail, and urban construction. The CEA mandates energy consumption benchmarks for designated consumers in cement and aluminum sectors, directly influencing calciner efficiency specifications. Gujarat and Rajasthan industrial corridors concentrate the steepest order acceleration, with domestic suppliers now required to meet global technical standards for multinational building materials group vendor lists.
Germany
Specialty chemical and industrial mineral processors sustain demand for precision-engineered indirect-heating systems. The EU Industrial Emissions Directive revision tightens Best Available Technique reference levels for nitrogen oxides, compelling Polish and Romanian cement operators to source advanced combustion equipment from German licensors. North Rhine-Westphalia and Bavaria host the principal fabricator clusters, where certified pressure vessel capacity constraints are extending lead times for specialized systems.
Vietnam
New alumina refining capacity along the Central Coast is creating demand for fluidized bed calciners with precise temperature uniformity specifications. The government's industrial zone development policies are attracting metallurgical investment that requires advanced thermal processing equipment. The Dung Quat and Nhon Hoi economic zones concentrate project development, with equipment procurement favoring systems that meet both export purity standards and emerging domestic emissions protocols.
Calciner Market Competitive Landscape
Concentration sits with full-system integrators possessing combustion control expertise and legacy cement technology heritage. The vendor base stratifies between multinational licensors with integrated digital platforms and regional fabricators serving maintenance-driven replacement cycles. Two strategic archetypes dominate: heritage cement technology suppliers leveraging rotary kiln expertise, and precision thermal specialists capturing alumina and specialty chemical applications. Competitive moves center on bundling emissions control systems into greenfield proposals and consolidating after-sales service contracts through predictive maintenance platforms.
Among heritage cement technology suppliers, FLSmidth and Thyssenkrupp Industrial Solutions occupy positions defined by large rotary installation expertise and European indirect-heating specialization respectively. Schenck Process represents the integrated material-handling and combustion control archetype, differentiating through platform convergence rather than standalone equipment sales. These three anchors exemplify how vendor positioning is diverging between commodity-scale efficiency optimization and precision-engineered systems for high-purity industrial minerals.
| Leading Market Players |
|---|
| Elan Technology |
| Alloy Engineering Company |
| FEECO International |
| Refratechnik |
| FCT Combustion |
| Schenck Process |
| Sackett Waconia |
| FLSmidth |
| Thyssenkrupp Industrial Solutions |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Indian cement producers and German equipment licensors lock in refractory-grade calciner supply while anchoring price visibility across volatile alumina input cycles. These arrangements insulate procurement teams from spot-market swings in magnesia and high-purity bauxite.
Pricing Analysis
EPA Maximum Achievable Control Technology standards dictate the pricing tier structure for rotary calciner retrofits in the United States. Three-tier pricing structure across premium oxygen-enriched combustion systems, standard direct-heating configurations, and economy-grade refractory packages separates compliance-ready installations from baseline equipment. Cost compression in economy tiers is intensifying because Indian domestic suppliers must now meet global technical standards for multinational building materials group vendor lists. State-owned cement producers in Gujarat and Rajasthan exhibit the highest price sensitivity, while specialty chemical processors in Germany prioritize temperature uniformity over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for pressure vessel components sourced from certified German and Italian fabricators. Supply concentrates in Germany for indirect-heating systems, China for fluidized bed calciner fabrication, and India for rotary kiln assembly serving domestic infrastructure buildout. Production draws from high-purity alumina from Guinea and Australia, magnesia from Chinese and Turkish mines, and specialized alloy steel from European mills. Single-source vulnerability in certified pressure vessel capacity creates procurement bottlenecks for European indirect-heating systems. Distribution runs through project-based direct sales for large rotary installations and regional service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as LafargeHolcim and HeidelbergCement centralize calciner specifications across Indian and Southeast Asian subsidiaries, compressing vendor qualification cycles and unbundling after-sales service from initial equipment contracts.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance platforms that lock in long-term service revenue against emerging digital twin specialists. Deepen backward integration into refractory-grade alumina supply through captive sourcing arrangements in Guinea and Australia to offset input volatility. Prioritize combustion engineering talent retention programs to counter the retiring specialized workforce for multi-fuel burner optimization. For New Entrants and Emerging Players: Lead with fluidized bed calciner offerings targeting Vietnam's Central Coast alumina expansion, where precise temperature uniformity specifications create white-space opportunity distinct from saturated rotary cement markets. Target brownfield emissions retrofit demand in China's non-ferrous metallurgical sector under MEE GB emission limits, where legacy DCS integration complexity deters heritage suppliers. Pursue joint development agreements with Indian state-owned cement producers seeking technology transfer for domestic fabrication capability. For Investors and Strategic Acquirers: The market sits at a regulatory-driven replacement cycle phase that favors equipment licensors with bundled DeNOx and emissions control capabilities. Long-term viability over the next decade hinges on exposure to India's infrastructure buildout and China's metallurgical retrofit waves rather than mature European cement demand. Acquisition targets should display integrated digital twin platforms or captive refractory supply chains. Watch for inflection in EPA enforcement intensity on hazardous air pollutant standards as a signal for North American retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Supply | Captive alumina and magnesia sourcing insulates margins from Guinean mining restrictions. |
| Bundled DeNOx System Integration | Preemptive selective catalytic reduction inclusion secures greenfield approvals under EU Industrial Emissions Directive. |
| Predictive Maintenance Platform Launch | Physics-based digital twin contracts convert equipment sales into recurring service revenue streams. |
| Oxygen-Enriched Combustion Scale-Up | Reduced fuel intensity addresses CEA energy benchmarks for Indian cement designated consumers. |
| Regional Fabrication Joint Venture | Domestic Indian production meets multinational technical standards while shortening procurement timelines. |
Research Methodology
Desk research of customs and trade data, SEC filings from industrial equipment manufacturers, and emissions enforcement databases preceded structured interviews with cement plant engineering directors, procurement leads at multinational building materials groups, aftermarket service heads, and combustion technology specialists. Primary fieldwork captured procurement specification evolution, retrofit economics decision frameworks, and regulatory compliance timelines. Secondary validation drew from EPA enforcement records, China's MEE emission standard publications, and India's CEA energy consumption notifications. Bottom-up order book analysis triangulated against top-down market sizing across product configurations.
Variance decomposition separates volume growth from price realization across rotary, fluidized bed, and shaft calciner configurations. Segmentation dimensions modeled include thermal technology tier, application concentration in cement versus alumina processing, end-user archetype between multinational construction material groups and state-owned metal refineries, and regional regulatory cluster spanning US EPA, China MEE, and India CEA jurisdictions. CAGRs were derived from equipment order flow projections and replacement cycle timing. Industry-specific forecast inputs incorporate refractory input cost trajectories and emissions compliance deadline clustering.
The analysis sits within stated boundaries; outcomes outside sustained Indian infrastructure investment intensity or accelerated EPA enforcement would require recalibration. Forecasts reflect assumptions on regulatory implementation timelines, technology substitution thresholds for plasma and microwave alternatives, and refractory raw material supply continuity. Recalibration cycles align with material shifts in emissions enforcement intensity, multinational procurement centralization decisions, and breakthroughs in electrified thermal processing below 1,200°C.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Nano-Bubble Generator Market