
 North America Medical Imaging Software Market | 2026-2036
North America Medical Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Imaging Software Market Foresight
Radiologist workforce shortages across the United States and Canada are unwinding traditional service delivery models and forcing health systems toward automated image analysis tools. GE HealthCare Technologies leverages its installed base of imaging hardware to bundle proprietary software contracts. Siemens Healthineers anchors its North American position through deep integration of AI algorithms into existing CT and MRI workflows. Koninklijke Philips competes by extending its diagnostic informatics portfolio into enterprise-wide imaging networks.
Medical imaging software encompasses programs that acquire, process, reconstruct, visualize, and analyze anatomical and functional data from modalities such as CT, MRI, and ultrasound, typically operating at slice thickness resolutions below one millimeter for diagnostic confidence. The primary commercial purpose centers on converting raw detector signals into clinically actionable images while streamlining radiologist interpretation time. Cloud-based deployment is capturing the fastest expansion as hospital IT departments prioritize scalable infrastructure over capital-intensive on-premise servers. Diagnostic imaging software retains the largest revenue pool given its direct linkage to billable radiology procedures across hospitals and diagnostic centers.
FDA software-as-a-medical-device frameworks and HIPAA security requirements shape product development cycles and customer procurement criteria throughout the United States. Health Canada's Medical Devices Bureau imposes parallel premarket review obligations that vendors must navigate for Canadian market access. Stakeholders should monitor how reimbursement policy evolution for AI-assisted reads alters purchasing timelines across hospital networks.
Market Dynamics
Radiologist workforce shortages across the United States and Canada are unwinding traditional service delivery models and forcing health systems toward automated image analysis tools.
Growth Catalysts
- FDA software-as-a-medical-device pathways:Streamlined clearance frameworks accelerate commercial entry for AI diagnostic developers, reducing time-to-revenue for algorithm vendors.
- Hospital IT infrastructure modernization:United States health systems prioritize scalable cloud deployment over capital-intensive on-premise servers, expanding addressable market for SaaS imaging platforms.
- CT and MRI modality expansion:Slice thickness resolutions below one millimeter now standard across diagnostic centers, generating raw data volumes that demand automated reconstruction software.
Market Restraints
- HIPAA security compliance costs:Encryption and audit requirements for patient data in transit impose recurring operational burdens on cloud-native vendors.
- Health Canada premarket review timelines:Medical Devices Bureau parallel obligations create dual-track regulatory friction for vendors seeking cross-border deployment.
- Legacy PACS integration complexity:Proprietary data formats from installed hardware bases constrain interoperability for new software entrants.
Strategic Opportunities
- Canadian cloud deployment corridor:Secondary growth market emerging as provincial health systems consolidate imaging networks and seek vendor-agnostic platforms.
- AI-assisted read reimbursement evolution:CMS policy experimentation creates first-mover advantage for vendors with FDA-cleared algorithms in lung nodule and fracture detection.
- Enterprise imaging network convergence:Radiology informatics platforms merging with cardiology and pathology workflows to capture hospital-wide IT budgets.
Industry Challenges
- Algorithm validation talent scarcity:Clinical AI development pipelines bottleneck on radiologists capable of ground-truth annotation at scale.
- Multi-site deployment standardization:Variability in DICOM implementation across United States hospital networks fragments vendor support requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Imaging Software Market |
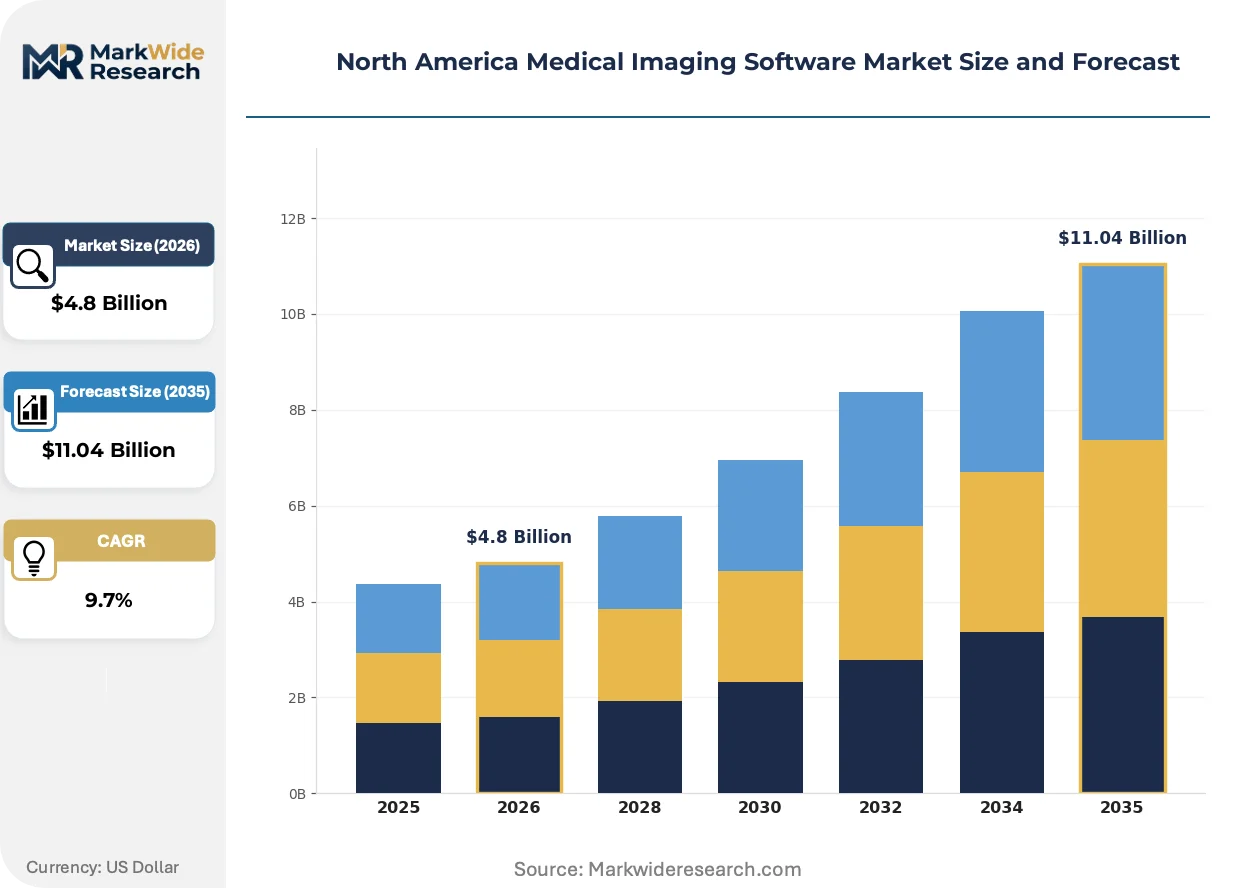
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Workflow Solutions, Picture Archiving, Radiology Information Systems End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions Technology: X-Ray, MRI, CT Scan, Ultrasound |
| Companies Covered | GE HealthCare Technologies, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, MIM Software, Fujifilm Holdings, Agfa-Gevaert Group, Merative, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Imaging Software Market Shifts & Advancements
Artificial intelligence deployment models are actively fragmenting how diagnostic software reaches clinical users, creating parallel tracks for embedded hardware solutions and independent cloud platforms.
Generative reconstruction algorithms is bifurcating the preprocessing layer of CT and MRI workflows. Academic medical centers in the United States deploy these tools to reduce radiation dose while maintaining diagnostic confidence. The technology is compressing hardware upgrade cycles as software-defined imaging displaces detector-centric performance claims.
FDA's predetermined change control plans for machine learning-enabled devices now govern iterative algorithm updates without full resubmission. This industrial consequence accelerates improvement velocity for cleared products. United States radiology groups respond by embedding software procurement into long-term service contracts rather than perpetual license purchases.
Subscription-based pricing now dominates procurement conversations between vendors and hospital networks. Capital expenditure committees defer to operational budgets as cloud hosting eliminates server ownership. Canadian provincial purchasing consortia exhibit this behavioral shift most visibly, consolidating multi-year enterprise agreements across imaging modalities.
North America Medical Imaging Software Market Segmentation
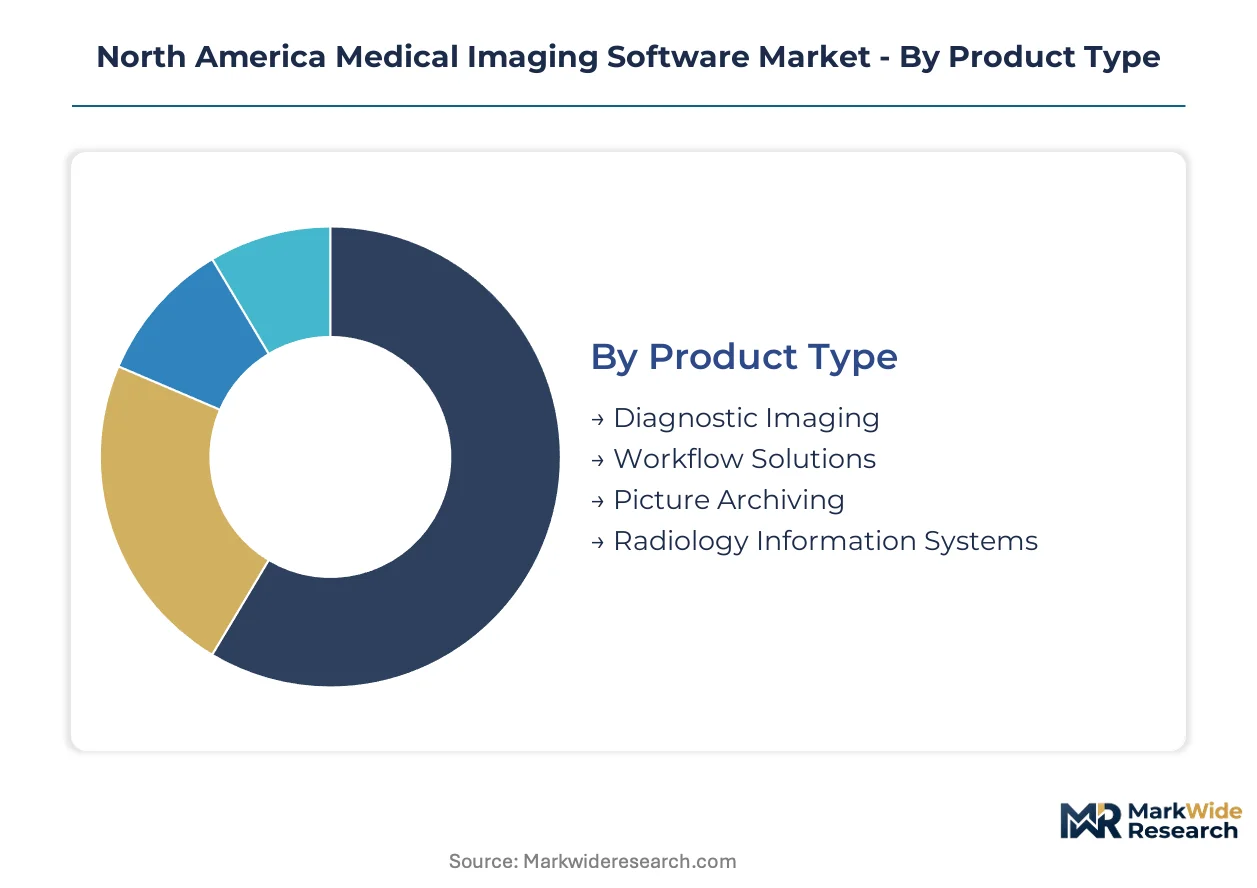
Medical imaging software segments align with distinct procurement pathways and regulatory obligations across the United States and Canada. Vendors structure product portfolios around deployment constraints, end-user IT maturity, and modality-specific FDA clearance requirements.
Product Type:
FDA software-as-a-medical-device frameworks impose divergent validation burdens across functional categories, shaping vendor R&D allocation and hospital procurement timelines.
- Diagnostic Imaging:Algorithms reconstruct raw detector signals into clinically actionable images at sub-millimeter slice thickness for CT and MRI modalities. United States hospitals prioritize these tools to compress radiologist reading times amid workforce shortages.
- Workflow Solutions:Orchestration platforms integrate scheduling, reporting, and communication layers across distributed radiology departments. Canadian provincial health systems deploy these to consolidate imaging networks spanning multiple facilities.
- Picture Archiving:DICOM-compliant storage systems manage longitudinal image repositories with HIPAA-mandated encryption and audit trails.
- Radiology Information Systems:Administrative modules handle order entry, result distribution, and billing integration with hospital EHR infrastructure.
Diagnostic Imaging handles the majority of throughput; Workflow Solutions is the fastest mover on share.
End User:
Capital availability and IT staffing depth segment demand across institutional tiers, with reimbursement complexity further stratifying purchasing authority.
- Hospitals:Integrated delivery networks command enterprise-wide imaging budgets and negotiate multi-year SaaS contracts. United States health systems embed AI procurement into long-term service agreements with modality vendors.
- Diagnostic Centers:Independent imaging facilities prioritize interoperability with referring physician networks and cloud scalability over on-premise infrastructure ownership.
- Research Institutes:Academic medical centers deploy generative reconstruction algorithms to reduce radiation dose while maintaining diagnostic confidence in clinical trials.
- Outpatient Clinics:Limited IT departments drive preference for vendor-managed hosting and simplified PACS integration.
Hospitals absorb the dominant share of enterprise licensing; Diagnostic Centers are climbing the fastest as independent imaging volume expands.
Deployment:
Health system IT modernization cycles and HIPAA security compliance costs create divergent total cost of ownership profiles across infrastructure models.
- Cloud-Based:Scalable hosting eliminates capital-intensive server procurement and shifts expenditure to operational budgets. Canadian provincial purchasing consortia consolidate multi-year enterprise agreements across this deployment mode.
- On-Premise:Legacy installations persist in United States hospitals with specialized security requirements or existing data center investments.
- Hybrid:Architectures partition sensitive patient data on-site while leveraging cloud compute for non-PHI processing workloads.
- Mobile Solutions:Point-of-care applications enable bedside ultrasound and emergency department triage with tablet-based image review.
Cloud-Based deployment leads volume expansion; Hybrid models are gaining share fastest as risk-averse institutions transition incrementally.
Technology:
Modality-specific algorithm development pipelines concentrate vendor expertise around detector physics and reconstruction mathematics.
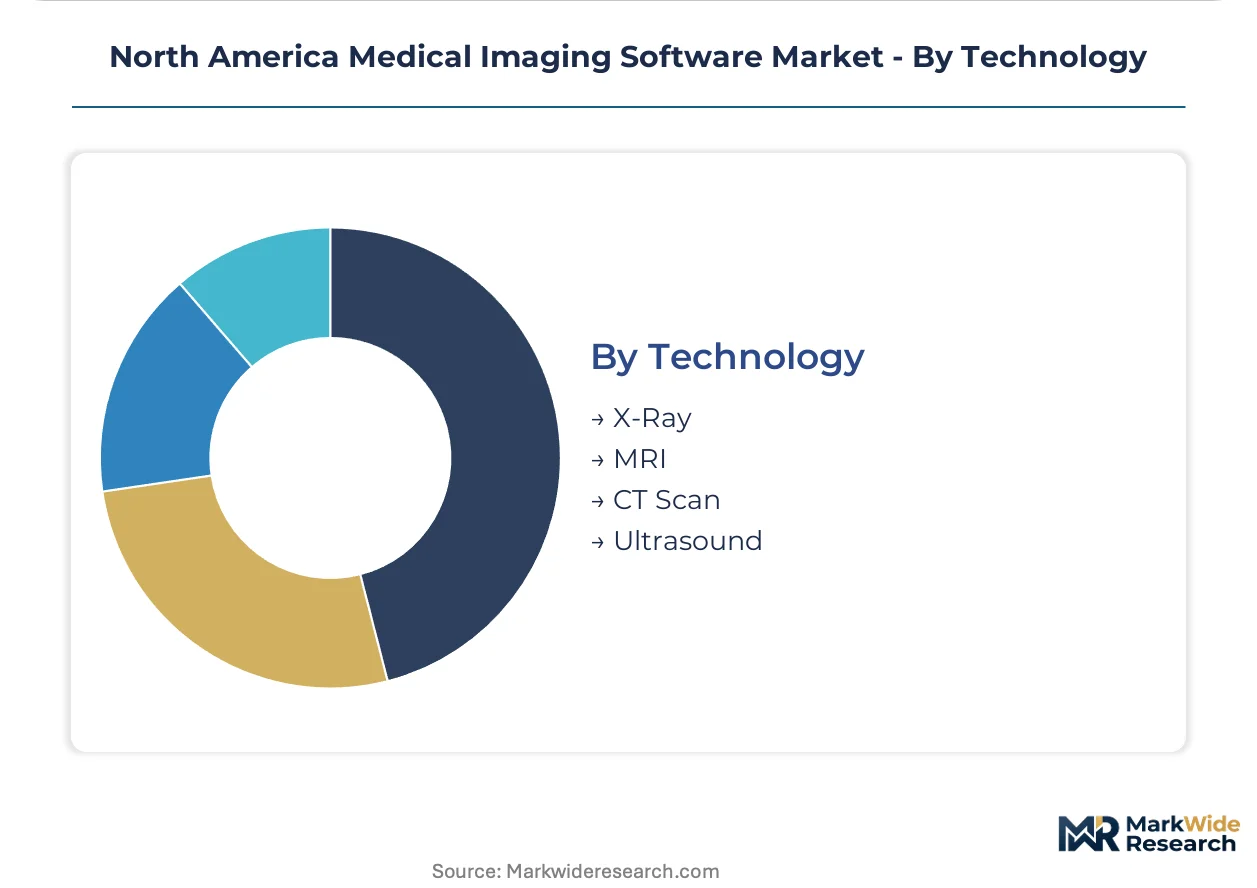
- CT Scan:Iterative reconstruction and deep learning denoising algorithms process high-volume axial datasets. FDA-cleared lung nodule detection tools anchor reimbursement experimentation by CMS.
- MRI:Accelerated acquisition sequences and synthetic contrast generation reduce scan duration. United States academic centers deploy these to expand throughput without magnet hardware upgrades.
- X-Ray:Digital radiography and fluoroscopy systems integrate computer-aided detection for fracture and pneumonia screening.
- Ultrasound:Real-time image enhancement and automated measurement tools target point-of-care and cardiovascular applications.
CT Scan commands the largest algorithm development investment; MRI shows the steepest expansion trajectory as software-defined imaging displaces hardware-centric performance claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes medical imaging software primarily through enterprise hospital networks seeking AI-enhanced diagnostic platforms, while Canadian health systems favor cloud-based deployment models for provincial network consolidation. Mexico represents an emerging corridor where diagnostic center chains are modernizing legacy PACS infrastructure.
United States
FDA software-as-a-medical-device pathways accelerate commercial entry for AI diagnostic developers across integrated delivery networks. HIPAA security requirements shape procurement criteria for cloud-native vendors serving hospital IT departments. The Greater Boston corridor anchors academic medical center deployment of generative reconstruction algorithms for radiation dose reduction.
Canada
Provincial health systems consolidate imaging networks spanning multiple facilities, driving demand for vendor-agnostic workflow orchestration platforms. Health Canada's Medical Devices Bureau imposes premarket review obligations parallel to FDA frameworks. Ontario's purchasing consortia negotiate multi-year enterprise agreements for cloud-based SaaS imaging platforms.
Mexico
Independent diagnostic imaging chains prioritize interoperability with referring physician networks and scalable cloud infrastructure over capital-intensive server ownership. The country's national pharmaceutical regulator maintains alignment with international medical device standards for software clearance. Mexico City Metro anchors private hospital network modernization of CT and MRI workflow integration.
North America Medical Imaging Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with modality-hardware bundlers commanding enterprise contract value while pure-play algorithm vendors capture niche diagnostic applications. The upper tier leverages installed imaging equipment bases to secure long-term service agreements. Three archetypes dominate: hardware-integrated platform providers, independent AI algorithm specialists, and legacy PACS modernization vendors. Competitive moves center on backward integration into proprietary reconstruction mathematics and geographic expansion through provincial purchasing consortia.
Among hardware-integrated platform providers, GE HealthCare Technologies and Siemens Healthineers exemplify the bundling archetype, anchoring positions through deep workflow integration. Koninklijke Philips occupies a position extending diagnostic informatics into enterprise-wide imaging networks. These three represent divergent strategic postures within the consolidated tier: equipment-centric bundling, algorithm-native integration, and informatics portfolio expansion.
| Leading Market Players |
|---|
| GE HealthCare Technologies |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| MIM Software |
| Fujifilm Holdings |
| Agfa-Gevaert Group |
| Merative |
| Carestream Health |
| Others |
Supply & Pricing Matrix
Multi-year SaaS contracts lock in both supply access and price visibility for United States hospital networks procuring AI-enhanced diagnostic platforms. These agreements shift capital expenditure to operational budgets while binding vendors to predictable revenue streams across the deployment lifecycle.
Pricing Analysis
Subscription-based SaaS pricing dominates procurement between vendors and United States hospital networks. Price differentiation hinges on FDA clearance tier and enterprise scale, with cleared algorithms commanding premium positioning over experimental modules. Cost compression in mid-tier workflow solutions is intensifying because Canadian provincial consortia negotiate volume-driven enterprise agreements. Diagnostic centers exhibit highest price sensitivity due to thin margins on reimbursable reads, while integrated delivery networks prioritize total cost of ownership over per-seat licensing.
Supply Chain Analysis
Inventory cycles for GPU compute infrastructure stretch lead times for cloud-native algorithm vendors serving North American health systems. Supply concentrates in Taiwan for semiconductor fabrication, the United States for cloud hyperscaler infrastructure, and Ireland for European data residency compliance. Raw material dependencies span NVIDIA accelerators, DICOM-compliant storage arrays, and HIPAA-certified encryption modules. Single-source vulnerability around specialized AI training hardware creates procurement risk for scaling vendors. Distribution runs through value-added resellers with hospital GPO relationships and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
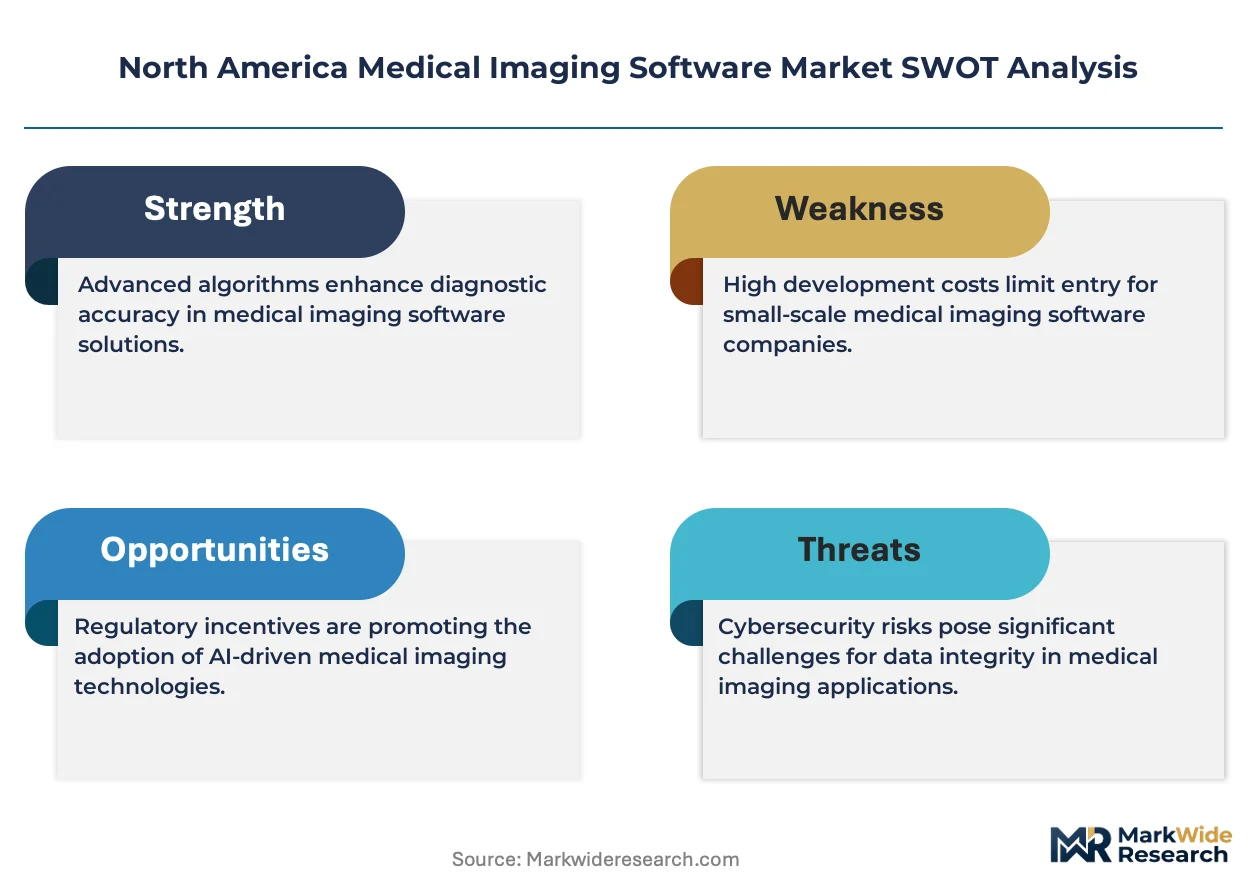
This market functions as a defensive-moat arena where regulatory entrenchment erects substantial barriers against algorithmic challengers. FDA software-as-a-medical-device frameworks and Health Canada parallel obligations cement incumbent positions through multi-year clearance timelines.
For Market Incumbents: Compound installed-base advantages by embedding proprietary reconstruction algorithms into modality hardware refresh cycles. Deepen backward integration into cloud infrastructure ownership to capture recurring SaaS margins. Counter pure-play AI specialists through exclusive GPO contract extensions with United States hospital networks.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for lung nodule and fracture detection algorithms. Canadian provincial cloud deployment corridors offer the most penetrable geography given vendor-agnostic procurement mandates. Pursue point-of-care ultrasound enhancement as a beachhead segment with lower regulatory friction and faster clinical validation cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-native specialists with FDA-cleared products in reimbursable diagnostic categories. Long-term viability rests on sustainable differentiation through iterative algorithm improvement under predetermined change control plans. Monitor CMS reimbursement policy evolution for AI-assisted reads as the decisive inflection signal for enterprise purchasing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | FDA clearance accelerates commercial entry for AI diagnostic developers across United States health systems. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks lock in multi-year SaaS revenue visibility. |
| Cloud Infrastructure Integration | Scalable hosting eliminates capital barriers for Canadian provincial imaging network consolidation. |
| Reimbursement Strategy Development | CMS policy alignment for AI-assisted reads unlocks purchasing authority within hospital IT committees. |
| Geographic Expansion via Provincial Consortia | Ontario and Quebec purchasing vehicles aggregate demand across multi-facility imaging networks. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. The research team conducted structured conversations with radiology department chairs, hospital purchasing committee members, biomedical engineers, and GPO contracts managers across United States and Canadian health systems. Secondary sources included FDA 510(k) and De Novo clearance databases, Health Canada Medical Devices Bureau submissions, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up algorithm vendor revenue estimates and top-down health system IT spending allocations were triangulated to establish market sizing boundaries.
Sensitivity analysis around cloud adoption velocity and AI reimbursement policy timelines shapes the forecast confidence intervals across the projection horizon. The analytical framework models segmentation across deployment mode, end-user institution tier, imaging modality, and regional regulatory cluster. CAGRs were derived from installed base expansion rates, hardware replacement cycles, and software attach-rate assumptions. Key inputs include radiologist workforce shortage projections, HIPAA compliance cost trajectories, and provincial health system consolidation timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance momentum and stable cloud infrastructure pricing would require recalibration. Forecasts reflect documented assumptions regarding algorithm validation throughput and cross-border regulatory alignment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
North America Computed Tomography (CT) Market