
 North America Low Fat Sausage Market | 2026-2036
North America Low Fat Sausage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Low Fat Sausage Market Insights
USDA Process Verified certification is unwinding competitive barriers for low-fat sausage entrants lacking verified lean-content claims. Johnsonville LLC leverages its vertically integrated pork supply chain to sustain consistent fat-standard compliance across retail and foodservice channels. Hormel Foods Corp. anchors its position through dedicated R&D facilities in Minnesota that specialize in fat-replacement technologies for processed meat applications. Tyson Foods Inc. competes by dominating chicken-based low-fat sausage production, a segment where white meat yields natural advantages in saturated fat reduction.
North America low fat sausage comprises emulsified or coarse-ground meat products containing reduced fat content, typically achieved through lean muscle selection, mechanical separation, or fat-mimicking hydrocolloid inclusion, formulated to deliver comparable texture and flavor intensity at under 10 grams total fat per serving. The primary commercial purpose centers on satisfying health-conscious consumers and institutional buyers seeking protein options aligned with cardiac dietary recommendations without sacrificing sensory expectations. Turkey and chicken product types lead volume contribution due to inherently leaner muscle composition, while online retail distribution channels represent the fastest-expanding access point as direct-to-consumer cold-chain logistics mature. Supermarkets retain the deepest margin pools through private-label low-fat sausage programs that capture price-sensitive shoppers.
FDA nutrition labeling standards and USDA FSIS inspection protocols collectively determine fat-content claim permissibility, directly constraining which products qualify for "low fat" or "lean" designations on North American shelves. Health Canada parallel regulations for saturated fat thresholds in processed meats create additional compliance layers for cross-border suppliers serving Canadian retail and foodservice accounts. Stakeholders must monitor evolving sodium-reduction mandates alongside fat-content rules, as dual reformulation requirements threaten to compress processing margins faster than single-nutrient adjustments alone.
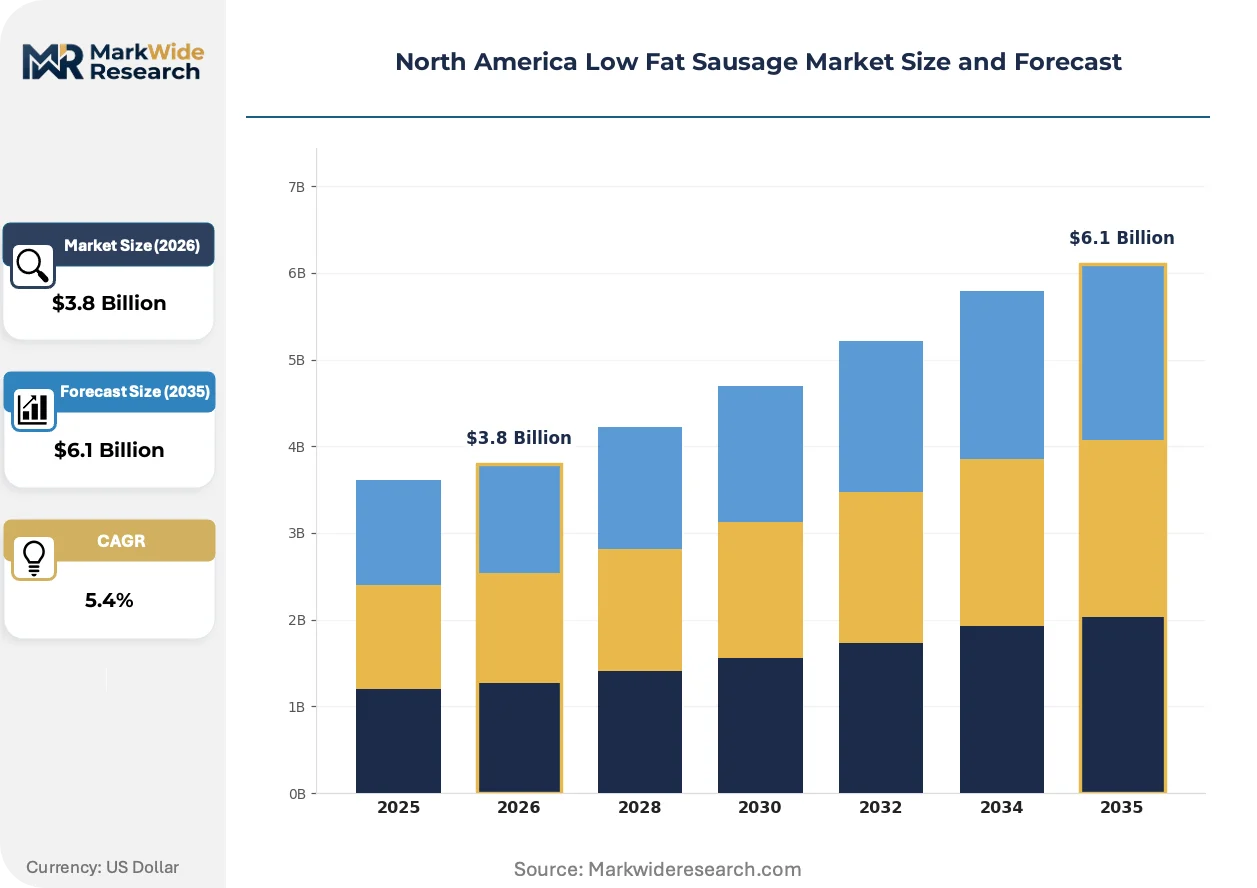
Market Dynamics
USDA Process Verified certification requirements are compressing margins for unverified processors while rewarding vertically integrated suppliers with compliant lean-content supply chains across retail and foodservice channels.
Growth Catalysts
- FDA Nutrition Labeling Standards:Updated serving-size and fat-content disclosure rules are compelling reformulation investments that create first-mover advantages for compliant processors in US retail channels.
- Quick-Service Restaurant Procurement:Texas, California, and Ontario operators are expanding all-day breakfast menus with certified lean sausage alternatives, pulling volume from traditional pork breakfast links.
- Direct-to-Consumer Cold-Chain Logistics:Refrigerated last-mile delivery infrastructure is decomposing supermarket gatekeeper power and enabling subscription-based low-fat poultry sausage programs.
Market Restraints
- Lean Pork Input Volatility:US sow herd contraction and Canadian pork processing capacity constraints are amplifying price swings for 90/10 lean-to-fat trim specifications.
- Dual-Nutrient Reformulation Costs:Simultaneous USDA sodium-reduction mandates and fat-content thresholds are forcing redundant R&D cycles that smaller processors cannot absorb.
- Plant-Based Protein Substitution:Pea and mycoprotein breakfast sausage alternatives are capturing shelf space in California and Pacific Northwest retail accounts.
Strategic Opportunities
- Underpenetrated Canadian Foodservice:Ontario and Quebec institutional buyers lag US counterparts in lean-sausage adoption, creating whitespace for USDA-certified suppliers with cross-border distribution.
- Online Retail Channel Expansion:Amazon Fresh and specialized meat subscription platforms are building refrigerated fulfillment networks that bypass traditional broker relationships.
- Health Canada Saturated Fat Threshold Alignment:Pending regulatory harmonization with US standards would streamline cross-border product qualification and reduce dual-labeling costs.
Industry Challenges
- Fat-Replacement R&D Talent Scarcity:Hydrocolloid formulation expertise for meat applications concentrates in Minnesota and Wisconsin, constraining expansion timelines for processors outside these clusters.
- USDA FSIS Inspection Queue Delays:Certification backlog for revised lean-content claims is extending product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Low Fat Sausage Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Turkey, Pork, Beef Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Cafes, Catering Services Flavor Profile: Spicy, Mild, Smoked, Herb |
| Companies Covered | Johnsonville LLC, Hormel Foods Corp., Bob Evans Farms, Tyson Foods Inc., Butterball LLC, Boar's Head, Applegate Farms LLC, Aidells Sausage Company, Premium Brands Holding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Low Fat Sausage Market Trends and Innovations
Reformulation science and procurement digitization are converging to compress traditional product development cycles while fragmenting historical channel control across North American protein supply chains.
Advanced fat-mimicking hydrocolloid systems are decomposing the texture-performance gap between reduced-fat and conventional sausage. Foodservice manufacturers in the Midwest are adopting these binding agents at accelerating rates. The technology is decomposing the premium pricing power historically held by full-fat artisanal producers.
USDA FSIS inspection protocol updates for "lean" and "extra lean" claims are tightening analytical verification requirements. Small-to-mid processors face capital outlays for compositional testing equipment. Canadian exporters to US retail are responding by pre-certifying production lines against both USDA and Health Canada standards.
Corporate procurement teams at multi-unit restaurant chains are consolidating supplier relationships around vertically integrated processors with captive lean-muscle supply. Traditional meat brokers are losing share to direct manufacturer agreements. This concentration is most visible in Texas and California breakfast-menu supply chains.
North America Low Fat Sausage Market Segmentation
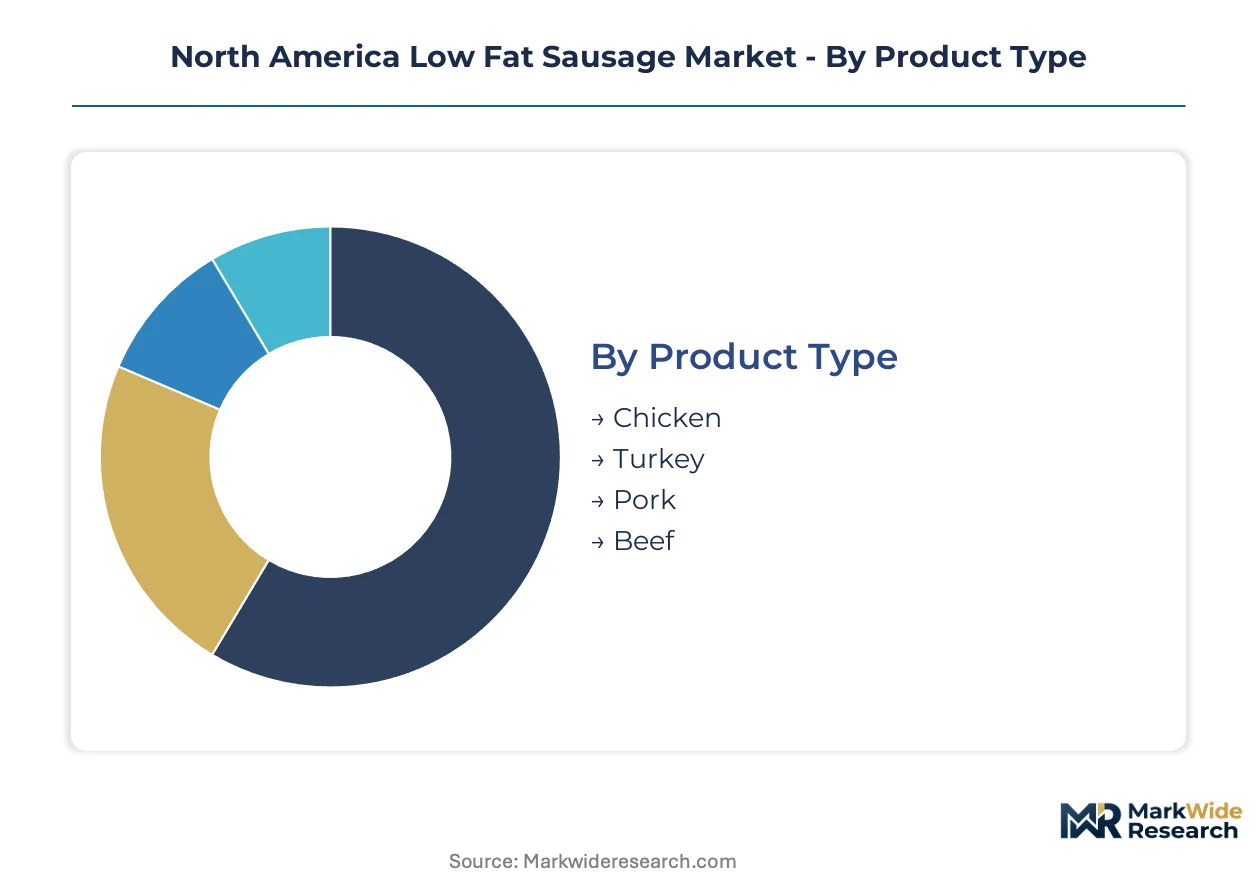
Segmentation in the North America low fat sausage market reveals distinct margin architectures across protein sources and channel access. Each dimension carries specific regulatory, logistical, and reformulation cost structures that determine profitability for processors and retailers.
Product Type:
Margin pools concentrate in poultry-based varieties where inherent leanness reduces fat-replacement R&D expenditure and USDA certification complexity.
- Chicken:White meat yields natural saturated fat advantages below USDA "lean" thresholds without hydrocolloid supplementation. Tyson Foods dominates production scale, with quick-service restaurant procurement in Texas and California driving volume concentration.
- Turkey:Dark meat inclusion allows texture parity with pork sausage at reduced fat content, though supply concentrates in Minnesota and Wisconsin processing clusters where vertical integration controls input costs.
- Pork:Requires mechanical separation and lean trim selection to achieve certification, exposing processors to 90/10 lean-to-fat input volatility from US sow herd contraction.
- Beef:Niche positioning in specialty retail with premium pricing offsetting higher raw material costs and limited foodservice penetration.
The dominant share belongs to Chicken, while Turkey is closing the gap fastest.
Distribution Channel:
Channel selection determines cold-chain cost absorption and price realization, with direct-to-consumer models capturing margin historically ceded to retail intermediaries.
- Supermarkets:Private-label programs at Kroger, Albertsons, and Loblaws capture price-sensitive households through dedicated shelf space and promotional velocity.
- Online Retail:Amazon Fresh and specialized subscription platforms are expanding refrigerated fulfillment networks that bypass traditional broker relationships, with steepest expansion trajectory in Ontario and Pacific Northwest metropolitan zones.
- Convenience Stores:Limited SKU breadth favors single-serve breakfast links with extended shelf-life packaging.
- Specialty Stores:Whole Foods and regional natural food retailers command premium placement for certified organic and animal welfare-approved varieties.
Supermarkets retain volume leadership, though Online Retail is gaining share fastest among emerging channels.
End User:
Application context dictates fat-content claim requirements and procurement specification rigor, with institutional buyers enforcing tighter compositional standards than household purchasers.
- Restaurants:Quick-service operators in Texas, California, and Ontario are expanding all-day breakfast menus with certified lean alternatives, consolidating supplier relationships around vertically integrated processors.
- Households:Health-conscious consumers in US suburban markets and Canadian urban centers drive retail velocity for reduced-fat poultry varieties.
- Cafes:Independent operators in Pacific Northwest and Northeast corridors favor artisanal-positioned turkey sausage with clean-label ingredient declarations.
- Catering Services:Institutional procurement teams at corporate and healthcare accounts require dual USDA-Health Canada certification for cross-border menu consistency.
Restaurants command the largest volume allocation, while Catering Services is expanding most quickly as institutional nutrition standards tighten.
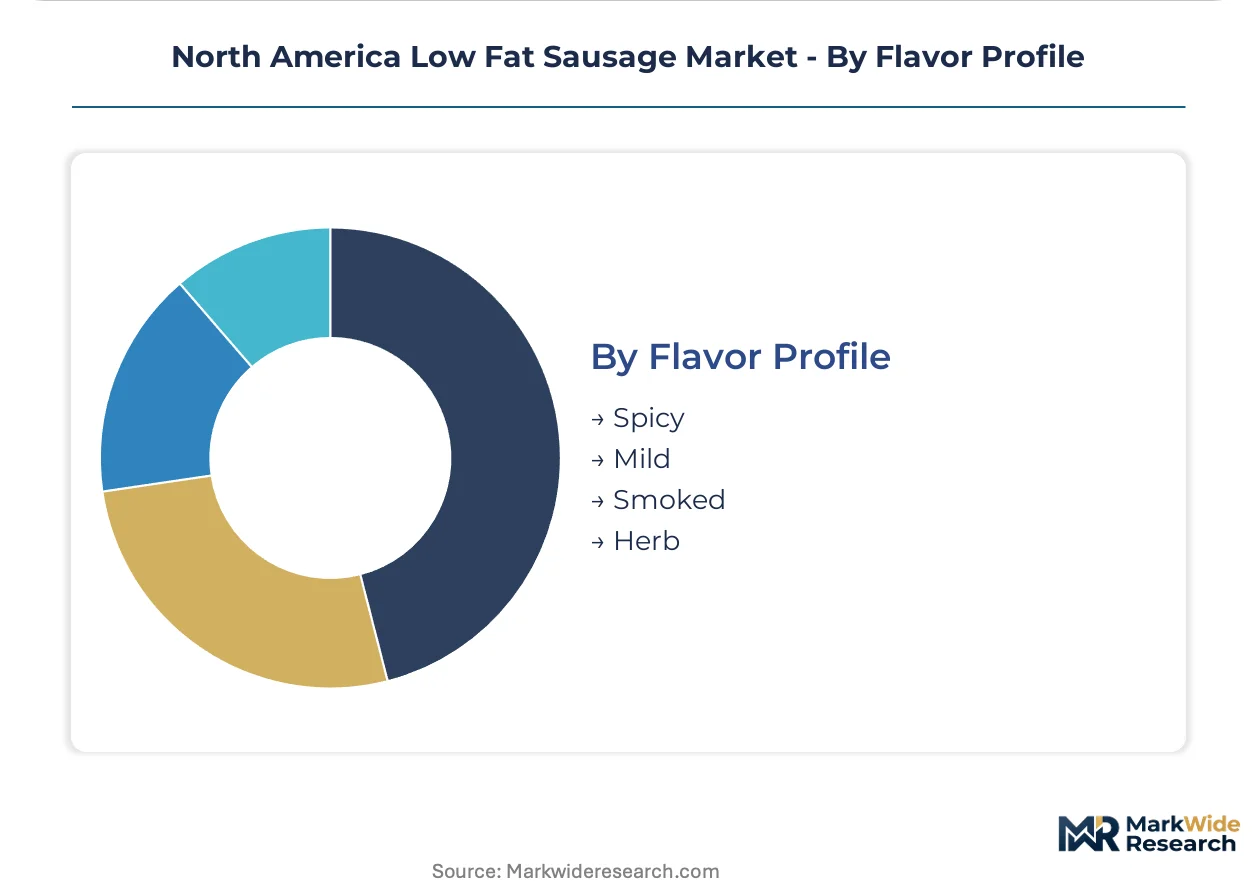
Flavor Profile:
Flavor innovation intensity correlates with premium positioning power and repeat purchase rates in saturated retail environments.
- Spicy:Jalapeño and andouille-style formulations dominate Texas and Southwest US foodservice accounts, with capsaicin masking reduced-fat texture deficits.
- Mild:Standard breakfast link positioning captures the broadest household penetration across US Midwest and Canadian Prairie provinces.
- Smoked:Hardwood smoke flavoring enables clean-label positioning without artificial additives, concentrated in specialty retail and premium foodservice.
- Herb:Sage, thyme, and rosemary profiles align with Mediterranean diet positioning in California and Northeast urban markets.
Mild formulations hold the dominant share, while Spicy variants are climbing the fastest as quick-service operators seek menu differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles cold-chain infrastructure anchors trans-Pacific protein flows into North American distribution networks. Interstate 35 and Canadian National Railway corridors link Midwest processing clusters to Texas and Ontario foodservice terminals. This multimodal grid shapes regional competitive positioning across the three-country trade zone.
United States
Texas quick-service operators and California health-conscious households drive divergent demand profiles for lean poultry and reformulated pork varieties. FDA updated nutrition labeling rules and USDA FSIS inspection protocols constrain fat-content claim permissibility on retail shelves. Minnesota and Wisconsin processing clusters concentrate hydrocolloid R&D talent and vertically integrated turkey supply chains.
Canada
Ontario and Quebec institutional buyers lag US counterparts in certified lean-sausage adoption, creating whitespace for cross-border suppliers. Health Canada saturated fat thresholds for processed meats impose additional compliance layers beyond USDA requirements. Toronto and Vancouver metropolitan zones show steepest online retail expansion for direct-to-consumer poultry sausage subscriptions.
Mexico
Nuevo León and Mexico City Metro foodservice sectors import US-certified lean varieties for hotel and restaurant breakfast programs. Mexico's national food safety regulator enforces processed meat labeling standards that partially align with US nutritional disclosure frameworks. Bajío Region pork processing capacity supplies domestic trim specifications while northern border states facilitate cross-border cold-chain logistics.
North America Low Fat Sausage Market Competitive Landscape
Listed leaders compete with private specialists across certification and channel access dimensions. The vendor base clusters around three structural tiers: scale-driven diversified protein conglomerates with captive poultry supply, mid-cap regional processors with USDA Process Verified lean-content claims, and specialty private-label suppliers serving natural food retail. Strategic moves concentrate on backward integration into lean-muscle supply and direct foodservice contracting that displaces traditional broker relationships.
Within the scale-driven tier, Tyson Foods Inc. and Hormel Foods Corp. exemplify diversified protein conglomerates with integrated supply chain control. Johnsonville LLC anchors the private specialist category as a vertically structured processor with captive pork supply. These three entities represent distinct competitive archetypes: white-meat poultry dominance, fat-replacement R&D specialization, and lean-trim supply chain integration.
| Leading Market Players |
|---|
| Johnsonville LLC |
| Hormel Foods Corp. |
| Bob Evans Farms |
| Tyson Foods Inc. |
| Butterball LLC |
| Boar's Head |
| Applegate Farms LLC |
| Aidells Sausage Company |
| Premium Brands Holding Corporation |
| Others |
Pricing and Supply Chain Analysis
Lean-trim pork substitution for mechanically separated poultry is redrawing procurement geography across the US-Canada border while compressing margin structures for processors lacking captive supply. This input shift simultaneously elevates Minnesota-Wisconsin processing clusters and intensifies spot-market exposure for unintegrated operators.
Pricing Analysis
USDA Process Verified certification grade creates the primary spread between premium and standard tiers, with compliant processors commanding shelf placement at Kroger and Loblabs. Three-tier pricing structure across premium certified, standard retail, and economy private-label levels stratifies by lean-content verification and hydrocolloid formulation quality. Cost compression in the economy tier is intensifying because sow herd contraction amplifies 90/10 trim price volatility. Quick-service restaurant procurement teams exhibit lowest price sensitivity due to menu-margin protection, while household purchasers through online channels demonstrate highest elasticity.
Supply Chain Analysis
Interstate 35 corridor chokepoints between Minnesota processing clusters and Texas distribution terminals concentrate cold-chain risk for time-sensitive lean-sausage delivery. Geographic supply concentration centers on the United States, Canada, and Mexico, with raw material dependencies spanning US sow herds, Canadian pork processing capacity, and Mexican trim specifications. Single-source vulnerability in Minnesota-Wisconsin hydrocolloid R&D talent constrains formulation innovation timelines. Distribution runs through multi-unit restaurant direct contracting that displaces traditional meat broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
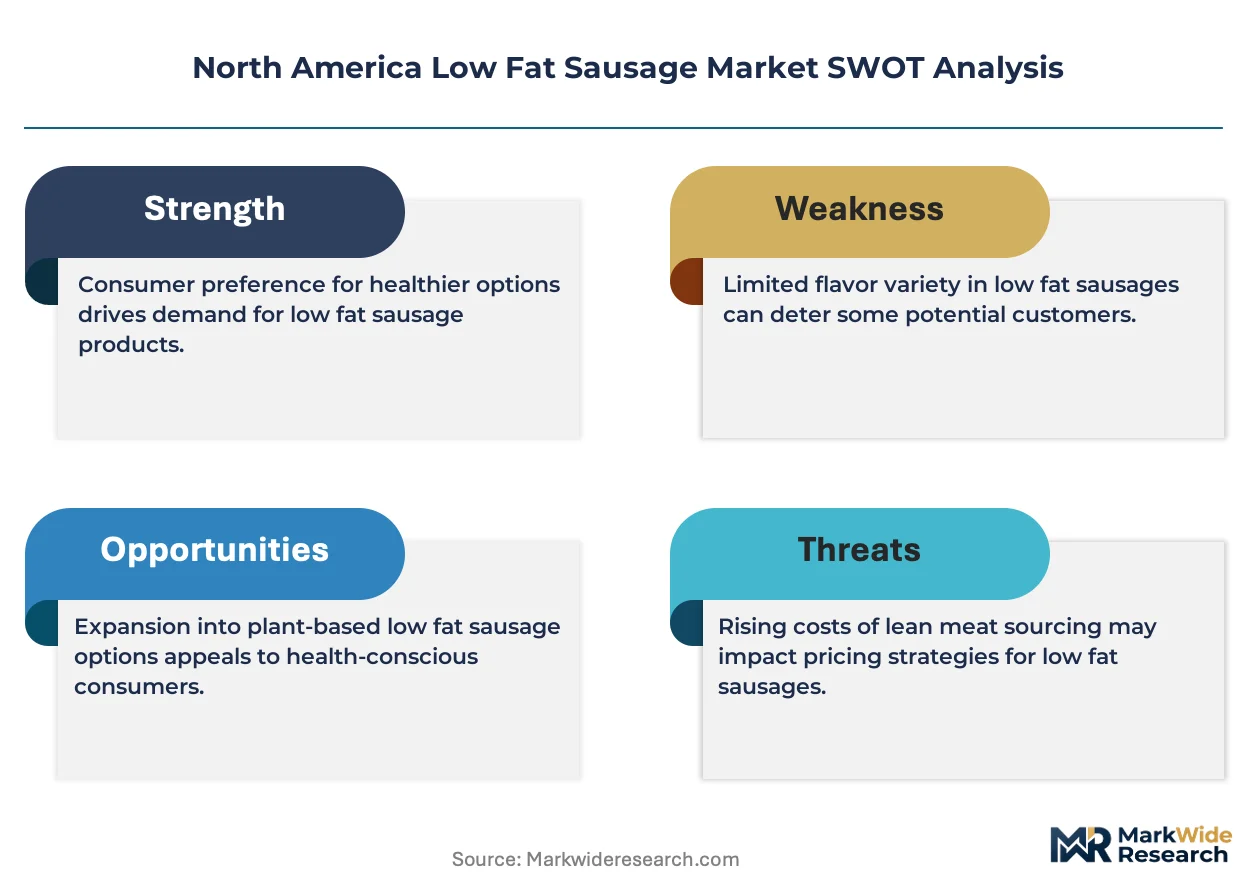
Incumbent processors face substitution defense imperatives as pea and mycoprotein breakfast alternatives capture California and Pacific Northwest retail shelf space. Plant-based protein entrants threaten to commoditize the reduced-fat positioning that once differentiated conventional sausage.
For Market Incumbents: Compound certification advantages by pre-qualifying production lines against both USDA FSIS and Health Canada standards before regulatory harmonization finalizes. Lock in multi-year lean-trim supply agreements with Minnesota-Wisconsin turkey operations to neutralize input volatility. Channel control through direct quick-service restaurant contracting in Texas and California insulates against broker displacement.
For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps in Ontario and Quebec metropolitan zones offer whitespace for direct-to-consumer poultry sausage programs with refrigerated last-mile capability. Target underpenetrated Canadian institutional foodservice where Health Canada compliance complexity deters smaller US competitors. Go-to-market leverage through Amazon Fresh partnership bypasses traditional retail slotting fee barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated processors with captive lean-muscle supply and cross-border certification infrastructure. Long-term viability over the next decade hinges on dual-compliance capability as regulatory harmonization proceeds. Acquisition targets should demonstrate established USDA Process Verified claims and Minnesota-Wisconsin R&D proximity. The signal to monitor is Health Canada saturated fat threshold alignment with US standards as inflection catalyst.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Process Verified Certification Investment | Pre-qualification against dual US-Canada standards reduces cross-border compliance costs for Ontario and Quebec expansion. |
| Direct-to-Consumer Cold-Chain Buildout | Refrigerated fulfillment networks at Amazon Fresh and specialized platforms decompose supermarket gatekeeper power. |
| Backward Integration into Lean-Trim Supply | Captive turkey operations in Minnesota-Wisconsin clusters neutralize 90/10 pork input volatility from sow herd contraction. |
| Hydrocolloid R&D Facility Expansion | Fat-mimicking formulation expertise concentration in Midwest processing corridors accelerates reduced-fat texture parity timelines. |
| Quick-Service Restaurant Direct Contracting | Consolidated supplier relationships with Texas and California operators displace traditional meat broker intermediaries. |
Research Methodology
A standing panel of protein procurement directors at multi-unit restaurant chains, USDA FSIS compliance officers, cold-chain logistics specialists, and private-label category managers at Kroger and Loblaws provided ongoing calibration throughout the study period. Primary interview data triangulated against secondary sources including USDA FSIS inspection protocol filings, Health Canada processed meat labeling standards, SEC 10-K disclosures from diversified protein conglomerates, and Nielsen retail audit data for reduced-fat meat categories. Bottom-up volume modeling from processor capacity and top-down demand validation from foodservice procurement trends converged on segment-level estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning protein source, distribution channel, end-user application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year market sizing adjusted for documented capacity additions and procurement contract volumes. Industry-specific forecast inputs incorporated sow herd cycle projections and quick-service restaurant menu expansion plans for all-day breakfast.
Forecasts assume regulatory continuity in USDA FSIS inspection protocols and Health Canada saturated fat thresholds; material policy shifts would require re-modeling of certification timelines and cross-border product qualification. Specific risk factors include simultaneous sodium-reduction mandate implementation and plant-based protein substitution acceleration. Practitioners should keep alternative scenarios live as regulatory harmonization negotiations and alternative protein cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Blended Meat Market
Meat Products
Chilled Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Germany Meat Products Market
Meat Products
Kosher Beef Market
Meat Products
Smokehouse Market
Meat Products
Poultry Processing Meat Market
Meat Products
Meat Flavors Market
Meat Products
Meat Emulsions Market
Meat Products
Organic Meat Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Brisket Market
Meat Products
Global Red Meat Market
Meat Products
Sausage Premixes Market