
 Smokehouse Market | 2026-2036
Smokehouse Market Size, Share, and Industry Trends Forecast 2026-2036
Smokehouse Market Intelligence
The integration of IoT-enabled sensors and automated controls for precision smoking is tilting the market towards industrial-grade equipment. Fessmann GmbH and Co KG leverages its expertise in large-scale systems for food processors. Alkar-RapidPak, Inc. specializes in continuous thermal processing solutions for high-volume production. Traeger Grills competes in the prosumer and high-end household segment with its wood pellet technology.
A smokehouse is an apparatus for curing food like meat, fish, and cheese through controlled exposure to smoke. The process imparts flavor and preserves food, requiring precise management of temperature, humidity, and smoke density from specific wood sources. Smoked meats and fish represent the largest product segments by revenue. The food service end-user category, encompassing restaurants and catering, is expanding rapidly, driving sales of commercial-grade units.
Food safety regulations from the USDA in the United States and the EFSA in Europe mandate strict hygiene and processing protocols. These rules govern allowable wood types and pathogen control, influencing equipment design. Future competitive positioning will be determined by the ability to deliver consistent product quality. Stakeholders must also navigate consumer preferences for natural ingredients and transparent processing.
Market Dynamics
The convergence of stringent food safety mandates and the adoption of IoT-enabled automation defines the smokehouse market. Pressure from regulators like the USDA and EFSA for verifiable pathogen control and process consistency is accelerating the shift toward industrial-grade, data-driven systems.
Growth Catalysts
- Food Service Expansion:The catering services and quick-service restaurant sectors demand high-volume, repeatable food preparation, driving sales of commercial-grade automated smokehouses that ensure product uniformity.
- Process Automation:Adoption of IoT sensors for real-time monitoring of temperature, humidity, and smoke density allows processors to optimize yields, reduce energy consumption, and improve product consistency.
- Processed Meat Demand:Sustained consumer appetite for smoked meats in established culinary centers, particularly within Germany and the United States, underpins baseline demand for large-scale processing equipment.
Market Restraints
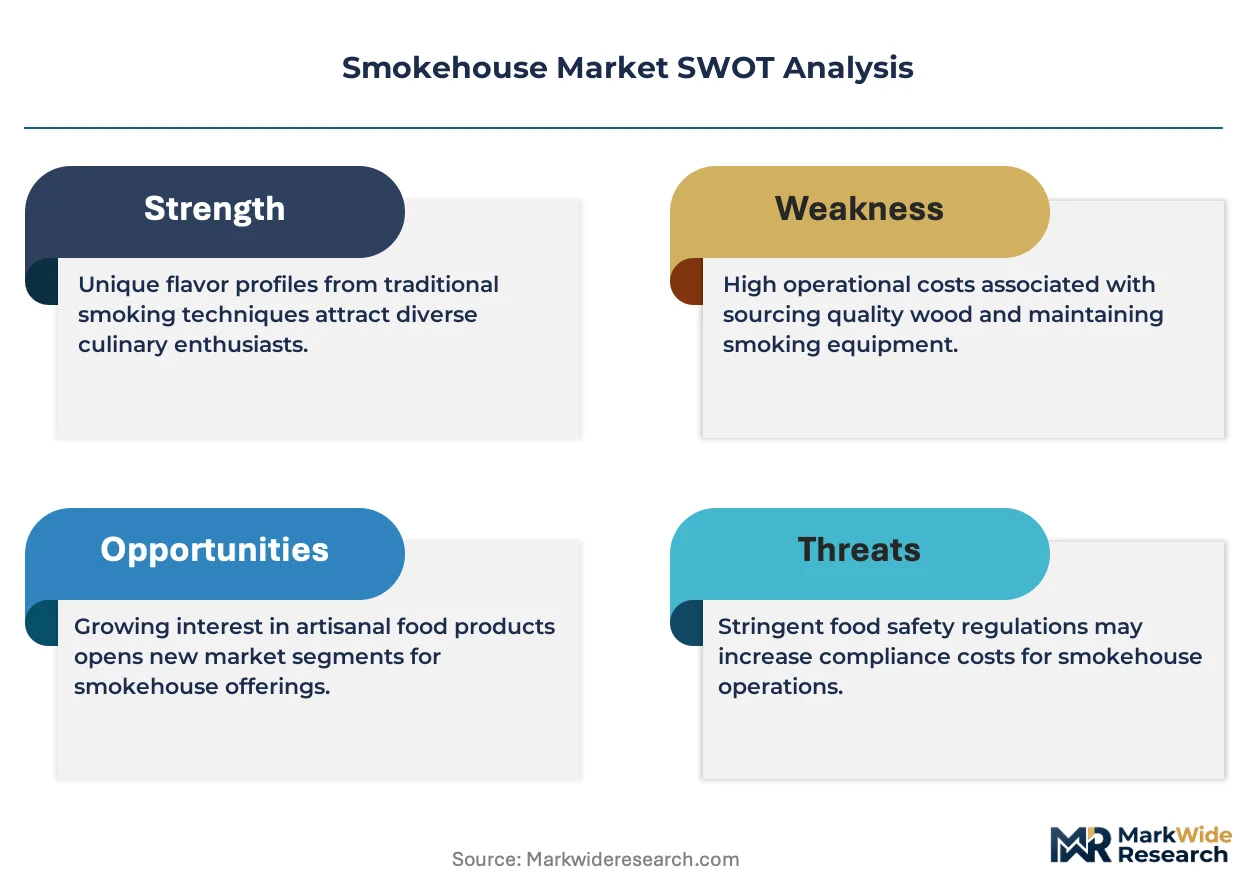
- Capital Intensity:The significant upfront investment required for industrial-grade, automated smoking systems with integrated environmental controls presents a substantial barrier for small and medium-sized enterprises.
- Wood Supply Volatility:Fluctuations in the price and availability of specific wood types, such as hickory and applewood, which are required for authentic flavor profiles, create input cost instability for processors.
- Regulatory Scrutiny:Strict EFSA limits on polycyclic aromatic hydrocarbons (PAHs) in foodstuffs require complex smoke generation and filtration technologies, increasing equipment cost and operational complexity.
Strategic Opportunities
- Plant-Based Applications:Applying smoking technology to plant-based alternatives, such as tofu, tempeh, and vegan cheeses, opens a new and expanding customer segment seeking complex flavor profiles.
- Clean Smoke Technology:Development of purified liquid smoke and advanced smoke generation systems that minimize harmful compounds offers a path to meet stricter health regulations and appeal to health-conscious consumers.
- Geographic Expansion:Entry into markets in Southeast Asia and Latin America, where disposable incomes and demand for diverse processed foods are increasing, presents significant growth potential for equipment suppliers.
Industry Challenges
- Skilled Technician Scarcity:A shortage of operators and maintenance personnel with the dual expertise in traditional food science and modern IoT-based automation systems hinders efficient plant operation.
- Compliance Fragmentation:Manufacturers must navigate divergent food safety and equipment certification standards between key markets, such as differing pathogen control protocols from the USDA and EFSA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smokehouse Market |
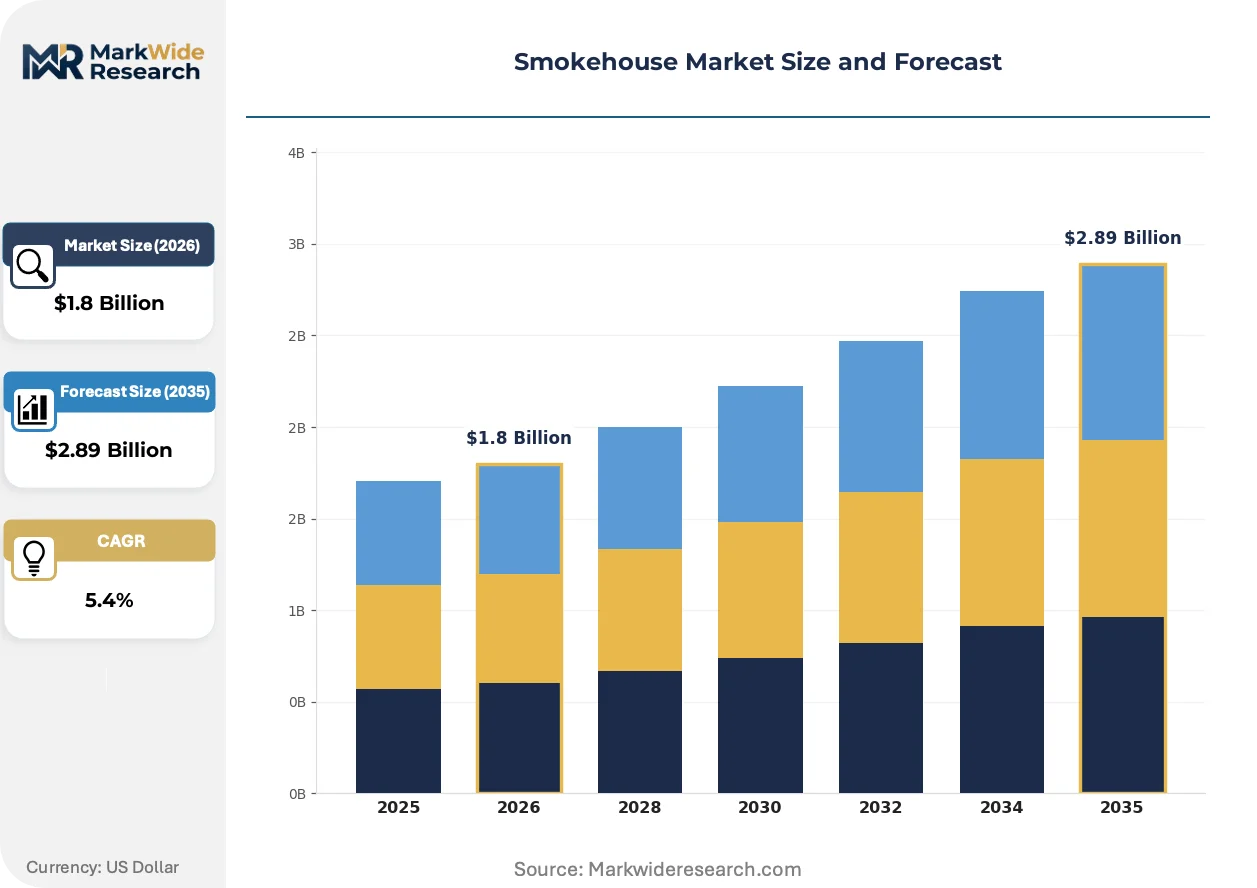
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smoked Sausages, Smoked Fish, Smoked Cheeses, Smoked Meats Distribution Channel: Retail Stores, Online Stores, Food Distributors, Farmers Markets End User: Restaurants, Food Service, Households, Catering Services Packaging Type: Vacuum Packs, Cans, Jars, Pouches |
| Companies Covered | Char-Broil LLC, Afoheat, Masterbuilt Manufacturing, LLC, Camp Chef, Weber-Stephen Products LLC, Bradley Smoker, Alkar-RapidPak, Inc., Fessmann GmbH and Co KG, Traeger Grills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smokehouse Market Strategic Shifts & Innovations
Industrialization of an artisanal craft is the central theme transforming the smokehouse market. The push for scientific precision, verifiable safety, and operational efficiency is fundamentally altering equipment design, with automation and data analytics becoming standard features rather than options.
Digital twin technology creates a complete software model of the physical smokehouse and its thermal processes. Large-scale food processors are adopting this to simulate smoking cycles, predict flavor development, and test new recipes without costly physical trials. This approach is virtualizing the product development and quality control process, reducing ingredient waste and accelerating time-to-market.
European Union regulations under the EFSA are tightening controls on contaminants like polycyclic aromatic hydrocarbons (PAHs) found in traditional wood smoke. This is forcing equipment manufacturers to integrate advanced filtration and smoke generation systems that produce cleaner, more consistent smoke for industrial use. The meat and fish processing segments are most affected, now prioritizing equipment that can document compliance with these stringent European food safety standards.
A demand-side shift toward verifiable food provenance and "clean label" ingredients is altering procurement criteria for smoking equipment. Food service buyers and processors are increasingly prioritizing systems that use certified, natural wood sources over those reliant on artificial smoke flavors. This preference is most visible within the premium retail and high-end restaurant segments in North America and Western Europe, where transparency is a key brand differentiator.
Smokehouse Market Segmentation
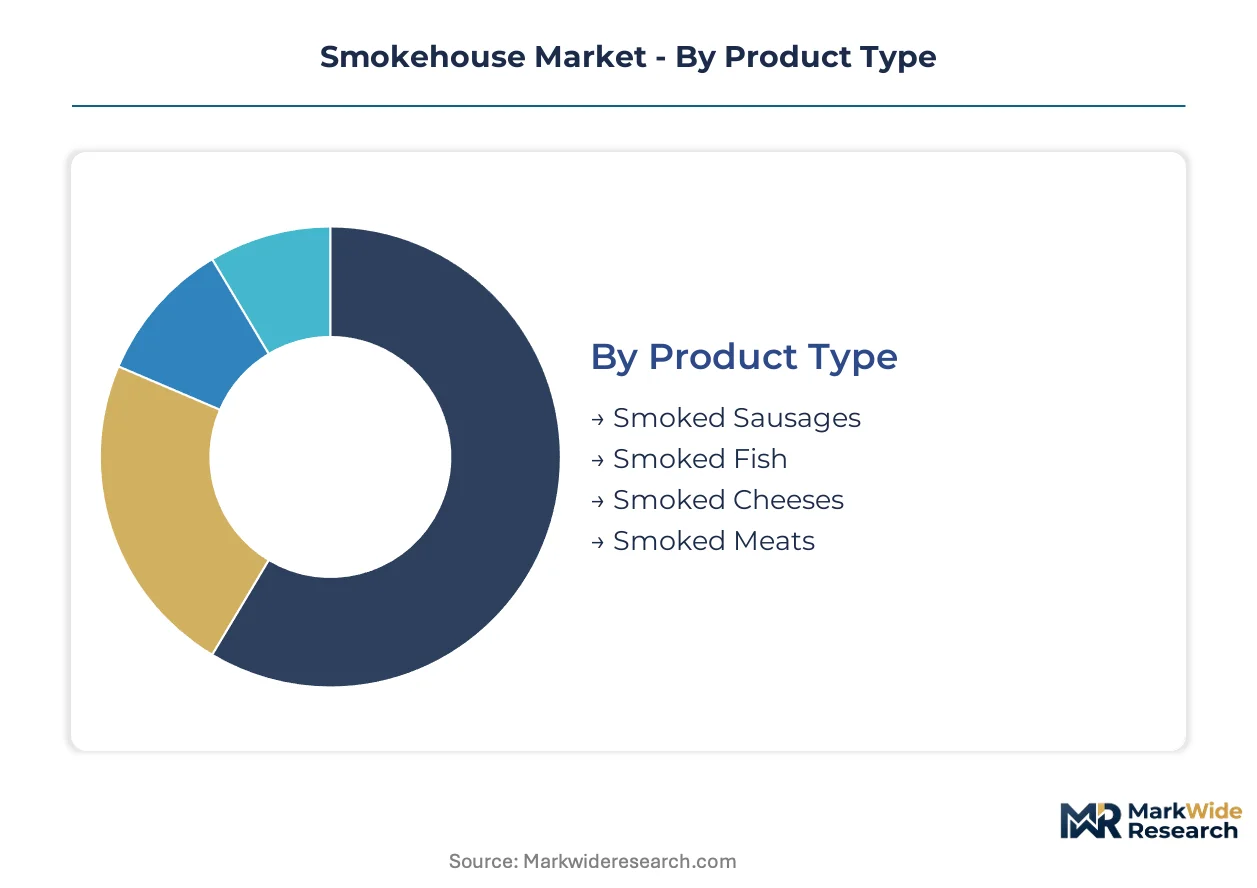
The smokehouse market exhibits diverse segmentation, reflecting varied product forms, distribution strategies, end-user requirements, and packaging preferences. Understanding these distinct segments is crucial for stakeholders to tailor equipment design, optimize supply chains, and target specific consumer or commercial niches effectively.
Product Type:
After-sales service intensity for smokehouse equipment varies significantly across product types, driven by the differing processing complexities and regulatory scrutiny each category demands.
- Smoked Meats:This segment includes a wide array of cured and smoked animal proteins, such as bacon, ham, and jerky, requiring precise temperature and smoke density control for consistent flavor and texture. Demand is particularly strong in Germany and the United States, where established culinary traditions and high consumption rates drive continuous industrial-scale production.
- Smoked Fish:Encompassing products like smoked salmon, mackerel, and trout, this category demands specialized equipment for delicate handling and often lower smoking temperatures to preserve texture and moisture. European markets, especially those with coastal traditions, exhibit robust demand for high-quality smoked fish products, influencing equipment specifications for precise humidity management.
- Smoked Sausages:This segment involves smoking various sausage formulations, which often requires specific wood types and longer smoking durations to develop characteristic flavors and extend shelf life. Quick-service restaurants and prepared meal manufacturers represent significant end-users.
- Smoked Cheeses:Specialty cheeses infused with smoke flavor, ranging from cheddar to gouda, cater to gourmet and deli markets. Equipment for this segment focuses on gentle smoking processes to avoid melting or altering the cheese's core structure.
Smoked Meats holds the largest share; momentum sits with Smoked Fish.
Distribution Channel:
Distribution channels for smoked products are influenced by volume requirements and the need for controlled environment logistics to maintain product integrity and shelf life.
- Food Distributors:These entities manage large-volume logistics, supplying smoked products to restaurants, catering services, and institutional buyers, requiring efficient cold chain management and bulk packaging solutions. Demand from large food service chains in major culinary centers drives significant procurement through this channel.
- Retail Stores:Supermarkets, hypermarkets, and specialty food stores offer smoked products directly to consumers, necessitating attractive packaging and a consistent supply of various product types. Consumer preferences for convenience and ready-to-eat options in North America and Western Europe bolster sales through this channel.
- Online Stores:E-commerce platforms provide direct-to-consumer access for specialty or niche smoked products, often catering to consumers seeking unique flavors or artisanal brands. This channel benefits from expanding digital infrastructure and consumer comfort with online grocery shopping.
- Farmers Markets:Local and artisanal producers often sell smoked goods directly to consumers through farmers markets, emphasizing fresh, locally sourced ingredients and traditional smoking methods. This channel caters to consumer demand for transparent provenance.
Food Distributors account for the largest volume; Online Stores are climbing the fastest.
End User:
The application of smoked products across various end-user categories dictates equipment scale, automation levels, and the versatility required for different product outputs.
- Catering Services:This sector demands high-volume, consistent output of smoked meats, fish, and cheeses for events and large-scale meal preparation, driving the need for industrial-grade automated smokehouses. The expansion of corporate and event catering services in urban centers fuels this segment's growth.
- Food Service:Encompassing a broad range of commercial kitchens, including institutional dining and cafeterias, this segment requires reliable, efficient smoking solutions to produce menu items consistently. Rapid expansion in quick-service restaurant chains contributes significantly to equipment sales.
- Households:Individual consumers purchase smoked products for home consumption, ranging from pre-packaged items to specialty cuts from delis. This segment is driven by convenience and the desire for diverse meal options.
- Restaurants:Fine dining and casual eateries utilize smoked ingredients for flavor enhancement and menu differentiation, often requiring smaller, more specialized smoking units for artisanal preparation. Culinary innovation in major cities worldwide influences this segment.
Food Service holds the largest market share; Catering Services is gaining share fastest.
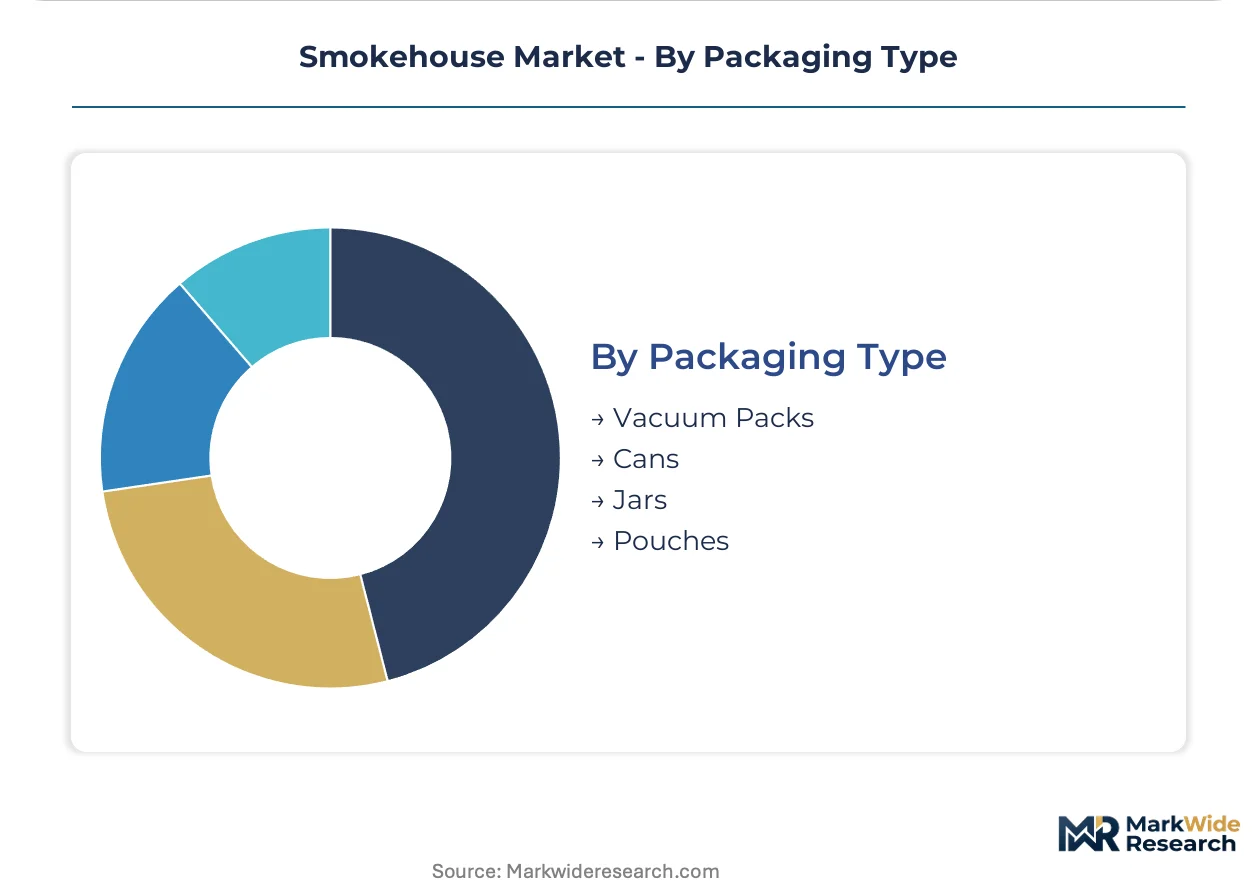
Packaging Type:
The cost tier of smoked products is often influenced by the packaging type, which impacts shelf life, presentation, and distribution efficiency.
- Vacuum Packs:This packaging method removes air to extend shelf life and preserve freshness, commonly used for sliced meats and fish, providing a cost-effective solution for retail and food service. Consumer preference for extended freshness and visible product quality drives its widespread use.
- Cans:Used for long-term preservation of smoked fish and some meats, cans offer robust protection and extended shelf stability without refrigeration before opening. This method is prevalent in regions with long supply chains or emergency food provisions.
- Jars:Often employed for specialty smoked products like fish spreads, pates, or gourmet cheeses, jars provide an attractive presentation and good shelf life, appealing to premium segments. This packaging type emphasizes product visibility and perceived quality.
- Pouches:Flexible pouches are gaining traction for their convenience, reduced material usage, and lighter weight, suitable for ready-to-eat smoked snacks or smaller portions. This packaging type aligns with on-the-go consumption trends.
Vacuum Packs account for the largest share; Pouches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade flow of smokehouse equipment and processed products from established European manufacturers to global culinary centers defines regional dynamics. Germany and the United States represent significant demand hubs, driving innovation in industrial-grade smoking technology. Future growth corridors are emerging in developing economies.
Germany
German demand for smoked meats, particularly sausages, drives high-volume industrial smokehouse equipment sales. EFSA limits on polycyclic aromatic hydrocarbons (PAHs) influence equipment design for cleaner smoke generation. Food processing hubs around Bavaria and North Rhine-Westphalia focus on advanced automation for consistent product quality.
United States
Consumer appetite for bacon, ham, and jerky sustains substantial demand for large-scale smokehouse operations. USDA food safety regulations mandate strict hygiene and pathogen control, impacting equipment design and processing protocols. Major culinary centers like Chicago and New York City concentrate food service and catering demand for smoked products.
United Kingdom
British consumers exhibit strong preferences for smoked fish and premium deli meats, stimulating demand for specialized smoking units. EFSA directives on food contaminants shape equipment procurement, favoring systems with advanced filtration capabilities. London's vibrant food service sector and retail chains drive consistent orders for diverse smoked product offerings.
Canada
Canadian food service expansion and household consumption of smoked products create a steady market for both commercial and prosumer smokehouses. Health Canada regulations, aligning with international food safety standards, influence equipment certification and operational practices. Food processing facilities in Ontario and Quebec invest in automated systems to meet production efficiency goals.
Brazil
Brazilian demand for processed meats is increasing with rising disposable incomes and urbanization, opening new avenues for smokehouse technology. ANVISA food safety standards guide equipment suppliers in ensuring compliance for local food processors. São Paulo's large metropolitan area and surrounding agricultural regions are developing modern processing plants for smoked goods.
Smokehouse Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing industrial-scale manufacturers, specialized continuous thermal processing providers, and prosumer-focused brands. Industrial equipment suppliers like Fessmann GmbH cater to large food processors, while Alkar-RapidPak, Inc. targets high-volume production. Traeger Grills competes in the premium household segment, emphasizing wood pellet technology. Competitive moves center on technology licensing for automation and capacity expansion to meet growing food service demand.
At the scale-driven end, Fessmann GmbH and Co KG exemplifies a European manufacturer specializing in large-scale systems for industrial food processors. Alkar-RapidPak, Inc., a US-based entity, occupies a position focused on continuous thermal processing solutions for high-volume production. In contrast, Traeger Grills represents the prosumer and high-end household segment, anchoring its offerings around wood pellet technology and home-use applications. These companies collectively illustrate the diverse market needs, from industrial automation to consumer-grade precision smoking.
| Leading Market Players |
|---|
| Char-Broil LLC |
| Afoheat |
| Masterbuilt Manufacturing, LLC |
| Camp Chef |
| Weber-Stephen Products LLC |
| Bradley Smoker |
| Alkar-RapidPak, Inc. |
| Fessmann GmbH and Co KG |
| Traeger Grills |
| Others |
Cost & Logistics Intelligence
German precision engineering for industrial smokehouse equipment, combined with specialized component suppliers, concentrates margin pools within advanced automation and after-sales service providers. This upstream concentration dictates equipment availability and pricing for large-scale food processors.
Pricing Analysis
The pricing gap between automated, industrial-grade smokehouses and basic prosumer units remains substantial, reflecting technology integration and compliance costs. Pricing predominantly follows a value-based model, where equipment cost is justified by enhanced product consistency and regulatory adherence. Price differentiation stems from the level of automation integration and the extent of after-sales service bundling. Pricing pressure intensifies on entry-level commercial units due to increased competition from Asian manufacturers. Food service operators exhibit higher price sensitivity compared to large industrial processors seeking long-term operational efficiency.
Supply Chain Analysis
Extended payment terms for industrial smokehouse equipment and specialized financing facilities for large projects define supplier-customer relationships. Geographic supply concentration for advanced smoking systems centers in Germany and the United States, home to major equipment manufacturers. Raw material dependencies include specific wood types like hickory and applewood, crucial for authentic flavor profiles, and specialized IoT sensors for precision control. Wood supply volatility represents a structural risk for processors, impacting input costs. Downstream distribution runs primarily through specialized food equipment distributors managing installation and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smokehouse market presents a significant service-attach opportunity, with recurring revenue from maintenance contracts and software subscriptions expanding faster than initial hardware sales. This trend underscores the importance of long-term customer relationships.
For Market Incumbents: Insulate core market share by deepening vertical integration into specialized component manufacturing, particularly for advanced filtration and IoT control systems. This strategy counters emerging competition from lower-cost manufacturers and mitigates supply chain risks associated with critical components. Invest in R&D for next-generation clean smoke technology to stay ahead of tightening EFSA regulations on PAHs. For New Entrants and Emerging Players: The plant-based applications segment represents the most penetrable entry point, targeting manufacturers of vegan cheeses and alternative proteins. Developing compact, energy-efficient smoking units specifically designed for these novel applications offers a clear differentiation strategy. A go-to-market angle focusing on customization and rapid recipe development support can attract innovative food startups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized equipment manufacturers specializing in continuous thermal processing or niche wood smoking technologies. These firms often possess strong intellectual property in specific smoke generation or filtration methods. Investors should target companies with robust after-sales service networks and high recurring revenue from maintenance contracts, signaling long-term customer stickiness. Watch for increasing patent activity in purified liquid smoke technologies as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Twin Technology | Simulates smoking cycles, predicts flavor, and accelerates recipe development for large food processors. |
| Develop Plant-Based Smoking Solutions | Captures a rapidly expanding customer segment seeking complex flavor profiles in alternative proteins. |
| Expand Geographic Presence in Southeast Asia | Addresses increasing demand for diverse processed foods fueled by rising disposable incomes. |
| Integrate Advanced Filtration Systems | Ensures compliance with stringent European food safety regulations regarding polycyclic aromatic hydrocarbons. |
| Strengthen After-Sales Service Networks | Builds customer loyalty and generates recurring revenue from maintenance and software subscriptions. |
Research Approach
The analysis maps industrial, commercial, and prosumer smokehouse sub-sectors, each validated through primary interviews with food processors, catering managers, and equipment engineers. Secondary data sources, including USDA and EFSA regulatory reports, trade association publications, and patent filings, provided essential market context. This approach utilized both bottom-up and top-down triangulation to ensure data accuracy and comprehensive coverage.
Assumptions regarding sustained consumer demand for smoked products and continued regulatory pressure for food safety were held fixed across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user category, packaging format, and regional demand dynamics. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates of automation technologies. Key forecast inputs included processed meat consumption trends and industrial automation adoption rates in food manufacturing.
Practitioners should monitor shifts in wood supply chain stability or significant changes in global food safety regulations for early signals. Forecasts reflect documented assumptions and industry trends over the projection horizon. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Edible Meat Market
Meat Products
Meat Paste Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Ham Slicers Market
Meat Products
United States Frozen Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Organic Lamb Market
Meat Products
Reduced Fat Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
North America Canned Meat Market
Meat Products
Organic Eggs Market
Meat Products
Europe Bacon Market
Meat Products
Meat Packaging Market