
 Chilled Meat Market | 2026-2036
Chilled Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Meat Market Analysis
Subscription-based cold-chain monitoring services is decoupling equipment ownership from temperature compliance accountability in the chilled meat trade. Tyson Foods leverages vertical integration across feedlots and processing plants to sustain margin capture from live animal to case-ready product. JBS S.A. anchors South American supply through its Brazilian beef complex, while Cargill competes via specialized protein solutions for North American foodservice accounts.
Chilled meat denotes fresh animal protein maintained at 0°C to 4°C without freezing, preserving myofibrillar texture and minimizing drip loss through controlled pH decline post-slaughter. Poultry leads volume within product type segmentation due to shorter production cycles and lower feed conversion ratios, while beef commands premium positioning in specialty stores and high-end foodservice. Modified atmosphere packaging extends retail shelf life through oxygen-scavenging films, and vacuum packs dominate foodservice channels where back-of-house handling intervals compress.
USDA FSIS inspection protocols and HACCP mandates govern slaughter and fabrication standards in the United States, while EFSA microbiological criteria shape EU market access thresholds for chilled poultry and pork. Brazil's MAPA export certification requirements and China's GB standards for imported chilled beef create layered compliance burdens that filter supplier eligibility. Stakeholders must monitor evolving cold-chain digitization mandates and carbon-accounting disclosures that will reshape procurement criteria and facility capital allocation across major producing regions.
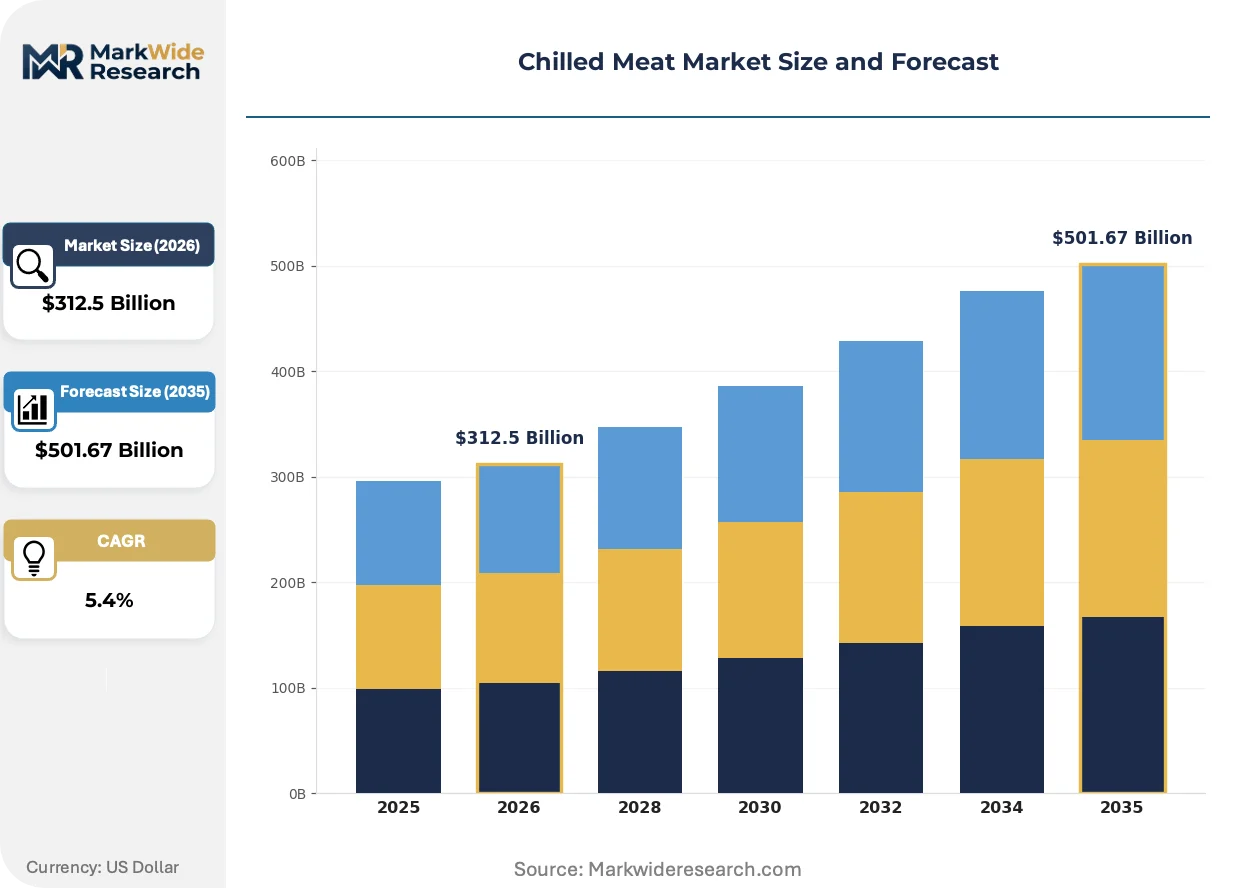
Market Dynamics
Cold-chain digitization mandates from USDA and EFSA are forcing processors to retrofit legacy facilities with real-time temperature logging and blockchain traceability, compressing margins for mid-tier operators while advantaging capital-rich integrators.
Growth Catalysts
- EU Green Deal carbon-accounting rules:The CSRD disclosure requirements for Scope 3 emissions are pressuring retailers to source from chilled-meat suppliers with verified low-carbon cold chains, redirecting procurement toward certified Brazilian and German clusters.
- Foodservice portion-control demand:North American restaurant chains are expanding case-ready chilled programs to reduce back-of-house labor and waste, pulling volume through specialized fabrication facilities.
- Modified atmosphere packaging:Oxygen-scavenging film technologies are extending retail shelf life for premium beef cuts, enabling wider distribution radii from centralized processing plants.
Market Restraints
- Feed input volatility:Corn and soybean price swings in the US Midwest and Brazil's Cerrado directly compress live-animal-to-meat margins, exposing non-integrated processors to margin calls.
- Brazilian supply concentration:JBS S.A. and Minerva Foods control disproportionate export-certified slaughter capacity, creating bottleneck risk for global chilled-beef availability.
- Freezer substitution at retail:Frozen private-label proteins continue absorbing price-sensitive demand in Germany and UK discount channels, capping chilled volume expansion.
Strategic Opportunities
- Underpenetrated Chinese premium chilled beef:GB standards for imported chilled product remain restrictive but are gradually harmonizing with Codex Alimentarius, opening pathways for certified Australian and US suppliers.
- Subscription cold-chain monitoring:IoT-as-a-service models are decoupling temperature compliance from capital ownership, lowering entry barriers for regional processors.
- EU F-Gas Regulation phase-down:The transition to CO2 and ammonia refrigeration systems is creating retrofit demand and first-mover advantage for engineering contractors.
Industry Challenges
- HACCP auditor scarcity:USDA FSIS-certified veterinarians and EUROPA-approved third-party auditors command premium fees, stretching compliance timelines for mid-cap facilities.
- Legacy ERP integration:Cold-chain digitization platforms must interface with decades-old slaughter-floor data systems, inflating implementation costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Meat Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $501.67 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Lamb, Poultry Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice End User: Households, Restaurants, Catering Services, Food Manufacturers Packaging Type: Vacuum Packs, Tray Packs, Modified Atmosphere Packaging, Others |
| Companies Covered | Tyson Foods, Inc., JBS S.A., Cargill, Inc., WH Group Limited, Hormel Foods Corp., BRF S.A., Marfrig Global Foods S.A., Smithfield Foods, Inc., Maple Leaf Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Meat Market Emerging Trajectories
Active packaging and blockchain traceability are compressing the information asymmetry between slaughter floor and retail shelf, while regulatory carbon-disclosure mandates are rewiring procurement criteria across major importing blocs.
Smart labels embedded with time-temperature indicators are expanding into high-value chilled beef and lamb shipments from Australia and New Zealand. Premium retailers in Japan and South Korea are mandating their inclusion for imported chilled product. The technology is expanding into contractual specifications, with rejections triggered automatically upon threshold breaches.
EFSA's tightened microbiological criteria for Campylobacter in chilled poultry are forcing processors to accelerate pre-slaughter interventions and rapid-chilling protocols. The regulation is compressing acceptable pathogen limits, requiring capital-intensive equipment upgrades. German and Dutch integrators are responding with in-house bacteriophage treatment lines and accelerated air-chilling tunnels.
Foodservice operators are consolidating procurement through specialized protein distributors, bypassing traditional broadline wholesalers for direct plant relationships. Chilled case-ready programs are displacing commodity boxed beef in North American casual-dining chains. The shift is most visible in the US Southeast, where Tyson Foods and Cargill have established dedicated foodservice fabrication lines.
Chilled Meat Market Segmentation
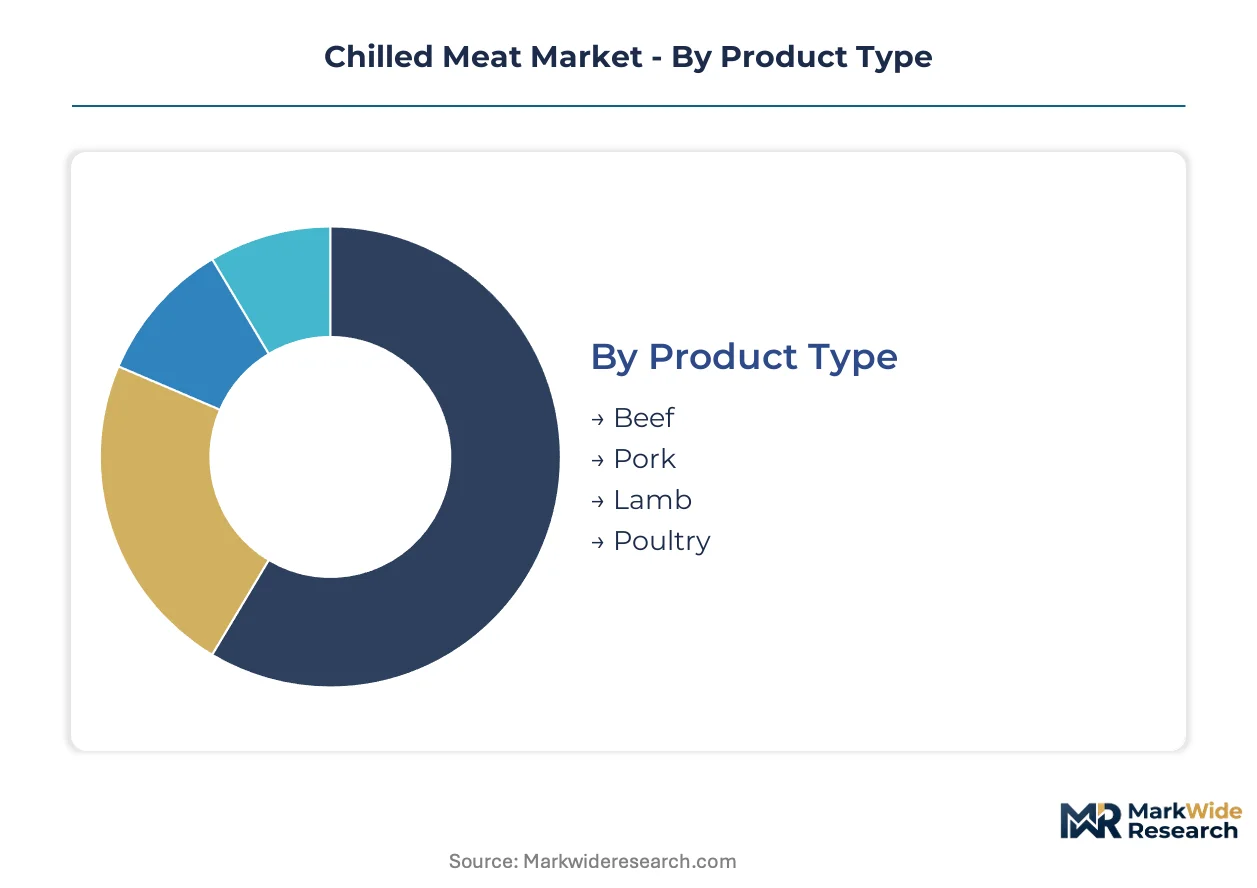
Segmentation in chilled meat reveals how temperature tolerance, shelf-life requirements, and handling intensity vary across protein categories and channel formats. Procurement patterns diverge sharply between retail case-ready programs and foodservice back-of-house specifications.
Product Type:
Biological turnover rates and myofibrillar stability create distinct cold-chain intensity tiers across animal proteins.
- Poultry:Shorter production cycles and superior feed conversion ratios concentrate volume leadership in this segment. Brazilian integrators and US Southeast processors dominate supply, with EFSA Campylobacter mandates driving rapid-chilling capital deployment in Dutch and German plants.
- Beef:Extended pH decline windows and premium positioning in specialty retail demand stricter temperature bandwidths. Australian and US suppliers target China's GB-certified import channels, while JBS S.A. anchors South American export certification through MAPA-compliant facilities.
- Pork:Intermediate cold-chain requirements serve processed-meat input demand and fresh retail cuts. German and Danish clusters specialize in high-turnover chilled distribution to Rhine-Ruhr retail networks.
- Lamb:Niche positioning in Middle Eastern and European ethnic retail channels with seasonal demand spikes. New Zealand and Australian exporters concentrate on halal-certified chilled programs for Gulf markets.
Poultry leads on scale; beef leads on momentum.
Distribution Channel:
Channel selection determines packaging format, temperature accountability, and margin capture architecture.
- Foodservice:Case-ready portion control and direct plant relationships compress handling stages. Tyson Foods and Cargill operate dedicated fabrication lines for North American casual-dining chains, eliminating broadline distributor markups.
- Supermarkets:Centralized retail distribution demands modified atmosphere packaging with oxygen-scavenging films. German discount channels absorb frozen substitution pressure, capping chilled expansion.
- Specialty Stores:Premium positioning with blockchain traceability and smart label integration. Japanese and South Korean retailers mandate time-temperature indicators for Australian chilled beef and lamb.
- Online Retail:Last-mile cold-chain accountability through subscription monitoring services. IoT-as-a-service models decouple temperature compliance from capital ownership for regional entrants.
Foodservice commands margin expansion; online retail gains share fastest.
End User:
Volume concentration and specification intensity separate institutional procurement from household consumption.
- Restaurants:Labor reduction through pre-portioned chilled programs drives North American chain adoption. Dedicated protein distributors displace traditional broadline wholesalers in procurement consolidation.
- Households:Retail case-ready formats with extended shelf life through vacuum and modified atmosphere technologies. Supermarket chilled counters in Brazil and Germany absorb dominant volume share.
- Catering Services:Event-driven demand with batch consistency requirements and HACCP documentation. EU Green Deal CSRD disclosures pressure carbon-accounting verification across supplier tiers.
- Food Manufacturers:Input-grade specifications for further processed products with less stringent temperature bandwidths. Brazilian integrated protein clusters serve this segment through captive supply arrangements.
Households anchor volume; restaurants drive specification upgrading.
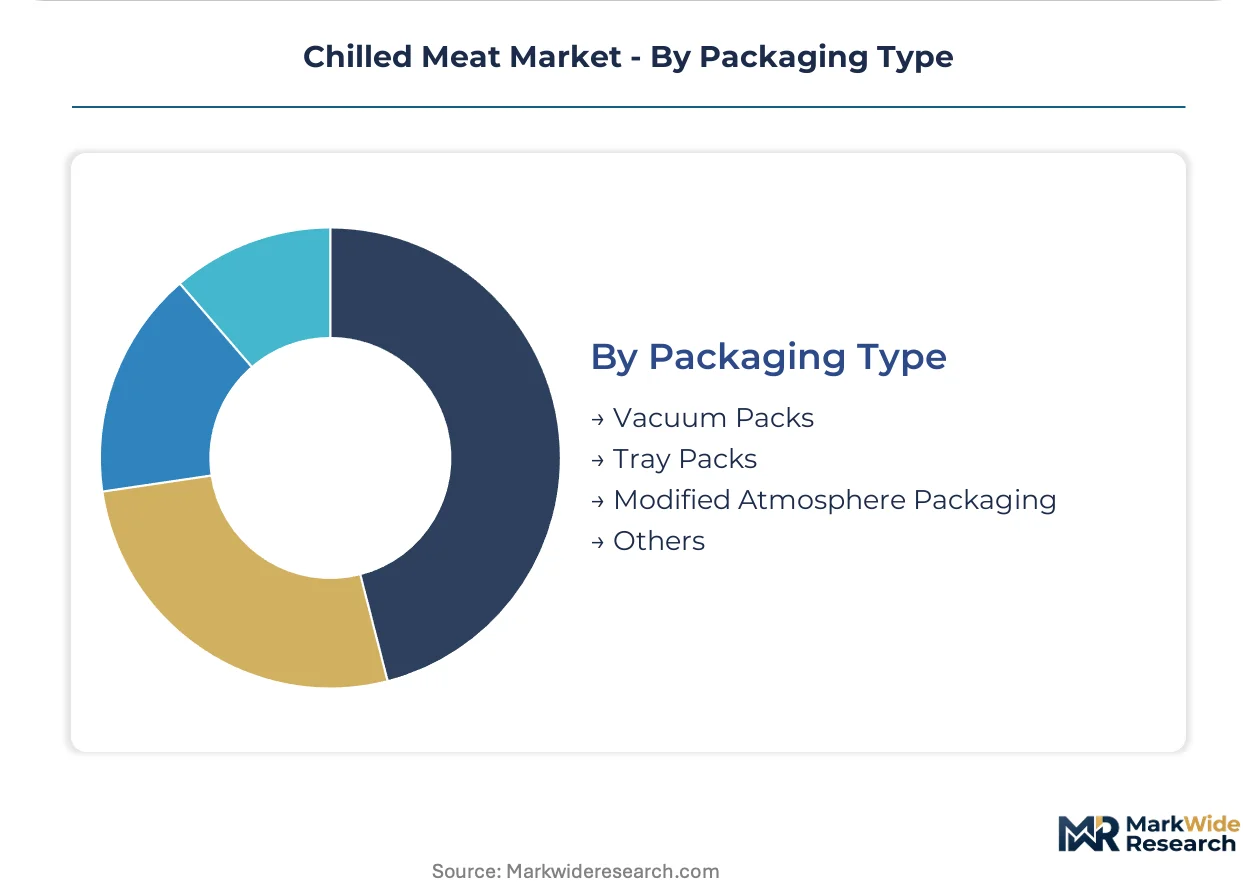
Packaging Type:
Gas composition and barrier properties define shelf-life extension and channel suitability.
- Modified Atmosphere Packaging:Oxygen-scavenging films extend retail shelf life for premium beef cuts, enabling wider distribution radii from centralized processing plants. German retailers mandate this format for chilled counter display.
- Vacuum Packs:Anaerobic environments dominate foodservice channels where back-of-house handling intervals compress. Cargill and Tyson Foods deploy this format for North American restaurant chain programs.
- Tray Packs:Overwrapped foam or fiber trays serve price-sensitive retail segments with shorter turnover requirements. UK and German discount channels favor this lower-cost format.
- Others:Active packaging with time-temperature indicators and smart labels for high-value shipments. Australian and New Zealand exporters embed these in contractual specifications for Japanese and South Korean premium retailers.
Modified atmosphere packaging leads on technology adoption; vacuum packs dominate foodservice penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting chilled-meat investment toward jurisdictions with harmonized cold-chain standards and lower compliance friction. Brazil and Australia capture capacity expansion as USDA and EFSA mandates raise facility-upgrade costs in mature markets.
United States
Foodservice chains in the Southeast are consolidating procurement through direct plant relationships, bypassing traditional broadline distributors. USDA FSIS inspection protocols and HACCP mandates govern slaughter-floor standards, compressing margins for non-integrated processors. Tyson Foods operates dedicated fabrication lines across Arkansas and Georgia, capturing margin from live animal to case-ready product.
Brazil
Integrated protein clusters in São Paulo and Mato Grosso serve export-certified chilled beef demand from China and the Middle East. MAPA export certification requirements filter supplier eligibility, advantaging capital-rich integrators with captive cold-chain infrastructure. JBS S.A. anchors South American supply through its Brazilian beef complex, controlling disproportionate export-certified slaughter capacity.
Germany
Retail-dense Rhine-Ruhr corridor supermarkets absorb dominant volume share, with discount channels capping chilled expansion through frozen private-label substitution. EFSA microbiological criteria and EU Green Deal CSRD disclosure requirements pressure Scope 3 carbon-accounting verification. Dutch and German integrators deploy accelerated air-chilling tunnels and in-house bacteriophage treatment lines to meet tightened Campylobacter limits.
China
GB standards for imported chilled beef remain restrictive but are gradually harmonizing with Codex Alimentarius, opening pathways for certified Australian and US suppliers. Premium urban households in Shanghai and Beijing drive demand for blockchain-traceable chilled product. Australian exporters embed smart labels with time-temperature indicators in contractual specifications for high-value shipments to these markets.
Australia
Halal-certified chilled lamb and beef programs target Gulf markets and East Asian premium retailers with seasonal demand spikes. Smart label integration and active packaging compress information asymmetry between slaughter floor and retail shelf. Exporters concentrate capacity in New South Wales and Victoria, where pre-slaughter interventions and rapid-chilling protocols align with Japanese and South Korean import specifications.
Chilled Meat Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with foodservice channels favoring direct plant relationships and retail consolidating through modified-atmosphere packaging suppliers. The vendor base concentrates around three strategic tiers: capital-rich integrators with captive cold-chain infrastructure, regional fabricators serving specialized distribution networks, and protein solution providers targeting institutional accounts. Dominant competitive moves include backward integration into feedlot operations and geographic expansion into underpenetrated Asian import channels.
Among North American integrators, Tyson Foods and Cargill occupy positions spanning feedlot control through case-ready fabrication, exemplifying the capital-intensive archetype that compliance mandates increasingly favor. JBS S.A. represents the export-certified South American complex, anchoring global chilled-beef availability through MAPA-compliant facilities. These three entities sit within distinct geographic clusters but converge on similar strategic imperatives: temperature accountability digitization and carbon-disclosure readiness.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| JBS S.A. |
| Cargill, Inc. |
| WH Group Limited |
| Hormel Foods Corp. |
| BRF S.A. |
| Marfrig Global Foods S.A. |
| Smithfield Foods, Inc. |
| Maple Leaf Foods |
| Others |
Supply Flow & Price Mechanics
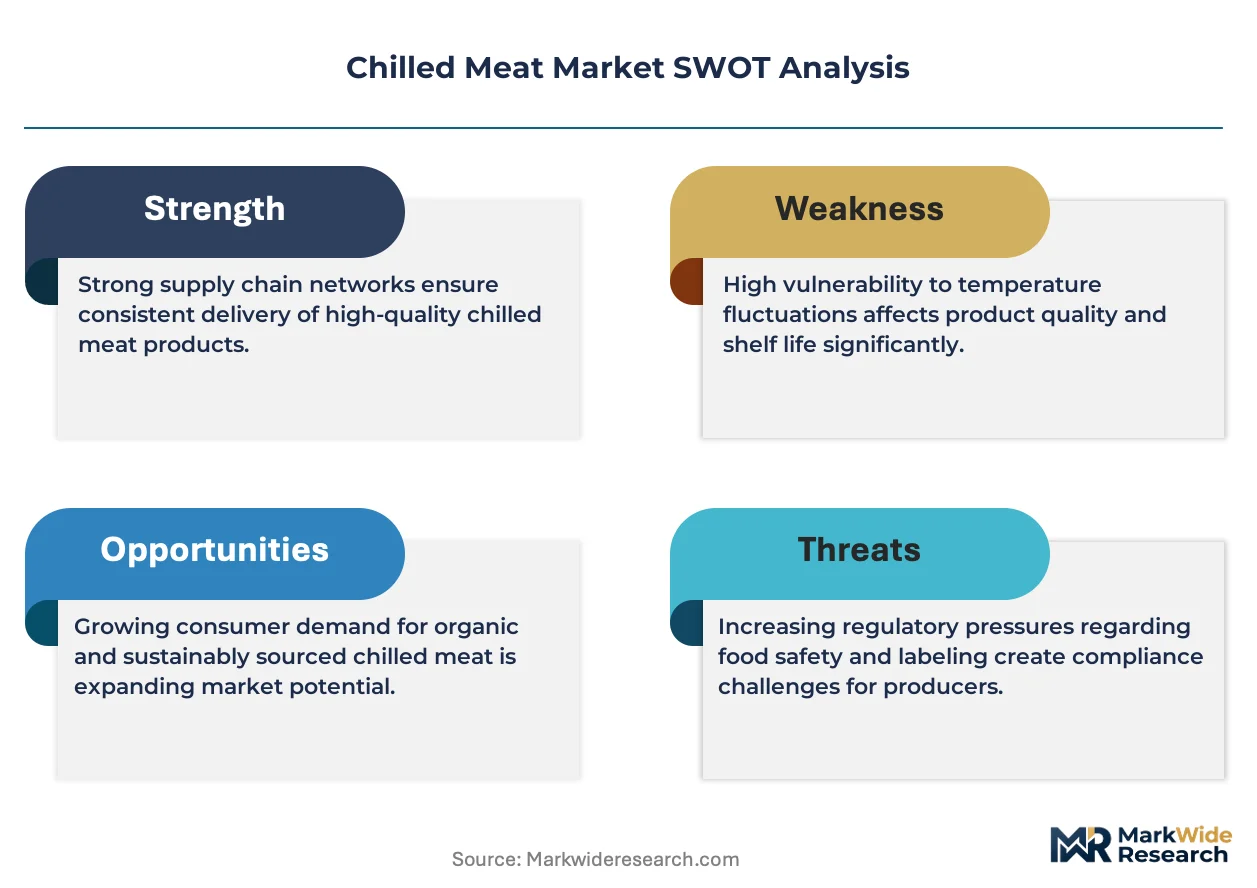
EFSA's tightened Campylobacter limits and EU Green Deal carbon-accounting mandates are forcing processors to absorb rapid-chilling equipment costs and Scope 3 verification expenses, compressing margins for non-integrated operators while advantaging capital-rich Brazilian and German clusters with captive cold-chain infrastructure.
Pricing Analysis
Foodservice direct-plant relationships eliminate broadline distributor markups that historically captured 12-18% of chilled meat value. Three-tier pricing structure across premium blockchain-traceable, standard case-ready, and economy tray-pack levels separates Australian smart-label beef from Brazilian MAPA-certified commodity cuts from German discount-channel private label. Pricing pressure stems from feed input volatility in the US Midwest and Brazil's Cerrado, with corn and soybean price swings compressing live-animal-to-meat margins. Discount retailers in Germany and the UK exhibit highest price sensitivity, while Japanese and South Korean premium retailers absorb smart-label premiums for Australian chilled beef and lamb.
Supply Chain Analysis
Feed grain supply rests on US Midwest corn belts and Brazil's Cerrado soybean complexes, with protein processors drawing from these regions for 60-70% of global feed inputs. Brazilian MAPA-certified slaughter capacity and German EFSA-compliant fabrication facilities anchor chilled meat availability, while Australian halal-certified plants serve Gulf and East Asian premium channels. Single-source vulnerability concentrates in JBS S.A. and Minerva Foods export-certified Brazilian capacity, creating bottleneck risk for global chilled-beef supply. Distribution runs through integrated protein clusters in São Paulo and Mato Grosso for export markets, with Rhine-Ruhr retail networks and US Southeast foodservice chains pulling through specialized fabrication lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's integrated protein clusters offer 15-20% cost advantages over EU facilities burdened by EFSA microbiological mandates and CSRD carbon-disclosure requirements, creating geographic-arbitrage opportunities for processors with MAPA-compliant cold-chain infrastructure.
For Market Incumbents: Anticipate margin compression from subscription-based cold-chain monitoring services decoupling temperature compliance from capital ownership, threatening equipment-leasing revenue streams. Defensive moves center on backward integration into feedlot operations in Brazil's Mato Grosso and certification investment for Chinese GB-standard harmonization. Channel control through dedicated foodservice fabrication lines in the US Southeast protects against broadline distributor disintermediation.
For New Entrants and Emerging Players: Capture underpenetrated Chinese premium chilled beef demand in Shanghai and Beijing, where GB standards are gradually harmonizing with Codex Alimentarius. The most penetrable segment is blockchain-traceable product for urban households willing to absorb smart-label premiums. Go-to-market angle leverages IoT-as-a-service cold-chain monitoring to bypass capital-intensive refrigeration infrastructure ownership.
For Investors and Strategic Acquirers: Asymmetric upside sits with Australian and US suppliers with pre-certified Chinese import pathways and existing smart-label integration for Japanese and South Korean retailers. Long-term viability favors processors with verified low-carbon cold chains and Scope 3 disclosure readiness as EU Green Deal procurement criteria harden. Watch for MAPA export certification expansions and Chinese GB-standard harmonization announcements as inflection signals for capacity reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedlot Operations | Tyson Foods and JBS S.A. control live-animal-to-case-ready margins through captive Brazilian and US Southeast supply. |
| Smart Label and Active Packaging Deployment | Australian exporters embed time-temperature indicators meeting Japanese retailer contractual specifications for premium chilled beef. |
| MAPA Export Certification Expansion | Brazilian integrators filter global chilled-beef supplier eligibility through capital-intensive cold-chain infrastructure mandates. |
| IoT Cold-Chain Monitoring as a Service | Subscription models decouple temperature compliance accountability from equipment ownership for regional processor entrants. |
| EU F-Gas Regulation Refrigeration Retrofit | Dutch and German engineering contractors capture first-mover advantage in CO2 and ammonia system transitions. |
Methodological Framework
Multiple input streams — structured interviews with protein procurement directors at North American foodservice chains, regulatory affairs leads at Brazilian MAPA-certified integrators, and cold-chain engineering specialists at Dutch and German fabrication facilities — were reconciled against trade flow databases, USDA FSIS inspection records, EFSA microbiological surveillance reports, and customs documentation of chilled meat shipments. Secondary validation drew from SEC filings of publicly traded protein processors, ANVISA export certification registries, and Chinese GB-standard harmonization notices. Bottom-up volume modeling across protein categories and distribution channels was cross-checked against top-down macroeconomic consumption indicators.
Data-stream reconciliation produced segmented forecasts across poultry, beef, pork, and lamb product types; foodservice, supermarket, specialty store, and online retail channels; and restaurant, household, catering, and food manufacturer end users. CAGRs were derived from trend extrapolation of cold-chain digitization adoption curves and carbon-accounting disclosure trajectories. Industry-specific inputs included EFSA Campylobacter limit compliance timelines, Chinese import certification pathway openings, and feed grain price volatility indices across the US Midwest and Brazil's Cerrado.
Feed input price spikes, regulatory harmonization delays in Chinese import channels, and HACCP auditor scarcity stretching compliance timelines are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about cold-chain infrastructure investment rates and carbon-disclosure mandate enforcement intensity. A small set of named triggers — MAPA certification expansion announcements, EU F-Gas Regulation phase-down acceleration, and GB-standard Codex alignment protocols — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Poultry Meat Market
Meat Products
Europe Meat Products Market
Meat Products
Organic Chicken Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Brisket Market
Meat Products
Beef Bouillon Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
3D Printed Meat Market
Meat Products
Global Poultry Meat Market
Meat Products
India Poultry Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
Emulsified Meat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
GCC Edible Meat Market
Meat Products
Europe Edible Meat Market
Meat Products
Middle East Red Meat Market