
 Sausage Premixes Market | 2026-2036
Sausage Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Sausage Premixes Market Analytics
The split between premium artisan premixes and commodity-grade industrial blends is realigning procurement patterns across the value chain. Kerry Group leverages its flavor science capabilities to dominate clean-label and reduced-sodium formulations for European processors. AC Legg anchors its position in the North American private-label segment through deep distribution into independent butcher shops and small-scale smokehouses. Corona Manufacturing competes on cost-engineered traditional spice matrices supplied to high-volume cooked sausage operations.
Sausage premixes constitute pre-blended seasoning, binder, and cure systems formulated to standardize flavor, texture, and shelf stability in emulsified or coarse-ground meat matrices, typically containing salt at 15-25% by weight plus nitrite cure accelerators where thermal processing is required. Fresh sausage premixes occupy the largest volume share due to minimal processing steps and broad retail distribution, while gluten-free and organic formulation types capture expanding margin pools as label-conscious consumers shift protein purchases. Pork-derived premixes sustain dominant demand across European and Asian processing clusters, though poultry-source blends are gaining traction in health-positioned product lines.
FDA oversight of cured meat additives under 21 CFR 170, USDA FSIS labeling mandates for species identification and allergen declaration, and EU Regulation 1169/2011 on food information to consumers collectively constrain formulation freedom while creating compliance-driven demand for validated premix suppliers. REACH chemical authorization requirements in Europe further restrict certain traditional preservative compounds, redirecting R&D spend toward rosemary-extract and cultured-celery alternatives. Stakeholders must monitor evolving nitrite-replacement pathways and regional clean-label thresholds to preserve formulation relevance without sacrificing shelf-life performance.
Market Dynamics
EU Green Deal farm-to-fork mandates are forcing accelerated reformulation across European processing clusters, compressing development cycles for reduced-sodium and phosphate-free premix architectures while artisan butcher shops simultaneously expand clean-label procurement.
Growth Catalysts
- REACH chemical authorization:Restrictions on traditional preservatives redirect R&D investment toward rosemary-extract and cultured-celery alternatives, creating validated supplier demand.
- Artisan butcher channel expansion:Specialty meat processors in Germany and France are scaling clean-label premix procurement to differentiate retail positioning.
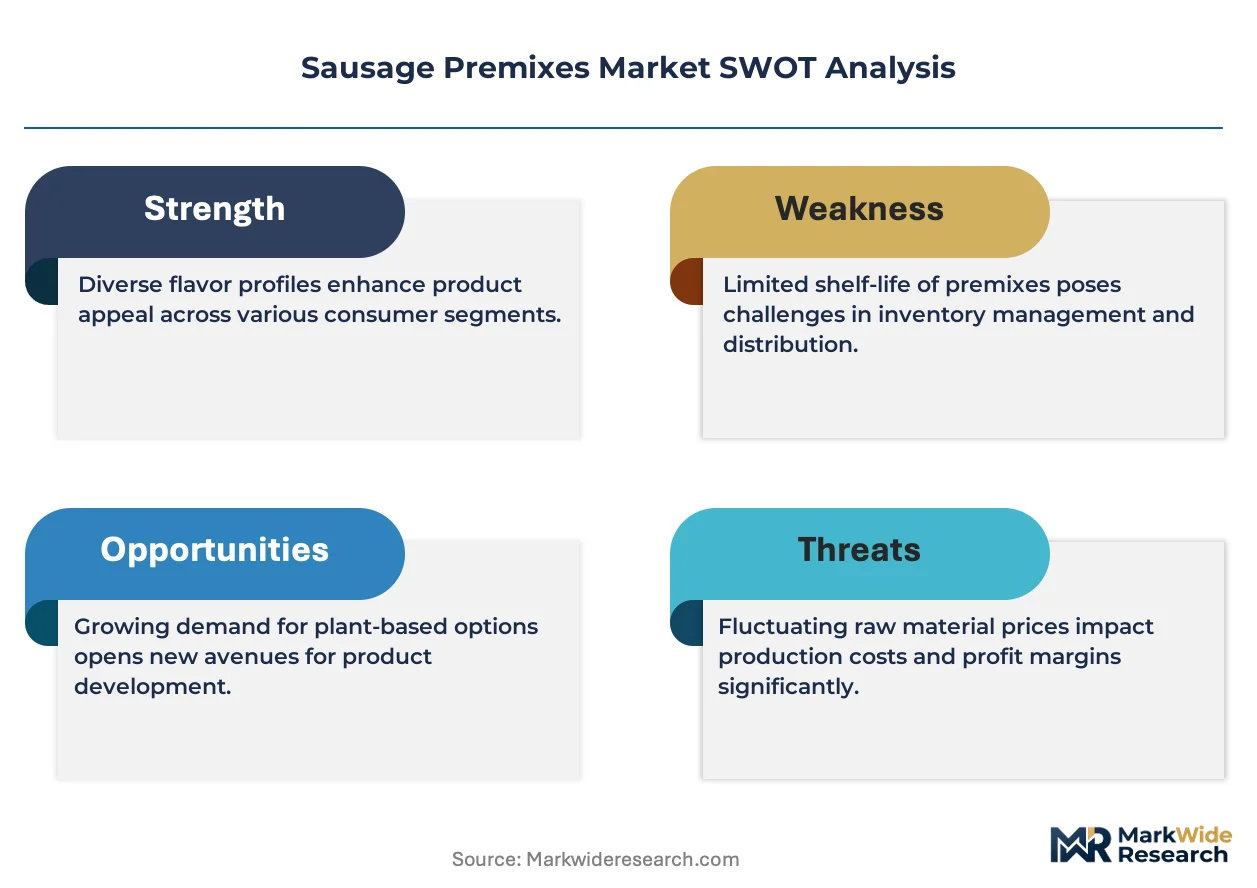
- Poultry-source formulation migration:Health-positioned product lines are displacing pork-derived matrices in premium private-label development.
Market Restraints
- Salt price volatility:Premix formulations carry 15-25% salt by weight, exposing margin structures to commodity mineral cost swings.
- Nitrite replacement technical ceiling:Shelf-life performance gaps in fully natural cure systems limit complete phosphate elimination in thermal-processed categories.
- USDA FSIS labeling complexity:Species identification and allergen declaration mandates constrain formulation freedom for multi-species processors.
Strategic Opportunities
- India FSSAI clean-label pathway:Emerging processed meat infrastructure creates first-mover positioning for validated reduced-sodium suppliers.
- Direct-to-smokehouse digital distribution:E-procurement platforms are compressing traditional ingredient distributor layers for independent butcher shops.
- EU AI Act supply-chain traceability:Automated batch documentation requirements favor premix suppliers with integrated digital validation systems.
Industry Challenges
- Flavor chemist talent scarcity:Clean-label sodium reduction without taste degradation requires specialized savory formulation expertise concentrated in European flavor houses.
- Dual certification timeline compression:Organic and gluten-free validation cycles extend product launch windows for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sausage Premixes Market |
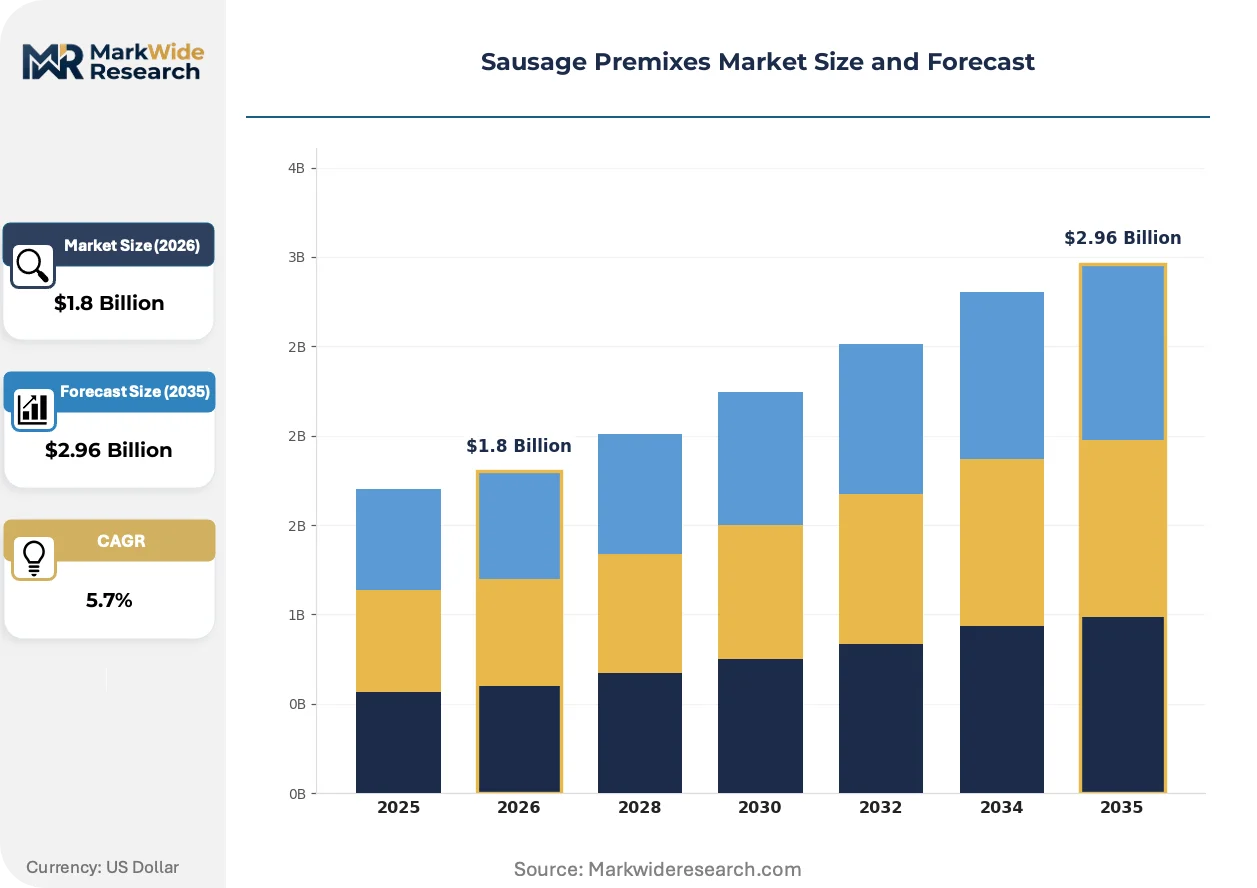
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Sausage, Cooked Sausage, Smoked Sausage, Dry Sausage Meat Source: Pork, Beef, Poultry, Lamb Flavor Profile: Spicy, Sweet, Savory, Mild Formulation Type: Traditional, Organic, Gluten-Free, Low-Fat |
| Companies Covered | The Dalesman Group, The Sausage Maker, AC Legg, Krio Krush, Corona Manufacturing, Master Butchers Co-operative Ltd, Dunninghams, Kerry Group, Newly Weds Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sausage Premixes Market Evolving Landscape
Formulation science is migrating toward bioactive preservation and precision fermentation-derived flavor precursors, compressing the gap between artisan taste profiles and industrial scale economics while regulatory chemistry restrictions accelerate.
Encapsulated salt and potassium chloride microsphere technologies are converging with traditional spice matrices to enable staged sodium release in emulsified sausages. German and Dutch processors are piloting these systems at commercial scale. The structural consequence is converging with commodity premix economics, forcing mid-tier suppliers to license flavor-house intellectual property or exit premium positioning.
EU Regulation 1169/2011 food information mandates are tightening declaration granularity for compound ingredients. Industrial consequence includes mandatory upstream documentation from premix suppliers to processors. Thermal-processed cooked sausage categories face the steepest compliance burden, redirecting procurement toward vertically integrated seasoning houses with captive analytical laboratories.
Independent butcher shops are consolidating purchasing through cooperative buying groups, displacing individual distributor relationships. These aggregators negotiate direct manufacturer contracts previously reserved for industrial volume tiers. Germany's traditional sausage culture clusters exhibit the most advanced cooperative procurement density, compressing price realization for legacy distributor-dependent suppliers.
Sausage Premixes Market Segmentation
Sausage premix formulation varies sharply across processing methods and protein matrices, with capital requirements clustering around thermal-processing equipment and clean-label validation infrastructure. Procurement patterns diverge meaningfully between commodity-volume industrial processors and specialty-scale artisan operations.
Product Type:
Capital intensity peaks in thermal-processed categories requiring controlled-humidity smoking chambers and continuous thermal processing lines, while fresh formulations demand minimal equipment beyond grinding and blending systems.
- Fresh Sausage:Minimal processing steps preserve volatile spice aromatics and require only grinding, blending, and stuffing equipment. German and French artisan butcher shops concentrate procurement here, driven by consumer preference for unaltered texture and clean-label positioning without phosphate additives.
- Cooked Sausage:Thermal processing mandates nitrite cure systems and precise temperature-humidity control for emulsion stability. High-volume operations in Germany deploy continuous cooking tunnels, with EU Green Deal sodium-reduction targets forcing reformulation investment in phosphate-free binders.
- Smoked Sausage:Smokehouse infrastructure requires substantial capital outlay for air-quality compliance and polycyclic aromatic hydrocarbon monitoring under EFSA guidelines.
- Dry Sausage:Extended aging cellars with climate-controlled humidity systems represent the highest fixed-asset commitment among premix applications.
Most installed capacity flows through Fresh Sausage. Expansion is steepest in Cooked Sausage.
Meat Source:
Raw material sourcing costs and protein functionality drive distinct premix architectures, with myofibrillar protein content determining binder requirements and water-holding capacity specifications.
- Pork:Dominant myofibrillar protein structure enables superior emulsion stability with lower phosphate inclusion. European processing clusters in Germany and Poland sustain concentrated demand, though EU animal welfare directives are compressing herd sizes and elevating input costs.
- Poultry:Lean protein matrix demands elevated fat-mimetic binders and modified starch systems to prevent texture degradation. Health-positioned private-label lines in France and the Netherlands are displacing pork-derived formulations fastest.
- Beef:Higher myoglobin content intensifies cure color requirements and oxidation sensitivity.
- Lamb:Distinctive flavor compounds limit application breadth to ethnic and specialty positioning.
Pork retains the broadest installed base. Poultry is climbing the fastest among reformulation-driven processors.
Flavor Profile:
Flavor house R&D intensity concentrates in high-heat and fermentation-tolerant volatile compounds, with regional palate variation dictating geographic specialization in premix development.
- Spicy:Capsaicinoid stability through thermal processing requires encapsulation technologies or post-cook topical application. Demand clusters in southern European markets and export-oriented North American processors serving Hispanic retail segments.
- Savory:Umami precursor systems leverage yeast extract and hydrolyzed vegetable protein, with clean-label alternatives requiring fermentation-derived nucleotide investments.
- Sweet:Maillard-reactive sugar systems demand precise moisture control to prevent surface burning.
- Mild:Base seasoning matrices prioritize salt-cure functionality over aromatic complexity.
Savory dominates volume throughput. Spicy is gaining share fastest in ethnic product line expansion.
Formulation Type:
Certification and validation costs create tiered margin structures, with third-party organic and gluten-free audits adding substantial overhead relative to traditional commodity premix production.
- Traditional:Conventional phosphate-salt-nitrite matrices offer lowest unit cost and broadest processing latitude. High-volume cooked sausage operations in Germany and Poland anchor demand, though REACH chemical restrictions are eroding preservative optionality.
- Organic:Certified ingredient sourcing and segregation protocols add 15-25% formulation cost premium. German cooperative butcher networks are consolidating procurement to justify minimum batch sizes for validated organic supply chains.
- Gluten-Free:Starch-based binder substitution requires modified tapioca or potato systems with distinct hydration kinetics.
- Low-Fat:Fat replacement through konjac, carrageenan, or oat fiber demands specialized extrusion and texturization equipment.
Traditional formulations retain most installed capacity. Organic is expanding most quickly in premium retail positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes more sausage premix volume than any other European nation, while the United States sustains the largest single-country market outside Europe through independent butcher networks and industrial smokehouse operations.
Germany
Traditional sausage culture drives artisan butcher demand for clean-label premixes, while industrial processors reformulate for EU Green Deal sodium-reduction targets. REACH chemical authorization restricts phosphate preservatives. The Bavaria and North Rhine-Westphalia clusters host concentrated smokehouse and cooked-sausage capacity.
United States
Independent butcher shops and small-scale smokehouses anchor specialty premix procurement, with private-label processors scaling reduced-sodium development. USDA FSIS labeling mandates for species identification and allergen declaration constrain multi-species formulation freedom. Regional concentration spans Wisconsin, Pennsylvania, and Texas processing corridors.
France
Health-positioned poultry-sausage lines displace traditional pork formulations fastest among reformulation-driven processors. EU Regulation 1169/2011 tightens declaration granularity for compound ingredients. The Brittany and Normandy clusters specialize in organic and artisan dry-sausage premix applications.
Poland
High-volume cooked-sausage operations sustain demand for cost-engineered traditional spice matrices. EFSA guidelines on polycyclic aromatic hydrocarbon monitoring elevate smokehouse compliance costs. The Greater Poland and Silesian voivodeships concentrate industrial processing infrastructure.
Netherlands
Poultry-source premix blends gain traction in premium private-label development for export-oriented processors. EU AI Act supply-chain traceability requirements favor suppliers with integrated digital validation systems. The Gelderland and North Brabant regions pilot encapsulated salt microsphere technologies at commercial scale.
Sausage Premixes Market Competitive Landscape
Top-tier vendors anchor clean-label and reduced-sodium formulation science, while mid-scale specialists serve independent butcher channels through cooperative procurement networks. The vendor base stratifies across three functional tiers: multinational flavor houses with captive R&D laboratories, regional seasoning blenders with deep distribution into smokehouses, and private-label contract manufacturers competing on batch-size flexibility. Dominant competitive moves include strategic partnerships with artisan cooperative buying groups and technology licensing agreements for encapsulated salt systems.
Within the multinational tier, Kerry Group and Newly Weds Foods exemplify integrated flavor-science positioning, while AC Legg occupies a specialist role in North American private-label distribution. The Dalesman Group and Dunninghams represent UK-based seasoning houses serving traditional butcher channels. Corona Manufacturing anchors cost-engineered supply to high-volume thermal-processing operations.
| Leading Market Players |
|---|
| The Dalesman Group |
| The Sausage Maker |
| AC Legg |
| Krio Krush |
| Corona Manufacturing |
| Master Butchers Co-operative Ltd |
| Dunninghams |
| Kerry Group |
| Newly Weds Foods |
| Others |
Value Network & Pricing Analysis
Salt commodity benchmarks and nitrite cure chemical indices cascade through sausage premix value chains into three distinct pricing tiers, with EU REACH authorization costs compressing margins for phosphate-dependent formulations while clean-label premiums widen spreads between artisan and industrial procurement.
Pricing Analysis
Capacity additions in encapsulated salt microsphere production are reshaping price floors for reduced-sodium formulations, compressing the premium gap between clean-label and traditional matrices. Three-tier pricing structure across premium organic, standard clean-label, and economy phosphate-inclusive levels stratifies buyer segments, with German cooperative butcher networks exhibiting lowest price sensitivity due to quality positioning while Polish high-volume processors face acute margin pressure from salt price volatility.
Supply Chain Analysis
EU domestic-content mandates for organic certification and FSSAI localization requirements in India are reshaping sourcing footprints for validated ingredient suppliers. Raw material supply concentrates in Germany, Poland, and the Netherlands for spice matrices and cure systems, with rosemary extract and cultured celery dependencies drawing from Mediterranean agricultural zones and North American fermentation facilities. Single-source vulnerability in encapsulated potassium chloride microspheres elevates risk exposure. Distribution runs through cooperative buying groups for artisan channels and direct manufacturer contracts for industrial processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sausage premixes rests on reformulation-driven premium capture and salt-input cost management, with EU Green Deal compliance investments creating tiered returns across clean-label validation levels.
For Market Incumbents: Anchor defensive positioning through captive R&D laboratories for sodium-reduction flavor science and backward integration into rosemary-extract supply. Kerry Group's integrated flavor-house model demonstrates how vertical control over clean-label validation preserves pricing power against commodity spice blenders. Threat from cooperative buying group consolidation demands direct channel investment in German artisan networks. For New Entrants and Emerging Players: Launch via direct-to-smokehouse digital distribution platforms to bypass legacy ingredient distributor layers. White-space opportunity concentrates in India FSSAI clean-label pathway development and poultry-source formulation migration for health-positioned private-label lines. Go-to-market angle should emphasize batch-size flexibility for mid-scale organic processors facing dual certification timeline compression. For Investors and Strategic Acquirers: Asymmetric upside sits with regional seasoning houses possessing integrated digital validation systems for EU AI Act supply-chain traceability compliance. Five-to-ten year viability favors targets with captive analytical laboratories and established cooperative butcher relationships. Signal to watch is nitrite-replacement technical ceiling breakthrough enabling full phosphate elimination in thermal-processed categories.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | REACH chemical authorization restrictions force R&D redirection toward rosemary-extract and cultured-celery alternatives. |
| Direct-to-Smokehouse Digital Distribution | E-procurement platforms compress distributor layers for German and French independent butcher cooperative networks. |
| Encapsulated Salt Technology Licensing | Flavor-house IP partnerships enable mid-tier suppliers to access premium positioning without captive R&D infrastructure. |
| Cooperative Buying Group Partnership | Direct manufacturer contracts with German artisan aggregators displace legacy distributor-dependent supply relationships. |
| Dual Certification Infrastructure Buildout | Organic and gluten-free validation capabilities extend product launch windows for mid-scale processors in France and Netherlands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sausage processor procurement directors, flavor house R&D leads, artisan butcher cooperative managers, and EU regulatory affairs specialists with secondary validation from EFSA additive safety assessments, REACH authorization databases, USDA FSIS labeling guidance documents, and customs trade data for spice matrix imports. Bottom-up volume modeling from processor capacity utilization and top-down value triangulation from ingredient supplier revenue disclosures converged on segment-level estimates.
Comparable historical periods anchored the forecast window to pre- and post-EU Green Deal implementation phases, with projection horizons extending across the analysis window. Segmentation dimensions modeled include product type, meat source, flavor profile, and formulation certification tier, with CAGRs derived from elasticity-adjusted volume growth trajectories and price-mix normalization. Forecast inputs incorporated salt commodity price scenarios and nitrite-replacement technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH chemical restrictions or breakthrough natural cure system shelf-life performance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
3D Printed Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Meat Emulsions Market
Meat Products
United States Animal Protein Market
Meat Products
Europe Processed Meat Market
Meat Products
Beef Liver Market
Meat Products
Beef Jerky Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Global Processed Pork Meat Market
Meat Products
United States Processed Pork Meat Market
Meat Products
US Meat Market
Meat Products
North America Poultry Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
South Africa Processed Meat Market