
 Meat Flavors Market | 2026-2036
Meat Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Flavors Market Outlook
The EU Green Deal is pivoting European food manufacturers toward reduced-sodium, plant-extended meat flavor systems that maintain sensory authenticity. Givaudan leverages its biotechnology platform to produce fermentation-derived meat taste precursors at scale. Kerry Group anchors supply relationships with major protein processors through integrated flavor-application laboratories in Ireland and the Americas. Symrise AG competes on regulatory foresight, pre-qualifying flavor portfolios for evolving EU F-Gas Regulation and REACH compliance thresholds.
Meat flavors comprise thermally processed reaction mixtures, enzymatic hydrolysates, and top-note volatile compounds formulated to replicate species-specific taste profiles in food matrices. These systems typically operate at 0.1-2.0% inclusion rates to deliver Maillard-derived savory depth without intact animal tissue. Powder formats dominate manufacturing economics through extended shelf stability and bulk logistics efficiency, while liquid concentrates command premium positioning in high-hydration sauce applications. RTE Meals represent the fastest-expanding application vector as retail and food-service channels converge on heat-and-eat protein formats.
FDA guidance on bioengineered food disclosure and USDA-FSIS labeling standards shape permissible ingredient declarations and natural flavor claims in the United States. EFSA safety evaluations and EU MDR-adjacent food contact protocols govern flavor carrier substances and extraction solvent residues across European markets. Japan's Ministry of Health, Labour and Welfare maintains distinct positive-list systems for synthetic flavor additives that fragment formulation strategies. Stakeholders must monitor divergence between JIS-aligned Asian regulatory frameworks and transatlantic clean-label standards to avoid reformulation costs.
Market Dynamics
Clean-label disclosure mandates from the EU Green Deal and FDA bioengineered food guidance are compressing formulation timelines while fragmenting supplier qualification requirements across protein processors and flavor houses.
Growth Catalysts
- EU Green Deal decarbonization targets:Food manufacturers in Germany and France accelerate reformulation of reduced-sodium meat flavor systems to maintain sensory authenticity under tightening emission protocols.
- Biotechnology platforms:Fermentation-derived taste precursors enable scalable production of species-specific savory compounds without intact animal tissue.
- RTE meal production clusters:Concentrated convenience food manufacturing in Japan and the United States drives disproportionate procurement of powder-format flavor systems.
Market Restraints
- Raw material input volatility:Amino acid and nucleotide precursor costs fluctuate with agricultural commodity cycles, squeezing margin stability for hydrolysate producers.
- Regulatory fragmentation:Divergence between EFSA safety evaluations, FDA labeling standards, and Japan's Ministry of Health positive-list systems forces parallel formulation tracks.
- Technical authenticity ceiling:Thermally processed reaction mixtures struggle to replicate volatile sulfur compounds characteristic of slow-cooked meat profiles.
Strategic Opportunities
- Plant-extended meat applications:Hybrid protein matrices in Germany and the Netherlands create demand for masking and enhancing flavor systems.
- EU F-Gas Regulation compliance:Pre-qualified solvent-free extraction processes capture premium positioning as carrier substance restrictions tighten.
- Direct-to-manufacturer digital channels:Flavor houses bypass traditional distribution tiers to embed application laboratories within customer R&D facilities.
Industry Challenges
- Maillard reaction expertise scarcity:Formulation chemists capable of optimizing time-temperature profiles for specific protein matrices command premium compensation.
- Multi-jurisdiction certification timelines:REACH registration, F-Gas pre-qualification, and positive-list approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Flavors Market |
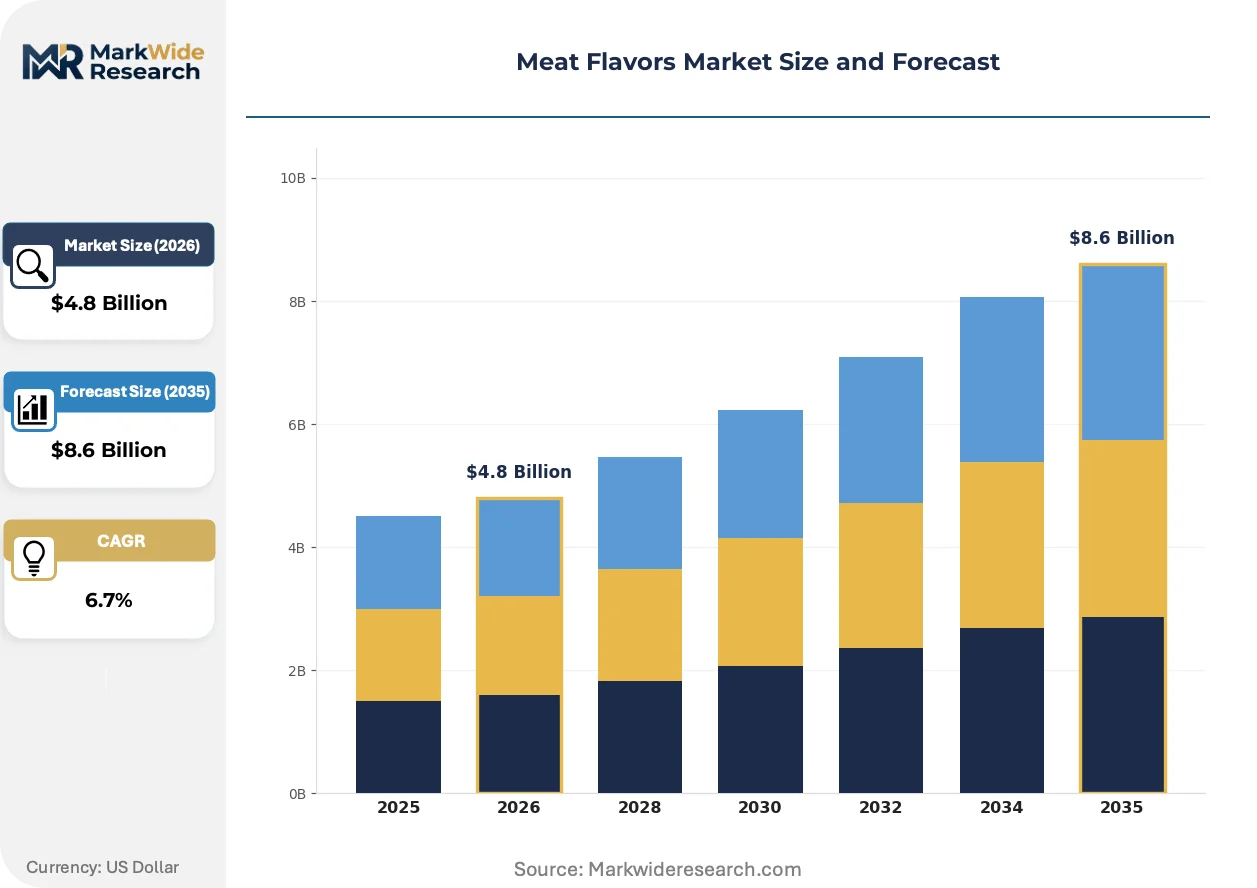
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Seasoning, Marinade Application: Processed Meat, Sauces, RTE Meals, Snacks Distribution Channel: Supermarket, Online, Specialty Stores, Food Services End User: Food Manufacturers, Restaurants, Retailers, Caterers |
| Companies Covered | Symrise AG, Sensient Technologies Corporation, Givaudan, Robertet Group, Takasago International Corporation, Kerry Group, Firmenich SA, Mane SA, International Flavors & Fragrances Inc. (IFF), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Flavors Market Strategic Shifts
Biotechnology-derived savory compounds, solvent-free extraction protocols, and embedded technical service models are restructuring how protein processors source and integrate flavor systems into product development workflows.
Enzymatic hydrolysate technology is expanding into high-volume plant protein applications. Alternative meat manufacturers in the Netherlands and California adopt these systems to mask off-notes in pea and soy isolates. The technology is compressing development cycles for hybrid protein formats while displacing traditional yeast extract dependence in premium positioning.
REACH-adjacent food contact protocols and EU F-Gas Regulation thresholds are reshaping carrier substance selection. Extraction solvent residues now face stricter residue limits across European markets. Flavor houses with pre-qualified solvent-free portfolios capture accelerated procurement decisions from multinational protein processors seeking unified formulation strategies.
Buyer concentration among consolidated protein processors is forcing flavor suppliers to unbundle technical service from product pricing. Major RTE meal manufacturers in Japan and Germany now demand captive application laboratories rather than transactional ingredient supply. This procurement compression favors integrated flavor houses with geographic proximity to customer R&D centers.
Meat Flavors Market Segmentation
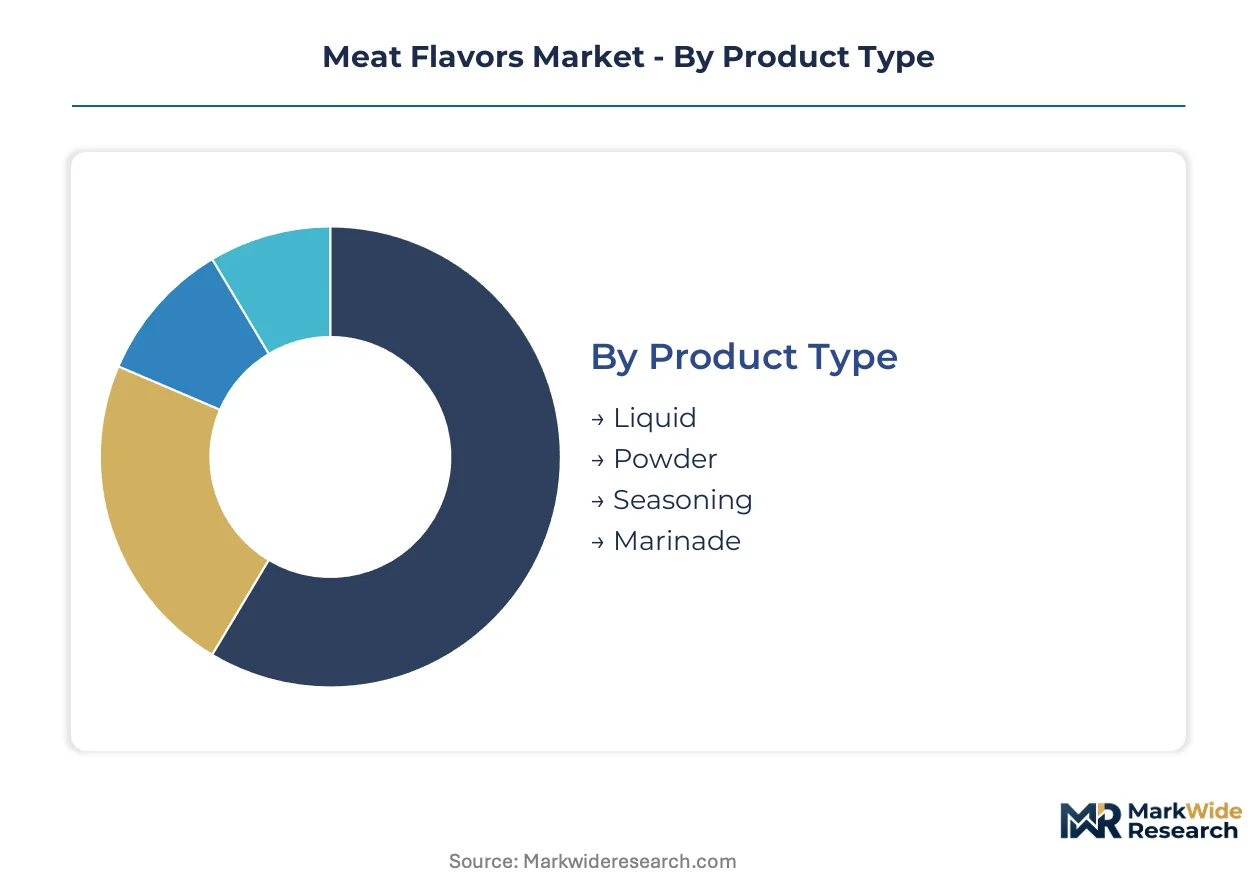
Meat flavor procurement strategies diverge sharply across product formats and end-use channels, with regulatory pre-qualification requirements fragmenting supplier selection criteria. Formulation specifications, shelf stability demands, and clean-label disclosure mandates reshape how processors match segment characteristics to manufacturing economics.
Product Type:
REACH registration and EU F-Gas pre-qualification burden liquid concentrates most heavily, while powder formats navigate simpler carrier substance compliance pathways.
- Powder:Spray-dried reaction mixtures and encapsulated volatiles deliver extended shelf stability through low-water-activity matrices. RTE meal manufacturers in Germany and Japan source disproportionate volumes for heat-and-eat protein formats where moisture control dominates specification sheets.
- Liquid:Aqueous concentrates and oil-based suspensions require solvent residue documentation under EFSA extraction protocols. Sauce applications in France and the United States drive demand for high-hydration systems that distribute evenly in emulsified matrices.
- Seasoning:Dry-blend spice carriers with integrated flavor precursors simplify label declarations for clean-positioned retail products.
- Marinade:Acid-stable flavor systems formulated for injection and tumbling processes in protein processing facilities.
Powder sits at the top of the volume ranking, with liquid climbing the fastest.
Application:
Customer procurement scale and technical service intensity separate high-volume contract manufacturing from specification-driven premium positioning.
- RTE Meals:Retort-stable and microwave-optimized flavor systems require Maillard precursor packages that survive aggressive thermal processing. Convenience food clusters in Japan and the United States concentrate demand for single-serve protein formats with authentic slow-cooked taste profiles.
- Processed Meat:Injection-grade hydrolysates and surface-applied reaction flavors must align with USDA-FSIS labeling standards for natural and artificial claims. Sausage and deli meat processors in Germany and the Netherlands specify reduced-sodium systems that maintain sensory depth through nucleotide enhancement.
- Sauces:Emulsion-stable concentrates for hot-fill and aseptic processing lines.
- Snacks:Top-note volatile systems for extruded and coated applications with rapid flavor release requirements.
RTE meals command the highest application-specific R&D investment, while processed meat maintains the broadest geographic footprint.
Distribution Channel:
Channel selection determines technical support depth, with direct supply relationships displacing transactional procurement in high-volume segments.
- Food Services:Bulk liquid and concentrated base systems for centralized kitchen operations and QSR protein platforms. National restaurant chains in the United States specify captive flavor laboratories for menu development support.
- Supermarket:Retail-packaged seasoning and marinade formats for consumer-facing protein preparation. German and French retailers demand clean-label declarations that preempt EU Green Deal disclosure tightening.
- Online:Direct-to-manufacturer digital procurement for mid-scale processors bypassing traditional distribution tiers.
- Specialty Stores:Premium-positioned artisan and ethnic flavor systems for differentiated retail positioning.
Food services anchor the highest volume throughput, with online channels gaining share fastest among emerging protein processors.
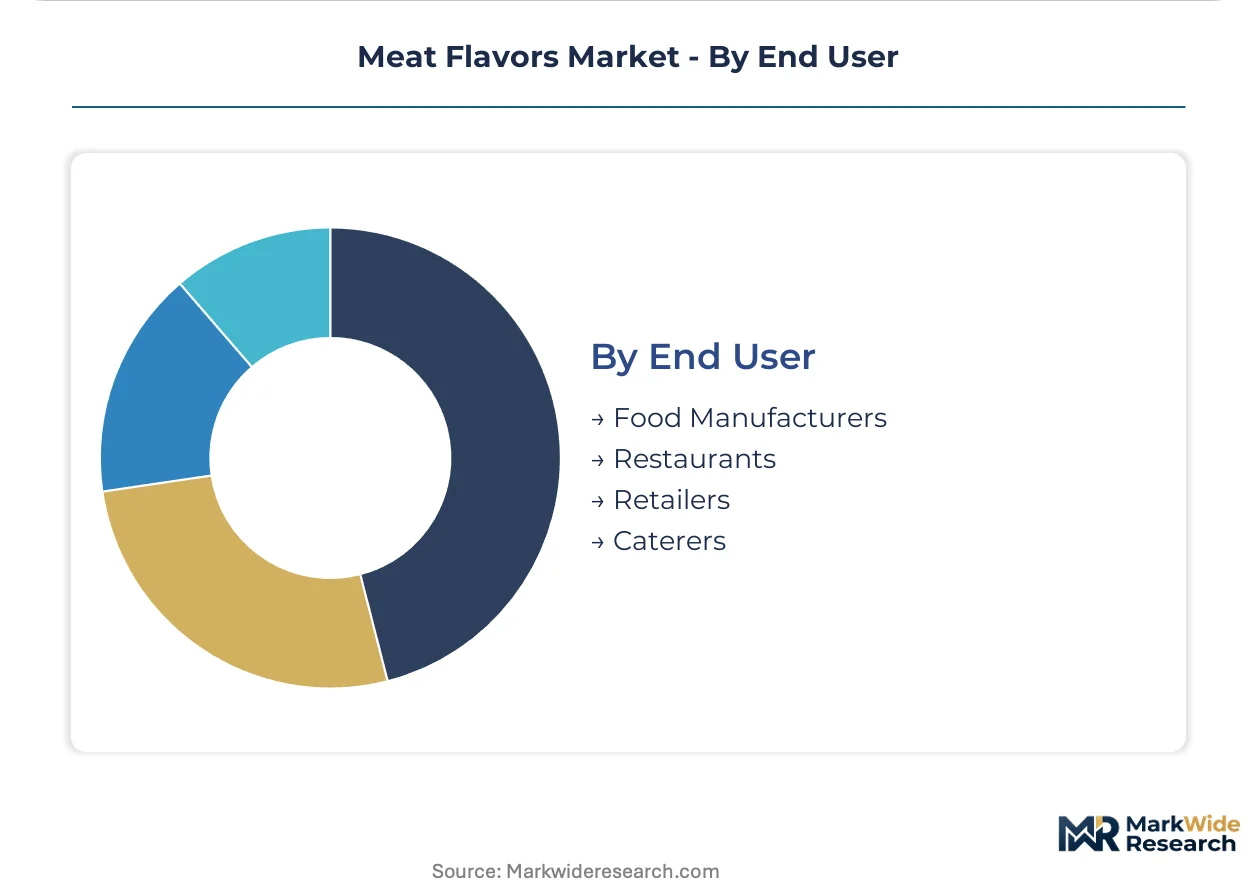
End User:
Scale concentration and formulation expertise scarcity separate integrated manufacturers from service-dependent operators.
- Food Manufacturers:Multinational protein processors with captive application laboratories demand embedded technical service rather than ingredient supply alone. Consolidated RTE meal producers in Japan and Germany specify unified formulation strategies across multiple production sites.
- Restaurants:Chain operators with centralized procurement specify custom flavor bases for menu consistency across franchise networks.
- Retailers:Private-label protein product developers seeking turnkey flavor systems for rapid line extensions.
- Caterers:Event and institutional food service operators with batch-scale preparation requirements and limited in-house formulation capability.
Food manufacturers dominate absolute volume procurement, with restaurants expanding specification influence through chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meat flavor technology originated in European culinary chemistry laboratories during the mid-twentieth century, with industrial-scale production first achieving commercial viability in Germany and Switzerland before spreading to North American and Asian markets.
Germany
Reduced-sodium reformulation and plant-extended protein matrices drive procurement from flavor houses. EU Green Deal decarbonization targets compress formulation timelines for meat processors. The Cologne-Düsseldorf corridor concentrates captive application laboratories serving RTE meal manufacturers.
United States
Consolidated protein processors and QSR chains demand embedded technical service rather than transactional supply. FDA bioengineered food disclosure guidance and USDA-FSIS labeling standards govern natural flavor claims. Chicago and Omaha host flavor-application facilities co-located with major meat processing headquarters.
Japan
Retort-stable and microwave-optimized flavor systems command premium R&D investment from convenience food producers. The Ministry of Health, Labour and Welfare maintains distinct positive-list systems for synthetic additives that fragment formulation strategies. Yokohama and Osaka production clusters specialize in single-serve protein formats with authentic taste profiles.
France
Clean-label declarations and preemptive EU regulatory compliance shape retailer procurement specifications. EFSA safety evaluations and REACH-adjacent food contact protocols govern extraction solvent residues. The Lyon-Grenoble axis anchors sauce application development for emulsion-stable concentrate systems.
Netherlands
Hybrid protein manufacturers adopt enzymatic hydrolysate technology to mask off-notes in pea and soy isolates. EU F-Gas Regulation thresholds reshape carrier substance selection for flavor houses. Wageningen food science clusters accelerate development cycles for plant-extended meat applications.
Meat Flavors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the meat flavors sector. Integrated flavor houses with captive biotechnology platforms and fermentation capacity face competition from specialized application laboratories that outsource precursor manufacturing. The market structure consolidates around three strategic archetypes: full-service houses with geographic proximity to customer R&D centers, regional specialists with regulatory pre-qualification expertise, and technology licensors with proprietary enzymatic platforms. Dominant competitive moves include captive application laboratory deployment and solvent-free extraction process certification.
Within the full-service tier, Symrise AG and Kerry Group exemplify integrated positioning through embedded technical service models. Sensient Technologies Corporation occupies a specialist position emphasizing regulatory foresight and compliance pre-qualification. These three anchors represent distinct competitive vectors: geographic proximity to protein processing clusters, unified formulation strategies across multi-site manufacturers, and accelerated procurement decisions through pre-qualified portfolios.
| Leading Market Players |
|---|
| Symrise AG |
| Sensient Technologies Corporation |
| Givaudan |
| Robertet Group |
| Takasago International Corporation |
| Kerry Group |
| Firmenich SA |
| Mane SA |
| International Flavors & Fragrances Inc. (IFF) |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal decarbonization targets gate qualified supply and premium-tier pricing access for meat flavor systems, as REACH registration and F-Gas pre-qualification burden liquid concentrates while powder formats navigate simpler compliance pathways. Clean-label disclosure mandates compress formulation timelines, forcing flavor houses to embed technical service costs into product pricing or unbundle them entirely for high-volume contract manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates solvent-free extraction portfolios from conventional carrier systems and commodity hydrolysate bases. Price differentiation hinges on REACH registration status and embedded application laboratory access, with biotechnology-derived precursors commanding premiums over thermally processed alternatives. Cost compression in standard-tier powder formats is intensifying because amino acid and nucleotide precursor costs fluctuate with agricultural commodity cycles. Mid-scale protein processors in Germany and Japan exhibit highest price sensitivity, while multinational RTE meal manufacturers prioritize unified formulation strategies over unit economics.
Supply Chain Analysis
Returns and refurbishment flows are minimal in meat flavor supply chains given the consumable nature of reaction mixtures and hydrolysates, though enzymatic precursor recovery from spent fermentation media is gaining traction among biotechnology platforms. Manufacturing concentrates in Germany, Switzerland, and the United States, with spray-drying facilities clustering near protein processing headquarters in Chicago, Omaha, and the Cologne-Düsseldorf corridor. Raw material dependencies center on amino acid precursors, nucleotide bases, and carrier substances like maltodextrin and gum arabic. Single-source vulnerability in fermentation-derived taste precursor supply creates concentration risk as Givaudan and specialized biotechnology houses scale proprietary platforms. Distribution runs through direct-to-manufacturer channels for consolidated processors, with traditional distribution tiers serving mid-scale regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meat flavors market functions as a stable compounder, with clean-label reformulation cycles and RTE meal proliferation driving steady procurement growth across protein processing clusters.
For Market Incumbents: Acquire captive application laboratory capacity in Japan and Germany to defend against emerging digital-native flavor houses that embed technical service through cloud-based formulation platforms. Prioritize solvent-free extraction process certification under EU F-Gas Regulation thresholds to capture accelerated procurement decisions from multinational protein processors seeking unified formulation strategies. Backward integration into fermentation-derived precursor manufacturing secures margin stability against amino acid cost volatility. For New Entrants and Emerging Players: Direct-to-manufacturer digital procurement routes offer lowest friction entry into mid-scale protein processors in the Netherlands and California seeking enzymatic hydrolysate systems for plant-extended meat applications. Target hybrid protein matrix developers with masking and enhancing flavor systems, as this segment exhibits fastest specification influence expansion and limited incumbent laboratory presence. Lead with rapid reformulation turnaround capabilities rather than price undercutting. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with regulatory pre-qualification expertise because REACH registration and positive-list approval timelines extend product launch cycles by 18-24 months, creating durable competitive moats. Focus on 5-10 year viability windows as biotechnology platforms displace conventional thermal processing. Monitor divergence between JIS-aligned Asian regulatory frameworks and transatlantic clean-label standards as inflection indicator for reformulation cost spikes and portfolio obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Acquisition | Fermentation-derived precursor capacity secures supply independence from agricultural commodity cycles. |
| Solvent-Free Extraction Certification | EU F-Gas pre-qualification captures premium positioning as carrier substance restrictions tighten. |
| Captive Application Laboratory Deployment | Embedded technical service in Yokohama and Chicago R&D centers locks in multinational RTE meal contracts. |
| Direct-to-Manufacturer Digital Channel | Bypassing distribution tiers accelerates procurement decisions from emerging plant-protein processors. |
| Regulatory Pre-Qualification Investment | Parallel REACH and Japan Ministry of Health positive-list approvals compress multi-jurisdiction launch timelines. |
Study Parameters
Coverage spans Germany, the United States, Japan, France, and the Netherlands, with primary inputs from each market combining interviews with flavor formulation chemists, protein processor procurement directors, RTE meal manufacturer R&D heads, and regulatory affairs specialists at multinational food manufacturers. Secondary validation draws from EFSA safety evaluations, FDA bioengineered food guidance documents, Japan Ministry of Health positive-list amendments, EU F-Gas Regulation threshold updates, and customs trade data on amino acid and nucleotide precursor flows. Bottom-up segment sizing triangulates against top-down market value estimates across powder, liquid, seasoning, and marinade formats.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window, with CAGRs derived from segment-level trend extrapolation adjusted for regulatory inflection points. Segmentation dimensions modeled include product format, application channel, distribution structure, and end-user scale concentration, plus biotechnology adoption intensity as industry-specific overlay. Forecast inputs incorporate EU Green Deal implementation pace, FDA labeling guidance finalization timelines, and fermentation platform scale-up trajectories at integrated flavor houses.
The model assumes a particular technology adoption path; alternative pathways for enzymatic hydrolysate displacement of yeast extract dependence would alter the outlook for premium positioning and margin structure. Forecasts reflect assumptions on regulatory harmonization versus fragmentation, raw material cost normalization, and captive laboratory deployment economics. Practitioners should monitor REACH registration backlog durations, F-Gas pre-qualification approval rates, and JIS standard revision announcements for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Qatar Poultry Meat Market
Meat Products
Chicken Buckets Market
Meat Products
Chilled Meat Market
Meat Products
Sausage Premixes Market
Meat Products
Smokehouse Market
Meat Products
North America Bacon Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Bacon Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Organic Halal Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Beef Extract Market
Meat Products
Global Poultry Meat Market
Meat Products
Germany Meat Products Market