
 Kosher Beef Market | 2026-2036
Kosher Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Kosher Beef Market Intelligence
A shift from fragmented, small-scale butchery towards centralized, large-volume processing is consolidating the supply base for kosher beef. American Foods Group leverages its extensive distribution network to serve both retail and wholesale channels across the United States. Agri Star Meat & Poultry specializes in a wide range of cuts for institutional buyers and food service clients. In contrast, Grow & Behold Foods differentiates through its focus on pasture-raised and ethically sourced products, targeting a premium consumer segment.
Kosher beef is derived from cattle slaughtered and processed according to Jewish dietary laws, known as kashrut. The process requires a specific ritual slaughter method, shechita, performed by a trained specialist, followed by rigorous inspection and the removal of forbidden fats and veins. Processed products, including deli meats and sausages, represent a fast-growing category driven by consumer demand for convenience. Certification from bodies like the Orthodox Union (OU) commands a premium, acting as a critical quality and authenticity signal for consumers.
Governmental bodies like the United States Department of Agriculture (USDA) and the European Food Safety Authority (EFSA) oversee general food safety and labeling, which run parallel to religious certification. The kashrut certification agencies themselves, such as Star-K and Kof-K, dictate market access and consumer trust through stringent audits of the entire supply chain. The key decision for processors is how to balance investments in supply chain transparency with the cost of maintaining multiple, distinct certifications.
Market Dynamics
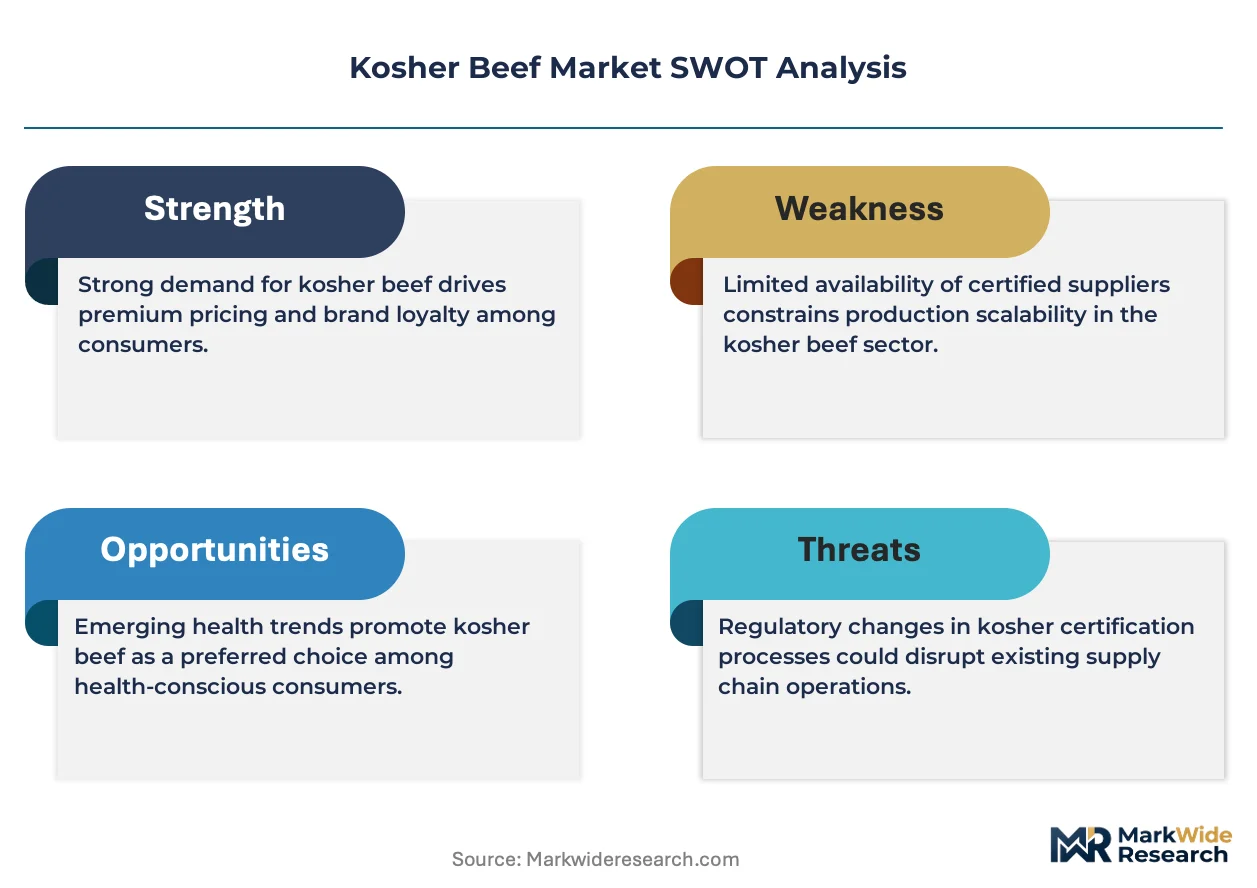
The imperative for supply chain transparency is the central force shaping the kosher beef market. Consumer and rabbinic demand for verifiable adherence to kashrut from farm to fork is compelling processors to adopt new technologies and consolidate operations for greater control.
Growth Catalysts
- Blockchain Traceability:The adoption of blockchain technology provides an immutable record of an animal's history, slaughter, and processing, directly addressing consumer demand for authenticity and enhancing the credibility of certification marks.
- Food Service Expansion:A rising number of hotels, airlines, and event caterers in global business hubs like London and Toronto are offering certified kosher meal options to serve a diverse international clientele, driving institutional demand.
- Retailer Certification Mandates:Major supermarket chains in the United States and France are increasingly requiring suppliers to carry specific, widely recognized certifications like OU or the Consistoire de Paris, expanding access to mainstream consumers.
Market Restraints
- Specialized Labor Scarcity:The market's capacity is constrained by a limited global pool of qualified ritual slaughterers (shochetim) and inspectors, creating a significant labor bottleneck that is difficult to scale quickly.
- Input Cost Volatility:The cost of kosher beef is intrinsically linked to feed prices for cattle, but it also carries the high, fixed costs of the certification and inspection process, making margins susceptible to commodity fluctuations.
- Regulatory Friction on Slaughter Methods:Animal welfare laws in several European countries, including Belgium and Denmark, restrict or ban the practice of slaughter without pre-stunning, directly conflicting with the requirements of shechita and limiting local production.
Strategic Opportunities
- Premium Product Development:There is a market opportunity for value-added products like dry-aged steaks, artisanal cured meats, and meal kits targeted at the premium, direct-to-consumer segment via e-commerce platforms.
- Latin American Market Entry:Jewish communities in large urban centers such as Buenos Aires, Argentina and São Paulo, Brazil represent underpenetrated markets with growing disposable incomes and a demand for certified kosher products.
- Halal-Kosher Crossover Potential:Exploring processing facilities that can accommodate both halal and kosher standards, where methodologies overlap, could create operational efficiencies and open access to the much larger global halal food market.
Industry Challenges
- Certification Authority Proliferation:Processors face complexity and added costs in managing audits and compliance for multiple kashrut certification agencies, each with slightly different standards and regional influence, such as OU, Kof-K, and Star-K.
- Cold Chain Infrastructure Investment:Maintaining the integrity of fresh and frozen beef from large, centralized processing plants to geographically dispersed consumer markets requires significant capital investment in an unbroken cold chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kosher Beef Market |
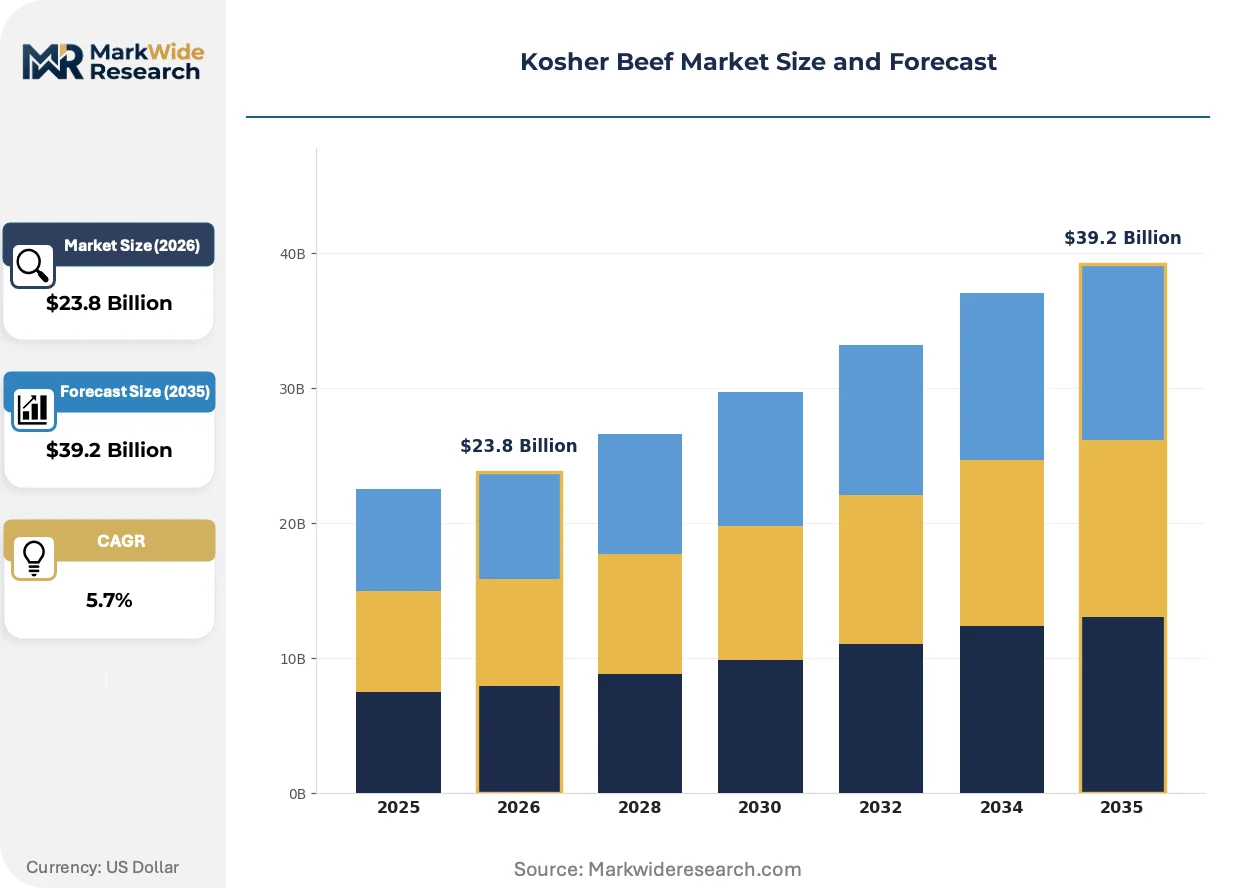
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Processed, Ground Distribution Channel: Retail, Wholesale, Online, Food Service Meat Cut: Brisket, Ribeye, Tenderloin, Chuck Certification: Orthodox Union, Star-K, Kof-K, Others |
| Companies Covered | Solomon Kosher Butcher, Grow & Behold Foods, Aufschnitt Meats, ZEPHYR FOODS LLC, KOL FOODS, American Foods Group, Tevya’s Ranch, Empire Kosher, Agri Star Meat & Poultry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kosher Beef Market Strategic Shifts & Innovations
The industrialization of kosher beef production is accelerating, driven by technological integration and evolving consumer expectations. This shift moves the sector from its artisanal roots toward scalable models that prioritize verification, convenience, and new product formats while navigating a complex regulatory environment.
Blockchain technology provides an immutable digital ledger for tracking cattle from farm to processor, ensuring end-to-end traceability. Certification bodies and large-scale producers are adopting this system to combat fraud and bolster consumer confidence in the authenticity of their kashrut claims. This digital verification layer is absorbing the function of traditional paper-based records, streamlining audits and reducing the risk of certification misrepresentation.
European Union regulations, interpreted and enforced by authorities like EFSA, continue to tighten rules around animal welfare, particularly concerning pre-slaughter stunning. This creates direct operational and legal friction with the religious requirements of shechita, which forbids the practice. Processors in affected member states like Sweden are forced to either lobby for religious exemptions, invest in contested post-cut stunning techniques, or relocate slaughter operations to non-EU countries.
A significant demand-side shift is the move toward direct-to-consumer (DTC) e-commerce and subscription box models. This channel disintermediates the traditional local butcher, allowing consumers to order specific cuts and curated selections directly from farms or specialized distributors. This trend is most advanced in the United States, particularly within and around urban centers like New York and Los Angeles, where convenience and product storytelling are valued.
Kosher Beef Market Segmentation
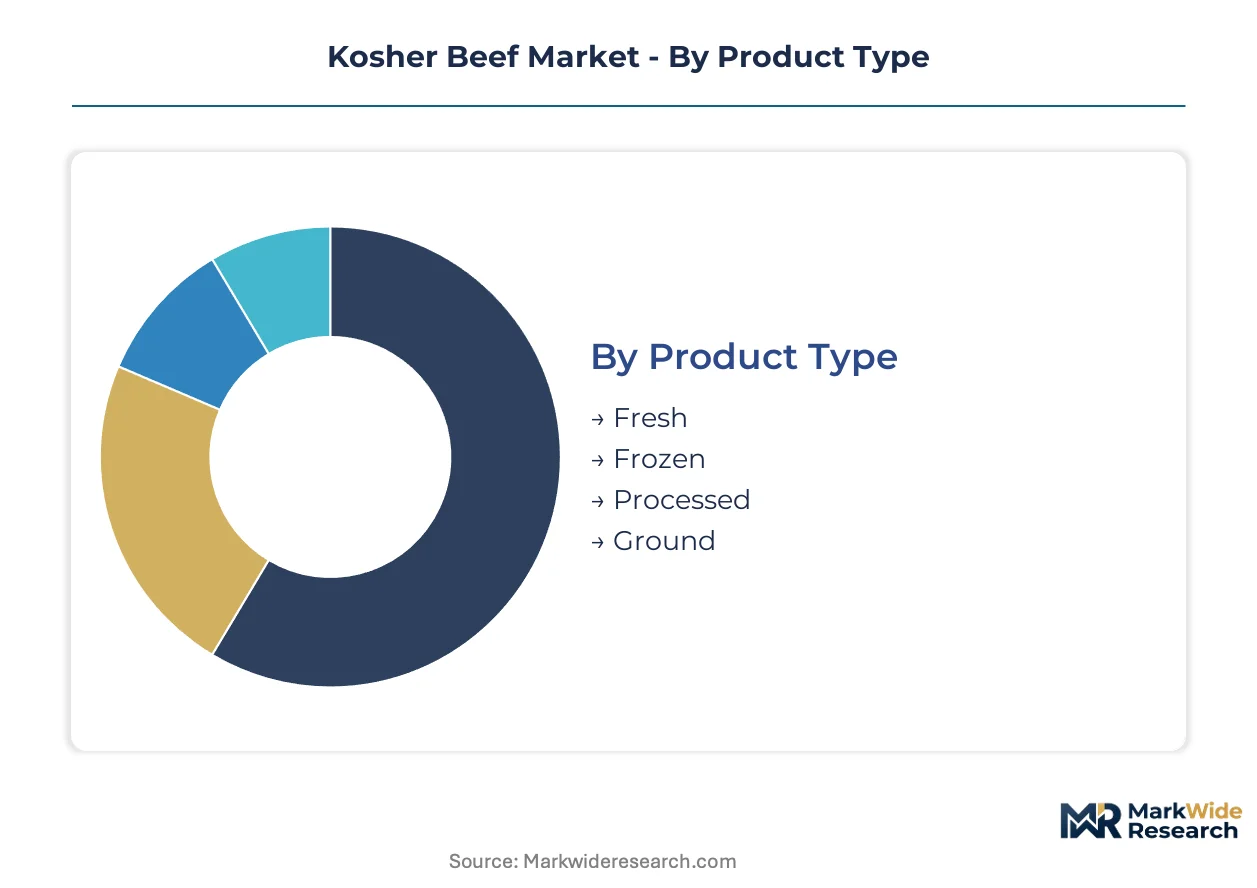
The Kosher Beef Market exhibits distinct dynamics across various product types, distribution channels, meat cuts, and certification bodies. Understanding these segments reveals specific consumer behaviors and operational requirements for processors and distributors. This granular view informs strategic decision-making.
Product Type:
The Kosher Beef Market observes a continuous cycle of product innovation and replacement, where traditional formats are enhanced or new convenient options emerge to meet evolving consumer lifestyles.
- Fresh:This category includes whole cuts and primal portions sold uncooked, requiring strict cold chain management. Demand concentrates in urban centers like New York and Tel Aviv, driven by traditional culinary practices and home meal preparation.
- Processed:Products such as deli meats, sausages, and pre-marinated items fall into this segment, offering convenience and extended shelf life. This segment sees significant growth in mainstream retail channels, catering to busy consumers seeking ready-to-eat options.
- Frozen:Comprises cuts preserved by freezing, offering longer storage duration for both retail and food service applications.
- Ground:Finely minced beef used for burgers, meatballs, and other dishes, representing a versatile and high-volume product.
Volume placements concentrate in Fresh beef; the faster expansion belongs to Processed products.
Distribution Channel:
Different customer types drive distinct distribution strategies within the Kosher Beef Market, influencing logistics and market access for producers.
- Food Service:This channel supplies restaurants, hotels, airlines, and event caterers with bulk and specific cuts for prepared kosher meals. Institutional demand in global business hubs like London and Toronto drives expansion.
- Online:Direct-to-consumer e-commerce platforms and subscription box models characterize this channel, offering convenience and a wider selection to geographically dispersed consumers. This segment is particularly advanced in the United States, serving urban and suburban populations.
- Retail:Supermarket chains and specialty kosher stores constitute this traditional channel, providing packaged and fresh cuts to individual consumers.
- Wholesale:This segment involves large-volume sales to distributors, smaller retailers, and institutional buyers, forming the backbone of regional supply networks.
The Retail channel currently commands the largest market share, but Online distribution is emerging as a significant growth driver.
Meat Cut:
The application of various meat cuts dictates their market value and consumer appeal, reflecting diverse culinary traditions and preparation methods in kosher households.
- Brisket:A popular cut from the breast or lower chest, known for its suitability for slow cooking and traditional holiday meals. Its demand is particularly strong during Jewish festivals in regions with large Jewish populations.
- Ribeye:This premium cut, sourced from the rib section, is valued for its tenderness and marbling, often featured in high-end kosher restaurants and specialty retail. Consumers seeking a luxury dining experience drive its market presence.
- Tenderloin:A highly prized, lean, and tender cut, typically reserved for special occasions and gourmet preparations.
- Chuck:A versatile cut from the shoulder, often used for roasts, stews, and ground beef due to its rich flavor and affordability.
Premium offerings like Ribeye attract higher price points, while Chuck provides a value-oriented option for everyday consumption.
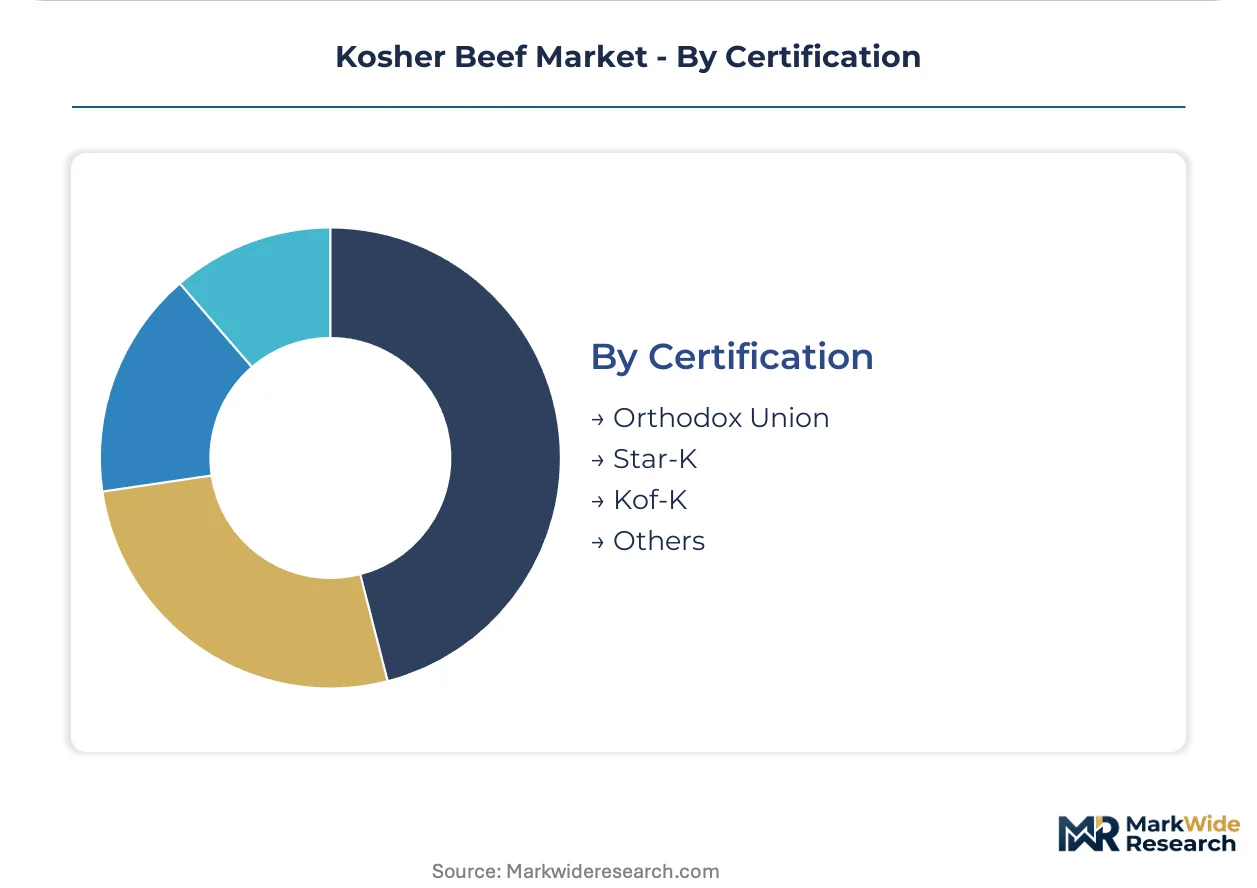
Certification:
Supply concentration within the Kosher Beef Market is heavily influenced by the presence and recognition of specific certification authorities, which dictate market access and consumer trust.
- Orthodox Union:This certification is globally recognized and highly influential, signifying stringent adherence to kashrut laws and opening access to major retail and food service markets. Processors prioritize OU certification for broad market acceptance.
- Star-K:A prominent certification agency known for its rigorous standards and comprehensive oversight across the supply chain, particularly strong in specific regional markets within the United States. Its reliability builds strong consumer loyalty.
- Kof-K:Another respected certification body, providing kashrut supervision for a range of products and gaining traction in specialized niches.
- Others:This category encompasses various smaller or regionally focused certification agencies, catering to specific community standards or niche markets.
The Orthodox Union holds significant market influence, while smaller certification bodies aim to expand their reach through niche specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a major cattle-producing nation, anchors significant kosher beef processing and distribution. Demand for certified products is high across its urban centers. This market sees diverse regional dynamics driven by local consumer bases and evolving regulatory environments.
United States
United States demand for kosher beef concentrates in major metropolitan areas like New York and Los Angeles. The USDA oversees general food safety and labeling for all meat products. New York City serves as a primary hub for both retail and food service distribution of kosher beef products.
Israel
Israel's market for kosher beef is driven by universal adherence to kashrut and a large consumer base. The country's Ministry of Health sets food safety standards alongside rabbinic certifications. Tel Aviv experiences high demand for fresh and processed kosher beef across its food service sector.
France
French consumers in urban centers like Paris exhibit consistent demand for certified kosher products. The European Food Safety Authority (EFSA) influences animal welfare regulations impacting slaughter practices across the EU. Paris serves as a key European hub for kosher food imports and specialty retail.
United Kingdom
London's diverse international clientele and significant Jewish population drive institutional demand for kosher meal options. The UK's Food Standards Agency (FSA) monitors food safety and labeling requirements. London remains a crucial center for kosher catering and specialized food service providers.
Argentina
Argentina's large Jewish communities in cities such as Buenos Aires present an underpenetrated market with growing disposable incomes. The country's National Service of Agrifood Health and Quality (SENASA) regulates meat production and export standards. Buenos Aires is a growing center for local kosher meat production and distribution.
Kosher Beef Market Key Industry Players
Global majors compete with regional champions across processing capacity and distribution networks. The kosher beef market is consolidating from fragmented small-scale butchery towards centralized, large-volume operations. Major strategic archetypes include large-scale processors, premium niche producers, and specialized distributors. Companies pursue capacity expansion and portfolio diversification to capture market share.
Specialists in premium, ethically sourced products such as Grow & Behold Foods occupy a position targeting discerning consumer segments. American Foods Group exemplifies the large-scale processor and distributor archetype, leveraging extensive networks for broad market reach. Agri Star Meat & Poultry sits within the institutional and food service specialist category, providing a wide range of cuts to bulk buyers.
| Leading Market Players |
|---|
| Solomon Kosher Butcher |
| Grow & Behold Foods |
| Aufschnitt Meats |
| ZEPHYR FOODS LLC |
| KOL FOODS |
| American Foods Group |
| Tevya’s Ranch |
| Empire Kosher |
| Agri Star Meat & Poultry |
| Others |
Cost & Logistics Intelligence
Institutional buyers for food service operations often negotiate long-term contract-based pricing for bulk kosher beef. This approach stabilizes supply costs for large-volume purchases across hotels and airlines.
Pricing Analysis
Certification services are bundled into the final price of kosher beef, reflecting rigorous inspection and specialized labor. Transactional pricing dominates for retail sales, while institutional buyers often use contract-based models. Price differentiation stems from the specific kashrut certification agency and the quality grade of the meat cut. Pricing pressure stems from the scarcity of shochetim and volatile feed prices; retail consumers for premium products show less price sensitivity than those seeking value-oriented chuck cuts.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the cold chain for kosher beef, connecting centralized processing plants to urban consumer markets. Supply concentration for processing remains strong in the United States, with growing capacity in Argentina and Israel. The market relies on cattle production, making it susceptible to feed price volatility. Cold chain infrastructure investment represents a structural risk for maintaining integrity across fresh and frozen products, with distribution running through retail, food service, and online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kosher beef market is fundamentally a cost-of-compliance story, where stringent kashrut laws create a significant barrier to entry. Adherence to shechita, alongside certifications like Orthodox Union, forms a moat for established processors.
For Market Incumbents: Lock in specialized labor through training programs and competitive compensation to mitigate scarcity. Consolidate processing capacity to leverage economies of scale and optimize audit costs for certifications like Star-K. Invest in blockchain technology to enhance supply chain transparency, counteracting potential regulatory friction on slaughter methods. Expanding cold chain infrastructure protects market share from emerging direct-to-consumer models.
For New Entrants and Emerging Players: The price-point gap between artisanal premium offerings and commodity kosher beef presents an opportunity for value-added products. Target direct-to-consumer e-commerce platforms with artisanal cured meats and meal kits. Latin American urban centers like Buenos Aires represent a highly penetrable geography with growing disposable incomes. Go-to-market strategies should emphasize product storytelling and ethical sourcing.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers focusing on specialized processors with robust kashrut certifications. Long-term viability over the next decade is strong, driven by consistent demand in established Jewish communities. Target mid-sized companies with strong regional distribution networks in urban hubs like New York or Tel Aviv. The signal to watch is the widespread adoption of blockchain traceability by major certification bodies like OU.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Blockchain Traceability | Enhances consumer trust and streamlines audits for kashrut certification agencies. |
| Expand Latin American Market Presence | Captures unmet demand in underpenetrated urban centers with growing Jewish populations. |
| Develop Halal-Kosher Crossover Facilities | Leverages operational efficiencies and accesses the larger global halal food market. |
| Focus on Premium Value-Added Products | Targets discerning consumers seeking artisanal cuts and convenience via e-commerce platforms. |
| Secure Specialized Labor Pipelines | Addresses the critical scarcity of shochetim and inspectors constraining market capacity. |
Research Approach
Independent corroboration across USDA reports, EFSA guidelines, and industry association publications underwrites the qualitative findings. Primary interviews with kosher beef processors, certification body representatives, and retail buyers provided granular insights. This approach combined bottom-up market sizing with top-down validation. Secondary research further informed market dynamics and competitive landscapes.
Historical reference periods anchored the forecast window, ensuring comparability across segments. The analytical framework modeled market dynamics by product type, distribution channel, meat cut, certification, and regional regulatory environment. Compound Annual Growth Rates were derived from a multi-variant regression analysis. Key forecast inputs included kashrut certification trends and specialized labor availability across the projection horizon.
Inputs from major certification bodies and government agricultural agencies were available through the study window; gaps in real-time supply chain cost data introduce uncertainty bands. Forecasts reflect underlying assumptions regarding consumer demand and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
GCC Red Meat Market
Meat Products
Middle East Red Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Meat Ingredients Market
Meat Products
North America Poultry Meat Market
Meat Products
Beef Liver Market
Meat Products
United States Poultry Meat Market
Meat Products
Canned Beef Market
Meat Products
Meat Emulsions Market
Meat Products
Chicken Buckets Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Beef Tallow Market
Meat Products
GCC Edible Meat Market
Meat Products
Organic Lamb Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Low Fat Beef Market